
 Bird Carriers Market | 2026-2036
Bird Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Bird Carriers Market Outlook
Avian veterinary transport is shifting toward specialized hard-shell designs that accommodate oxygen ports and perch stabilization. Prevue Pet Products leverages its cage manufacturing heritage to anchor the veterinary clinic channel. Caitec Corporation differentiates through R&D intensity in bird-specific ergonomics. MidWest Homes for Pets sustains geographic dominance in North American big-box retail distribution.
Bird carriers are enclosed transport enclosures engineered from ventilated polymers, woven textiles, or composite shells with perch mounts, access doors, and restraint systems designed to reduce avian stress during transit. Wall thickness, mesh gauge, and perch diameter vary by species target, with macaw-grade units requiring powder-coated steel frames and cockatiel formats using lightweight nylon with PVC-coated mesh. Soft-sided carriers lead the product type category due to airline cabin compatibility and collapsible storage appeal. Nylon dominates the material segment for moisture resistance and dye sublimation branding opportunities. The extra-large size bracket captures concentrated margin pools from parrot owners seeking airline cargo compliance.
The United States Consumer Product Safety Commission and the Federal Aviation Administration jointly shape domestic demand through flammability standards and in-cabin dimensional limits. The European Chemicals Agency's REACH restrictions on phthalates and heavy metals in plastics redirect European sourcing toward certified nylon weaves and food-grade polymers. Stakeholders must monitor evolving airline pet policies and state-level animal welfare transport codes to anticipate certification requirements ahead of procurement cycles.
Market Dynamics
Airline cabin dimensional restrictions and veterinary transport oxygen compatibility requirements are forcing simultaneous redesign of hard-shell and soft-sided carrier architectures, compressing development cycles and fragmenting procurement specifications across channels.
Growth Catalysts
- Avian Veterinary Transport Standards:Specialized clinics in the United States now mandate oxygen port integration and perch stabilization systems for patient intake protocols.
- REACH Chemical Substitution:ECHA restrictions on phthalates and heavy metals in plastics are redirecting European sourcing toward certified nylon weaves and food-grade polymer alternatives.
- Urban Apartment Birdkeeping:Collapsible soft-sided formats with airline cabin compatibility are concentrating demand among space-constrained companion bird owners in dense metropolitan zones.
Market Restraints
- Nylon Input Cost Volatility:Petroleum-derived polymer feedstock fluctuations compress margin pools for woven textile carrier manufacturers without backward integration into fiber production.
- Aviation Regulatory Fragmentation:FAA in-cabin dimensional limits diverge from IATA cargo specifications, forcing dual-SKU inventory strategies that inflate working capital requirements.
- Substitution by Modified Pet Carriers:General-purpose small animal transport enclosures with aftermarket perch retrofits threaten price premiums for species-specific designs.
Strategic Opportunities
- Veterinary Clinic Channel Expansion:Unbranded white-label procurement contracts with avian specialist networks in Germany and France offer volume anchoring with lower customer acquisition costs.
- Biometric Stress Monitoring Convergence:Integration of heart-rate sensors and temperature logging with carrier ventilation systems creates telemetry-enabled premium tiers for research and breeding operations.
- State Animal Welfare Transport Codes:California and New York legislative momentum around companion animal transit conditions is mandating ventilation minimums that obsolete non-compliant inventory.
Industry Challenges
- Multi-Regulatory Certification Timelines:Simultaneous FAA flammability testing, USDA interstate transport approval, and REACH material compliance extends product launch windows by 8-14 months.
- Avian-Specific Ergonomics Talent Scarcity:Industrial designers with ornithological stress-behavior expertise command premium compensation, constraining R&D throughput for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bird Carriers Market |
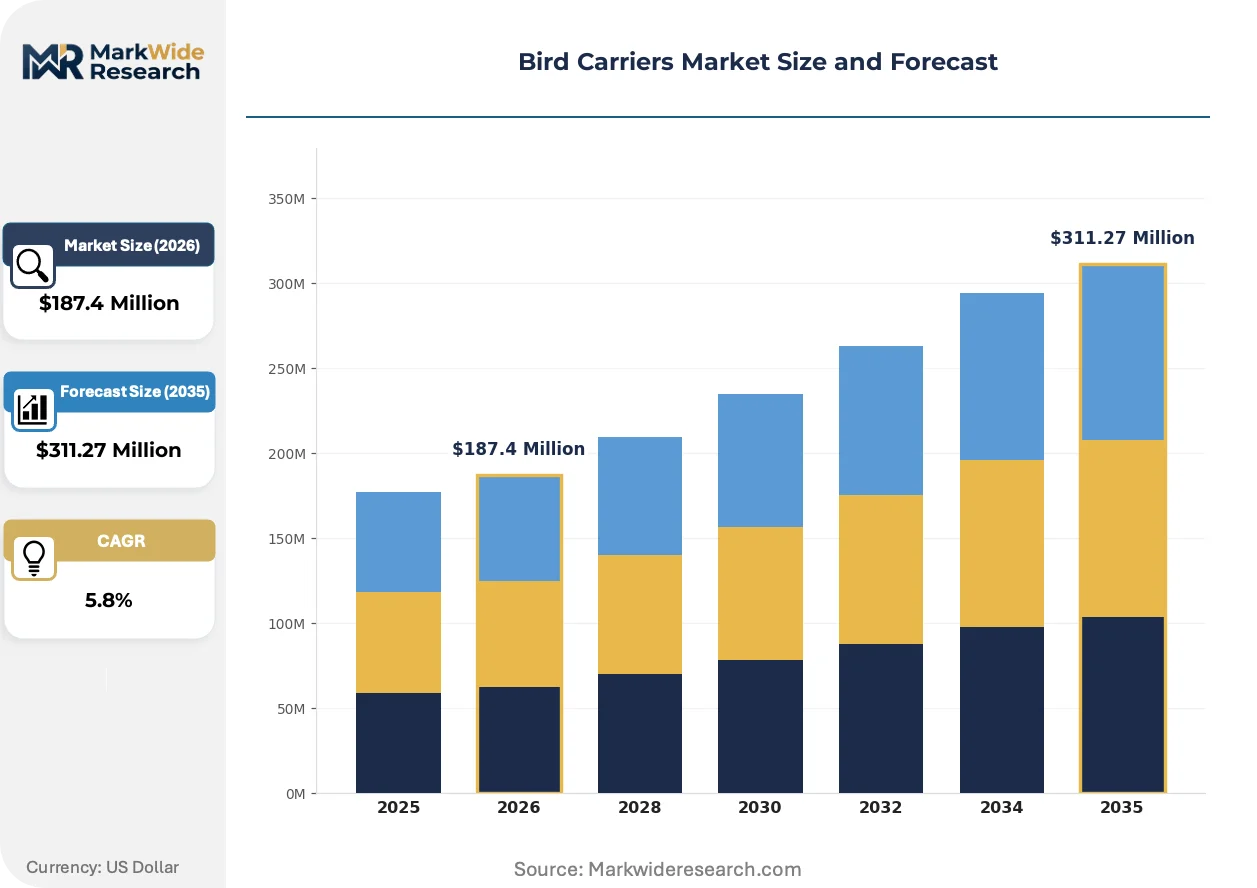
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft-Sided Carriers, Hard-Shell Carriers, Travel Crates, Backpack Carriers Material: Nylon, Plastic, Metal, Fabric Size: Small, Medium, Large, Extra Large End User: Pet Owners, Retail Stores, Veterinary Clinics, Animal Shelters |
| Companies Covered | Prevue Pet Products, Caitec Corporation, MidWest Homes for Pets, A&E Cage Company, Kaytee Products, Petmate, Sherpa Pet, Pet Gear, Rolf C. Hagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bird Carriers Market Strategic Shifts
Modular carrier architectures and embedded sensor integration are fragmenting the traditional single-purpose transport enclosure category into adaptive systems capable of serving veterinary, airline, and home-confinement contexts through component reconfiguration.
Carbon fiber reinforced polymer shells with integrated oxygen port manifolds are decentralizing the veterinary transport equipment supply chain. Avian specialty clinics in the United States and Netherlands are adopting these lightweight rigid formats for ambulatory services. The technology is decentralizing repair and maintenance away from manufacturer service centers toward clinic-level component replacement protocols.
REACH Annex XVII restrictions on cadmium and lead compounds in plasticized materials are forcing polymer reformulation across European supply bases. Manufacturers serving EU markets are migrating toward bio-based polyamides and recycled ocean nylon certified under OEKO-TEX Standard 100. Soft-sided carriers with dye-sublimation branding capabilities are absorbing disproportionate compliance investment due to their moisture-resistant coating requirements.
Direct-to-breeder subscription models with seasonal replacement cycles are compressing traditional retail inventory turnover patterns. Large-scale parrot breeding operations in Florida and Texas are bypassing pet specialty distributors for container-direct procurement. This channel rotation is most visible among macaw and cockatoo handlers requiring quarterly carrier replacement for biosecurity protocols.
Bird Carriers Market Segmentation
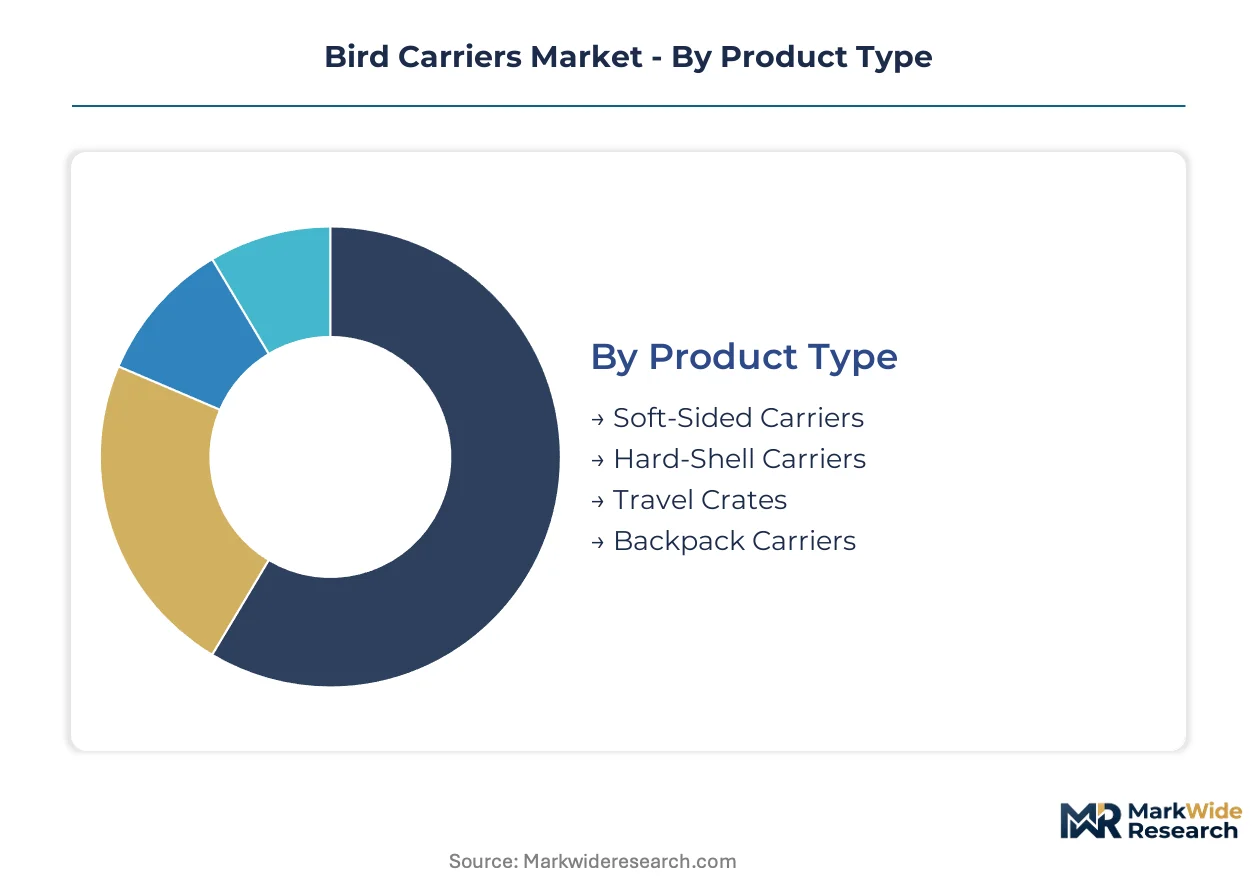
Carrier architecture and material composition dictate procurement economics across avian transport channels. Segmentation reveals where capital deployment concentrates and which specifications command premium positioning.
Product Type:
Hard-shell formats demand the highest upfront tooling investment for injection molding and oxygen port integration.
- Soft-Sided Carriers:Collapsible nylon constructions with PVC-coated mesh panels dominate airline cabin compliance. Urban apartment dwellers in the United States concentrate demand for stowable formats that fit under-seat dimensional limits.
- Hard-Shell Carriers:Rigid polymer or composite shells with integrated perch stabilization and ventilation manifolds serve veterinary transport protocols. Avian specialty clinics in the Netherlands and United States mandate these for patient intake requiring oxygen compatibility.
- Travel Crates:Wire-frame collapsible enclosures for extended transit or cargo hold placement.
- Backpack Carriers:Textile-based wearable formats with viewing windows for hands-free urban mobility.
Soft-sided carriers absorb the bulk of installed capacity; hard-shell formats are expanding most quickly.
Material:
Feedstock sourcing and regulatory compliance costs stratify margin structures across polymer and textile supply chains.
- Nylon:Woven polyamide with moisture-resistant coatings enables dye-sublimation branding and REACH-compliant OEKO-TEX certification. European manufacturers absorb disproportionate compliance investment for coating reformulation away from phthalate-based treatments.
- Plastic:Injection-molded ABS or polypropylene for rigid shell construction with food-grade polymer alternatives replacing legacy formulations.
- Metal:Powder-coated steel frames for macaw-grade units requiring structural integrity under cargo stress.
- Fabric:Cotton-polyester blends for budget-tier soft carriers with limited durability cycles.
Nylon commands the widest procurement volume; plastic faces the steepest substitution pressure from REACH chemical restrictions.
Size:
Dimensional brackets align with species-specific ergonomics and airline regulatory thresholds.
- Small:Cockatiel and parakeet formats under 12 inches in longest dimension.
- Medium:Conure and small parrot enclosures balancing cabin portability with perch diameter requirements.
- Large:African grey and Amazon parrot carriers approaching FAA under-seat limits.
- Extra Large:Macaw and cockatoo formats requiring IATA cargo compliance with reinforced frames and multiple access points. Breeding operations in Florida and Texas drive replacement cycles for biosecurity protocols.
Medium formats anchor baseline production runs; extra-large units capture the steepest expansion trajectory from parrot ownership concentration.
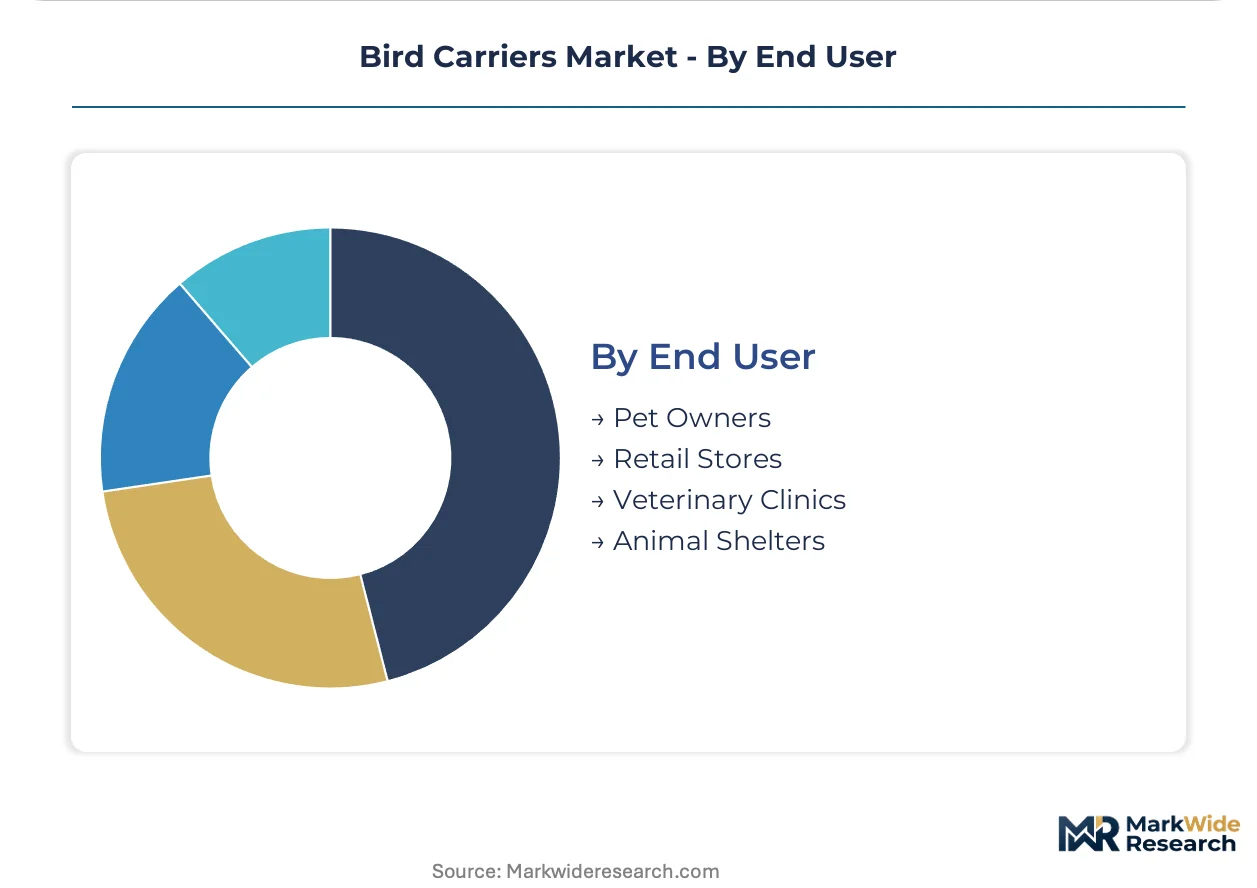
End User:
Channel-specific certification requirements fragment procurement specifications and contract structures.
- Pet Owners:Individual consumers prioritizing airline cabin compatibility and collapsible storage for urban residential constraints.
- Retail Stores:Pet specialty distributors stocking tiered price points across soft-sided and hard-shell categories.
- Veterinary Clinics:Avian specialist networks in Germany and France sourcing oxygen-port-equipped formats for ambulatory services. White-label procurement contracts offer volume anchoring with reduced customer acquisition costs.
- Animal Shelters:Municipal and nonprofit operations requiring durable, sanitizable enclosures for intake and transfer protocols.
Veterinary clinics are gaining share fastest; retail stores retain the broadest SKU coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and Texas concentrate veterinary equipment manufacturing, while REACH-compliant material sourcing clusters reshape European supply chains around certified polymer hubs.
United States
Urban apartment birdkeeping in New York and Chicago drives collapsible soft-sided carrier demand for airline cabin compliance. The FAA maintains strict in-cabin dimensional limits that manufacturers must satisfy for domestic flight eligibility. Florida breeding operations around Miami-Dade and Fort Myers execute quarterly carrier replacement cycles for macaw and cockatoo biosecurity protocols.
Germany
Avian specialty clinic networks in Bavaria and North Rhine-Westphalia source oxygen-port-equipped hard-shell formats for ambulatory veterinary services. ECHA REACH Annex XVII restrictions on phthalates redirect procurement toward OEKO-TEX certified nylon weaves. The Stuttgart industrial corridor hosts reformulation facilities for food-grade polymer alternatives to legacy plasticized materials.
Netherlands
Veterinary transport equipment distributors in Rotterdam and Amsterdam serve cross-border clinic networks requiring standardized oxygen compatibility. The country's national chemicals regulator enforces REACH compliance timelines that compress product launch windows. Eindhoven's polymer research cluster develops bio-based polyamides for carrier shell construction.
China
Injection molding capacity in Guangdong Province supplies ABS and polypropylene shell components for export markets. The Ministry of Ecology and Environment enforces dual carbon goals that pressure feedstock sourcing toward recycled ocean nylon. Shenzhen textile manufacturers produce PVC-coated mesh panels for soft-sided carrier assembly.
United Kingdom
Pet specialty retail chains in Greater London and Manchester stock tiered price points across soft-sided and hard-shell categories. The country's national veterinary regulator aligns with EU transport welfare standards for companion animal transit. Birmingham distribution hubs consolidate procurement for domestic avian clinic networks.
Bird Carriers Market Competitive Environment
Top-tier vendors anchor veterinary clinic and airline-compliant channels, while mid-tier fabricators compete on collapsible formats for urban consumers. The vendor base stratifies across three functional tiers: heritage cage manufacturers with veterinary relationships, textile specialists with airline certification expertise, and diversified pet product conglomerates with big-box retail penetration. Dominant competitive moves include backward integration into polymer fiber production and white-label contracting with clinic networks to reduce customer acquisition costs.
Within the heritage manufacturing tier, Prevue Pet Products and Caitec Corporation exemplify contrasting strategic positions. Prevue Pet Products anchors the veterinary clinic channel through cage manufacturing heritage. Caitec Corporation occupies a position emphasizing bird-specific ergonomics research. MidWest Homes for Pets represents the geographic concentration archetype with sustained North American big-box retail distribution presence.
| Leading Market Players |
|---|
| Prevue Pet Products |
| Caitec Corporation |
| MidWest Homes for Pets |
| A&E Cage Company |
| Kaytee Products |
| Petmate |
| Sherpa Pet |
| Pet Gear |
| Rolf C. Hagen |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII chemical restrictions gate qualified supply for European markets and premium-tier pricing access for compliant manufacturers. Veterinary clinics in Germany and the Netherlands pay material premiums for OEKO-TEX certified carriers with oxygen port integration, while budget-tier fabricators face margin compression from reformulation costs.
Pricing Analysis
Short lead-time premiums dominate pricing structures for veterinary clinic procurement with urgent patient transport requirements. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified airline formats from basic collapsible models and unbranded commodity carriers. Price differentiation hinges on certification grade and customization level for species-specific ergonomics. Pricing pressure stems from petroleum-derived nylon feedstock volatility compressing margins for woven textile manufacturers without captive fiber production. Breeding operations in Florida exhibit lowest price sensitivity due to biosecurity-driven replacement cycles; urban apartment consumers in Chicago and New York show highest sensitivity to unit economics.
Supply Chain Analysis
Certification and qualification gating concentrates supply among manufacturers with concurrent FAA flammability testing, USDA interstate approval, and REACH material compliance capabilities. Manufacturing clusters in China, the United States, and Germany anchor shell component injection molding, final assembly integration, and polymer research respectively. Raw material dependencies draw from ABS and polypropylene resin streams, PVC-coated mesh textiles, and powder-coated steel framing. Single-source vulnerability runs through Guangdong Province injection molding capacity for hard-shell base components. Distribution runs through pet specialty retail chains, veterinary clinic procurement networks, and direct-to-breeder subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where multi-regulatory certification timelines and avian ergonomics talent scarcity force weaker fabricators toward exit or acquisition.
For Market Incumbents: Lock in veterinary clinic channel control through white-label contracting with avian specialist networks in Germany and France, reducing customer acquisition costs against emerging textile competitors. Anchor backward integration into polymer fiber production to offset petroleum-derived nylon cost volatility threatening margin pools. Defend against general-purpose pet carrier retrofit substitutes by accelerating oxygen port standardization across hard-shell product lines. For New Entrants and Emerging Players: Begin with biometric stress monitoring integration for research and breeding operations in Florida and Texas, where telemetry-enabled premium tiers command weakest incumbent penetration. Target direct-to-breeder subscription models with quarterly replacement cycles, bypassing pet specialty distributors with container-direct procurement structures. Establish go-to-market positioning through avian veterinary clinic relationships rather than retail channel competition. For Investors and Strategic Acquirers: California and New York legislative momentum around companion animal transit ventilation minimums is the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded inventory risks. Position for five-to-ten year viability windows by targeting manufacturers with concurrent FAA, USDA, and REACH certification infrastructure rather than single-market specialists. Watch for state-level animal welfare transport code adoptions as the signal for accelerated channel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Fiber Production | Captive nylon supply insulates margin pools from petroleum feedstock volatility affecting woven textile competitors. |
| Biometric Sensor Platform Development | Heart-rate and temperature telemetry creates defensible premium tier for research breeding operations in Florida. |
| White-Label Veterinary Clinic Contracting | Volume anchoring with German and French avian specialist networks reduces customer acquisition cost exposure. |
| REACH-Compliant Material Reformulation | Bio-based polyamide certification opens EU market access while obsoleting non-compliant competitor inventory. |
| Direct-to-Breeder Subscription Launch | Quarterly replacement cycles for macaw and cockatoo biosecurity protocols compress traditional retail turnover patterns. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with avian veterinary clinic procurement managers, pet specialty retail category buyers, polymer manufacturing plant managers, and breeding operation supply heads combined with secondary validation from FAA certification databases, ECHA REACH substance restrictions, and USDA interstate transport guidelines. Bottom-up carrier unit economics and top-down market sizing triangulated across product type, material composition, size bracket, and end-user channel dimensions.
Segmentation-level granularity modeled carrier architectures at product type and material composition resolution, with end-user channel and geographic regulatory cluster as cross-cutting dimensions. CAGRs derived from installed base replacement cycles, airline policy evolution trajectories, and veterinary transport protocol adoption curves across the projection horizon. Forecast inputs incorporated REACH chemical substitution timelines, state-level animal welfare legislative momentum, and petroleum-derived polymer price elasticity assumptions.
Airline regulatory fragmentation, REACH compliance timeline extensions, and avian ergonomics talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around certification harmonization and substitution elasticity without guaranteed realization. A model refresh is warranted upon material change in FAA in-cabin dimensional standards or ECHA Annex XVII restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Poland Car Rental Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Car Rental Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Cross Docking Services Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Drayage Services Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Corporate Car Sharing Market