
 Chemical Tanker Market | 2026-2036
Chemical Tanker Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Tanker Market Analysis
Southeast Asian shipyard capacity is fragmenting as newbuilding orders spread across yards in Vietnam, the Philippines, and Indonesia. Hafnia leverages its integrated technical management platform to sustain fleet utilization across volatile trade lanes. Odfjell SE anchors its competitive stance through stainless-steel tanker specialization for high-grade chemical cargoes. Scorpio Tankers competes aggressively on cost discipline in the medium-range segment.
A chemical tanker is a double-hulled cargo vessel engineered with coated or stainless-steel tanks to transport liquid chemicals in bulk, typically maintaining cargo temperatures between minus 50 and plus 220 degrees Celsius through integrated heating and cooling systems. Its primary commercial purpose is enabling safe, segregated maritime transport of incompatible chemical grades from production hubs to downstream processing facilities. The product-type dimension shows acids and specialized alcohols commanding premium freight rates due to corrosion-resistant coating requirements and limited vessel eligibility. Application-level demand from pharmaceutical and food-processing shippers is tightening cargo-handling protocols and driving investment in temperature-controlled tank configurations.
The International Maritime Organization's MARPOL Annex II governs chemical tanker construction and pollution prevention, while the EU's F-Gas Regulation shapes refrigeration system choices for temperature-sensitive cargoes on European routes. Classification societies including DNV and ABS enforce structural standards that directly determine vessel market access and resale liquidity. Stakeholders must monitor how impending carbon-intensity regulations reshape fleet retirement schedules and newbuild fuel-technology commitments.
Market Dynamics
The International Maritime Organization's revised MARPOL Annex II standards are compressing vessel eligibility pools and forcing accelerated fleet renewal decisions among chemical tanker operators. These pollution-prevention rules now mandate stricter cargo classification protocols and coating specifications that legacy coated tankers cannot satisfy without prohibitively expensive retrofits.
Growth Catalysts
- Specialty Chemicals Demand:Pharmaceutical manufacturers in Switzerland and Germany are expanding maritime procurement of high-purity solvents, requiring stainless-steel tank configurations that command premium freight rates.
- REACH Compliance:The EU's chemical registration framework is consolidating cargo documentation standards across European ports, reducing inspection delays and improving vessel turnaround times.
- Coastal Processing Clusters:China's integrated chemical parks along the Yangtze Delta and Bohai Rim are scaling import volumes of temperature-sensitive intermediates, driving demand for heated tanker capacity.
Market Restraints
- Stainless-Steel Input Costs:Nickel price volatility directly pressures newbuild economics for chemical-grade tankers, with shipyards in South Korea and Japan passing alloy surcharges to owners.
- Yard Concentration Risk:Overreliance on Chinese state-owned shipbuilders for coated chemical tankers creates delivery slot scarcity and extends order backlogs beyond thirty-six months.
- Cargo Compatibility Limits:Epoxy-coated tanks cannot sequentially load certain acid-alcohol combinations without intermediate cleaning cycles that degrade utilization metrics.
Strategic Opportunities
- Biofuel Bunkering Hubs:Singapore and Rotterdam are developing methanol and ammonia fueling infrastructure that enables dual-fuel chemical tanker deployments on Asia-Europe routes.
- Food-Grade Certification:Edible oil and juice concentrate shippers are creating demand for dedicated stainless-steel fleets with ISO tank cleaning protocols separate from industrial chemical rotations.
- Digital Freight Platforms:Real-time cargo-matching algorithms are reducing ballast voyages and improving fleet utilization for independent tanker owners operating spot markets.
Industry Challenges
- Marine Chemist Certification Shortage:Qualified cargo inspectors capable of verifying tank cleanliness for high-purity chemical loads are concentrated in Northern European and Japanese labor pools.
- Legacy System Integration:Tanker operators retrofitting IoT temperature-monitoring sensors face compatibility failures with existing integrated automation systems from 1990s-era newbuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Tanker Market |
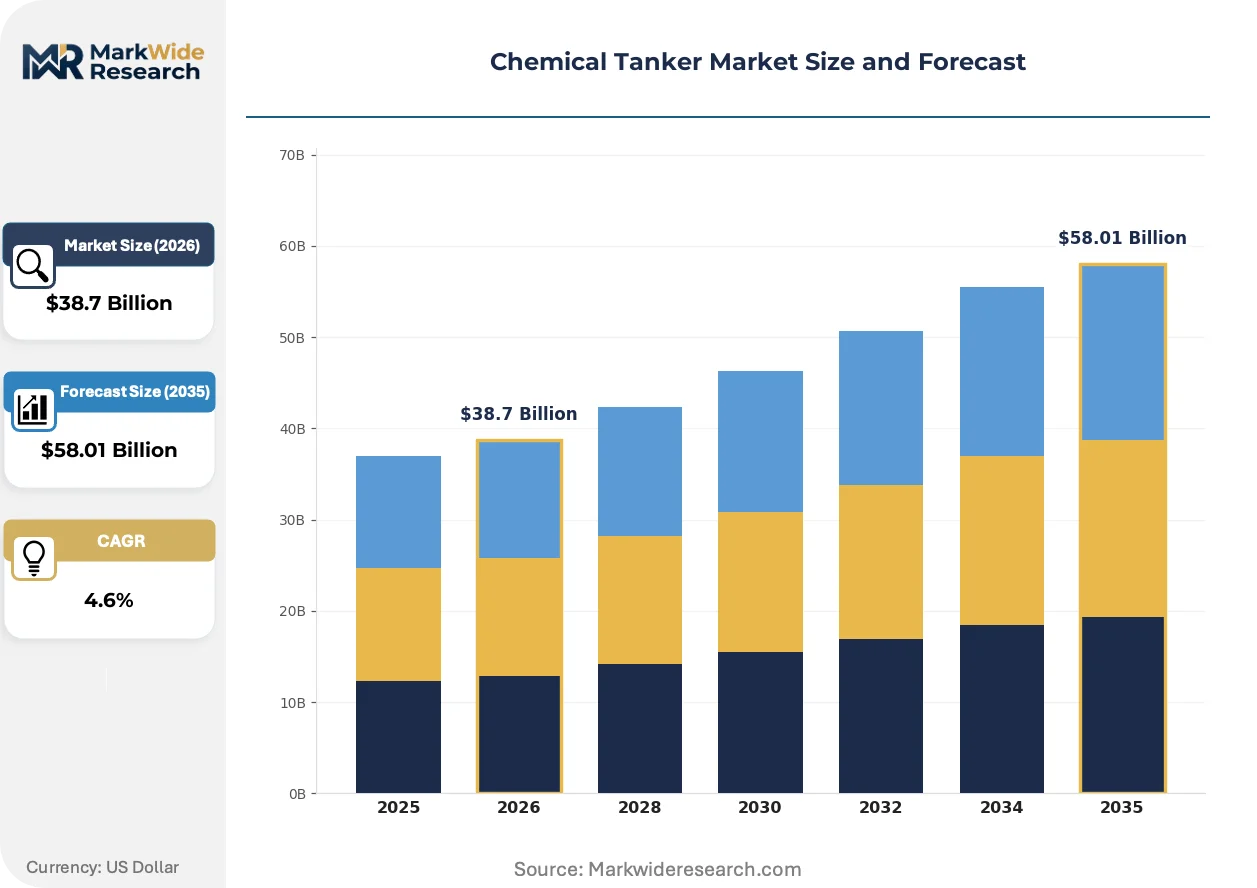
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Acids, Alcohols, Oils Application: Food Processing, Pharmaceuticals, Agriculture, Paints Technology: Vacuum, Pressure, Gravity, Specialized End User: Manufacturers, Distributors, Exporters, Retailers |
| Companies Covered | Hafnia, Ardmore Shipping, Stolt-Nielsen, Maersk Tankers, Scorpio Tankers, Odfjell SE, Navig8 Chemical Tankers, Bahri, MOL Chemical Tankers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Tanker Market Emerging Trajectories
Digital cargo-matching platforms and predictive maintenance algorithms are compressing traditional chartering cycles and reshaping how chemical tanker capacity gets priced and deployed. These technologies are eroding the information asymmetries that once protected established broker networks.
Advanced polymer tank linings with self-healing corrosion resistance are extending coating service intervals from five to ten years. Major petrochemical shippers in the Netherlands and Belgium are specifying these materials for new fixtures. Conventional epoxy coating maintenance schedules are rendering obsolete as charterers prioritize vessels with reduced drydock downtime.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in chemical tanker cooling systems. Shipowners operating European routes must retrofit with natural refrigerant alternatives or face port access restrictions. Temperature-sensitive cargo operators serving Rotterdam and Antwerp are accelerating fleet upgrades to comply with 2030 reduction targets.
Consolidated procurement by integrated oil majors is displacing fragmented spot-market chartering for base chemical movements. Large shippers in Texas and Louisiana now contract directly with tanker pools for three-year committed capacity. Independent shipowners without scale relationships are retreating to specialty cargo niches requiring stainless-steel segregation.
Chemical Tanker Market Segmentation
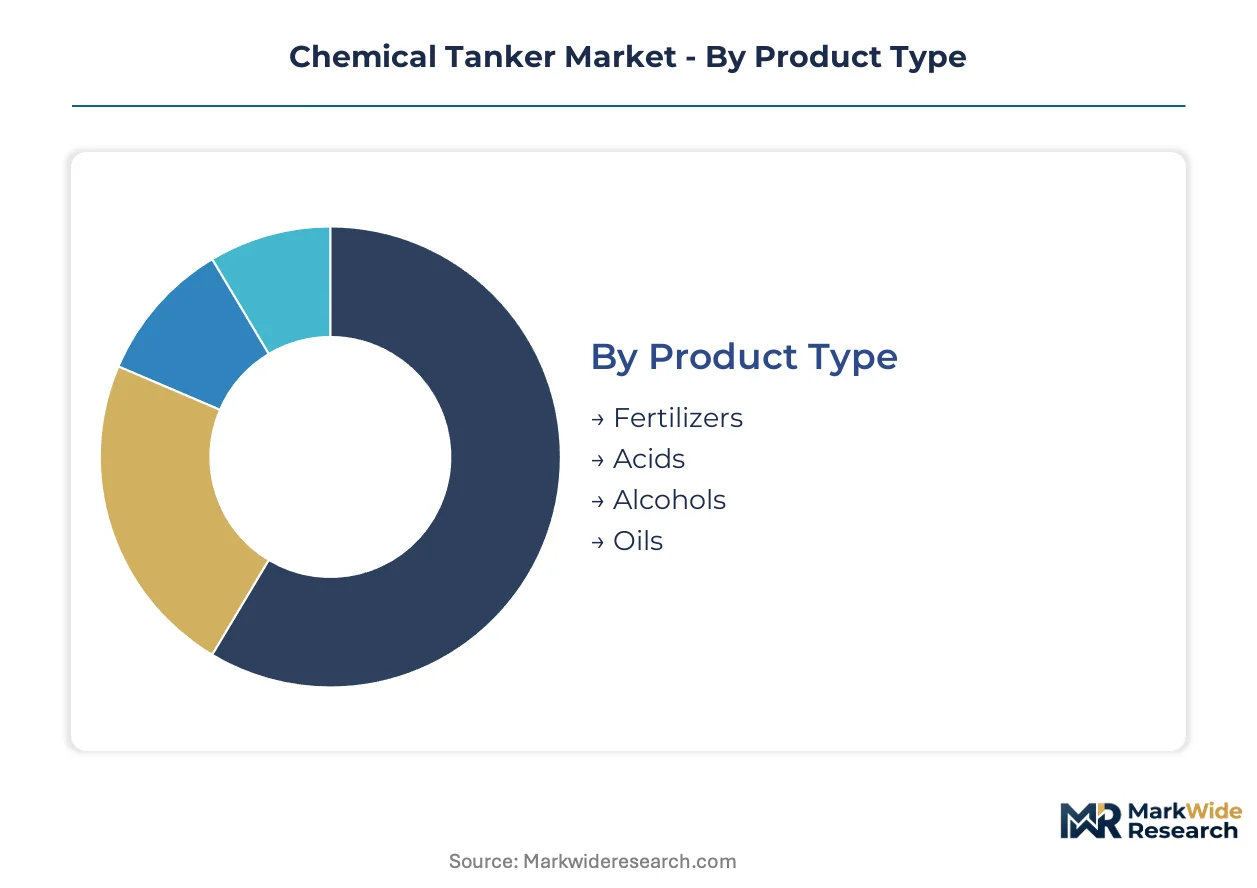
Chemical tanker segmentation determines vessel specifications, coating requirements, and charter rate premiums. Cargo compatibility rules and temperature sensitivity create rigid boundaries between transport categories.
Product Type:
Cost tier differentiation separates commodity movements from specialty chemical logistics requiring corrosion-resistant configurations.
- Acids:Sulfuric and phosphoric acid cargoes demand epoxy or phenolic tank linings resistant to pH extremes. Petrochemical processors in China's Yangtze Delta cluster are scaling import volumes of industrial acids for fertilizer derivative production, tightening vessel eligibility pools.
- Alcohols:Methanol, ethanol, and specialized alcohol cargoes require inert gas blanketing systems and explosion-proof pump configurations. Pharmaceutical manufacturers in Switzerland and Germany are expanding maritime procurement of high-purity solvent alcohols, commanding premium freight rates for stainless-steel tank segregation.
- Fertilizers:Ammonia and urea solutions move in coated mild-steel tanks with pressure-rated cargo systems.
- Oils:Edible and industrial oils utilize dedicated stainless-steel fleets with ISO cleaning protocols separate from chemical rotations.
Acids command the established base. The steepest expansion runs through alcohols.
Application:
End-use specifications determine cargo-handling protocols and certification requirements across destination markets.
- Pharmaceuticals:Active pharmaceutical ingredient intermediates and high-purity solvents require temperature-controlled transport between minus 10 and plus 40 degrees Celsius with continuous monitoring. Swissmedic and EMA documentation standards are tightening chain-of-custody requirements for temperature-sensitive pharmaceutical cargoes entering European ports.
- Food Processing:Edible oils, juice concentrates, and food-grade chemicals demand dedicated stainless-steel configurations with cleaning protocols verified by marine chemist certification. Rotterdam and Singapore shippers are creating dedicated fleet demand with three-year committed capacity contracts.
- Agriculture:Fertilizer derivatives and crop protection chemicals move in standard coated tankers with seasonal demand spikes.
- Paints:Solvents and resin precursors require compatibility verification for sequential loading patterns.
Food processing commands the established base. Pharmaceuticals show the steepest expansion trajectory.
Technology:
Transfer mechanism selection depends on cargo viscosity, vapor pressure, and port infrastructure limitations.
- Specialized:Cryogenic and heated tank systems maintain cargo temperatures between minus 50 and plus 220 degrees Celsius through integrated thermal management. China's coastal chemical parks along the Bohai Rim are scaling import volumes of temperature-sensitive intermediates, driving heated tanker capacity investment.
- Pressure:Liquefied gas and high-vapor-pressure chemicals utilize rated cargo containment with relief valve systems. South Korean shipyards are passing nickel alloy surcharges for pressure-rated stainless-steel newbuilds.
- Gravity:Low-viscosity liquids discharge through bottom outlet configurations with minimal pumping equipment.
- Vacuum:High-viscosity or solid-laden cargoes require suction discharge systems with heating coils.
Pressure systems command the established base. Specialized configurations gain share fastest.
End User:
Customer type shapes contract duration, fleet dedication, and pricing structure across the charter market.
- Manufacturers:Integrated chemical producers in Texas and Louisiana contract directly with tanker pools for three-year committed capacity on base chemical movements, displacing fragmented spot-market chartering. Consolidated procurement by oil majors is restructuring fleet deployment patterns.
- Distributors:Independent chemical traders rely on spot-market access with flexible vessel substitution across cargo grades. Digital freight platforms are reducing ballast voyages for distributor-serving independent owners through real-time cargo-matching algorithms.
- Exporters:Production-hub shippers require dedicated berth access and storage integration at load ports.
- Retailers:Downstream formulation plants purchase in smaller parcel sizes with frequent rotation requirements.
Manufacturers command the established base. Distributors are expanding most quickly through platform-enabled spot access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical terminal infrastructure anchors European maritime chemical logistics, while Singapore's Jurong Island petrochemical complex underwrites Asia-Pacific throughput capacity. These gateway assets determine regional fleet deployment patterns and coating specification requirements.
China
Yangtze Delta chemical processors are scaling import volumes of specialty solvents and temperature-sensitive intermediates. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate retirement of older coated tankers serving domestic routes. Bohai Rim industrial clusters near Tianjin are commissioning heated tanker capacity for polymer feedstock deliveries.
United States
Gulf Coast petrochemical expansions in Texas and Louisiana are restructuring contract chartering toward three-year committed capacity agreements. The EPA administers vessel discharge standards under the Clean Water Act that influence tank cleaning protocol investments. Houston Ship Channel throughput is concentrating stainless-steel tanker demand for high-purity chemical exports.
Germany
Pharmaceutical manufacturers in Ludwigshafen and Leverkusen are expanding maritime procurement of high-grade solvent alcohols. The Federal Maritime and Hydrographic Agency enforces EU F-Gas Regulation compliance for refrigerated cargo systems serving Hamburg and Bremen ports. Rhine-Main chemical logistics corridors are integrating with Rotterdam feeder services.
Singapore
Jurong Island petrochemical complexes are driving demand for dual-fuel chemical tankers compatible with emerging methanol bunkering infrastructure. The Maritime and Port Authority administers port dues incentives for low-emission vessel calls. Tuas Port development is consolidating Southeast Asian chemical transshipment volumes.
Netherlands
Rotterdam-Botlek chemical terminals are specifying advanced polymer tank linings with extended service intervals for European coastal trade. The Human Environment and Transport Inspectorate enforces REACH documentation standards that reduce inspection delays. Moerdijk industrial park shippers are contracting dedicated food-grade stainless-steel fleets.
Chemical Tanker Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on coating and tank configuration technology. The chemical tanker sector exhibits moderate consolidation with differentiated fleet strategies across stainless-steel and coated vessel categories. Three archetypes dominate: integrated technical management platforms, stainless-steel specialization operators, and cost-disciplined medium-range competitors. Competitive moves center on fleet renewal acceleration and biofuel-ready newbuild commitments.
Among Nordic-integrated operators, Stolt-Nielsen and Odfjell SE exemplify the stainless-steel specialization archetype for high-grade chemical cargoes. Hafnia anchors the technical management platform tier with integrated fleet deployment systems. These structures represent contrasting approaches to volatile trade lane utilization and cargo segregation requirements.
| Leading Market Players |
|---|
| Hafnia |
| Ardmore Shipping |
| Stolt-Nielsen |
| Maersk Tankers |
| Scorpio Tankers |
| Odfjell SE |
| Navig8 Chemical Tankers |
| Bahri |
| MOL Chemical Tankers |
| Others |
Supply Flow & Price Mechanics
Asia-Europe chemical freight corridors concentrate pricing power among stainless-steel tanker operators serving temperature-sensitive pharmaceutical cargoes, while coating-grade vessel rates compress under yard concentration and nickel alloy cost pass-through from South Korean and Japanese builders.
Pricing Analysis
Three-tier pricing structure across premium stainless-steel, standard coated, and economy-grade chemical tanker segments stratifies vessel day rates by cargo compatibility certification and heating system specifications. Price differentiation hinges on IMO MARPOL Annex II compliance tier and stainless-steel nickel content grade, with pharmaceutical shippers in Switzerland and Germany absorbing premium spreads for high-purity solvent segregation. Cost compression in the coated tanker tier is intensifying because Chinese state-owned shipyard delivery scarcity extends order backlogs and concentrates owner bargaining power. Distributor-serving independent operators exhibit highest price sensitivity due to spot-market exposure, while integrated oil majors committing three-year capacity contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for chemical tanker newbuild procurement and component sourcing. Vessel construction concentrates in China, South Korea, and Japan, with stainless-steel plate and nickel alloy feedstock drawing from Indonesian and Philippine mining operations. Single-source vulnerability in marine chemist certification pools—concentrated in Northern European and Japanese labor markets—threatens tank cleanliness verification throughput. Distribution runs through Rotterdam-Botlek terminal complexes and Singapore Jurong Island petrochemical hubs for European and Asia-Pacific coastal trade respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical tanker incumbents face substitution pressure from modular ISO tank container logistics on intra-regional pharmaceutical routes, requiring fleet specialization defense to sustain charter rate premiums.
For Market Incumbents: Entrench stainless-steel specialization through accelerated retirement of epoxy-coated legacy tonnage unable to meet IMO MARPOL Annex II coating specification tightening, while securing dual-fuel newbuild slots at Vietnamese and Philippine yards to circumvent Chinese state-owned builder delivery scarcity. Backward integration into technical management platforms sustains utilization across volatile trade lanes against independent spot-market competitors.
For New Entrants and Emerging Players: Pursue food-grade stainless-steel certification niches requiring ISO cleaning protocols separate from industrial chemical rotations, where Rotterdam and Singapore shippers are contracting dedicated fleet demand with three-year committed capacity agreements. Digital freight platform partnerships reduce ballast voyage exposure for distributor-serving independent owners through real-time cargo-matching algorithm integration.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants reshapes the acquisition landscape toward temperature-control system retrofit capabilities and natural refrigerant alternative vessel configurations. Five-to-ten year viability favors operators with biofuel-ready dual-fuel commitments and heated tanker capacity serving China's Bohai Rim polymer feedstock demand. Monitor methanol bunkering infrastructure deployment at Singapore and Rotterdam as fleet deployment pattern inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Stainless-Steel Fleet Renewal | IMO MARPOL Annex II compliance tiering eliminates legacy coated tanker eligibility for high-grade chemical cargoes. |
| Dual-Fuel Newbuild Commitment | Methanol bunkering infrastructure at Singapore and Rotterdam enables low-emission Asia-Europe route deployment. |
| Food-Grade Certification Investment | Rotterdam shippers contract dedicated stainless-steel fleets with ISO cleaning protocols for edible oil rotations. |
| Digital Platform Integration | Real-time cargo-matching algorithms compress ballast voyages for independent tanker owners in spot markets. |
| Technical Management Platform Expansion | Integrated fleet deployment systems sustain utilization volatility across specialty chemical trade lanes. |
Methodological Framework
The analysis maps stainless-steel versus coated tanker vessel categories, each validated through chartering executives, shipyard procurement managers, marine chemist certification bodies, and petrochemical shipper logistics directors. Primary interview intelligence triangulates against customs trade data, International Maritime Organization regulatory filings, classification society structural standards, and SEC 10-K fleet disclosure documents. Bottom-up vessel supply-demand modeling reconciles with top-down regional chemical throughput projections.
Forecast assumptions hold fixed the current IMO MARPOL Annex II regulatory enforcement trajectory while varying nickel price volatility scenarios and dual-fuel technology adoption curves across the analysis window. Segmentation dimensions span cargo compatibility tier, tank coating specification, temperature-control system configuration, and end-use industry pharmaceutical versus food-processing concentration. CAGRs derive from iterative capacity-demand balance modeling incorporating shipyard delivery slot availability and fleet retirement schedules.
Sensitivities concentrate around nickel alloy cost pass-through magnitude, Chinese state-owned shipyard delivery reliability, and EU F-Gas Regulation refrigerant phase-down enforcement timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
LNG Carrier Market