
 Singapore Autonomous Navigation Market | 2026-2036
Singapore Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Autonomous Navigation Market Insights
The gap between premium sensor fusion stacks and commodity GPS-dependent systems is shifting procurement patterns across Singapore's autonomous navigation sector. nuTonomy leverages its decade-long autonomous vehicle testing pedigree to anchor software validation protocols for urban deployments. Grab competes through its integrated mobility platform, controlling rider data streams that refine navigation algorithms. Hyundai Motor extends its manufacturing scale to supply purpose-built autonomous chassis for Southeast Asian operating conditions.
Autonomous navigation encompasses self-directed positioning and path-planning systems that fuse multi-sensor inputs to determine location, orientation, and trajectory without continuous human intervention. These systems typically integrate LiDAR point clouds, computer vision inference, and differential GPS corrections to achieve centimeter-level accuracy in dynamic environments, primarily serving industrial logistics and commercial transport applications where operational continuity demands reduced crew dependency. Computer vision segments dominate near-term deployment volumes as camera-based perception achieves cost parity for structured environments like container yards. LiDAR maintains premium positioning where millimeter-range accuracy prevents collision incidents in dense port traffic. Edge computing deployment architectures are gaining traction among maritime operators requiring sub-100-millisecond latency for dynamic obstacle avoidance without satellite connectivity dependency.
Singapore's Land Transport Authority governs autonomous vehicle testing through structured sandbox frameworks, while the Maritime and Port Authority coordinates unmanned vessel trials in designated port waters. The Infocomm Media Development Authority shapes data governance standards for navigation system telemetry, creating compliance thresholds that filter market entrants by cybersecurity maturity. Stakeholders must monitor how evolving liability frameworks allocate risk between system integrators and fleet operators as commercial deployments scale beyond controlled test zones.
Market Dynamics
The Land Transport Authority's regulatory sandbox compresses commercialization timelines for urban autonomous vehicle deployments, while the Maritime and Port Authority's designated trial zones accelerate vessel autonomy validation. This dual-track regulatory architecture shapes competitive positioning across Singapore's autonomous navigation sector.
Growth Catalysts
- Maritime Port Authority Trial Zones:Designated unmanned vessel testing corridors in Singapore's port waters reduce validation costs for logistics operators deploying autonomous container handling systems.
- Container Terminal Automation:Logistics operators face crew dependency constraints during peak throughput periods, driving procurement of autonomous navigation stacks for yard tractors and quay cranes.
- Edge Computing Architectures:Maritime operators deploy sub-100-millisecond latency systems for dynamic obstacle avoidance without satellite connectivity dependency in dense port traffic.
Market Restraints
- LiDAR Sensor Cost Concentration:Premium sensor fusion stacks remain dependent on concentrated offshore manufacturing for solid-state LiDAR arrays, compressing margin structures for domestic system integrators.
- Cybersecurity Compliance Thresholds:Infocomm Media Development Authority telemetry governance standards filter market entrants by maturity levels, creating barrier-to-entry friction for smaller software vendors.
- Commodity GPS System Substitution:Structured environments like container yards achieve adequate positioning accuracy through differential GPS corrections, limiting premium stack penetration in cost-sensitive deployments.
Strategic Opportunities
- Tuas Port Expansion:The phased opening of Singapore's next-generation container terminal creates greenfield deployment opportunities for fully autonomous yard operations without legacy system integration burden.
- Last-Mile Logistics Convergence:Integration of autonomous navigation with warehouse robotics and drone delivery networks enables end-to-end supply chain automation for e-commerce fulfillment operators.
- Land Transport Authority Commercial Licensing:Transition from sandbox testing to revenue-service permits creates regulatory clarity for mobility-as-a-service platforms deploying autonomous vehicle fleets.
Industry Challenges
- Multi-Sensor Calibration Expertise:Fusion of LiDAR point clouds with computer vision inference demands specialized systems engineering talent scarce in Singapore's domestic labor market.
- Liability Framework Ambiguity:Evolving risk allocation between system integrators and fleet operators creates insurance underwriting uncertainty that delays capital commitment for scaled deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Autonomous Navigation Market |
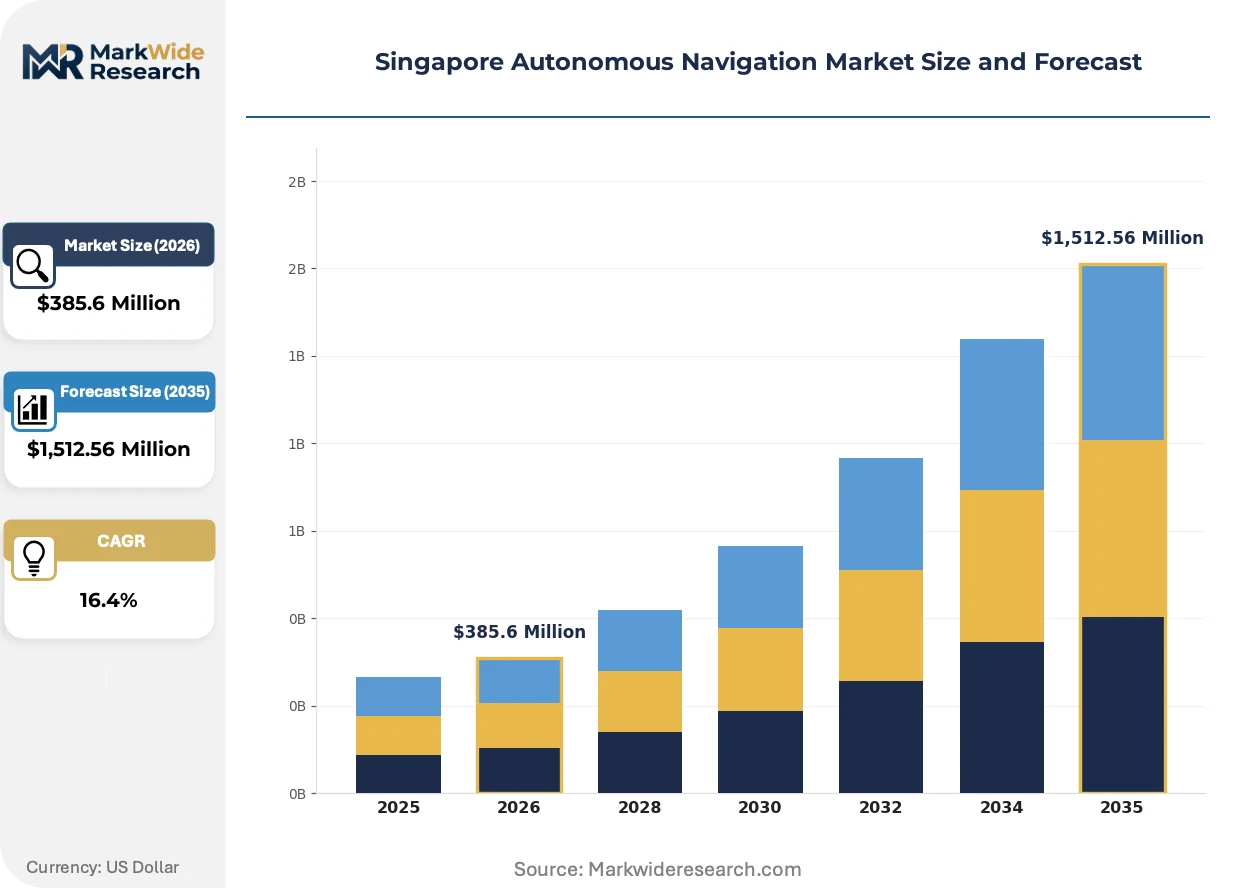
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,512.56 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Computer Vision, GPS, Ultrasonic Sensors Application: Logistics, Personal Mobility, Marine Navigation, Agriculture End User: Transportation Companies, Research Institutions, Maritime Sector, Agriculture Producers Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | nuTonomy, Grab, Moovita, Hyundai Motor, Renault, Baidu, Gojek, Toyota, SoftBank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Autonomous Navigation Market Trends and Innovations
Sensor fusion architectures and regulatory frameworks are actively reshaping procurement patterns across Singapore's autonomous navigation sector. Three developments dominate competitive positioning.
Camera-based perception systems are absorbing structured-environment navigation tasks previously requiring LiDAR arrays. Container terminal operators deploy computer vision stacks for yard tractor routing at cost parity with differential GPS systems. This absorption is compressing addressable market scope for premium sensor fusion vendors in logistics applications.
Singapore's Land Transport Authority has expanded its autonomous vehicle regulatory sandbox to permit revenue-service operations with remote supervision requirements. This policy evolution enables mobility platforms to transition from testing to commercial deployment. Urban logistics segments respond by accelerating fleet procurement timelines ahead of full unsupervised operation permits.
Logistics operators now unbundle navigation system procurement from vehicle chassis acquisition, selecting software stacks through competitive tender separate from hardware supply. This pattern disrupts traditional bundled sales channels dominated by original equipment manufacturers. The shift is most visible in port automation projects where terminal operators specify sensor fusion requirements independently of chassis vendors.
Singapore Autonomous Navigation Market Segmentation
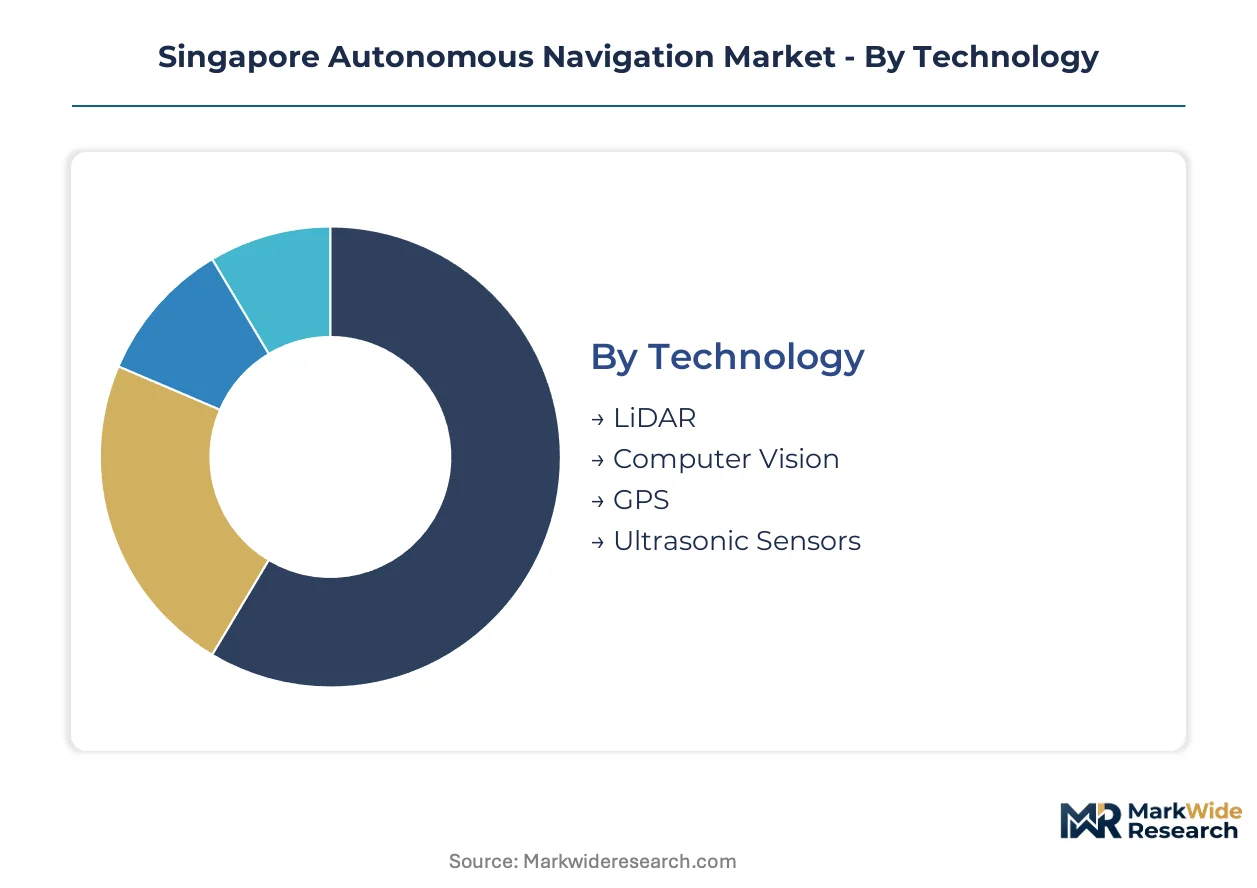
Segmentation in Singapore's autonomous navigation market reveals how procurement decisions diverge across certification requirements and operational environments. Technology choices, application priorities, and deployment architectures each carry distinct regulatory burdens that shape vendor selection and implementation timelines.
Technology:
Certification pathways from Singapore's Land Transport Authority and Maritime and Port Authority create divergent approval timelines across sensor modalities, with LiDAR and computer vision facing distinct validation protocols for urban versus maritime deployment zones.
- LiDAR:Solid-state arrays generate dense point clouds for millimeter-range obstacle detection in dense port traffic. Maritime operators at PSA Singapore terminals specify LiDAR fusion stacks for autonomous yard tractors where collision avoidance demands exceed camera-based perception limits, though concentrated offshore manufacturing constrains domestic margin structures.
- Computer Vision:Camera-based inference engines process visual feeds through neural network architectures optimized for structured container yard environments. Terminal operators at Jurong Port deploy computer vision navigation for quay crane positioning where differential GPS corrections provide adequate accuracy, achieving cost parity with premium sensor stacks in lane-marked zones.
- GPS:Differential correction systems leverage Singapore's SBAS infrastructure for centimeter-level positioning in open-sky maritime corridors.
- Ultrasonic Sensors:Short-range proximity detection supplements primary navigation stacks in low-speed terminal maneuvering zones.
Computer Vision sits at the top of the volume ranking, with Edge Computing climbing the fastest.
Application:
End-use concentration across Singapore's port cluster and urban mobility corridors determines which segments absorb near-term procurement investment versus longer-cycle validation requirements.
- Logistics:Container terminal automation drives procurement of autonomous navigation stacks for yard tractors, automated guided vehicles, and quay crane positioning systems. PSA Singapore's Tuas Port expansion creates greenfield deployment opportunities without legacy integration burden, while peak throughput constraints accelerate crew reduction mandates.
- Marine Navigation:Autonomous vessel trials in Maritime and Port Authority designated corridors validate collision avoidance algorithms for unmanned surface vessels. Harbor craft operators deploy navigation stacks for ship-to-shore logistics in restricted port waters where remote supervision requirements apply.
- Personal Mobility:Ride-hailing platforms navigate Land Transport Authority sandbox frameworks toward revenue-service permits with remote operator oversight.
- Agriculture:Precision farming applications remain nascent in Singapore's land-constrained context, limited to vertical farming automation and research trials.
Logistics commands the dominant procurement share, with Marine Navigation expanding most quickly through port authority trial zone acceleration.
End User:
Buyer sophistication and in-house systems engineering capability separate segments with unbundled software procurement from those defaulting to integrated vendor packages.
- Transportation Companies:Ride-hailing and logistics fleet operators specify navigation software independently of chassis supply, running competitive tenders for sensor fusion stacks that integrate with existing fleet management platforms.
- Maritime Sector:Terminal operators and harbor craft companies demand maritime-certified systems with IMO compliance documentation for vessel autonomy trials.
- Research Institutions:Universities and polytechnics validate algorithmic approaches through Land Transport Authority sandbox participation.
- Agriculture Producers:Vertical farming operators pilot limited-scope automation with minimal navigation complexity requirements.
Maritime Sector sits at the top of the volume ranking, with Transportation Companies climbing the fastest.
Deployment:
Latency requirements and connectivity availability in Singapore's port waters versus urban road networks drive architectural selection between centralized and distributed processing models.
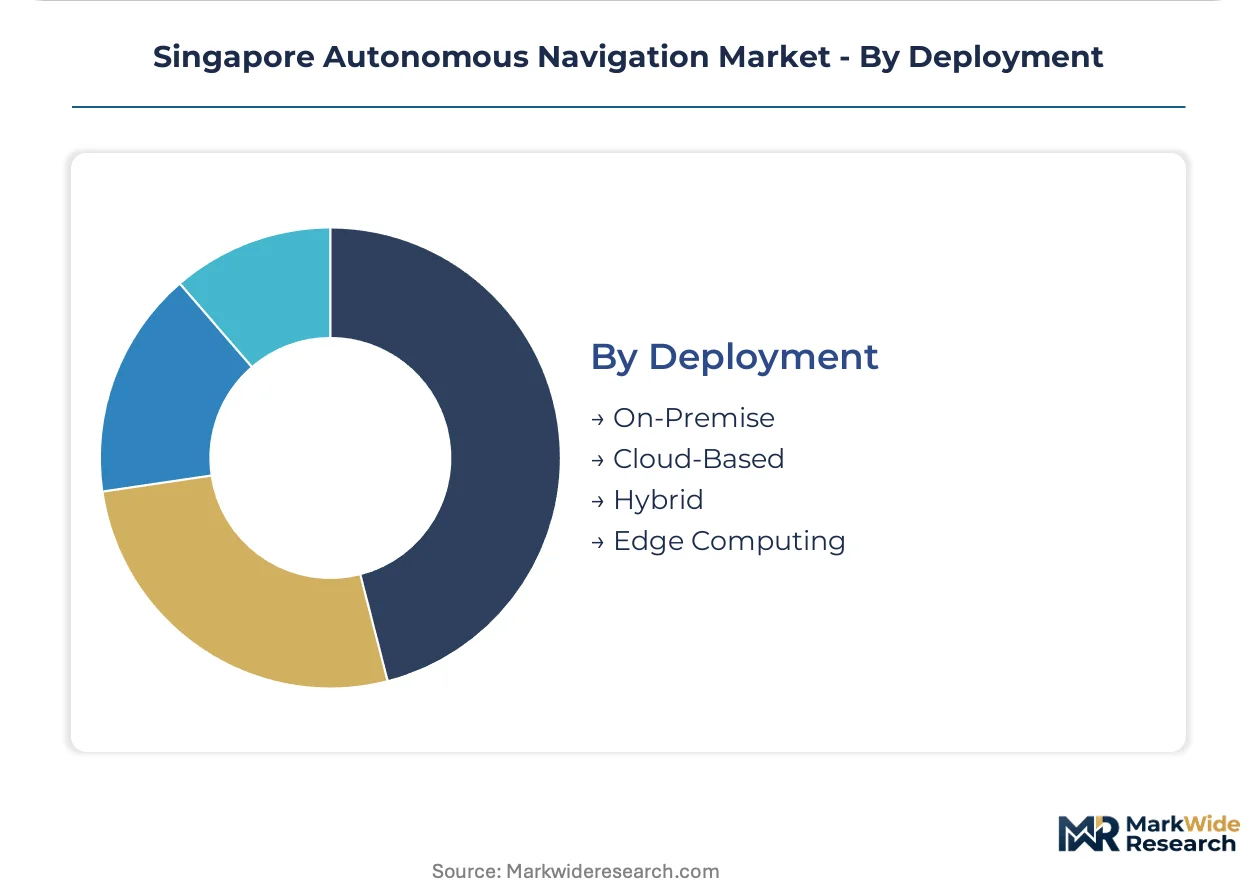
- Edge Computing:Sub-100-millisecond processing latency enables dynamic obstacle avoidance without satellite dependency in dense terminal traffic. Maritime operators at Pasir Panjang Terminal deploy edge architectures for autonomous yard tractors where 4G/5G coverage gaps would interrupt cloud-dependent navigation.
- Cloud-Based:Centralized model training and fleet-wide algorithm updates support urban autonomous vehicle deployments with continuous connectivity. Mobility platforms leverage cloud infrastructure for over-the-air navigation stack improvements across distributed vehicle fleets.
- Hybrid:Split processing architectures balance real-time decision requirements with centralized optimization for fleet coordination.
- On-Premise:Air-gapped installations serve defense and sensitive infrastructure applications with cybersecurity isolation mandates.
Edge Computing sits at the top of the volume ranking, with Cloud-Based climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's autonomous navigation sector draws engineering talent from its polytechnic cluster and specialized maritime training institutes, anchoring regional capability development across Southeast Asian deployment corridors.
Malaysia
Iskandar Malaysia's special economic zone hosts cross-border logistics pilots connecting Johor Port to Singapore's Tuas terminal. The Malaysia Digital Economy Corporation accelerates autonomous vehicle testing permits for commercial corridor applications. Port of Tanjung Pelepas operators trial yard automation systems with sensor fusion specifications matching Singaporean terminal standards.
Indonesia
Nusantara capital city development creates greenfield demand for autonomous public transit and logistics infrastructure without legacy system constraints. Indonesia's Ministry of Transportation issued autonomous vehicle testing guidelines modeled on Singapore's sandbox framework. Batam's free trade zone electronics manufacturers supply camera modules and edge computing hardware to Singapore system integrators.
Vietnam
Ho Chi Minh City's smart city initiative deploys autonomous shuttle pilots in District 2 innovation precincts. Vietnam's Ministry of Science and Technology coordinates with Singapore regulators on mutual recognition of navigation system certifications. Da Nang's port automation projects adopt Singapore-validated collision avoidance algorithms for container yard operations.
Thailand
Eastern Economic Corridor logistics operators seek autonomous yard tractor systems for Laem Chabang Port expansion phases. Thailand's Ministry of Transport established autonomous vehicle testing zones in Chonburi province with regulatory protocols referencing Singapore's Land Transport Authority frameworks. Bangkok's ride-hailing platforms evaluate Singapore-proven remote supervision architectures for future fleet deployment.
Philippines
Cebu Port Authority examines autonomous navigation for inter-island cargo operations across archipelago logistics chains. The Department of Transportation's public utility vehicle modernization program creates demand for driver-assist systems with upgrade paths to full autonomy. Manila's gateway terminal operators consult Singapore maritime autonomy trial data for vessel collision avoidance system procurement.
Singapore Autonomous Navigation Market Competitive Landscape
Top-tier vendors anchor integrated mobility platforms, while specialized sensor fusion developers and automotive original equipment manufacturers populate lower tiers with component and chassis supply. The market structure concentrates around three strategic archetypes: software-first autonomy stack developers, platform-integrated mobility operators, and manufacturing-scale vehicle suppliers. Competitive moves center on unbundled software procurement patterns and regulatory sandbox participation acceleration.
Within the software validation tier, nuTonomy exemplifies decade-long urban testing pedigree applied to sandbox protocol development. Among platform-integrated operators, Grab occupies a position leveraging rider data streams for algorithmic refinement. Hyundai Motor represents manufacturing-scale supply of purpose-built autonomous chassis for Southeast Asian operating conditions.
| Leading Market Players |
|---|
| nuTonomy |
| Grab |
| Moovita |
| Hyundai Motor |
| Renault |
| Baidu |
| Gojek |
| Toyota |
| SoftBank |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed terminal operators at PSA Singapore and Jurong Port anchor procurement discipline through competitive tender processes that unbundle navigation software from chassis supply, compressing margin structures for system integrators while rewarding vendors with maritime certification pedigree.
Pricing Analysis
Bundled sensor-vehicle packages from Hyundai Motor and Toyota compete against unbundled software procurement where terminal operators specify LiDAR fusion requirements independently. Pricing stratifies across maritime-certified premium stacks, computer vision mid-tier systems, and differential GPS economy configurations for structured yard environments. Cost compression in the economy tier intensifies as commodity GPS systems achieve adequate accuracy for lane-marked container zones. Logistics operators show highest price sensitivity in yard tractor deployments, while marine navigation segments absorb premium pricing for collision avoidance certification.
Supply Chain Analysis
Regional distribution centers in Singapore's Jurong and Tuas port clusters feed hub-and-spoke deployment patterns across Southeast Asian maritime corridors. Solid-state LiDAR arrays draw from concentrated manufacturing in China, Japan, and Germany, while edge computing hardware sources from Batam's free trade zone electronics cluster. Single-source vulnerability in solid-state LiDAR emitters creates procurement risk for domestic system integrators. Distribution runs through maritime equipment distributors with IMO compliance documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's autonomous navigation market represents a late-cycle quality story where procurement shifts toward maritime-certified sensor fusion stacks with sub-100-millisecond latency specifications.
For Market Incumbents: To counter unbundled software procurement patterns disrupting traditional bundled sales channels, deepen backward integration into edge computing hardware production and secure exclusive distribution agreements with maritime equipment specialists possessing IMO compliance documentation capabilities. For New Entrants and Emerging Players: Begin with computer vision navigation for structured container yard environments where cost parity with differential GPS systems creates accessible entry points, then leverage sandbox participation credentials to graduate toward revenue-service permits with remote supervision architectures. For Investors and Strategic Acquirers: Maritime logistics operators are the most active acquirer in this space, targeting sensor fusion developers with decade-long urban testing pedigrees and established regulatory sandbox relationships. The inflection signal to monitor is Land Transport Authority transition from remote supervision requirements to full unsupervised operation permits.| Strategic Initiative | Industry Significance |
|---|---|
| Maritime Certification Investment | IMO compliance documentation unlocks procurement eligibility at PSA Singapore's Tuas Port expansion. |
| Edge Computing Hardware Integration | Sub-100-millisecond latency systems eliminate satellite dependency in dense Pasir Panjang Terminal traffic. |
| Regulatory Sandbox Acceleration | Land Transport Authority revenue-service permits enable commercial deployment ahead of full autonomy standards. |
| Sensor Fusion Unbundling | Software procurement separate from chassis supply disrupts Hyundai Motor and Toyota bundled channels. |
| Cross-Border Logistics Pilots | Iskandar Malaysia corridor trials validate interoperability with Johor Port terminal automation systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with autonomous vehicle fleet managers, maritime terminal operations directors, sensor fusion engineering leads, and Land Transport Authority regulatory officials with secondary validation against Maritime and Port Authority trial zone disclosures, Infocomm Media Development Authority telemetry governance standards, and PSA Singapore terminal automation procurement records. Bottom-up deployment estimates triangulated against top-down port throughput capacity modeling.
Historical reference periods anchored the projection horizon through documented sandbox participation timelines and commercial licensing transition patterns. Segmentation dimensions modeled include sensor modality certification pathways, application environments spanning logistics and marine navigation, deployment architectures balancing edge and cloud processing, and end-user sophistication separating unbundled procurement from integrated vendor packages. CAGRs derived from terminal automation investment cycles and autonomous vessel trial acceleration curves.
Several conditions sit outside the modeled scope, including defense and aerospace navigation applications, consumer automotive autonomy beyond ride-hailing platforms, and agricultural robotics outside vertical farming pilots. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Europe Autonomous Navigation Market