
 Ship Breaking Market | 2026-2036
Ship Breaking Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Breaking Market Analytics
Higher-grade steel segregation and hazardous-material certification tiers is rotating the competitive landscape toward yards with advanced gas-freeing and asbestos-handling protocols. PHP Ship Breaking and Recycling Industries leverages its Bangladeshi coastal permits to anchor high-volume demolition contracts for obsolete tankers. International Shipbreaking LLC sustains specialized capabilities at its Texas facility for U.S. Navy vessel disposal under strict environmental oversight. Alang Ship Yard dominates the Indian coastline through scale advantages across multiple simultaneous berths.
Ship breaking encompasses the systematic dismantling of end-of-life vessels to recover ferrous and non-ferrous metals, machinery, and equipment through cutting, lifting, and sorting processes typically conducted at coastal beaching sites or dry dock facilities. The primary purpose centers on material recovery—particularly steel plate and structural sections—for re-rolling into construction-grade products while managing toxic residues including PCBs, heavy metals, and residual fuels. Steel recovery from obsolete vessels leads material-type segmentation due to volume scale and established re-rolling mill demand across South Asian construction markets. Marine salvage services within the service-type category attract premium margins where intact propulsion systems or navigation equipment retain resale value to secondary operators.
The Hong Kong Convention for the Safe and Environmentally Sound Recycling of Ships shapes operational standards for yard certification and inventory-of-hazardous-materials documentation, while national regulators including Bangladesh's Department of Environment and India's Ministry of Shipping enforce coastal compliance through beaching permits and waste-handling audits. The EU Ship Recycling Regulation creates dual-track market access where European-flagged vessels must utilize approved yard lists, fragmenting contract flows between certified and non-certified facilities. Stakeholders must monitor convergence between international convention ratification timelines and unilateral regulatory enforcement to anticipate capacity reallocations across the Bangladesh-India-Pakistan dismantling corridor.
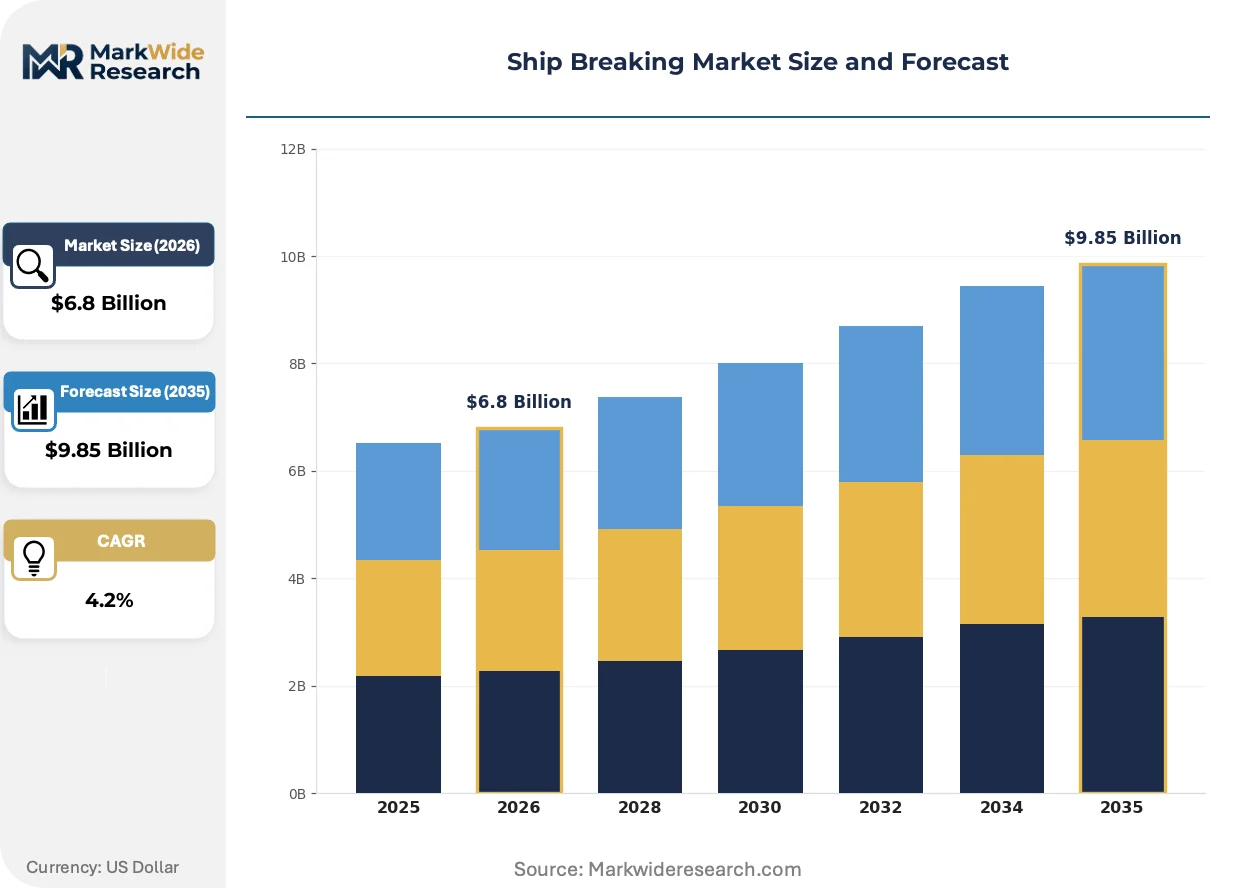
Market Dynamics
The Hong Kong Convention's pending enforcement is compressing certification timelines across South Asian dismantling yards, forcing capital deployment into gas-freeing infrastructure and hazardous-material documentation systems ahead of formal ratification deadlines.
Growth Catalysts
- EU Ship Recycling Regulation:European-flagged vessel mandates are diverting high-value demolition contracts toward certified South Asian facilities, expanding addressable contract pools for compliant yards in Bangladesh and India.
- Construction-grade steel demand:Re-rolling mills across South Asia are absorbing ferrous plate recovered from obsolete tankers and bulk carriers to feed infrastructure buildouts in Dhaka, Mumbai, and Karachi.
- Tidal beaching geography:Bangladesh's Sitakunda coastline and India's Alang-Sosiya stretch provide natural intertidal zones that minimize dry-dock capital requirements for vessel grounding and sectioning operations.
Market Restraints
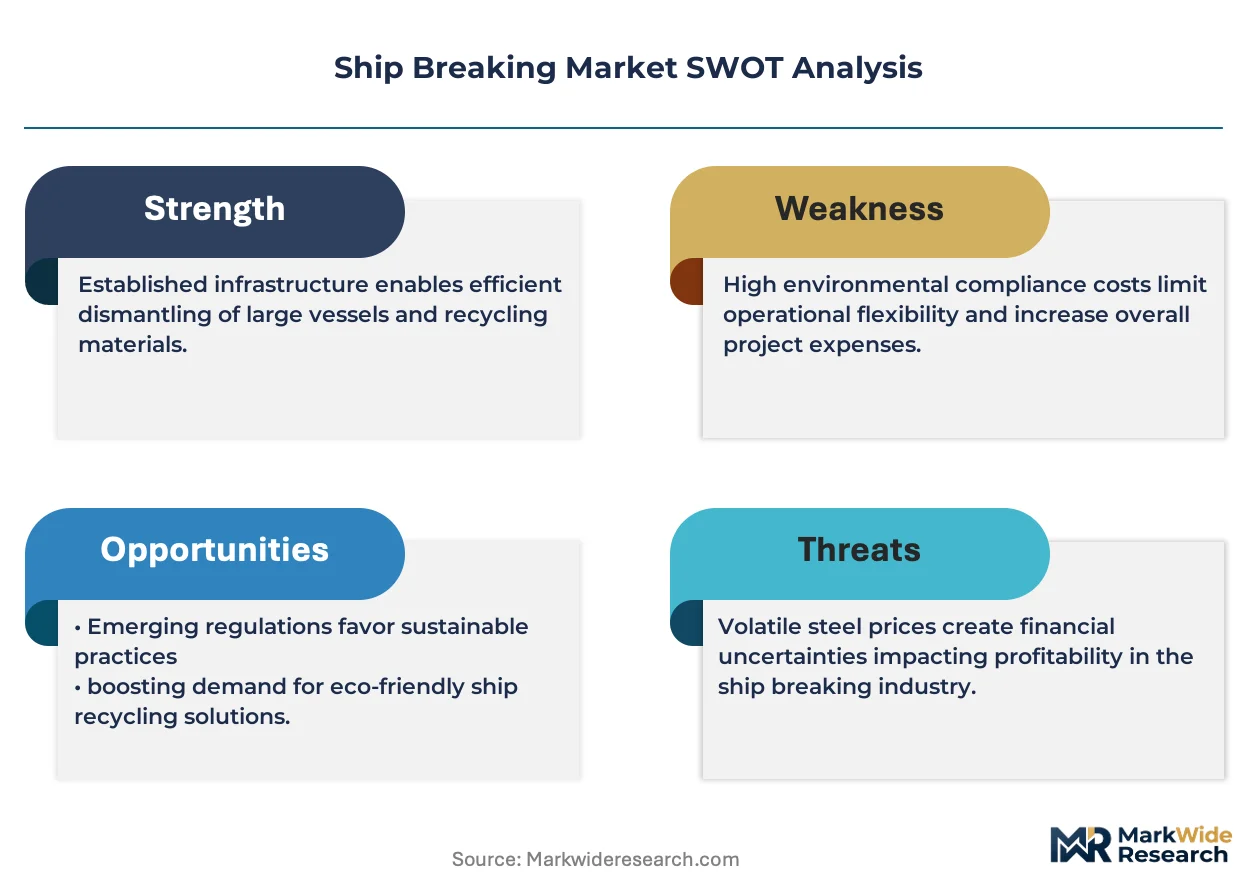
- Steel price volatility:Scrap metal valuation swings compress demolition contract margins when international ferrous benchmarks drop below break-even recovery economics for labor-intensive dismantling.
- Single-corridor supply concentration:Overwhelming dismantling capacity clusters along Bangladesh-India-Pakistan coastlines, creating geopolitical and climate-risk exposure without geographic diversification buffers.
- Hong Kong Convention ratification delays:Incomplete international adoption maintains regulatory fragmentation, forcing yards to maintain dual compliance systems for EU-regulated versus non-EU vessel flows.
Strategic Opportunities
- Green ship recycling certification:Early alignment with ISO 30000 and Hong Kong Convention inventory standards positions select yards for premium contract tiering as European owners accelerate ESG-mandated fleet renewal.
- Marine equipment resale channels:Intact propulsion systems, auxiliary engines, and navigation electronics from dismantled vessels are finding secondary markets through specialized salvage brokers in Singapore and Dubai.
- Beaching-to-dry-dock migration:Investment in floating dry docks and pier-side cutting infrastructure addresses EU Ship Recycling Regulation facility standards while reducing tidal schedule dependencies.
Industry Challenges
- Certified gas-freeing technician scarcity:Safe tank and void-space atmosphere verification requires specialized training that outpaces current vocational pipeline output across Bangladeshi and Indian coastal districts.
- Asbestos and PCB remediation capex:Proper hazardous-material containment infrastructure demands capital outlays that strain smaller yard operators already operating on thin demolition contract margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Breaking Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Copper, Fiberglass End User Type: Shipyards, Recycling Facilities, Construction, Metal Traders Service Type: Marine Salvage, Dismantling, Refurbishing, Transportation Equipment Used: Cranes, Shears, Cutters, Bulldozers |
| Companies Covered | PHP Ship Breaking and Recycling Industries, International Shipbreaking LLC, Alang Ship Yard, Amix Real Estate Holdings, Wan Hai Lines, Chittagong Ship Yard, Ratanpur Ship Recycling Industries, Carnival Cruise Line, Gadani Ship Breaking Yard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Breaking Market Evolving Landscape
Systematic vessel dismantling is experiencing technology-driven efficiency compression alongside regulatory documentation digitization, reshaping how yards manage inventory tracking and material segregation workflows.
Automated oxy-fuel cutting systems with plasma-arc precision are displacing manual torch operations in larger Indian and Bangladeshi facilities. Alang-based operators with capital access are adopting CNC-guided sectioning equipment to reduce plate damage and improve steel recovery yields. This capital-intensive shift is displacing smaller beaching yards unable to finance mechanized cutting infrastructure, concentrating high-value demolition contracts among scaled operators.
Bangladesh's Department of Environment is tightening coastal compliance through mandatory hazardous-material inventory documentation ahead of Hong Kong Convention ratification. Yard operators must now submit detailed IHM (Inventory of Hazardous Materials) reports for each vessel prior to beaching approval, extending pre-dismantling timelines. The regulatory friction most affects mid-sized facilities lacking dedicated environmental compliance staff, pushing contract concentration toward vertically integrated yard groups with in-house documentation capabilities.
European shipowners are unbundling demolition contracting from traditional ship-management relationships, establishing direct procurement relationships with certified South Asian yards. This channel disintermediation bypasses Singapore-based brokers who historically captured margin between vessel sellers and dismantling operators. The behavioral shift is most visible among German and Greek tanker fleets where ESG disclosure requirements demand traceable recycling chain-of-custody documentation.
Ship Breaking Market Segmentation
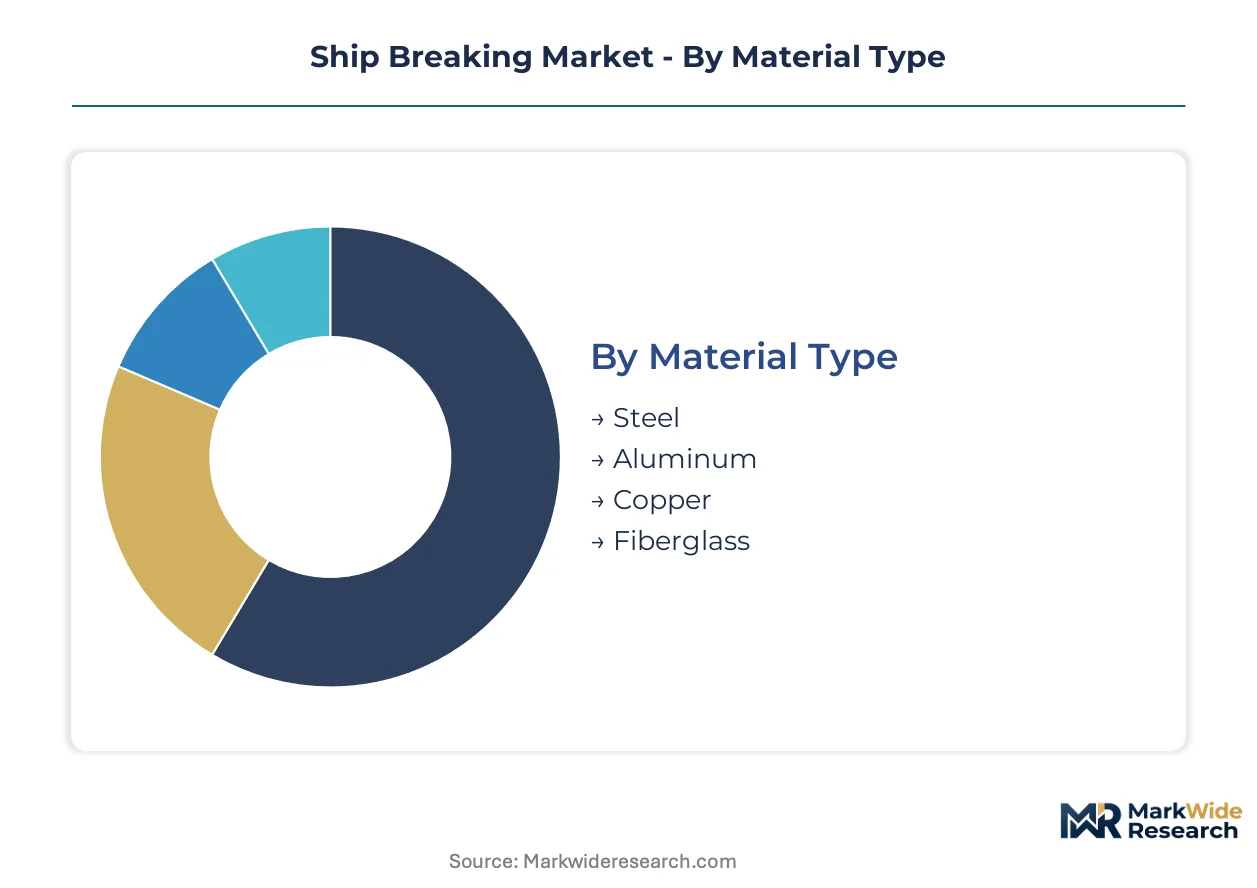
Segmentation in ship breaking reveals how material recovery economics, service specialization, and equipment intensity fragment contract value across the dismantling value chain. Understanding these divides exposes where capital deployment and regulatory compliance concentrate competitive advantage.
Material Type:
Steel faces substitution pressure from composite hull designs in newer vessel construction, threatening long-term feedstock availability for South Asian re-rolling mills.
- Steel:Structural plate and section steel dominates recovered tonnage from obsolete tankers and bulk carriers. Bangladeshi re-rolling mills in Chittagong absorb this feedstock for construction-grade rerolling, though volatile ferrous benchmarks compress yard margins during price troughs.
- Aluminum:Superstructure and deckhouse alloys command premium recovery values due to energy-intensive primary production substitution. Indian smelters in Gujarat source dismantled vessel aluminum to bypass bauxite refining costs.
- Copper:Wiring and piping fractions from electrical systems and plumbing networks.
- Fiberglass:Hull laminates from recreational craft and specialized vessels requiring landfill disposal or cement kiln co-processing.
Steel retains volume leadership; aluminum holds the steepest expansion curve.
End User Type:
Downstream absorption capacity varies sharply by sector, with construction-grade steel demand outpacing maritime equipment reuse channels.
- Shipyards:Secondary operators in Southeast Asia and the Middle East purchase intact propulsion systems, auxiliary engines, and navigation equipment from dismantled vessels. Singapore-based marine equipment brokers mediate these transactions, capturing margin through technical inspection and refurbishment coordination.
- Recycling Facilities:Ferrous and non-ferrous metal processors receive sorted scrap streams from dismantling yards. Pakistan's Gadani coastline hosts concentration of re-rolling mills integrated with beaching operations.
- Construction:Re-rolled steel plate feeds infrastructure buildouts in Dhaka, Mumbai, and Karachi.
- Metal Traders:Speculative arbitrageurs bridge timing gaps between vessel purchase and scrap sale.
Construction absorbs the largest volume share; shipyards generate the highest unit margins.
Service Type:
Service intensity correlates inversely with asset residual value, with intact equipment recovery commanding premium pricing over commodity scrap.
- Marine Salvage:Recovery of operational machinery and electronics before hull cutting. Dubai-based brokers specialize in resale of second-hand marine equipment to African and Southeast Asian fleet operators.
- Dismantling:Systematic hull sectioning and material segregation through oxy-fuel cutting and mechanical shearing. Bangladesh's Sitakunda yards perform this labor-intensive work across tidal beaching zones.
- Refurbishing:Engine rebuilding and equipment reconditioning for secondary market insertion.
- Transportation:Logistics coordination for scrap movement to re-rolling mills and hazardous waste to licensed disposal facilities.
Dismantling commands the greatest labor deployment; marine salvage delivers the steepest margin expansion.
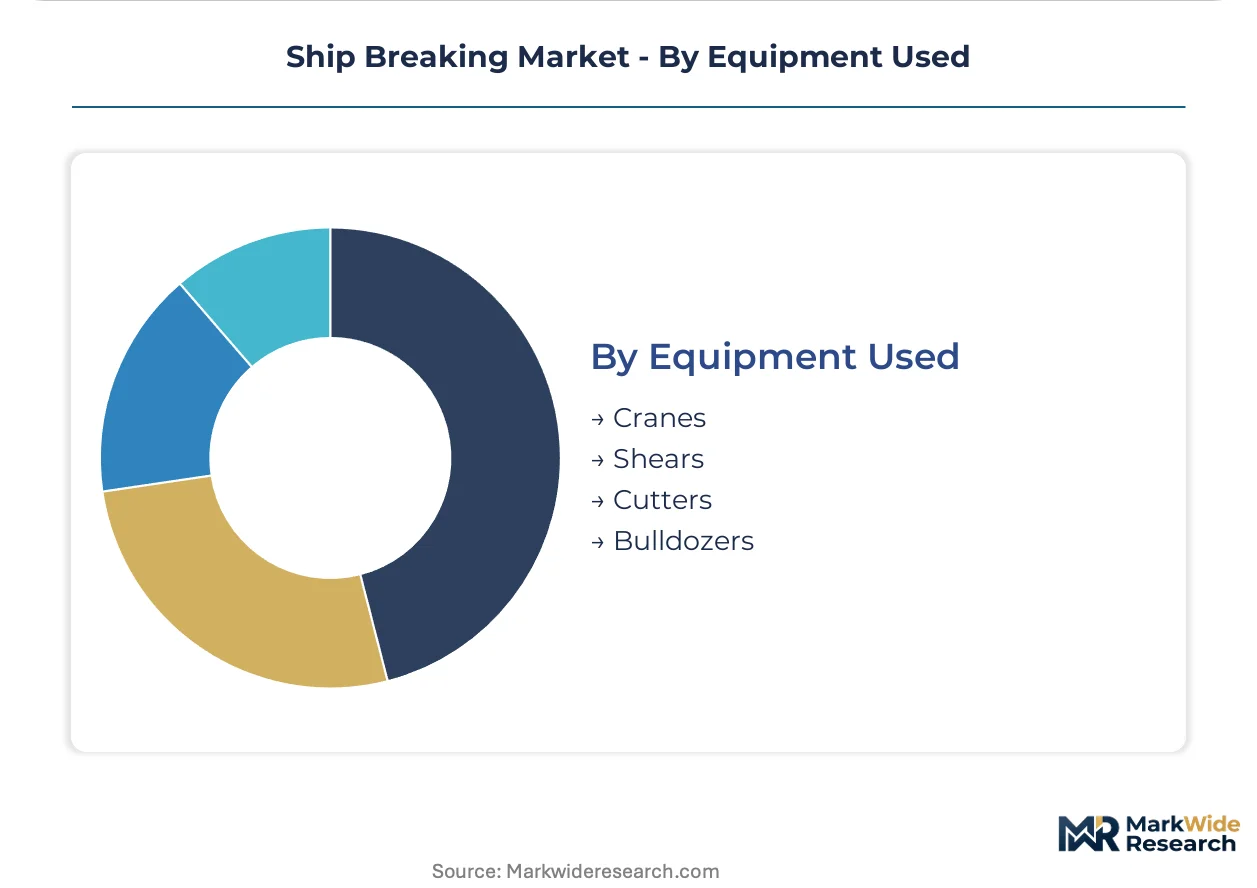
Equipment Used:
Mechanization intensity separates scaled operators from manual beaching yards, with capital access determining productivity ceilings.
- Cranes:Heavy-lift crawler and floating cranes position hull sections for cutting access. Alang-based operators with capital access deploy 200-tonne capacity units across multiple simultaneous berths.
- Shears:Hydraulic scrap shears process structural sections into furnace-ready dimensions. Mechanized cutting displaces manual torch operations in larger Indian facilities.
- Cutters:Oxy-fuel and plasma-arc systems for precision plate sectioning.
- Bulldozers:Earthmoving equipment for tidal zone preparation and scrap aggregation.
Cranes absorb the greatest capital investment; shears deliver the fastest productivity gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in steel scrap and vessel decommissioning schedules create divergent dismantling economics across coastal economies. Bangladesh, India, and Pakistan absorb obsolete tonnage from European and East Asian fleets while generating construction-grade steel for domestic infrastructure buildouts. Regulatory divergence between EU Ship Recycling Regulation compliance zones and conventional beaching yards fragments contract flows.
Bangladesh
Chittagong's Sitakunda coastline anchors the world's largest beaching yard concentration, processing tankers and bulk carriers for domestic re-rolling mills. The Department of Environment enforces mandatory Inventory of Hazardous Materials documentation ahead of Hong Kong Convention ratification, extending pre-dismantling approval timelines. PHP Ship Breaking and Recycling Industries and Chittagong Ship Yard operate across this tidal zone, feeding steel plate to construction markets in Dhaka.
India
Gujarat's Alang-Sosiya stretch hosts simultaneous multi-berth operations with capital-intensive crane infrastructure for precision steel recovery. The Ministry of Shipping coordinates coastal compliance through beaching permits and waste-handling audits aligned with Hong Kong Convention standards. Alang Ship Yard dominates throughput volume, while smaller facilities struggle with gas-freeing technician shortages and asbestos remediation capital requirements.
Pakistan
Gadani's coastline integrates beaching operations with captive re-rolling mill capacity, reducing scrap transport costs to Karachi construction markets. National environmental regulators enforce hazardous-material handling protocols through coastal zone management frameworks. Gadani Ship Breaking Yard anchors regional dismantling activity despite periodic safety enforcement actions that disrupt operational continuity.
United States
Texas-based dismantling facilities capture U.S. Navy vessel disposal contracts under strict EPA environmental oversight, commanding premium margins for specialized hazardous-material handling. International Shipbreaking LLC sustains operations at this facility, serving federal fleet renewal programs with documented chain-of-custody compliance. The domestic market remains isolated from South Asian price competition due to labor cost differentials and regulatory stringency.
Turkey
Aliaga's ship recycling zone offers EU-proximate dismantling capacity for European-flagged vessels seeking reduced transit costs to certified facilities. Turkish environmental regulators align yard certification with EU Ship Recycling Regulation standards, creating competitive positioning for ESG-mandated fleet owners. The cluster processes cruise ships and naval vessels with dry-dock infrastructure that reduces tidal scheduling dependencies.
Ship Breaking Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and capital intensity dimensions. The vendor base stratifies between integrated yard groups with in-house environmental compliance capabilities and smaller beaching operators dependent on broker-mediated contract flows. Three archetypes dominate: tidal beaching specialists with scale advantages, dry-dock facilities with EU certification premiums, and naval disposal contractors with government security clearances. Competitive moves concentrate on Hong Kong Convention pre-ratification certification investments and direct procurement relationships that disintermediate Singapore-based brokers.
Among Bangladeshi coastal operators, PHP Ship Breaking and Recycling Industries exemplifies the integrated yard group archetype with permitted beaching capacity and vertical coordination with re-rolling mills. International Shipbreaking LLC occupies a position within the specialized naval disposal tier, serving U.S. federal contracts with documented environmental compliance. Alang Ship Yard represents scale-driven Indian dismantling, anchoring multi-berth throughput across Gujarat's coastline. These three entities illustrate how geographic concentration, regulatory positioning, and capital access fragment competitive advantage across the dismantling corridor.
| Leading Market Players |
|---|
| PHP Ship Breaking and Recycling Industries |
| International Shipbreaking LLC |
| Alang Ship Yard |
| Amix Real Estate Holdings |
| Wan Hai Lines |
| Chittagong Ship Yard |
| Ratanpur Ship Recycling Industries |
| Carnival Cruise Line |
| Gadani Ship Breaking Yard |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between European shipowners and certified South Asian yards lock in vessel demolition access while stabilizing price visibility against volatile ferrous scrap benchmarks. These arrangements concentrate pricing power among vertically integrated operators in Bangladesh and India who can guarantee Hong Kong Convention compliance.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the ship breaking market. Price differentiation hinges on certification grade under EU Ship Recycling Regulation standards and volume scale of vessel tonnage. Cost compression in economy-tier beaching yards is intensifying because smaller operators lack gas-freeing infrastructure to qualify for European-flagged contracts. Fleet operators with ESG-mandated fleet renewal programs exhibit the lowest price sensitivity, while speculative vessel brokers demonstrate acute responsiveness to scrap metal valuation swings.
Supply Chain Analysis
Bangladesh, India, and Pakistan anchor global ship dismantling capacity through tidal beaching corridors feeding re-rolling mills. Raw material inputs draw from obsolete tankers, bulk carriers, and container vessels retired from European and East Asian fleets. Single-corridor supply concentration creates geopolitical risk exposure without geographic diversification buffers. Distribution runs through Singapore-based marine equipment brokers for intact machinery resale and direct mill relationships for ferrous scrap absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ship breaking market fragmentation creates entry niches as regulatory compliance requirements displace smaller beaching operators unable to finance certification investments. The demand-side shift toward traceable recycling chain-of-custody documentation splits contract flows between certified and conventional facilities.
For Market Incumbents: Secure Hong Kong Convention pre-ratification certification ahead of formal enforcement deadlines to capture diverted European-flagged vessel flows. Defensive consolidation of gas-freeing technician training pipelines addresses capability scarcity threatening operational continuity. Alang-based operators with capital access should expand crane infrastructure across multiple simultaneous berths to maintain throughput scale advantages. For New Entrants and Emerging Players: Lead with dry-dock facility investments in Turkey's Aliaga zone to serve EU-proximate demand from ESG-mandated cruise operators. The most penetrable segment lies in marine salvage services for intact propulsion system recovery, where Dubai-based brokers currently capture excessive margin. A specialized go-to-market angle centers on direct procurement relationships that bypass Singapore-based intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated yard groups with in-house hazardous-material documentation capabilities and permitted coastal access. Long-term viability over the coming decade favors operators positioned at the intersection of EU Ship Recycling Regulation compliance and captive re-rolling mill relationships. The signal to watch is Hong Kong Convention ratification velocity across South Asian jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Hong Kong Convention Certification Investment | Unlocks European-flagged vessel contract pools ahead of ratification deadlines. |
| Gas-Freeing Infrastructure Deployment | Addresses certified technician scarcity constraining Bangladeshi and Indian yard expansion. |
| Direct Procurement Channel Development | Bypasses Singapore-based brokers to capture margin between vessel sellers and dismantlers. |
| Beaching-to-Dry-Dock Migration | Reduces tidal schedule dependencies while meeting EU Ship Recycling Regulation facility standards. |
| Marine Equipment Resale Partnership | Connects intact propulsion systems with secondary operators through Dubai and Singapore brokers. |
Research Methodology
Operator-level perspectives from yard managers, marine equipment brokers, re-rolling mill procurement leads, and regulatory compliance officers anchored the qualitative base for this study. Primary interviews across Bangladesh's Sitakunda coastline, India's Alang-Sosiya stretch, and Turkey's Aliaga zone combined with secondary validation from customs records, Department of Environment filings, and EU Ship Recycling Regulation yard lists. Bottom-up vessel decommissioning schedules and top-down steel demand projections were triangulated to establish market sizing.
Sensitivity analysis across steel price volatility scenarios, Hong Kong Convention ratification timelines, and EU regulatory enforcement intensity shaped the analytical framework. Segmentation dimensions modeled include material type, service intensity, equipment mechanization level, and certification tier across the projection horizon. CAGRs were derived from regression analysis against historical demolition contract flows and re-rolling mill capacity expansion. Forecast inputs incorporated vessel age profiles from Lloyd's Register data and infrastructure construction pipelines in Dhaka, Mumbai, and Karachi.
Forecasts assume regulatory continuity in Bangladesh's Department of Environment, India's Ministry of Shipping, and EU Ship Recycling Regulation enforcement; material policy shifts would require re-modeling. Specific risks include sudden Hong Kong Convention ratification delays, ferrous scrap price collapse below break-even recovery economics, and coastal safety enforcement actions disrupting operational continuity. Recalibration cycles align with material shifts in vessel decommissioning schedules and South Asian construction steel demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Middle East Offshore Support Vessels Market