
 Ship Wind Indicator Market | 2026-2036
Ship Wind Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Wind Indicator Market Insights
The capability gap between in-house sensor manufacturing and outsourced assembly is rotating competitive advantage toward vertically integrated suppliers. Gill Instruments leverages its UK-based R&D facilities to sustain proprietary ultrasonic technology development. Garmin anchors its position through integrated navigation ecosystems that bundle wind data with GPS and radar outputs. B&G competes in the high-performance racing segment where brand heritage commands premium positioning among competitive sailing programs.
A ship wind indicator measures real-time wind speed and direction through mechanical vane rotation, ultrasonic pulse timing, or pressure differential sensing, typically operating across ranges from 0 to 100 knots with accuracy thresholds of ±0.5 knots for electronic units. These instruments feed navigation systems, automated sail trim controls, and bridge decision-support tools that optimize vessel routing and fuel efficiency. Anemometers and digital indicators capture the dominant revenue share as commercial fleets replace legacy mechanical systems with sensor packages that integrate directly with vessel performance management software. Wireless deployment architectures represent the fastest-expanding configuration, eliminating cable runs through mast structures and reducing installation labor for retrofit projects across aging commercial fleets.
The International Maritime Organization enforces emissions monitoring protocols that require validated wind data for vessel efficiency calculations, while ISO 19030 standards govern hull and propeller performance measurement where wind indicators serve as critical input sensors. The US Coast Guard and European Maritime Safety Agency both mandate operational wind monitoring for certain vessel classes, creating compliance-driven replacement cycles. Stakeholders must evaluate sensor interoperability standards before committing to platform architectures, as fleet-wide data integration requirements are tightening across classification society certification processes.
Market Dynamics
Electronic sensing architectures are compressing mechanical wind indicator margins as commercial fleets mandate ISO 19030-compliant sensor packages for emissions verification. This technology rotation is forcing incumbent suppliers to reconfigure R&D priorities and assembly footprints.
Growth Catalysts
- IMO emissions protocols:The International Maritime Organization mandates validated wind data inputs for vessel efficiency calculations, compelling fleet operators to upgrade sensor suites across existing tonnage.
- Ultrasonic anemometry:Pulse-timing sensors eliminate moving parts and reduce maintenance intervals, attracting container line procurement teams managing thousand-vessel portfolios.
- Shipbuilding clusters in South Korea:Hyundai Heavy Industries and Samsung Heavy Industries integrate wind indicators into newbuild bridge systems, creating specification pull through the supply chain.
Market Restraints
- Marine-grade semiconductor supply:ASIC fabrication for ultrasonic transducers concentrates at TSMC and Samsung Foundry facilities, exposing lead times to geopolitical friction.
- Mechanical system installed base:Decades of vane-style anemometers on aging bulk carriers create replacement inertia where captains distrust electronic alternatives.
- Classification society recertification:Lloyd's Register and DNV require extensive sea trials for new sensor installations, extending sales cycles by six to eighteen months.
Strategic Opportunities
- India coastal fleet retrofit:The country's Sagarmala port modernization program creates demand for wireless wind indicators on domestic cargo vessels operating without integrated bridge systems.
- Autonomous vessel sensor fusion:Wind data integration with LiDAR and radar arrays enables collision-avoidance algorithms for unmanned surface vessels under development in Norway.
- EU Green Deal vessel performance monitoring:The European Maritime Safety Agency is tightening verified emissions reporting requirements, expanding the addressable sensor base for EU-flagged fleets.
Industry Challenges
- Embedded software certification:IEC 61162 compliance for NMEA 2000 data protocols demands specialized marine electronics engineers, a talent pool concentrated in Hamburg and Oslo.
- Mast retrofit integration:Cable routing through existing aluminum spars on sailing yachts requires rigger coordination and hull penetration work, complicating aftermarket installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Wind Indicator Market |
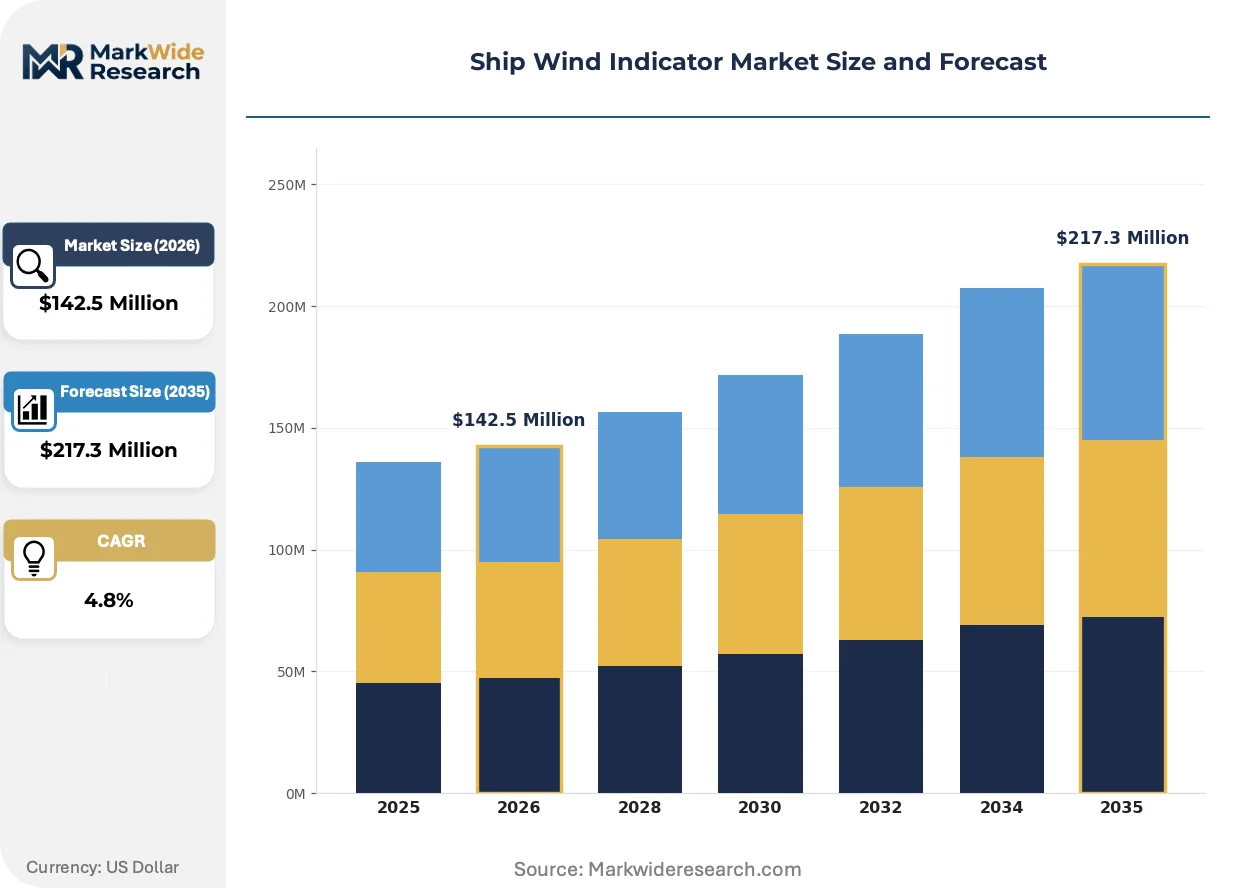
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anemometers, Wind Vanes, Weather Stations, Digital Indicators Technology: Mechanical, Electronic, Hybrid, Wireless End User: Commercial Shipping, Recreational Vessels, Naval, Research Institutions Deployment: Onboard Systems, Remote Monitoring, Integrated Solutions, Standalone Units |
| Companies Covered | Ronstan International, Davis Instruments, Gill Instruments, Osculati, WINDEX, Allen Brothers, B&G, Marinetech, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Wind Indicator Market Trends and Innovations
Sensor fusion architectures are redefining how wind data traverses vessel networks, with implications for hardware form factors and supplier competitive moats. Three developments warrant particular attention.
Ultrasonic wind sensing is bifurcating the product landscape. These solid-state units measure time-of-flight differentials across multiple axes to calculate vector wind data without mechanical wear. Container lines operating trans-Pacific routes are specifying them exclusively for newbuilds. The technology is bifurcating supplier tiers into those with captive ultrasonic IP and those dependent on licensed chipsets.
EU MRV and IMO DCS reporting requirements are hardening data integrity standards for voyage performance documentation. Fleet operators must now maintain calibrated wind sensor records spanning five-year audit windows. Container shipping segments face the steepest compliance burdens, with operators in Rotterdam and Singapore establishing dedicated sensor calibration contracts.
Aftermarket procurement is consolidating through fleet management platforms rather than individual vessel chandlery. Maersk and MSC now specify wind indicators through centralized technical procurement functions, bypassing traditional marine distributor networks. This channel compression is most advanced in Northern Europe, where integrated fleet software mandates direct supplier relationships.
Ship Wind Indicator Market Segmentation
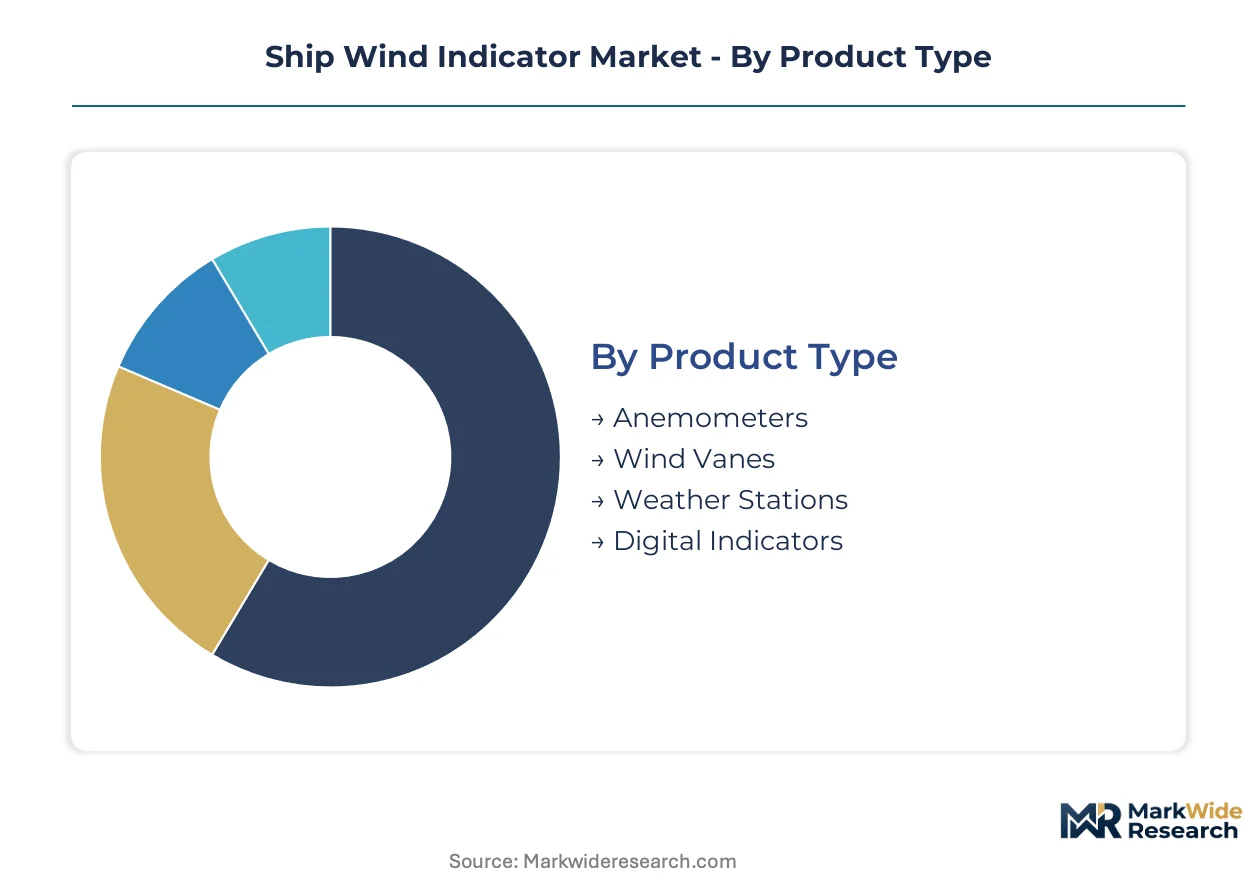
Ship wind indicator procurement patterns diverge sharply across vessel classes and regulatory jurisdictions. Segment boundaries reflect IMO compliance tiers, bridge integration architectures, and the technical maturity of sensing modalities.
Product Type:
ISO 19030 certification requirements favor sensor packages with validated calibration chains over discrete mechanical components.
- Anemometers:Cup-and-vane or ultrasonic configurations measure scalar wind speed with ±0.5 knot precision for emissions verification. Container fleets operating under EU MRV protocols in Rotterdam and Singapore specify these as mandatory bridge equipment.
- Wind Vanes:Directional sensors track apparent wind angle through mechanical rotation or solid-state magnetometry. Recreational yards in the Solent and Chesapeake Bay specify compact vane units for retrofit on legacy sailing yachts where mast cable routing is constrained.
- Weather Stations:Multi-parameter units combining barometric pressure, temperature, and humidity with wind data. Research vessels operating under CSIRO and IFREMER programs deploy these for oceanographic data collection.
- Digital Indicators:NMEA 2000-compliant displays presenting processed wind vectors to bridge crews. Hyundai Heavy Industries integrates these into newbuild integrated bridge systems at South Korean yards.
Established volume favors Anemometers; emerging adoption favors Digital Indicators.
Technology:
Cost tiers separate maintenance-intensive mechanical systems from capital-intensive electronic architectures with embedded software certification burdens.
- Mechanical:Rotating cup and vane assemblies with bearing wear requiring annual replacement. Aging bulk carriers flagged in Panama and Liberia retain these for cost containment despite IMO pressure for sensor upgrades.
- Electronic:Ultrasonic time-of-flight arrays eliminating moving parts entirely. Maersk's trans-Pacific container fleet specifies these exclusively for newbuilds to satisfy five-year calibration audit windows.
- Hybrid:Mechanical backup with electronic primary sensing for redundancy-critical naval applications. Royal Norwegian Navy frigates deploy these for Arctic operations where sensor failure carries operational risk.
- Wireless:Bluetooth Low Energy or proprietary RF links eliminating mast cable runs. India's Sagarmala coastal fleet retrofit program favors these for vessels lacking integrated bridge wiring infrastructure.
Replacement cycles favor Electronic; retrofit feasibility favors Wireless.
End User:
Customer type determines specification authority, with fleet operators exercising centralized procurement distinct from individual vessel owners.
- Commercial Shipping:Container lines, bulk operators, and tanker fleets subject to IMO DCS and EU MRV reporting. MSC and CMA CGM centralize wind indicator procurement through technical departments in Geneva and Marseille.
- Recreational Vessels:Sailing yachts and motor cruisers where brand heritage influences purchasing. High-performance racing programs in Cowes and Newport specify B&G instrumentation for sail trim optimization.
- Naval:Military vessels requiring shock-hardened and EMI-shielded sensor packages. Damen Shipyards integrates custom wind indicators into NATO frigate programs at Dutch and Romanian facilities.
- Research Institutions:Oceanographic and atmospheric monitoring vessels with data logging requirements. Scripps Institution of Oceanography operates dedicated calibration protocols for Pacific research fleet sensors.
Compliance spending concentrates in Commercial Shipping; premium positioning persists in Recreational Vessels.
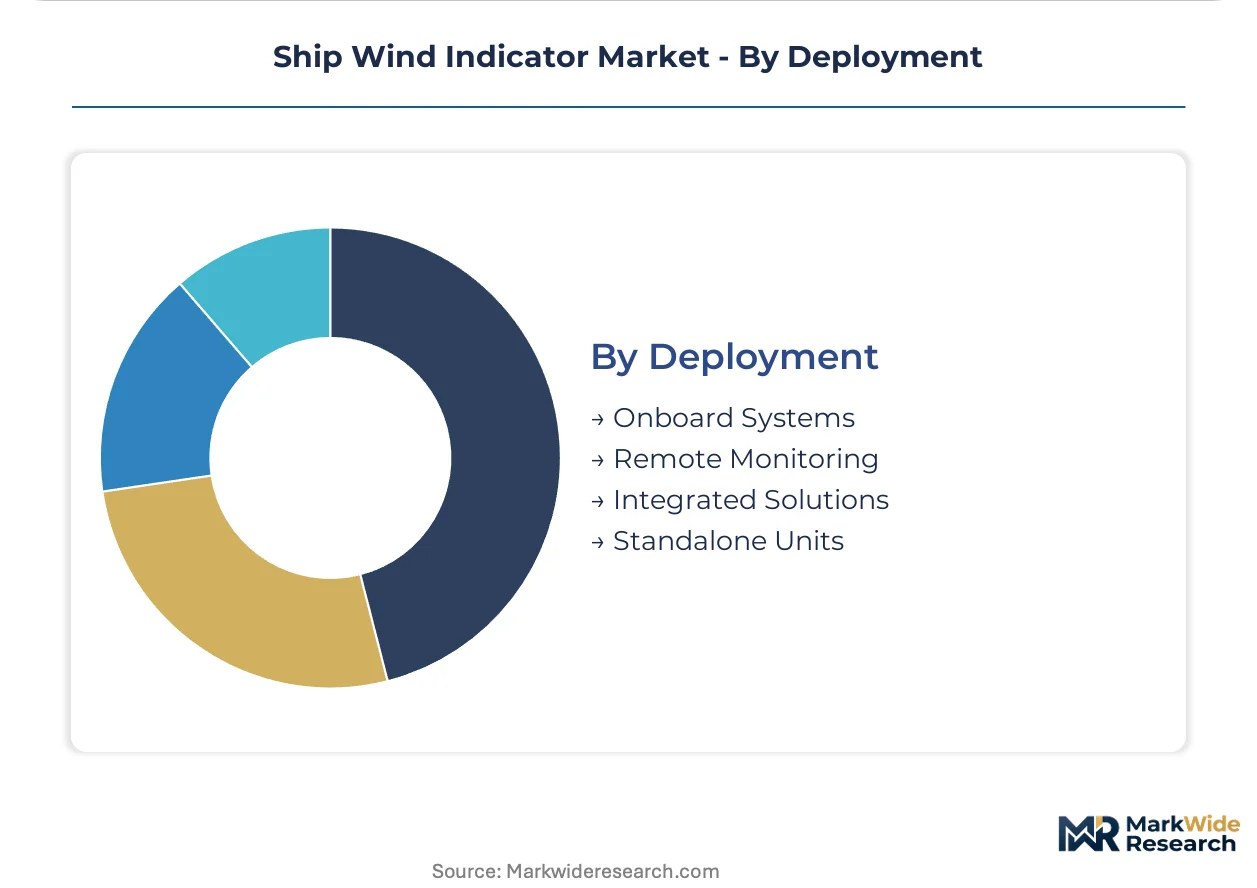
Deployment:
Supply concentration among integrated bridge system vendors shapes channel access for standalone versus embedded configurations.
- Onboard Systems:Hardwired sensors feeding vessel performance management software. Wärtsilä and Kongsberg package these within bridge system contracts for newbuilds at Chinese and South Korean yards.
- Remote Monitoring:Satellite-linked wind data transmission to shore-based fleet operations centers. V.Group and Wilhelmsen Ship Management deploy these for technical supervision of dispersed tonnage.
- Integrated Solutions:Wind sensors fused with radar, AIS, and autopilot arrays. Autonomous vessel developers in Norway's Trondheim cluster require these for collision-avoidance algorithm development.
- Standalone Units:Battery-powered indicators for small craft without vessel-wide electrical systems. Indonesian inter-island ferries under Pelni's domestic fleet specification use these for basic route safety.
Shipyard integration favors Integrated Solutions; aftermarket flexibility favors Standalone Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container lines in Singapore and South Korea absorb premium pricing for ISO 19030-compliant sensor packages, while operators in Panama and Liberia flag-state registries prioritize cost containment on aging mechanical retrofits.
Germany
Hamburg and Bremen harbor shipping consortia drive demand for integrated bridge systems with validated wind data chains. Lloyd's Register and DNV classification requirements enforce five-year calibration audit windows for EU MRV compliance. The country's northern port cluster concentrates specification authority among fleet technical departments.
China
Shanghai and Dalian shipyards integrate wind indicators into newbuild contracts for COSCO and China Merchants Energy Shipping fleets. The Ministry of Ecology and Environment enforces domestic emissions monitoring protocols aligned with IMO DCS standards. Yangtze River Delta manufacturing bases supply ultrasonic transducer components to regional integrators.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries specify electronic wind sensors for container vessels bound for trans-Pacific routes. The Korea Register of Shipping mandates operational wind monitoring for certain vessel classes under national safety codes. Busan-Ulsan shipbuilding corridors concentrate procurement decisions at the yard level.
United States
Houston and New Orleans petrochemical tanker operators face US Coast Guard mandates for operational wind monitoring on specified tonnage. Environmental Protection Agency enforcement of vessel efficiency documentation drives sensor upgrade cycles. Gulf Coast maritime clusters balance compliance spending against mechanical system replacement inertia.
India
Mumbai and Visakhapatnam coastal cargo fleets require wireless wind indicators under the Sagarmala port modernization program. The Directorate General of Shipping implements safety equipment standards for domestic vessels. Gujarat shipbreaking yards generate aftermarket demand for standalone units on refurbished tonnage.
Ship Wind Indicator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated R&D control separating ultrasonic technology developers from licensed chipset assemblers. The market structure bifurcates between navigation ecosystem bundlers and standalone sensor fabricators. Three archetypes dominate: vertically integrated ultrasonic specialists, integrated navigation platform vendors, and mechanical heritage suppliers serving cost-sensitive retrofit segments. Competitive moves concentrate on strategic partnerships with classification societies for calibration protocol validation and geographic expansion through fleet management platform integrations.
Among UK-based instrument developers, Gill Instruments occupies a position exemplifying captive ultrasonic intellectual property development. Garmin anchors the integrated navigation tier, representing ecosystem bundling strategies that fuse wind data with GPS and radar outputs. B&G sits within the high-performance racing specialization, exemplifying brand heritage premium positioning among competitive sailing programs.
| Leading Market Players |
|---|
| Ronstan International |
| Davis Instruments |
| Gill Instruments |
| Osculati |
| WINDEX |
| Allen Brothers |
| B&G |
| Marinetech |
| Garmin |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay calibration contracts spanning five-year audit windows lock in both supply access and price visibility for ISO 19030-compliant sensor packages. Container lines operating under EU MRV protocols in Rotterdam and Singapore use these structures to secure validated wind data chains while insulating procurement from spot-market volatility in marine-grade semiconductor inputs.
Pricing Analysis
After-sales service revenue from recalibration and transducer replacement drives lifetime value in electronic wind indicator deployments. Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic units with captive IP from licensed-chipset assemblers and legacy mechanical suppliers. Cost compression in economy tiers is intensifying because aging bulk carriers flagged in Panama and Liberia defer electronic upgrades. Commercial shipping fleets exhibit lowest price sensitivity due to compliance mandates, while Indonesian coastal ferry operators demonstrate highest sensitivity given standalone unit procurement without integrated bridge budgets.
Supply Chain Analysis
China and South Korea anchor ultrasonic transducer fabrication and integrated bridge system assembly respectively. Taiwan draws from specialized ASIC foundries for pulse-timing chipsets, while Germany sources precision-machined mechanical vane components. Single-source vulnerability concentrates at TSMC and Samsung Foundry facilities for marine-grade semiconductor wafers. Distribution runs through fleet management platforms rather than traditional marine chandlery networks, with Maersk and MSC centralizing technical procurement functions in Geneva and Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
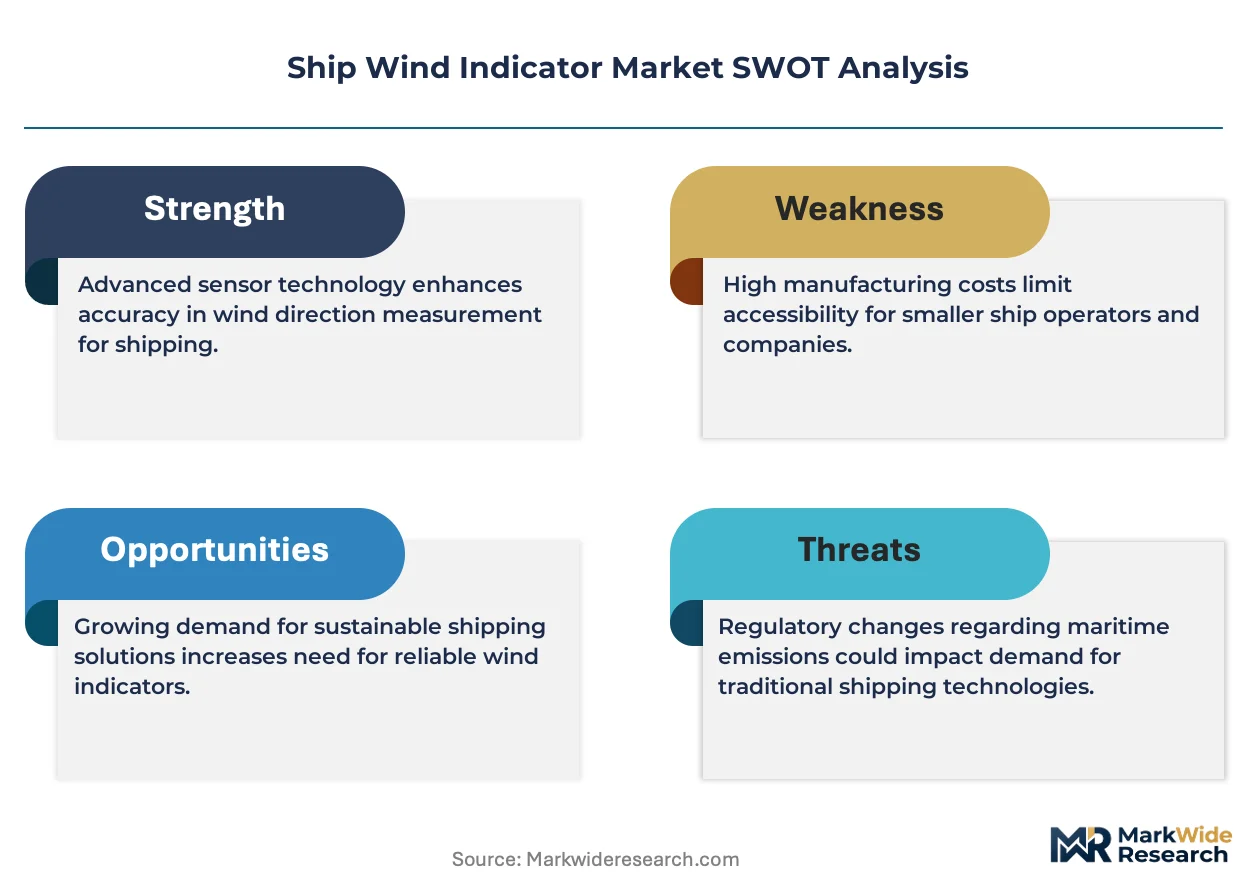
Incumbents face substitution defense against solid-state ultrasonic architectures displacing mechanical vane systems across IMO-regulated fleets. Electronic sensing modalities threaten to commoditize suppliers lacking captive IP or integrated navigation ecosystem bundling.
For Market Incumbents: Shield proprietary ultrasonic technology positions through backward integration into transducer R&D and captive calibration protocol validation with Lloyd's Register and DNV. Secure classification society pre-approval for sensor packages to compress six-to-eighteen-month sea trial cycles that delay revenue recognition. Counter licensed-chipset assemblers by embedding wind data deeper into vessel performance management software stacks. For New Entrants and Emerging Players: Differentiate on wireless deployment architectures for India's Sagarmala coastal fleet retrofit program, where vessels lack integrated bridge wiring infrastructure. Target aftermarket standalone units for Indonesian inter-island ferries and Gujarat shipbreaking yard refurbishments. Pursue direct fleet management platform integrations with V.Group and Wilhelmsen Ship Management to bypass compressed distributor channels. For Investors and Strategic Acquirers: The market sits at a technology rotation phase that favors vertically integrated ultrasonic specialists with captive IP over mechanical heritage suppliers facing margin erosion. Long-term viability hinges on sensor fusion capabilities for autonomous vessel collision-avoidance algorithms under development in Norway's Trondheim cluster. Watch for inflection signals in EU Green Deal vessel performance monitoring enforcement tightening verified emissions reporting requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Pre-Approval | Compresses DNV and Lloyd's Register sea trial cycles from eighteen months to six. |
| Wireless Architecture Development | Eliminates mast cable runs for India's Sagarmala coastal fleet retrofit demand. |
| Sensor Fusion Integration | Enables collision-avoidance algorithms for Norway's autonomous vessel developers. |
| Fleet Management Platform Partnership | Bypasses traditional marine distributor compression with Maersk and MSC procurement. |
| Calibration Service Contracting | Captures five-year audit window revenue under EU MRV and IMO DCS protocols. |
Research Methodology
A standing panel of fleet technical managers, marine electronics procurement officers, classification society surveyors, and shipyard integration engineers provided ongoing calibration against market developments. Primary interviews combined with secondary validation from Lloyd's Register certification databases, DNV sensor approval registries, and IMO emissions protocol documentation. Customs records from Hamburg and Singapore port authorities supplemented trade flow analysis. Bottom-up vessel-by-vessel sensor deployment estimates triangulated against top-down fleet operator procurement disclosures.
Consistency checks validated volume and value outputs against external benchmarks from integrated bridge system vendors and ultrasonic component manufacturers. The analytical framework modeled product type, technology modality, end-user segment, and deployment architecture across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and regulatory compliance phase-in schedules. Forecast inputs incorporated IMO DCS enforcement timelines and EU MRV audit window requirements without specifying implementation years.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of emissions verification protocols would require recalibration. Forecasts reflect assumptions regarding classification society certification continuity and marine-grade semiconductor supply stability. Geopolitical friction at TSMC and Samsung Foundry facilities, or relaxation of EU Green Deal vessel performance monitoring, would revise projected sensor upgrade cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Wire Mooring Ropes Market