
 Global Maritime Safety Market | 2026-2036
Global Maritime Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Safety Market Foresight
South Korea's shipyard corridor is fragmenting as multiple domestic and foreign suppliers establish competing safety system integration facilities. BAE Systems leverages its naval electronics heritage to dominate military vessel safety contracts. Honeywell International Inc. anchors commercial shipping through its integrated bridge and automation platforms. Thales Group competes in satellite-linked vessel tracking with dual-use technology spanning defense and civilian applications.
Maritime safety encompasses engineered systems and protocols designed to prevent loss of life, vessel damage, and environmental harm across marine operations, incorporating redundant communication links, thermal-resistant materials rated to 1,100°C in fire suppression housings, and real-time kinematic positioning accurate to centimeter-scale. Navigational Systems command the largest revenue pool as SOLAS-mandated bridge upgrades cycle across aging fleets. Automatic Identification System technology represents the fastest-expanding segment as port authorities mandate transponder density for congested waterway management. Communication Devices retain mature margins in coastal fisheries and inland waterway fleets where regulatory enforcement lags open-ocean standards.
The International Maritime Organization's SOLAS convention shapes equipment certification timelines, while the EU's MRV Regulation and IMO's DCS framework force emissions-linked safety monitoring integration. The US Coast Guard's NVIC standards govern port state control inspections, creating compliance-driven replacement demand for non-conforming legacy systems. Stakeholders must monitor convergence between cybersecurity mandates and physical safety protocols as autonomous vessel trials expand.
Market Dynamics
The International Maritime Organization's SOLAS convention revision is compressing equipment refresh cycles across commercial fleets, forcing bridge system replacements and integrated safety suite procurement decisions.
Growth Catalysts
- Offshore platform safety mandates:North Sea operators are expanding procurement of integrated safety suites to meet harsh-environment operational requirements. Norway's maritime cluster drives premium system adoption for extreme-condition vessel traffic.
- IMO DCS framework:The Data Collection System for emissions monitoring is accelerating sensor integration into safety platforms. Shipowners must install emissions-linked safety monitoring to maintain compliance certification.
- LiDAR-based collision avoidance:Port authorities in congested waterways are mandating enhanced transponder density and centimeter-scale positioning systems for automated vessel traffic management.
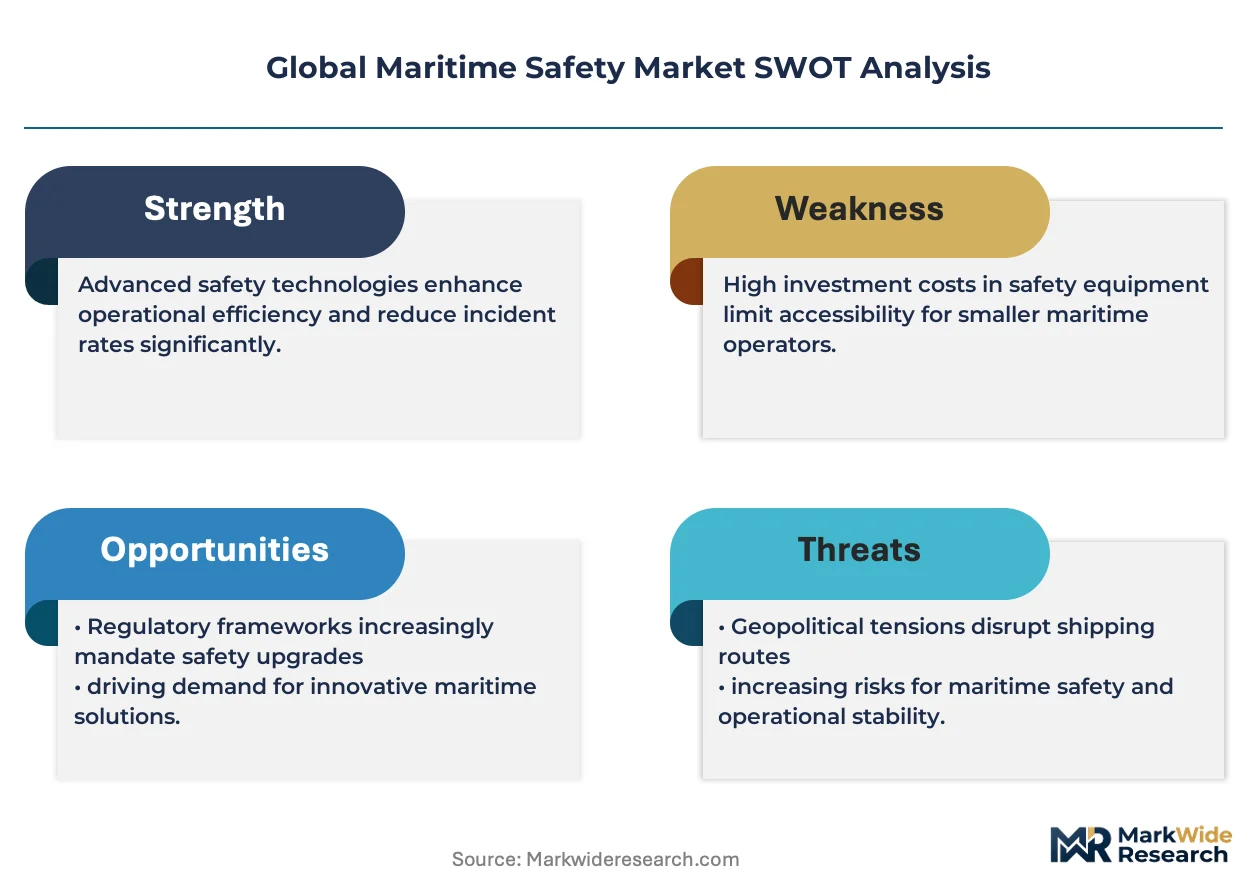
Market Restraints
- Copper and rare-earth magnet volatility:Thermal-resistant fire suppression housings and motor assemblies face input cost pressure from concentrated Chinese processing capacity.
- South Korean supply concentration:The shipyard corridor's fragmentation into competing integration facilities creates interoperability risks and certification timeline uncertainty for vessel operators.
- Cyber-physical protocol gaps:Autonomous vessel trials expose unresolved standards for converging cybersecurity mandates with physical safety systems, delaying insurer coverage decisions.
Strategic Opportunities
- Indian coastal fisheries digitization:Regulatory enforcement gaps in inland waterway fleets create first-mover potential for affordable AIS transponder deployment.
- Satellite-linked tracking convergence:Dual-use defense-civilian positioning technology is opening commercial maritime applications previously restricted to naval contracts.
- EU MRV Regulation integration:The Monitoring, Reporting and Verification framework creates bundled procurement opportunities combining emissions and safety monitoring into single-platform contracts.
Industry Challenges
- Marine cyber-physical engineering scarcity:Vessel operators struggle to recruit specialists capable of integrating legacy bridge systems with autonomous navigation protocols.
- SOLAS certification timeline compression:Equipment manufacturers face bottlenecks in type-approval processes as multiple flag states implement concurrent deadline shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Safety Market |
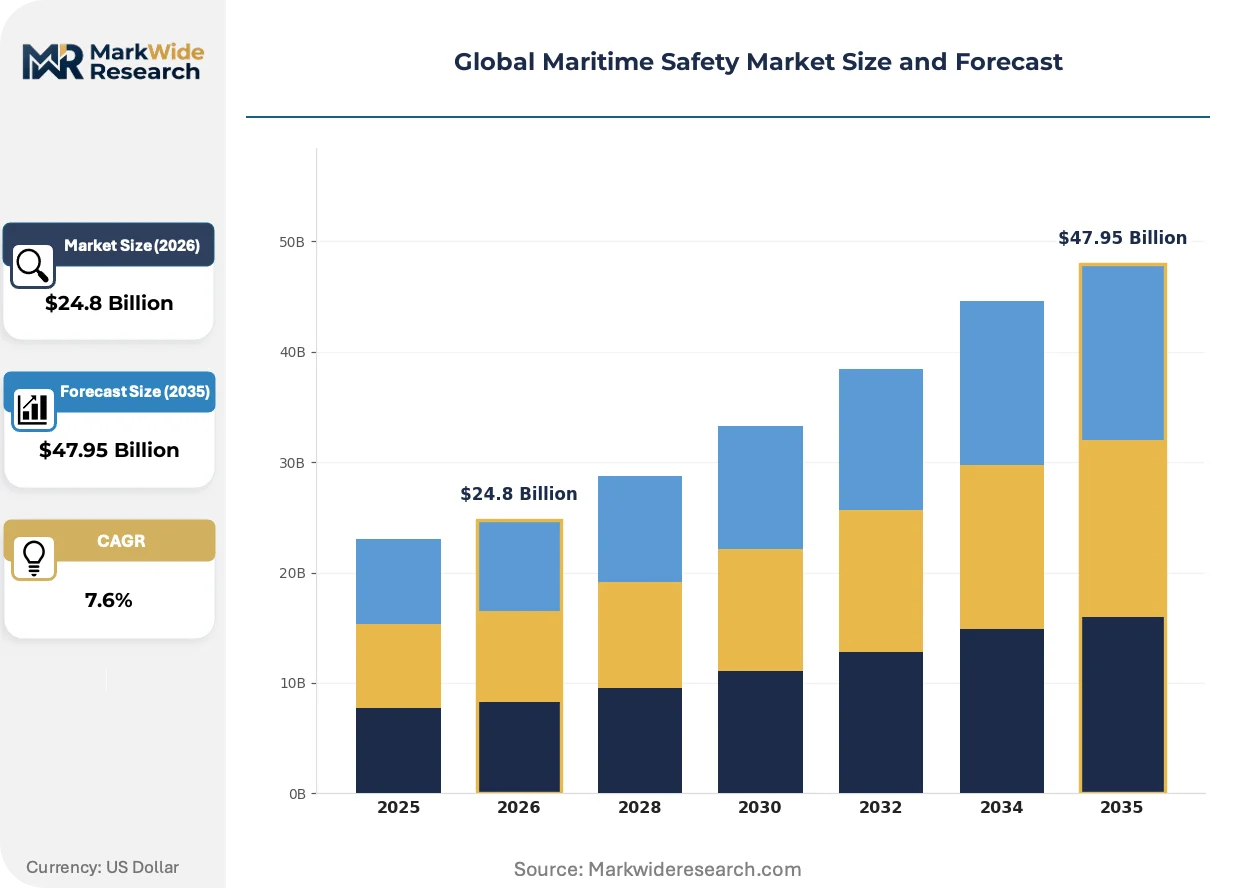
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life-saving Appliances, Fire Protection Equipment, Navigational Systems, Communication Devices Technology: Automatic Identification System, Radar Systems, Sonar Technology, Electronic Chart Display & Information System Application: Crew Safety, Vessel Tracking, Accident Prevention, Emergency Response Coordination End User: Ship Operators, Port Authorities, Marine Contractors, Offshore Platforms |
| Companies Covered | BAE Systems, Honeywell International Inc., Elbit Systems Ltd., Thales Group, OSI Maritime Systems, Saab Group, L3Harris Technologies, Inc., Kongsberg Gruppen, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Safety Market Shifts & Advancements
Real-time kinematic positioning and thermal-resistant materials are converging with emissions monitoring to reshape vessel safety architecture. Three developments dominate competitive positioning.
Digital twin simulation platforms are digitizing vessel safety system validation before sea trials. Classification societies in Germany and Norway are mandating virtual collision scenario testing for newbuild approvals. This compresses physical prototype cycles and reduces certification risk for integrated bridge manufacturers.
REACH chemical restrictions in Europe are forcing reformulation of fire suppression foams and thermal barrier materials. Manufacturers must substitute legacy halogenated compounds with mineral-based alternatives rated to 1,100°C. Norwegian offshore operators face the steepest compliance curve due to North Sea platform density requirements.
Charterers are unbundling safety system maintenance from vessel management contracts. Third-party technical managers in Singapore and Rotterdam are capturing specialized servicing revenue previously retained by shipowners. This shifts capital allocation toward predictive maintenance platforms and away from periodic overhaul schedules.
Global Maritime Safety Market Segmentation
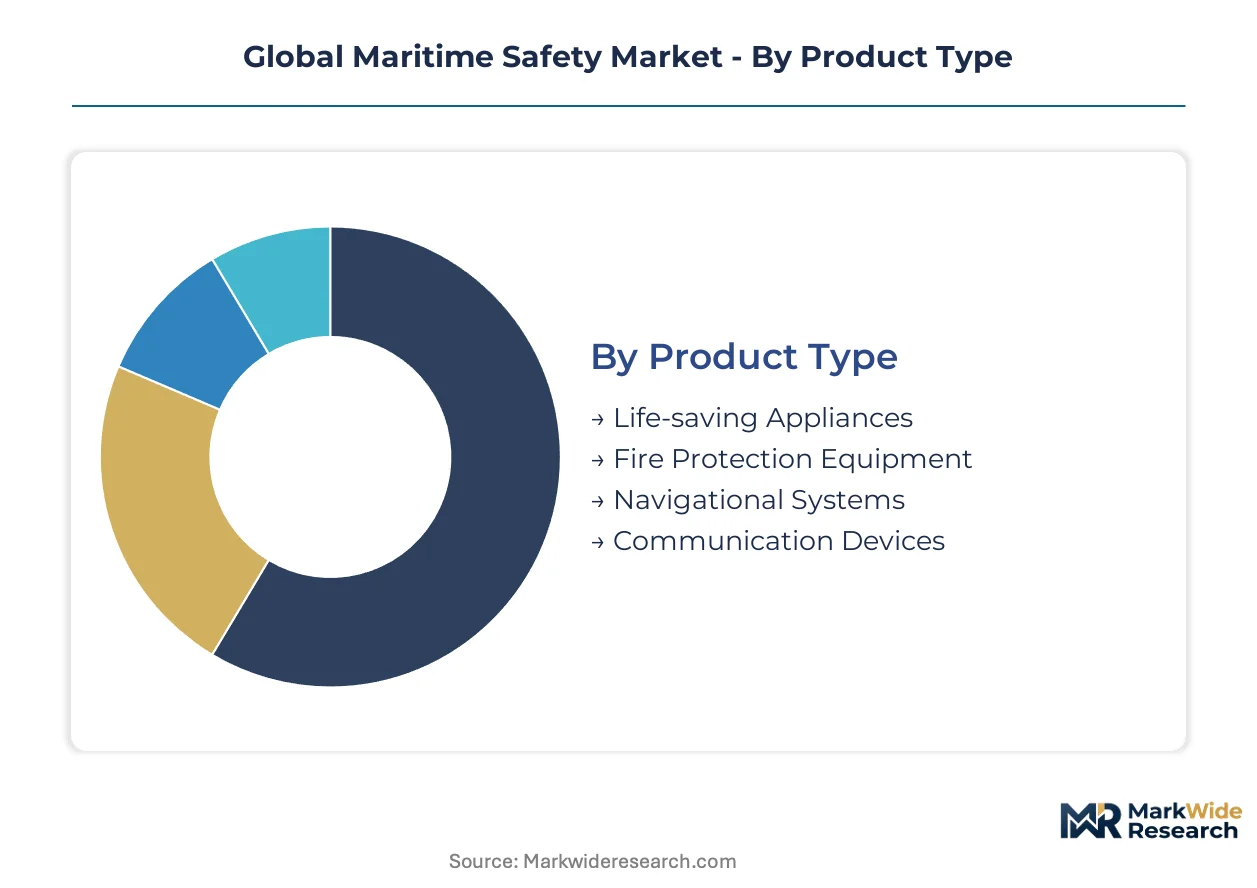
Maritime safety procurement splits across equipment categories, digital infrastructure layers, operational use cases, and stakeholder types. Each dimension carries distinct certification requirements and replacement cycles that reshape vendor positioning.
Product Type:
Use cases span from personal survival equipment through fleet-wide navigation suites to integrated platform protection systems.
- Navigational Systems:Bridge-integrated gyrocompasses, ECDIS workstations, and dynamic positioning units process real-time kinematic corrections for centimeter-scale accuracy. SOLAS-mandated upgrades across aging commercial fleets concentrate procurement in Germany's container-ship operators and Norway's offshore supply vessel segment.
- Fire Protection Equipment:Thermal-resistant housings rated to 1,100°C protect suppression system electronics in engine-room and cargo-hold deployments. REACH chemical restrictions in Europe are forcing reformulation of legacy foams, with Norwegian offshore platforms facing the steepest compliance curve due to North Sea density requirements.
- Life-saving Appliances:Inflatable liferafts, immersion suits, and rescue boats with hydrostatic release mechanisms serve coastal fisheries and deep-sea fleets. Regulatory enforcement gaps in India's inland waterways create price-sensitive demand distinct from open-ocean certification tiers.
- Communication Devices:GMDSS-compliant satellite terminals and VHF radios retain mature margins where flag-state enforcement varies. Coastal fisheries in Southeast Asia and inland European waterways show slower refresh cycles than SOLAS-regulated deep-sea routes.
Established volume favors Navigational Systems; emerging adoption favors Fire Protection Equipment.
Technology:
Sensor and data-layer investments concentrate where port congestion and autonomous navigation trials intersect.
- Automatic Identification System:VHF-transponder networks broadcast vessel identity, position, and cargo data to shore stations and neighboring ships. Port authorities in Singapore and Rotterdam mandate enhanced transponder density for automated traffic management in confined waterways.
- Radar Systems:X-band and S-band arrays with ARPA tracking capabilities detect collision risks in reduced visibility. Military heritage from naval electronics suppliers is migrating into commercial ice-class vessels operating in Baltic and Arctic routes.
- Sonar Technology:Multibeam bathymetric and forward-looking obstacle detection systems support underkeel clearance monitoring. Offshore platform operators in the North Sea deploy these for subsea infrastructure proximity alerts.
- Electronic Chart Display & Information System:ECDIS workstations replace paper charts with real-time ENC updates and route optimization. Flag-state type-approval bottlenecks compress implementation timelines for shipowners facing concurrent SOLAS deadlines.
Sensor density requirements in congested ports favor AIS deployment; ice-route expansion favors Radar Systems refresh.
Application:
Operational priorities shift from reactive emergency response toward predictive risk mitigation.
- Vessel Tracking:Satellite-linked position reporting and geofencing alerts monitor fleet movements across exclusive economic zones. EU MRV Regulation integration bundles emissions and safety monitoring into single-platform contracts for European-registered tonnage.
- Accident Prevention:LiDAR-based collision avoidance and proximity warning systems reduce allisions in restricted channels. Classification societies in Germany and Norway mandate virtual scenario testing before newbuild approvals.
- Crew Safety:Man-overboard detection, lone-worker monitoring, and enclosed-space gas detection protect personnel in high-risk operations. Offshore platforms in harsh-environment zones drive premium system specifications.
- Emergency Response Coordination:Distress relay networks and SAR resource dispatch systems link vessel casualties with rescue coordination centers. Third-party technical managers in Singapore and Rotterdam are capturing specialized servicing revenue previously retained by shipowners.
Regulatory compliance investment favors Vessel Tracking; autonomous trial expansion favors Accident Prevention system adoption.
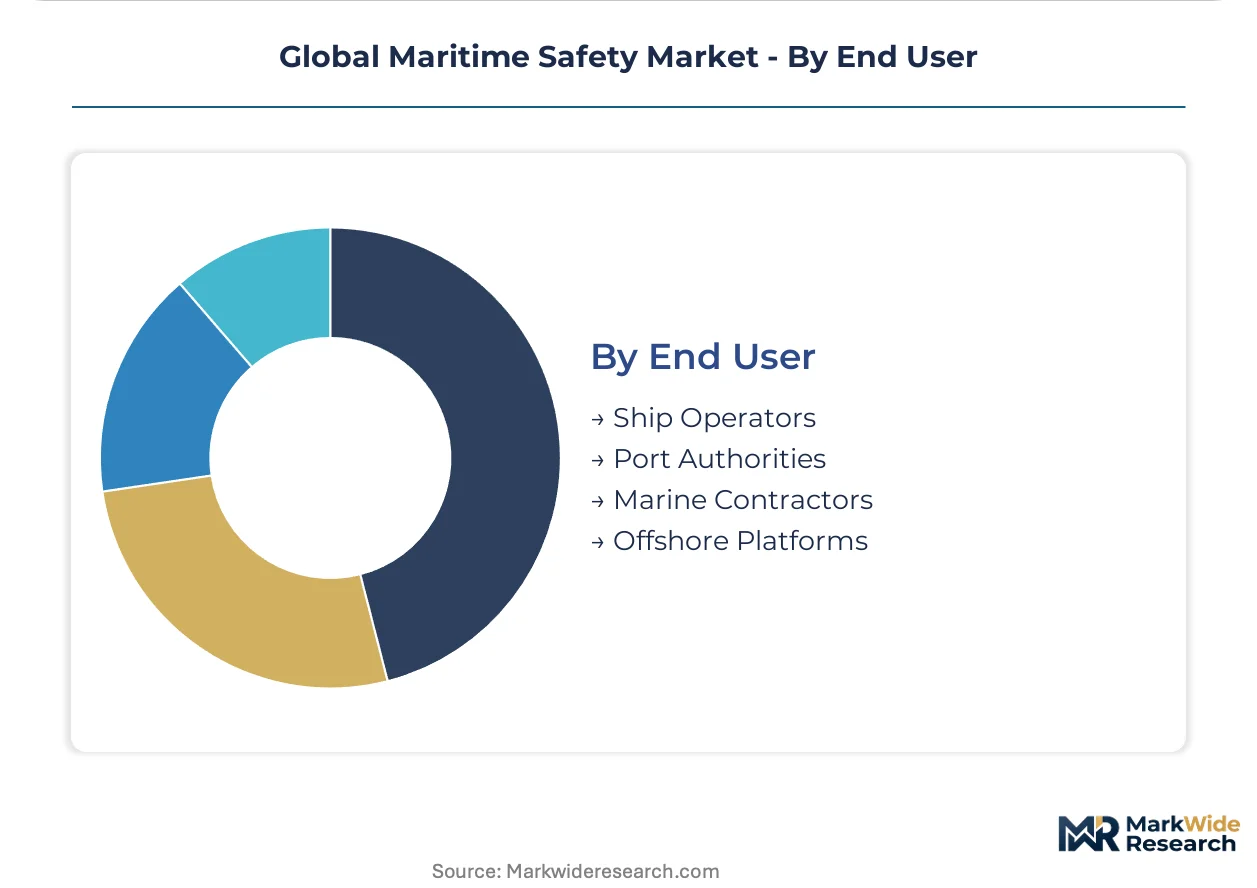
End User:
Procurement authority fragments between asset owners, infrastructure operators, and contracted service providers.
- Ship Operators:Container lines, tanker fleets, and bulk carriers face compressed SOLAS refresh cycles across bridge and safety suite replacements. South Korean shipyard corridor fragmentation creates interoperability risks for integrated system procurement.
- Offshore Platforms:Fixed and floating production facilities require explosion-proof safety systems rated for Zone 1 hazardous areas. North Sea operators expand integrated safety suite procurement to meet harsh-environment operational requirements.
- Port Authorities:Vessel traffic services and pilotage organizations mandate transponder density and shore-based monitoring infrastructure. Congested waterway management in the Malacca Strait and English Channel drives shore-side sensor network investment.
- Marine Contractors:Dredging, cable-laying, and offshore construction fleets deploy dynamic positioning and dive-support safety systems. Project-specific chartering patterns create episodic procurement spikes tied to contract awards.
Fleet-wide mandates favor Ship Operators; infrastructure-linked investment favors Port Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's SOLAS convention anchors regulatory harmonization across maritime safety procurement, though implementation intensity varies sharply by coastal economy maturity and enforcement capacity.
Norway
North Sea offshore platform operators drive integrated safety suite procurement for harsh-environment vessel traffic. The Norwegian Maritime Authority enforces some of Europe's strictest bridge equipment certification timelines. Bergen and Stavanger host the continent's densest cluster of dynamic positioning specialists and subsea safety system integrators.
South Korea
Shipyard corridor fragmentation into competing integration facilities creates interoperability risks for vessel operators. The Ministry of Oceans and Fisheries accelerates domestic supplier qualification under the Smart Ship initiative. Ulsan and Geoje concentrate newbuild safety system commissioning amid Hyundai Heavy and Samsung Heavy contracting cycles.
Germany
Container-ship operators face compressed ECDIS and bridge upgrade cycles under concurrent SOLAS and EU MRV deadlines. The Federal Maritime and Hydrographic Agency mandates type-approval bottlenecks that compress manufacturer delivery schedules. Hamburg anchors Europe's largest fleet management software cluster linking safety monitoring with emissions compliance platforms.
Singapore
Port authorities mandate enhanced AIS transponder density for automated vessel traffic management in the Malacca Strait chokepoint. The Maritime and Port Authority bundles coastal fisheries digitization grants with safety equipment subsidies. Third-party technical managers in Tuas and Jurong capture specialized servicing revenue previously retained by shipowners.
United States
The US Coast Guard's NVIC standards govern port state control inspections, creating compliance-driven replacement demand for non-conforming legacy systems. EPA and OSHA convergence pressures offshore platform operators in the Gulf of Mexico to upgrade fire suppression and crew safety systems. Houston hosts the hemisphere's largest concentration of offshore safety engineering contractors.
Global Maritime Safety Market Competitive Landscape
Defense-electronics heritage and commercial-avionics crossovers split the market between military-anchored system integrators and civilian-focused automation platforms. The vendor base concentrates around three strategic archetypes: naval electronics specialists with dual-use technology pipelines, diversified industrial conglomerates with integrated bridge portfolios, and regional shipyard-captive integrators. Consolidation pressures favor acquisition of autonomous navigation startups by incumbent bridge manufacturers, while certification timeline compression drives strategic partnerships between equipment makers and classification societies.
Within the defense-electronics tier, BAE Systems and Thales Group exemplify naval heritage migration into commercial ice-class and offshore safety contracts. Honeywell International Inc. anchors the commercial-shipping vector through its integrated bridge and automation platforms. Kongsberg Gruppen occupies a position bridging Norwegian offshore platform specialization with dynamic positioning dominance in harsh-environment zones.
| Leading Market Players |
|---|
| BAE Systems |
| Honeywell International Inc. |
| Elbit Systems Ltd. |
| Thales Group |
| OSI Maritime Systems |
| Saab Group |
| L3Harris Technologies, Inc. |
| Kongsberg Gruppen |
| Northrop Grumman |
| Others |
Supply & Pricing Matrix
Shipyard overcapacity in South Korea's Ulsan-Geoje corridor is compressing equipment margins while fragmenting supplier integration capabilities, forcing buyers to absorb interoperability premiums or accept extended certification timelines.
Pricing Analysis
Price spreads between Norwegian North Sea specifications and Southeast Asian coastal fisheries exceed threefold, with harsh-environment certification tiers commanding premiums tied to thermal-resistance ratings and redundant communication links. Three-tier pricing structure across premium, standard, and economy levels separates SOLAS-compliant integrated suites from modular retrofits and basic GMDSS equipment. Cost compression in standard-tier fire suppression housings is intensifying because REACH-mandated halogen-free reformulations require mineral-based alternatives rated to 1,100°C. India's inland waterway operators exhibit highest price sensitivity, while Norway's offshore platforms accept premium positioning for Zone 1 hazardous-area ratings.
Supply Chain Analysis
Copper smelting and rare-earth magnet processing feed from concentrated Chinese capacity, creating input cost volatility for thermal-resistant housings and motor assemblies in fire suppression systems. Manufacturing gravity centers on South Korea, Germany, and Norway, with Bergen-Stavanger clusters specializing in dynamic positioning integration. Single-source vulnerability in LiDAR sensor modules exposes collision-avoidance system deliveries to semiconductor foundry bottlenecks. Distribution runs through shipyard-captive integrators in Ulsan, third-party technical managers in Singapore, and direct OEM procurement for offshore platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across South Korean shipyard integration facilities is creating niche opportunities for specialized safety system validators and certification accelerators as vessel operators seek interoperability guarantees.
For Market Incumbents: Build certification moats through accelerated type-approval partnerships with Norway's Maritime Authority and Germany's Federal Maritime and Hydrographic Agency. Invest in backward integration into thermal-resistant material formulation to offset REACH-driven input cost volatility. Capture servicing revenue from charterers unbundling maintenance contracts by deploying predictive maintenance platforms in Singapore and Rotterdam. For New Entrants and Emerging Players: Build out affordable AIS transponder distribution networks targeting India's coastal fisheries digitization gap, where regulatory enforcement lags create first-mover pricing flexibility. Anchor go-to-market strategy through bundled emissions-safety monitoring platforms aligned with EU MRV Regulation integration timelines. Prioritize satellite-linked tracking convergence applications leveraging dual-use defense-civilian technology pipelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across autonomous navigation protocol development as software-defined safety platforms displace hardware-heavy bridge replacements. Target acquisition candidates with marine cyber-physical engineering capabilities bridging legacy system integration with autonomous trial requirements. Monitor insurer coverage decisions for autonomous vessels as the critical inflection signal for commercial deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Partnership | Virtual collision scenario testing mandates from DNV and Germanischer Lloyd compress newbuild approval cycles. |
| Sensor Integration Platform | LiDAR-AIS fusion for port congestion management addresses Singapore and Rotterdam transponder density requirements. |
| Halogen-Free Material Transition | REACH-compliant thermal barrier reformulation secures Norwegian offshore platform procurement continuity. |
| Predictive Maintenance Rollout | Third-party technical managers in Tuas capture charterer unbundling revenue previously retained by shipowners. |
| Satellite Tracking Convergence | Dual-use defense-civilian positioning technology opens commercial maritime applications from Thales and BAE pipelines. |
Research Methodology
Initial hypotheses were tested against primary input from shipyard procurement directors, offshore platform safety engineers, classification society surveyors, and port authority vessel traffic managers and refined through secondary validation against IMO SOLAS amendment records, EU MRV compliance databases, US Coast Guard NVIC standards, and flag-state type-approval registries. Bottom-up equipment shipment tracking was triangulated with top-down fleet replacement cycle modeling.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, technology layer, operational application, and end-user procurement authority. CAGRs were derived from installed base depreciation curves and regulatory deadline clustering. Forecast inputs incorporated shipyard orderbook pipelines and offshore platform greenfield investment announcements.
Stress conditions across copper and rare-earth magnet price volatility, SOLAS certification timeline compression, and autonomous vessel trial regulatory clarity were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Lloyd's List vessel equipment databases and Clarksons newbuild order tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Ship Anchor Market