
 Global Dry Bulk Shipping Market | 2026-2036
Global Dry Bulk Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Bulk Shipping Market Analysis
The EU Green Deal is hardening emissions benchmarks for maritime transport, compelling fleet operators to reconsider vessel deployment strategies. COSCO Shipping Bulk Co., Ltd. leverages its state-owned scale to secure long-term cargo contracts across Pacific routes. Star Bulk Carriers Corp. anchors its competitiveness through a modern Capesize fleet with lower carbon intensity profiles. Golden Ocean Group Limited specializes in ice-class vessels that extend operating seasons on high-latitude ore corridors.
Dry bulk shipping denotes the maritime transport of unpackaged commodities such as iron ore, coal, grain, and fertilizers in holds without containerization, with Capesize vessels exceeding 100,000 deadweight tons designed specifically for high-volume, low-value cargo on dedicated routes. Capesize tonnage dominates transoceanic iron ore flows from Western Australia to East Asian steel mills, while Panamax and Supramax vessels compete on grain and coal trades where port draft limitations restrict larger hulls. The voyage charter segment sustains spot-market liquidity for mining majors seeking cargo flexibility, whereas time charters occupy the contracting preference of agricultural traders managing seasonal volume uncertainty.
The International Maritime Organization's Energy Efficiency Existing Ship Index shapes retrofit investment timelines across flagged fleets, while the EU Emissions Trading System extends carbon pricing to maritime voyages terminating at European ports. China's Ministry of Transport enforces domestic emission control areas that constrain bunker fuel sulfur content on coastal routes. Stakeholders must monitor how regional carbon border adjustments redirect cargo flows and vessel registration choices before regulatory asymmetries crystallize into permanent competitive disadvantages.
Market Dynamics
The International Maritime Organization's Energy Efficiency Existing Ship Index is forcing fleet-wide retrofits before 2026 compliance deadlines, compressing operating margins for older Capesize tonnage while accelerating demolition cycles across Panamax and Supramax segments.
Growth Catalysts
- Steel mill restocking cycles:Chinese blast furnace operators are rebuilding iron ore inventories after destocking periods, sustaining spot charter demand on Western Australia-East Asia routes.
- EU Emissions Trading System expansion:Maritime carbon pricing on voyages terminating at European ports is redirecting investment toward scrubber-fitted and LNG-ready vessel orders.
- Grain corridor reopenings:Ukrainian Black Sea export volumes through alternative Romanian and Bulgarian ports are creating new Supramax employment patterns.
Market Restraints
- Low-sulfur fuel oil volatility:VLSFO price spreads against high-sulfur alternatives swing unpredictably, eroding scrubber payback calculations for operators.
- Chinese port congestion:Iron ore discharge delays at Ningbo-Zhoushan and Qingdao anchorages absorb vessel supply without generating freight revenue.
- Shipyard capacity concentration:Korean and Chinese yards control over 80% of newbuild slots, extending delivery timelines for specialized ore carriers.
Strategic Opportunities
- Indonesian nickel ore exports:EV battery supply chain demand is creating new Capesize and Newcastlemax employment on Southeast Asian routes previously served by smaller Handymax units.
- Wind-assisted propulsion retrofits:Rotor sail and kite systems are qualifying vessels for preferential EU ETS treatment and green financing terms.
- Digital freight platforms:Blockchain-based voyage charter marketplaces are compressing broker intermediation and accelerating fixture finalization.
Industry Challenges
- Dual-fuel engineering scarcity:Shipyards and engine manufacturers face acute shortages of LNG and methanol system specialists, delaying newbuild deliveries.
- EU Monitoring, Reporting and Verification audit complexity:Documenting voyage-level carbon emissions for ETS compliance requires new data infrastructure that smaller operators struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Bulk Shipping Market |
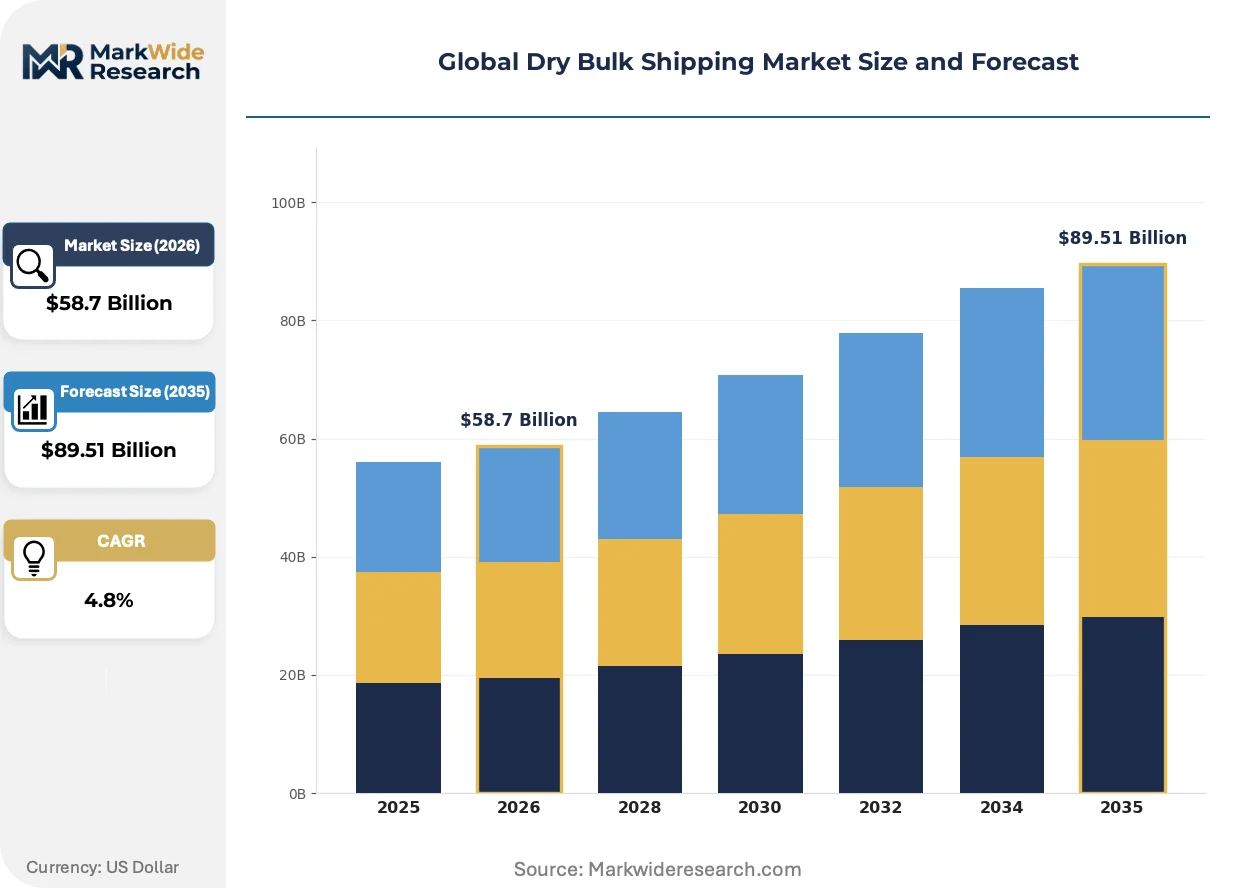
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Capesize, Panamax, Supramax, Handysize Cargo Type: Grain, Coal, Iron Ore, Fertilizers Service Type: Voyage Charter, Time Charter, Bareboat, Contract of Affreightment End User: Mining, Agriculture, Energy, Manufacturing |
| Companies Covered | COSCO Shipping Bulk Co., Ltd., Star Bulk Carriers Corp., Golden Ocean Group Limited, Pacific Basin Shipping Limited, Oldendorff Carriers, Nippon Yusen Kabushiki Kaisha (NYK Line), Diana Shipping Inc., Genco Shipping & Trading Limited, Ultrabulk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Bulk Shipping Market Emerging Trajectories
Carbon intensity benchmarking is overtaking speed optimization as the dominant operational discipline, with charterers now screening vessel efficiency profiles before fixing cargo. Three developments are compressing competitive timelines.
Rotor sail wind propulsion is overtaking conventional engine-downrating as the primary emissions reduction pathway for Capesize bulkers. Mining majors Rio Tinto and BHP are inserting wind-assist clauses into five-year time charter agreements. The technology is overtaking scrubber investments in newbuild specification discussions at Korean yards.
The EU Green Deal's maritime emissions framework is tightening vessel efficiency standards for all cargo ships calling at Rotterdam, Antwerp, and Hamburg. Fleet operators must document attained Energy Efficiency Existing Ship Index ratings or face port access restrictions. Brazilian iron ore exporters are accelerating scrubber retrofits to maintain European market access.
Steel mill procurement departments are compressing contract durations from annual to quarterly fixtures to retain fuel price flexibility. Japanese trading houses are disintermediating traditional shipbrokers through direct platform engagement with vessel owners. This behavioral shift is most visible in spot market liquidity for Australian ore routes.
Global Dry Bulk Shipping Market Segmentation
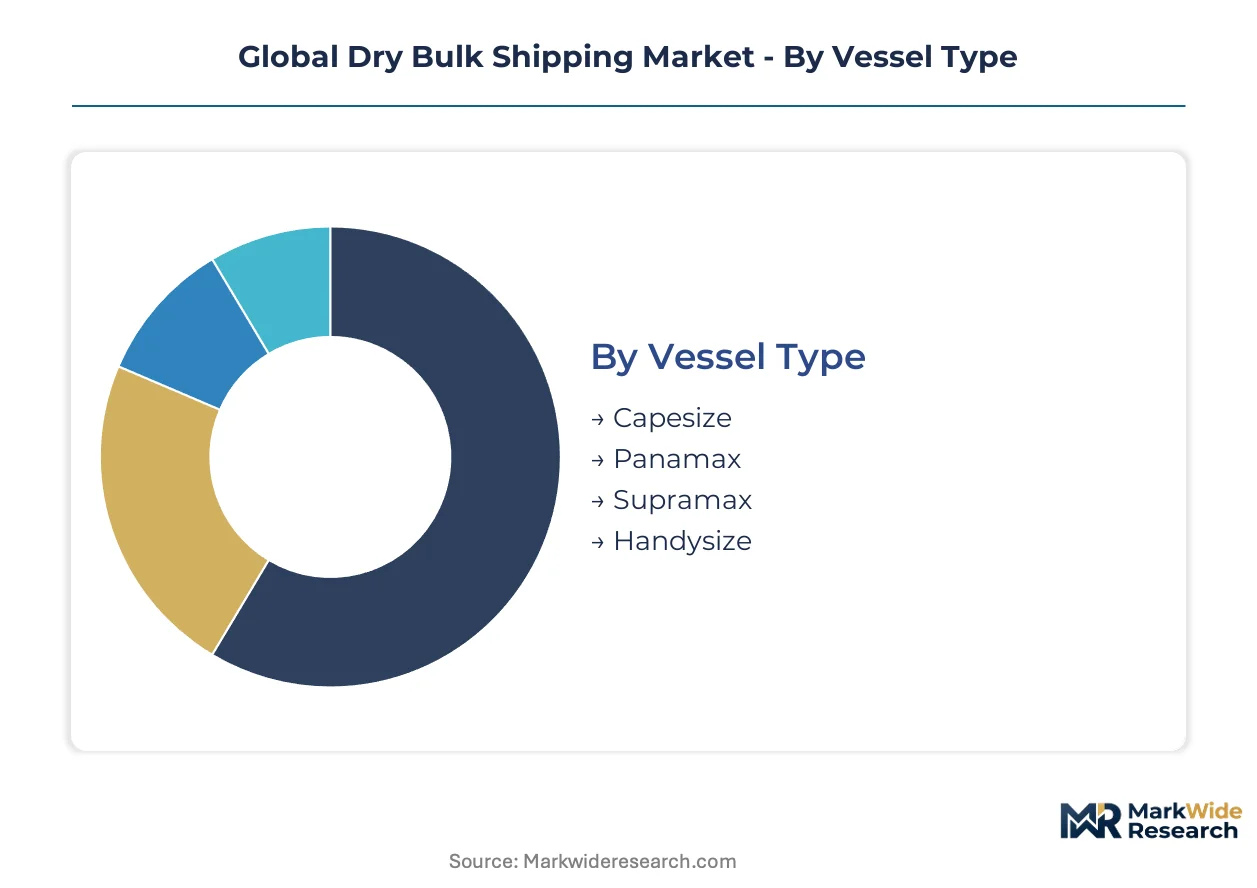
Dry bulk shipping segmentation reveals how vessel economics, cargo density, and contracting structures interlock. Fleet composition and chartering preferences vary sharply across commodity lanes and regional regulatory exposure.
Vessel Type:
Standalone Capesize deployment dominates dedicated ore corridors, while embedded multi-vessel operations characterize grain and coal trades requiring port flexibility.
- Capesize:Hulls exceeding 100,000 deadweight tons with reinforced structures for high-density iron ore. Australian mining majors fix these vessels on Western Australia-China routes where port drafts accommodate their 17-meter loaded depth.
- Panamax:Beam-constrained at 32.2 meters to transit Panama Canal locks. Grain traders in Brazil and the US Gulf deploy Panamax fleets for soybean and corn exports to East Asian feed mills.
- Supramax:Geared vessels with onboard cranes enabling discharge at ports lacking shore infrastructure. Indonesian nickel ore exporters and Black Sea grain operators favor this segment for operational independence.
- Handysize:Smallest segment in the analysis, serving coastal distribution of fertilizers and construction aggregates where draft limitations exclude larger tonnage.
Volume placements concentrate in Capesize; the faster expansion belongs to Supramax.
Cargo Type:
Cost tier stratification separates high-volume, low-value bulk from seasonal agricultural commodities with price-sensitive logistics.
- Iron Ore:Dense, non-reactive cargo requiring minimal hold preparation. Chinese blast furnace operators account for the dominant share of seaborne volume, with procurement cycles tied to steel mill restocking rhythms.
- Coal:Thermal and metallurgical grades with divergent stowage requirements. Indian power utilities and European steelmakers drive import demand through distinct seasonal patterns.
- Grain:Agricultural commodities requiring moisture control and hold cleanliness certification. Brazilian soybean exports and Ukrainian wheat shipments compete for Panamax and Supramax capacity during harvest windows.
- Fertilizers:Specialized bulk with corrosive handling protocols. Moroccan phosphate rock and Russian potash movements sustain Handysize and Supramax employment on shorter-haul routes.
Iron ore claims the largest cargo volume; fertilizers are climbing the fastest as agricultural input demand intensifies.
Service Type:
Customer type segmentation distinguishes spot-market participants from integrated supply chain operators with cargo forecasting capabilities.
- Voyage Charter:Single-voyage contracts priced at prevailing spot rates. Mining majors deploy this structure for flexible volume adjustments to Chinese steel mill demand.
- Time Charter:Multi-month vessel hire transferring operational control to cargo interests. Agricultural traders managing seasonal volume uncertainty prefer this structure for harvest-period fleet security.
- Bareboat:Long-term vessel lease with full operational and maintenance responsibility transferred to charterer. Energy companies with captive cargo flows utilize bareboat structures for fleet control without ownership capital.
- Contract of Affreightment:Multi-voyage cargo commitments without designated vessel assignment. Brazilian iron ore exporters and Japanese trading houses employ COAs to secure transport capacity across fluctuating market conditions.
Voyage charters dominate spot liquidity; contracts of affreightment are expanding most quickly among integrated commodity traders.
End User:
Maturity differentiation separates extractive industries with predictable cargo flows from manufacturing sectors with fragmented shipping requirements.
- Mining:Iron ore and coal producers with dedicated loading terminals and long-term vessel demand profiles. Australian and Brazilian exporters anchor Capesize fleet employment through multi-year offtake agreements.
- Agriculture:Grain traders and fertilizer distributors with seasonal volume spikes and quality-sensitive cargo handling. US, Brazilian, and Black Sea export corridors define Supramax and Panamax deployment patterns.
- Energy:Thermal coal importers and emerging biomass consumers. Indian and Southeast Asian power utilities drive import demand with government-mandated fuel security inventories.
- Manufacturing:Steel mills, cement producers, and chemical plants with diverse raw material requirements. Chinese and East Asian industrial consumers integrate shipping into just-in-time production scheduling.
Mining commands the deepest vessel commitments; manufacturing end users are gaining share fastest as supply chain integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia and Brazil concentrate iron ore production for blast furnaces in China and Japan. Consumption gravity sits with East Asian steel mills. Regulatory divergence on maritime emissions is fragmenting vessel deployment strategies across trade lanes.
China
Chinese steel mills account for over sixty percent of seaborne iron ore imports, with procurement departments at Baowu and Shagang Group driving Capesize fixture volumes. The Ministry of Transport enforces domestic emission control areas restricting bunker fuel sulfur content on coastal routes. Ningbo-Zhoushan and Qingdao anchorages absorb vessel supply through discharge delays that compress effective fleet availability.
Australia
Pilbara mining majors Rio Tinto and BHP anchor global Capesize employment through dedicated Western Australia-China ore corridors. The Australian Maritime Safety Authority aligns with IMO Energy Efficiency Existing Ship Index compliance timelines for vessels under its flag. Port Hedland and Dampier terminals sustain the highest volume loading rates for dry bulk tonnage worldwide.
Brazil
Vale's Carajás iron ore system feeds Chinese and European blast furnaces through dedicated Capesize and Valemax vessel classes. Brazilian regulators are accelerating scrubber retrofits to maintain European market access under EU ETS maritime carbon pricing. Itaqui and Tubarão terminals concentrate outbound bulk movements on the Atlantic route.
Japan
Japanese trading houses and steelmakers at Nippon Steel and JFE Holdings contract time-charter tonnage for iron ore and coal procurement. METI coordinates national fleet decarbonization programs aligned with IMO greenhouse gas reduction targets. Chiba and Kawasaki industrial corridors concentrate blast furnace capacity and associated vessel demand.
Germany
German steelmakers at ThyssenKrupp and Salzgitter import iron ore through Rotterdam and Hamburg transshipment. The EU Green Deal's maritime emissions framework tightens vessel efficiency standards for all cargo ships calling at Hamburg and Bremerhaven. Hamburg port authorities are screening vessel Energy Efficiency Existing Ship Index ratings before granting berth access.
Global Dry Bulk Shipping Market Vendor Landscape
The competitive structure tilts toward state-backed and publicly listed fleet operators with differentiated vessel profiles. Consolidation favors owners of modern Capesize tonnage capable of meeting tightening emissions benchmarks. Three archetypes dominate: state-owned champions with cargo contract security, listed operators with scale-driven unit cost advantages, and specialized ice-class or geared-vessel niche players. Dominant competitive moves include fleet renewal through newbuild orders and retrofits for wind-assisted propulsion, plus long-term cargo partnerships with mining majors.
Among state-owned and publicly listed carriers, COSCO Shipping Bulk Co., Ltd. exemplifies the state-backed archetype securing long-term cargo contracts, while Star Bulk Carriers Corp. and Golden Ocean Group Limited occupy positions within the modern-fleet tier emphasizing lower carbon intensity profiles. These three entities represent contrasting strategic postures: sovereign scale, listed-market transparency, and specialized vessel deployment for high-latitude ore corridors.
| Leading Market Players |
|---|
| COSCO Shipping Bulk Co., Ltd. |
| Star Bulk Carriers Corp. |
| Golden Ocean Group Limited |
| Pacific Basin Shipping Limited |
| Oldendorff Carriers |
| Nippon Yusen Kabushiki Kaisha (NYK Line) |
| Diana Shipping Inc. |
| Genco Shipping & Trading Limited |
| Ultrabulk A/S |
| Others |
Supply Flow & Price Mechanics
Captive integration into Australian and Brazilian mining terminals anchors Capesize vessel deployment patterns and reinforces long-term contracting premiums for fleet operators with dedicated berth access. This vertical control over loading infrastructure insulates major ore exporters from spot market volatility while compressing margins for independent vessel owners lacking similar cargo commitments.
Pricing Analysis
Cost compression in voyage charter rates reflects persistent overcapacity among older Capesize tonnage struggling to meet IMO Energy Efficiency Existing Ship Index benchmarks. Contract-based long-term offtake agreements dominate Australian iron ore corridors, while spot pricing governs grain and coal trades with seasonal volume uncertainty. Price differentiation hinges on vessel carbon intensity ratings and scrubber installation status, with EU ETS compliance costs widening spreads between efficient and legacy hulls. Mining majors exhibit lowest price sensitivity due to integrated logistics planning, whereas agricultural traders demonstrate highest sensitivity to freight rate swings during harvest windows.
Supply Chain Analysis
Direct-to-steel-mill channels handle hyperscale iron ore demand from Pilbara loading terminals through dedicated Western Australia-China corridors. Supply concentrates in Australia, Brazil, and China for ore extraction and consumption, with South Korean and Chinese shipyards controlling newbuild vessel output. Raw material dependencies include marine steel plate, low-sulfur bunker fuels, and specialized engine components for dual-fuel propulsion systems. Single-source vulnerability permeates shipyard capacity, where concentrated slot control extends delivery timelines for specialized ore carriers. Distribution runs through mining-major cargo desks, Japanese trading houses, and digital freight platforms disintermediating traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
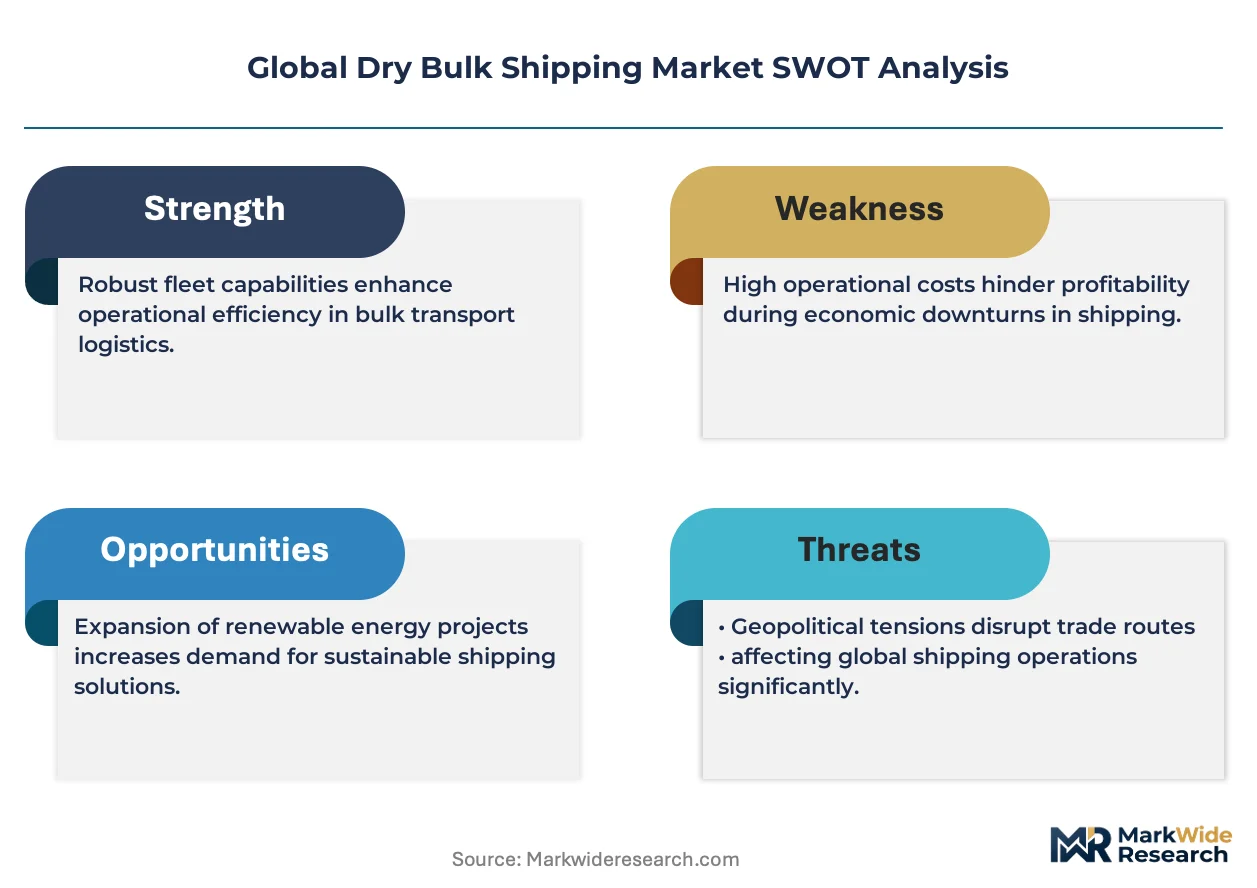
The Global Dry Bulk Shipping Market operates as a cost-of-compliance arena where EU Emissions Trading System carbon pricing erects regulatory moats favoring fleet operators with capital reserves for retrofit investments and newbuild specifications.
For Market Incumbents: Deploy wind-assisted propulsion retrofits to secure preferential EU ETS treatment and green financing terms from institutional lenders screening vessel efficiency profiles. Accelerate demolition of pre-2010 Capesize tonnage before Energy Efficiency Existing Ship Index enforcement hardens port access restrictions at Rotterdam and Hamburg. Consolidate market position through long-term cargo partnerships with Rio Tinto and BHP inserting emissions clauses into five-year time charter agreements. For New Entrants and Emerging Players: Trading houses with direct platform engagement capabilities represent the most penetrable channel partner type for bypassing traditional shipbroker intermediation. Target Indonesian nickel ore export corridors where EV battery supply chain demand creates new Capesize employment on Southeast Asian routes previously served by smaller Handymax units. Pursue bareboat charter structures with energy companies seeking fleet control without ownership capital deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-backed champions seeking sovereign cargo security and listed operators pursuing scale-driven unit cost advantages. Long-term viability favors owners of modern Capesize tonnage with ice-class specifications or geared-vessel flexibility for high-latitude ore corridors. Monitor EU Monitoring, Reporting and Verification audit complexity as the signal to watch for competitive differentiation between compliant operators and smaller players struggling with data infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Wind-Assisted Propulsion Retrofit | Rotor sail installations qualify vessels for preferential EU ETS carbon pricing treatment at Rotterdam. |
| Scrubber System Installation | Exhaust gas cleaning enables continued high-sulfur fuel oil consumption amid VLSFO price volatility. |
| Long-Term Cargo Partnership | Five-year time charter agreements with Australian mining majors secure revenue visibility through steel mill restocking cycles. |
| Fleet Renewal Program | Newbuild orders at Korean and Chinese yards replace aging tonnage before IMO compliance deadlines tighten. |
| Digital Platform Integration | Blockchain-based voyage charter marketplaces compress broker intermediation and accelerate fixture finalization. |
Methodological Framework
IMO regulatory filings, customs trade data, and SEC vessel owner disclosures formed the secondary backbone for market sizing and fleet composition analysis. Primary interviews with fleet operations managers, chartering executives at mining majors, shipbroker principals, and marine engineering specialists supplied forward-looking contract structures and retrofit investment timelines. Bottom-up triangulation across vessel deployment patterns and top-down validation through commodity trade flow databases ensured cross-verified volume estimates.
Bottom-up modeling of Capesize, Panamax, Supramax, and Handysize vessel segments combined with top-down macroeconomic freight rate indices across the projection horizon. Segmentation dimensions included vessel type, cargo category, service contract structure, and end-user industry with regional regulatory cluster overlays. CAGRs were derived from fitted trend analysis of historical fixture rates and projected fleet supply-demand balances. Industry-specific forecast inputs incorporated steel mill restocking cycle patterns and EU ETS carbon price trajectory assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption of Black Sea grain corridors and abrupt shifts in Chinese blast furnace operating rates. Forecasts reflect documented assumptions regarding regulatory implementation timelines and shipyard delivery schedules. Periodic stress-testing of base assumptions is recommended given commodity price volatility and evolving maritime emissions enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Intralogistics Containers Market