
 Hybrid Fishing Boats Market | 2026-2036
Hybrid Fishing Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Fishing Boats Market Insights
Norway is reconfiguring North Atlantic fishing fleet operations through aggressive harbor electrification and hybrid conversion programs. Brunswick Corporation anchors North American sport fishing with integrated gas-electric propulsion platforms across its center console portfolio. Groupe Beneteau leverages European manufacturing scale to supply dual-console hybrids for Mediterranean charter fleets. Candela Technology AB specializes in hydrofoil-assisted electric systems that extend range for coastal commercial operators.
Hybrid fishing boats combine conventional internal combustion engines with electric motors, battery storage, and regenerative charging systems to enable variable-speed propulsion and zero-emission harbor maneuvering. Lithium-ion battery packs typically deliver 50–150 kWh capacity with thermal management systems rated for saltwater exposure, supporting 4–8 hours of silent electric-only operation for sensitive marine environments. Center console configurations dominate sport fishing applications where deck layout flexibility accommodates battery enclosures beneath gunwales. Solar hybrid power sources represent the fastest-expanding segment as photovoltaic-integrated hardtops reduce generator dependency for electronics and climate systems. Commercial fishing end users concentrate demand in diesel-electric configurations that preserve range for offshore trawling while cutting fuel costs in regulated nearshore zones.
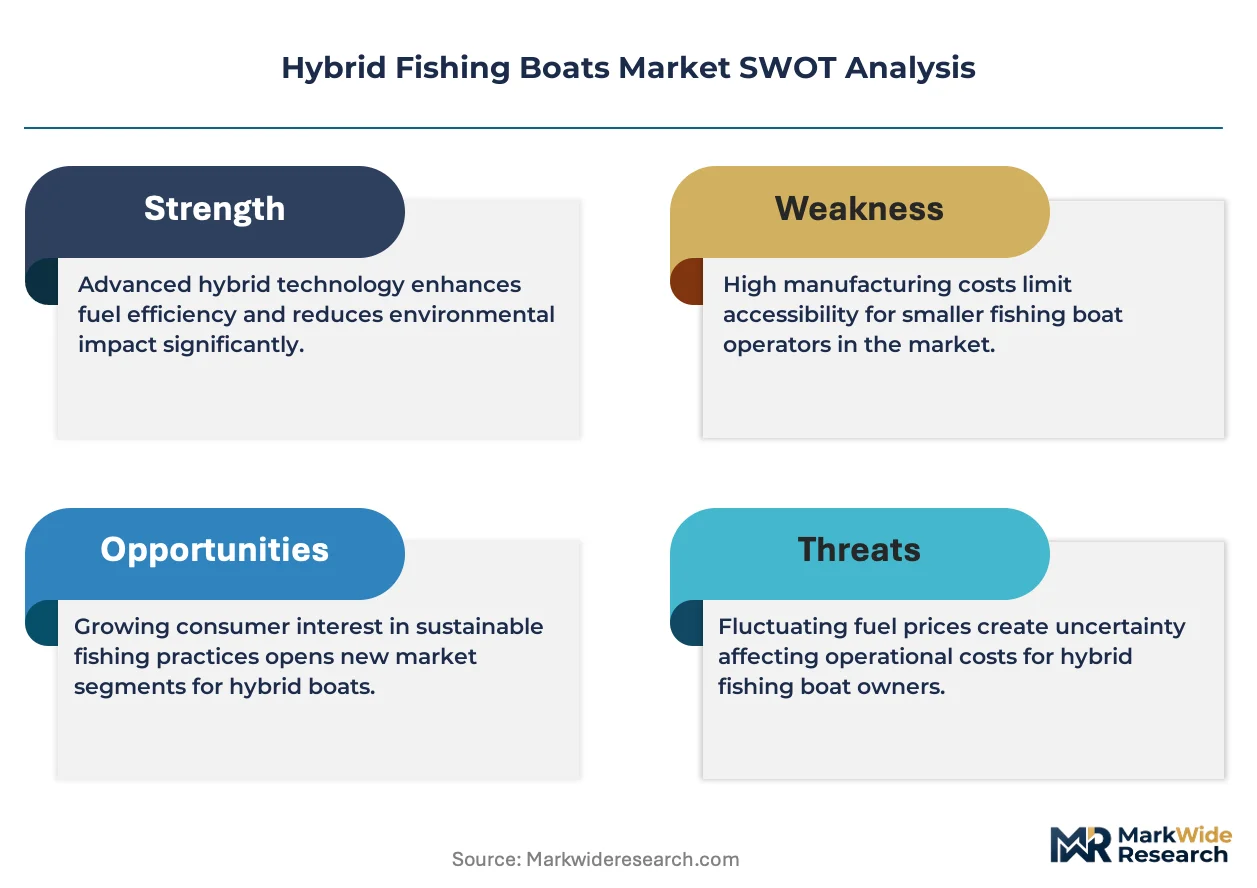
EPA marine engine standards and the EU Green Deal's FuelEU Maritime initiative are tightening emissions benchmarks for coastal and inland waterway vessels, directly accelerating hybrid propulsion investment. Japan's METI provides vessel electrification subsidies through its Green Innovation Fund, while the IMO's revised carbon intensity indicators reshape global fleet procurement criteria. Stakeholders must monitor battery supply chain localization requirements and emerging solid-state chemistry timelines that could reset total-cost-of-ownership calculations across all power source segments.
Market Dynamics
The EU Green Deal's FuelEU Maritime initiative is compressing conversion timelines for coastal fishing fleets. Battery supply chain localization mandates are simultaneously reshaping procurement geography.
Growth Catalysts
- Harbor electrification infrastructure:Norway's port authorities are installing shore power systems that enable diesel-electric hybrids to operate in zero-emission zones during loading and unloading operations.
- METI vessel subsidies:Japan's Green Innovation Fund covers up to 50% of electrification retrofit costs for aging coastal fleets in Hokkaido and Kyushu prefectures.
- Lithium-iron-phosphate chemistry:Improved thermal stability in saltwater environments is extending battery cycle life for commercial operators running daily charge-discharge schedules.
Market Restraints
- Cathode material concentration:Lithium carbonate processing capacity clusters in China, exposing European and North American boatbuilders to supply disruption risks.
- Range anxiety in offshore segments:Trawler operators in the North Atlantic require 800+ nautical mile endurance that pure-electric configurations cannot deliver.
- Port infrastructure gaps:Coastal municipalities in Mediterranean Spain and Italy lack grid capacity for simultaneous multi-vessel fast charging.
Strategic Opportunities
- Solar-integrated hardtops:Photovoltaic panels on sport fishing vessels reduce generator runtime for electronics and climate control systems.
- Solid-state battery timelines:Toyota and Samsung SDI development roadmaps promise energy density improvements that could reset total-cost-of-ownership calculations by 2030.
- Indonesia's archipelago fleet:The world's largest island nation presents untapped demand for shallow-draft electric vessels serving reef-sensitive tourism zones.
Industry Challenges
- Marine electrical certification backlog:Bureau Veritas and DNV classification societies face 6-12 month queues for hybrid propulsion system approval.
- Skill gaps in vessel electrification:Shipyards in traditional fishing regions lack technicians trained in high-voltage battery management and thermal runaway protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Fishing Boats Market |
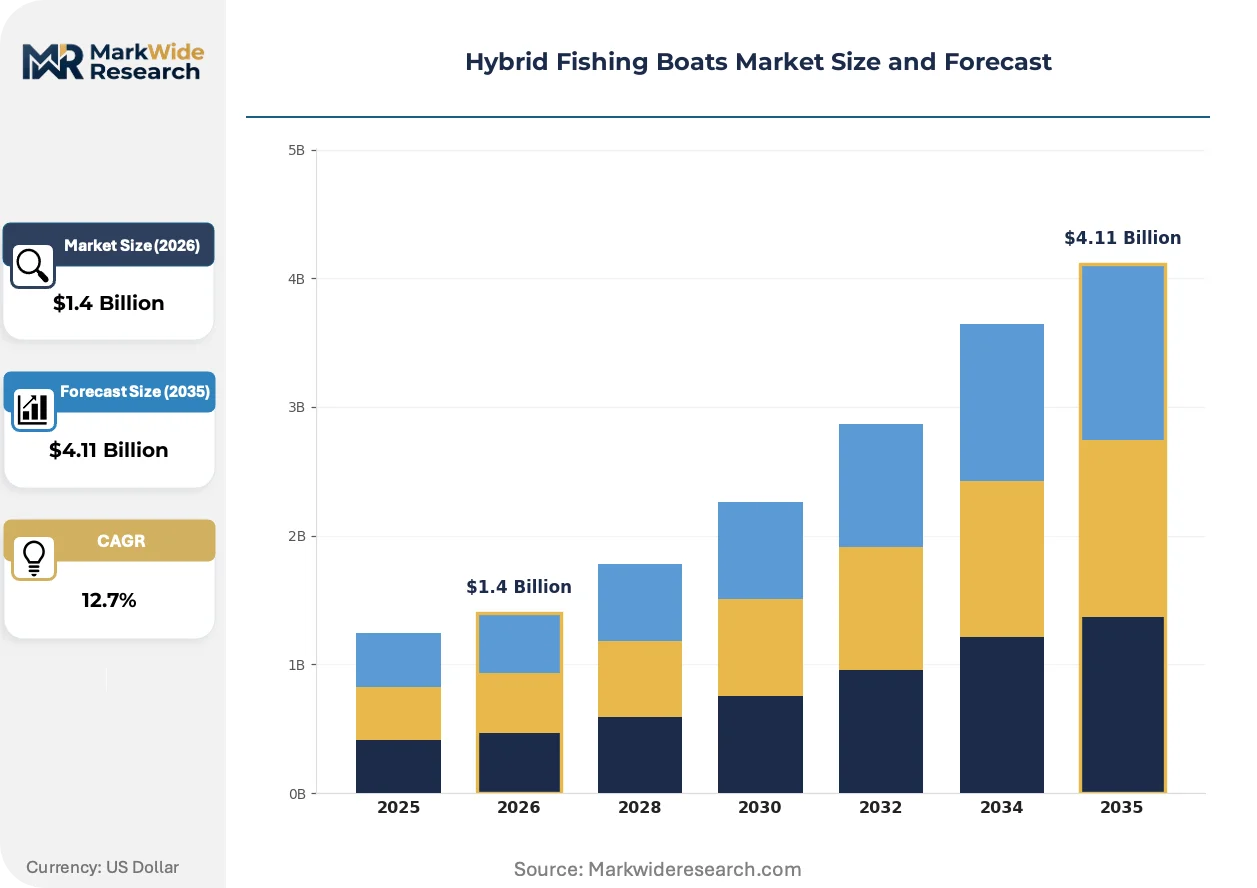
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Center Console, Dual Console, Pontoon, Kayak Power Source: Gas & Electric, Solar Hybrid, Battery-Powered, Diesel & Electric Application: Sport Fishing, Commercial Fishing, Recreational Use, Environmental Monitoring End User: Fishing Enthusiasts, Charter Services, Environmental Agencies, Research Institutions |
| Companies Covered | Brunswick Corporation, Groupe Beneteau, Greenline Yachts, Candela Technology AB, Silent Yachts, Everglades, Solace Boats, Grady-White, Crevalle Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Fishing Boats Market Trends and Innovations
Propulsion architecture is splitting into modular platforms that accommodate multiple power sources. This shift enables boatbuilders to customize configurations across sport, commercial, and charter segments without redesigning hull structures.
Hydrofoil-assisted electric systems are migrating from recreational day-cruisers into commercial fishing applications. Coastal salmon farmers in Norway and Scotland are adopting Candela's foil technology to reduce wave resistance and extend electric range. The structural consequence is compressing the viable market for conventional displacement hulls in nearshore zones under 50 nautical miles from port.
FuelEU Maritime's 2025 enforcement timeline is tightening emissions benchmarks for vessels over 400 gross tons. Commercial fishing cooperatives in Denmark and the Netherlands are pooling capital for fleet-wide hybrid conversions ahead of compliance deadlines. Trawler segments operating in the North Sea and Baltic are most affected, with owners prioritizing diesel-electric configurations that preserve range while cutting fuel costs in regulated nearshore zones.
Charter operators are unbundling vessel ownership from trip packaging. Mediterranean fleets in Croatia and Greece now offer hybrid center consoles through membership subscriptions rather than traditional daily rates. This model concentrates in high-frequency tourism corridors where environmental credentials command premium positioning with eco-conscious anglers.
Hybrid Fishing Boats Market Segmentation
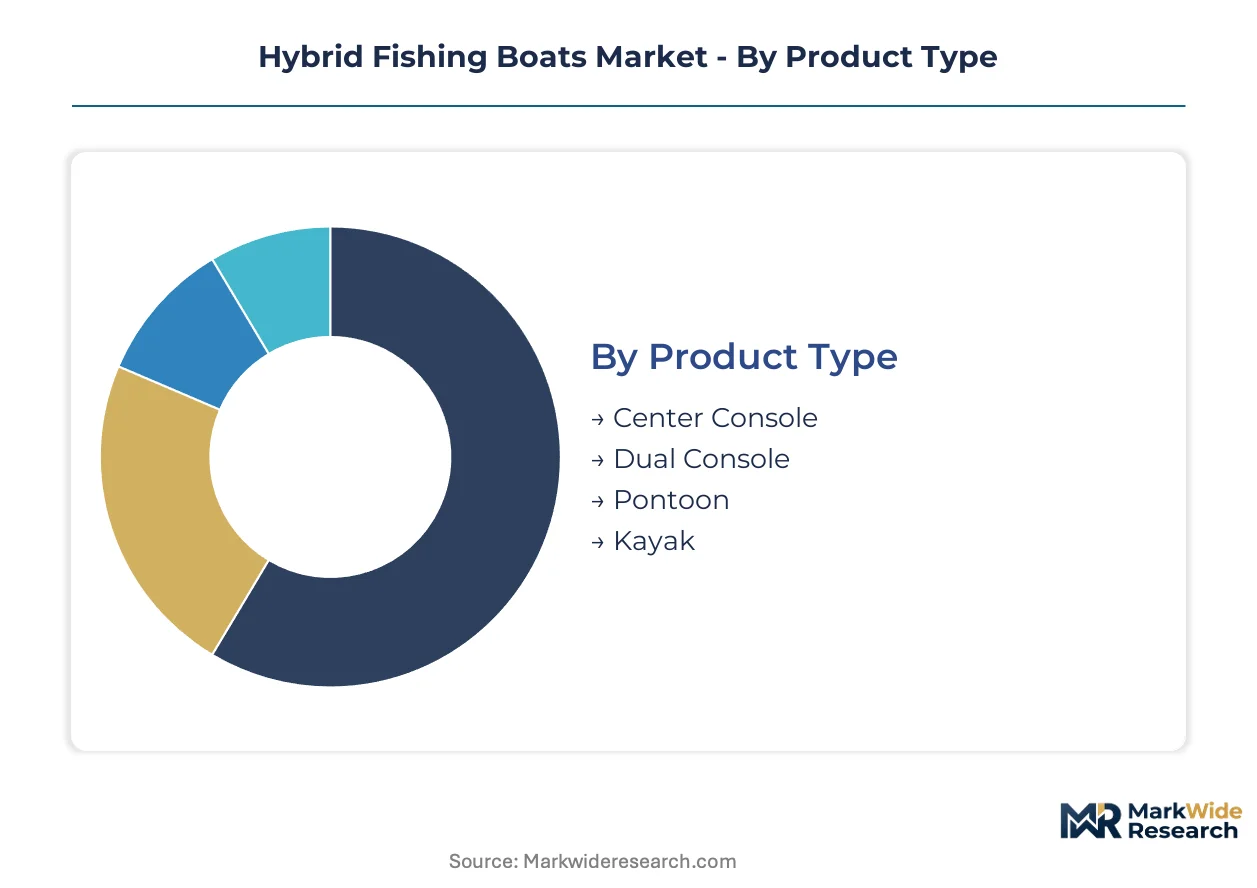
Hybrid fishing boats fragment across four distinct dimensions that shape procurement patterns and technology deployment. Product architecture determines battery enclosure feasibility and deck layout flexibility. Power source selection locks in operational economics and regulatory compliance trajectories for fleet operators.
Product Type:
Configuration options span the use-case spectrum from open-deck commercial platforms to enclosed recreational hulls.
- Center Console:Open-deck layout with centrally positioned helm stations accommodates battery packs beneath gunwales without sacrificing fishing space. Brunswick Corporation and other North American builders concentrate production here for sport fishing demand in Florida and the Gulf Coast.
- Dual Console:Enclosed windscreens and passenger seating expand weather protection for charter operations. Groupe Beneteau leverages European manufacturing scale to supply Mediterranean fleets where dual-console hybrids command premium daily rates.
- Pontoon:Flat-deck platforms with multiple hull tubes provide stable casting surfaces and ample battery storage in pontoons. Demand clusters in freshwater lake systems across the US Upper Midwest.
- Kayak:Human-scale vessels with integrated electric assist motors target solo anglers in shallow estuaries. Lightweight lithium packs enable portage between launch points.
The dominant share belongs to Center Console, while Dual Console is closing the gap fastest as charter operators upgrade Mediterranean fleets.
Power Source:
Cost tier stratification separates premium solar-integrated systems from baseline gas-electric retrofits.
- Gas & Electric:Conventional outboards paired with auxiliary electric motors enable harbor maneuvering without main engine ignition. Entry-level sport fishing buyers in North America favor this architecture for its retrofit compatibility with existing hulls.
- Solar Hybrid:Photovoltaic-integrated hardtops reduce generator dependency for electronics and climate systems. Photovoltaic panels on sport fishing vessels reduce generator runtime for electronics and climate control systems, gaining share fastest in high-sunshine coastal zones.
- Battery-Powered:Pure-electric configurations eliminate combustion entirely for zero-emission operation. Range constraints limit deployment to nearshore zones under 50 nautical miles from charging infrastructure.
- Diesel & Electric:Heavy-duty commercial systems preserve offshore endurance while cutting fuel costs in regulated nearshore zones. Norwegian and Danish trawler cooperatives prioritize this configuration for North Atlantic operations under FuelEU Maritime compliance timelines.
Diesel & Electric commands commercial fleet procurement, though Solar Hybrid is expanding most quickly as photovoltaic costs decline.
Application:
Volume concentration in recreational segments masks higher margins in specialized commercial and monitoring deployments.
- Sport Fishing:Competitive and leisure angling drives center-console demand with emphasis on deck layout flexibility and silent trolling motors. METI subsidies in Japan support vessel electrification for aging coastal fleets in Hokkaido and Kyushu prefectures.
- Commercial Fishing:Diesel-electric hybrids enable trawler operators to meet emissions benchmarks while preserving range for offshore operations. FuelEU Maritime enforcement is compressing conversion timelines for North Sea and Baltic fleets.
- Recreational Use:General boating and family cruising applications prioritize cabin comfort and reduced noise signatures. Pontoon configurations dominate this segment in inland waterway systems.
- Environmental Monitoring:Research vessels require silent propulsion for acoustic sampling and minimal wake for water quality assessment. Battery-powered kayaks and small catamarans serve marine biology fieldwork.
Sport Fishing holds the installed base advantage, though Commercial Fishing is gaining share fastest as regulatory deadlines approach.
End User:
Customer type determines financing structures and technology risk tolerance across the procurement landscape.
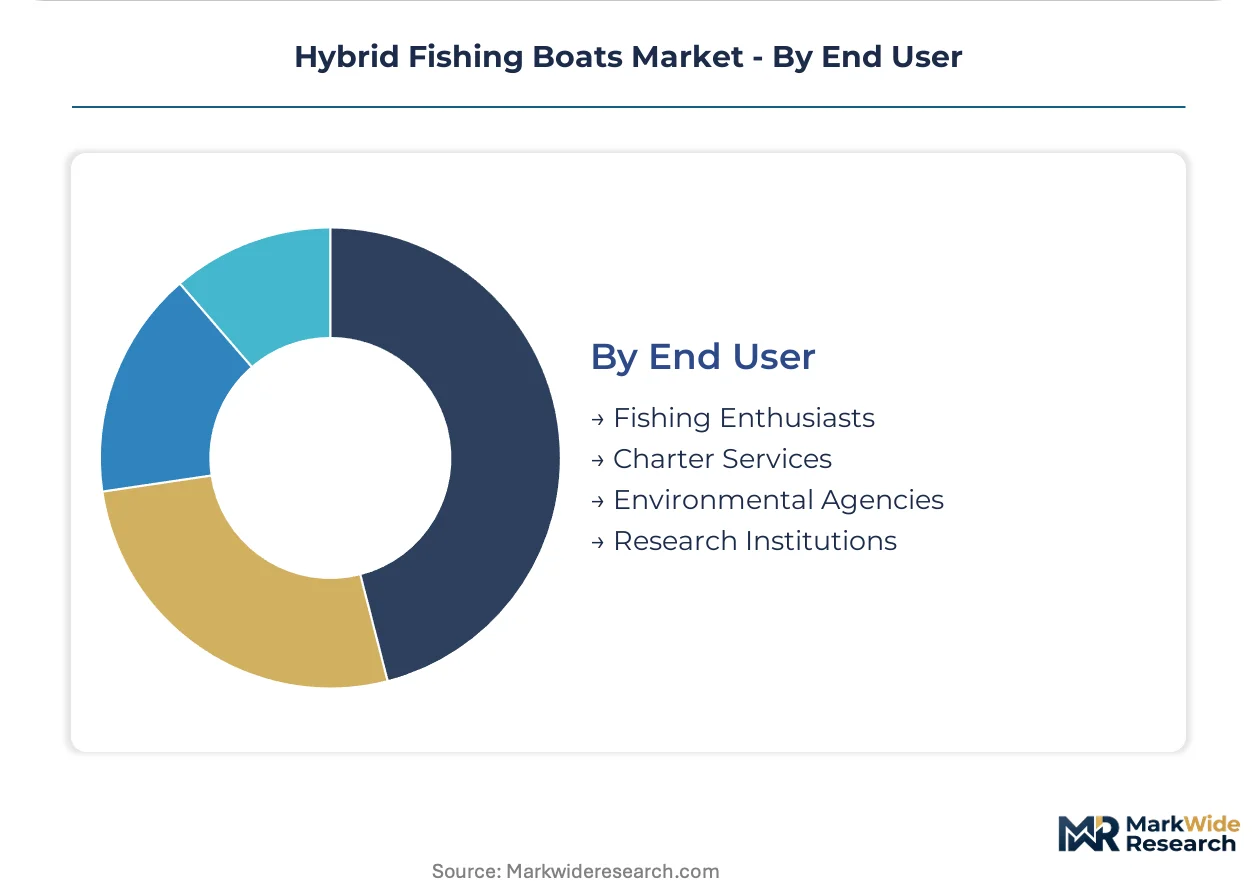
- Fishing Enthusiasts:Individual owners purchasing for personal use prioritize upfront cost and familiar maintenance procedures. This segment concentrates in coastal US states and Australian recreational boating markets.
- Charter Services:Fleet operators monetize environmental credentials through premium pricing to eco-conscious anglers. Mediterranean subscription models in Croatia and Greece unbundle vessel ownership from trip packaging.
- Environmental Agencies:Government purchasers mandate compliance with public-sector sustainability targets and domestic content requirements. Procurement timelines extend 18-24 months for budget authorization cycles.
- Research Institutions:Academic and nonprofit operators require specialized sensor integration and extended stationary operation for data collection. Silent electric propulsion enables acoustic research without engine noise interference.
Fishing Enthusiasts represent the largest addressable population, while Charter Services is climbing the fastest as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's vessel electrification subsidies anchor Japanese demand for hybrid fishing boats, while EU Green Deal enforcement compresses conversion timelines across North Atlantic fleets. Coastal municipalities in Norway and Japan lead harbor infrastructure deployment. Regulatory pressure spans three continents with distinct compliance mechanisms.
Norway
North Atlantic trawler cooperatives are pooling capital for fleet-wide diesel-electric conversions ahead of FuelEU Maritime deadlines. The country's port authorities are installing shore power systems enabling zero-emission harbor operations during loading and unloading. Bergen and Tromsø host the densest concentrations of hybrid vessel retrofit activity.
Japan
Coastal prefectures Hokkaido and Kyushu drive aging fleet replacement through METI's Green Innovation Fund covering up to half of electrification retrofit costs. Battery-powered configurations dominate nearshore zones under 50 nautical miles from charging infrastructure. Nagasaki shipyards specialize in lithium-iron-phosphate thermal management systems for saltwater environments.
United States
EPA marine engine standards accelerate gas-electric retrofits across Florida and Gulf Coast sport fishing fleets. Center console configurations accommodate battery enclosures beneath gunwales without sacrificing deck flexibility. Brunswick Corporation anchors integrated propulsion platform supply from its coastal manufacturing footprint.
Denmark
Commercial fishing cooperatives in the North Sea and Baltic prioritize diesel-electric configurations preserving offshore range while cutting fuel costs in regulated nearshore zones. The country's national maritime regulator enforces IMO carbon intensity indicators reshaping procurement criteria. Esbjerg functions as the primary hub for trawler hybrid conversion services.
Indonesia
Archipelago geography creates untapped demand for shallow-draft electric vessels serving reef-sensitive tourism zones. Solar-integrated hardtops reduce generator dependency for electronics in high-sunshine coastal corridors. Bali and Lombok charter operators are piloting subscription-based vessel access models unbundling ownership from trip packaging.
Hybrid Fishing Boats Market Competitive Landscape
Integrated marine conglomerates and specialized electric propulsion boutiques split the market along technology-risk lines. The vendor base concentrates in North American sport fishing and European commercial conversion segments. Three archetypes dominate: legacy boatbuilders with gas-electric portfolios, foil-assisted electric specialists, and solar-hybrid system integrators. Capacity expansion and strategic technology licensing represent the primary competitive vectors as battery supply chain localization mandates reshape procurement geography.
Within the legacy boatbuilder tier, Brunswick Corporation and Groupe Beneteau occupy positions reflecting continental manufacturing scale and charter market access. Candela Technology AB exemplifies the foil-assisted electric specialist archetype migrating recreational technology into commercial salmon farming applications. These three entities represent distinct strategic postures without overlapping segment focus.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Groupe Beneteau |
| Greenline Yachts |
| Candela Technology AB |
| Silent Yachts |
| Everglades |
| Solace Boats |
| Grady-White |
| Crevalle Boats |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese lithium carbonate processing is compressing margins for European and North American boatbuilders while concentrating supplier bargaining power among cathode material processors. This utilization asymmetry forces hybrid fishing boat manufacturers to absorb input volatility or pass costs to fleet operators already facing FuelEU Maritime compliance expenditures.
Pricing Analysis
Geographic price spreads between Norwegian commercial conversions and Mediterranean charter configurations reflect divergent regulatory urgency and subsidy coverage. Three-tier pricing structure across premium foil-assisted, standard diesel-electric, and economy gas-electric levels separates Candela's hydrofoil systems from Brunswick's integrated platforms and entry-level retrofit kits. Price differentiation centers on battery energy density ratings and DNV certification tiers rather than hull architecture alone. Cost compression in the economy tier is intensifying because Japanese METI subsidies concentrate demand-pull toward mid-range electrification packages, pressuring bare-bones gas-electric retrofits without shore-power compatibility.
Supply Chain Analysis
Contract manufacturing concentration among Nagasaki shipyards and Groupe Beneteau's Polish production facilities limits flexible capacity expansion for foil-assisted hull fabrication. Geographic supply concentration in China, South Korea, and Japan for lithium-iron-phosphate cells draws from cobalt-free cathode chemistries and saltwater-rated thermal management systems. Raw material dependencies on processed lithium carbonate, copper busbar assemblies, and marine-grade power electronics create single-source vulnerability through Chinese cathode processing dominance. Distribution runs through direct fleet procurement for commercial operators and dealer networks for recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid fishing boats market is recovering from a cyclical trough driven by post-pandemic fleet renewal backlogs and compressed shipyard capacity. Regulatory enforcement timelines for FuelEU Maritime and EPA marine engine standards are synchronizing procurement waves across North Atlantic and North American coastal zones.
For Market Incumbents: Entrench position through backward integration into battery pack assembly and captive supply of lithium-iron-phosphate cells from localized sources. Lock in long-term harbor electrification partnerships with Norwegian and Japanese port authorities to secure preferential shore-power access for converted fleets. Prioritize DNV certification investment to accelerate approval queues that currently stretch 6-12 months.
For New Entrants and Emerging Players: Build out shallow-draft electric vessel capabilities targeting Indonesia's archipelago tourism corridors where reef-sensitive zones restrict combustion engine access. Solar-integrated hardtops for Bali and Lombok charter operators represent the most penetrable segment given minimal incumbent presence and high sunshine hours enabling photovoltaic range extension. Pursue subscription-based ownership models that unbundle capital expenditure from trip revenue.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charter services with subscription fleet access rather than individual enthusiast ownership. Long-term viability over a 5-10 year window favors vertically integrated boatbuilders with in-house battery thermal management and foil-assisted hull engineering. Target acquisition archetypes include foil-assisted electric specialists migrating from recreational to commercial salmon farming applications. Monitor solid-state battery development timelines from Toyota and Samsung SDI as inflection indicators that could reset total-cost-of-ownership calculations across all power source tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Harbor Electrification Partnership | Locks in preferential shore-power access for Norwegian trawler cooperatives ahead of FuelEU deadlines. |
| Solid-State Battery Supply Agreement | Secures early allocation from Toyota or Samsung SDI development roadmaps for range-extended commercial configurations. |
| Foil-Assisted Hull Platform Licensing | Extends Candela's hydrofoil technology into Mediterranean charter and Indonesian tourism markets. |
| Subscription Fleet Ownership Model | Unbundles vessel capital expenditure from trip revenue for Croatian and Greek charter operators. |
| DNV Classification Fast-Track Program | Compresses 6-12 month marine electrical certification queues for hybrid propulsion system approvals. |
Research Methodology
A standing panel of commercial fleet operators, shipyard electrification technicians, port authority infrastructure planners, and marine classification society surveyors provided ongoing calibration throughout the study period. Primary interviews with Norwegian trawler cooperative managers, Japanese METI subsidy administrators, and Brunswick Corporation platform engineers combined with secondary validation from EPA marine engine standard filings, EU Green Deal regulatory texts, and IMO carbon intensity indicator databases. Bottom-up vessel deployment counts and top-down fuel cost savings estimates were triangulated to anchor market sizing.
Scenario-bracketing framed analytical approach across the projection horizon, with demand cases varying METI subsidy renewal trajectories and FuelEU Maritime enforcement stringency. Segmentation dimensions modeled included propulsion architecture, hull configuration, power source chemistry, fleet operator type, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to historical diesel-electric penetration in North Atlantic trawler fleets and solar-hybrid uptake in Mediterranean charter markets. Forecast inputs incorporated lithium-iron-phosphate cell cost decline curves and harbor electrification infrastructure deployment schedules.
Sensitivities concentrate around battery supply chain localization mandates and solid-state chemistry commercialization timelines that could reset competitive economics. Forecasts reflect assumptions regarding regulatory enforcement consistency and subsidy program continuity without guaranteed extension. Quarterly review of DNV certification queue lengths, METI fund allocation announcements, and cathode material spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Big Data Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Europe Marine Communication Systems Market
Marine
Marine Beacon Market
Marine
Global Submarine Market
Marine
Marine Bearings Market
Marine
Submarine Propulsion Systems Market
Marine
Electric Ship Market
Marine
Europe Recreational Boating Market
Marine
Marine Interiors Market
Marine
Rescue Boats Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine and Marine Management Software Market
Marine
Freighter Conversions Market
Marine
Marine Diesel Engine Market
Marine
Marine Pipes Market