
 Asia-Pacific Digital Shipyard Market | 2026-2036
Asia-Pacific Digital Shipyard Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Shipyard Market Analytics
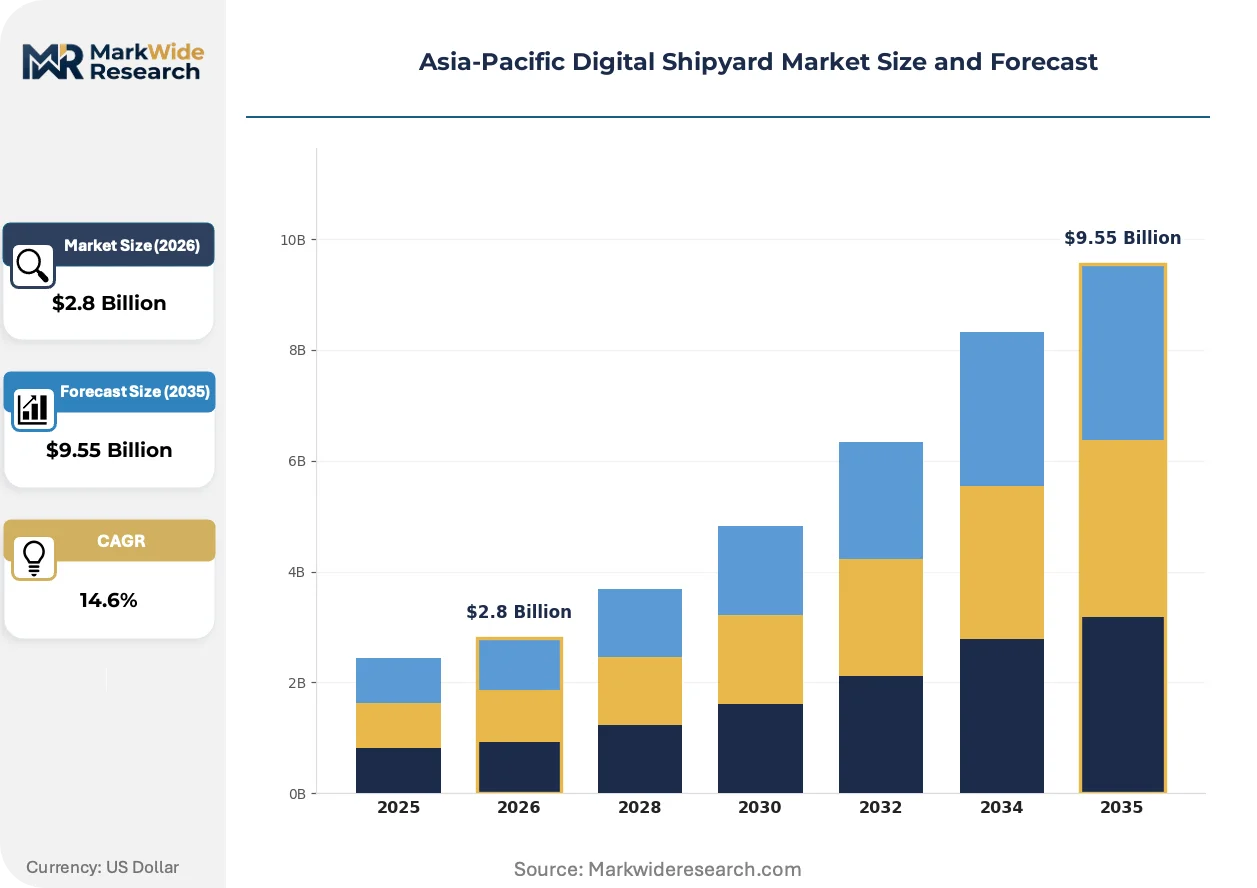
Modular service bundling is repositioning buyer choice in the Asia-Pacific Digital Shipyard Market, as shipyards shift from standalone software licenses to integrated implementation-and-maintenance contracts. Siemens leverages its digital twin portfolio to anchor European-Asian technology transfer partnerships. Hanwha Systems sustains its domestic Korean dominance through defense-focused shipyard automation platforms. AVEVA differentiates via cloud-native engineering data management tailored to multi-yard fleet operators.
Digital shipyards integrate AI-driven production planning, IoT-enabled asset monitoring, and cloud-based collaborative engineering to optimize vessel construction workflows and reduce drydock turnaround times. The technology dimension shows AI and IoT commanding the deepest R&D commitments as yards pursue predictive maintenance and real-time hull welding quality control. Service type insights reveal implementation services capturing the largest immediate revenue pools, while maintenance contracts generate the stickiest recurring revenue streams across the forecast horizon.
Japan's METI promotes smart shipbuilding roadmaps that mandate interoperable data standards across keiretsu supplier networks. South Korea's KOSHA occupational safety frameworks and China's MIIT smart manufacturing directives collectively tighten compliance requirements for yard digitization vendors. Stakeholders must monitor evolving cybersecurity certification regimes as naval and commercial fleets converge on connected operational technology architectures.
Market Dynamics
Naval defense procurement across Southeast Asian states is compressing platform modernization timelines, while China's MIIT smart manufacturing mandates and dual carbon goals force simultaneous energy efficiency and automation upgrades across commercial yards.
Growth Catalysts
- MIIT Smart Manufacturing Directives:China's Ministry of Industry and Information Technology mandates digital twin adoption across heavy industry, compelling state-owned and private yards to accelerate IoT infrastructure deployment.
- Naval Fleet Modernization:Southeast Asian defense ministries in Indonesia, Vietnam, and the Philippines are commissioning frigate and submarine programs that require digitally integrated construction workflows.
- AI-Driven Welding Quality Systems:Machine vision and predictive hull inspection technologies are reducing rework rates and drydock turnaround times for Korean and Japanese builders.
Market Restraints
- Legacy System Integration Costs:Proprietary CAD and ERP architectures from the 1990s require expensive middleware layers to connect with cloud-native digital twin platforms.
- Cybersecurity Certification Fragmentation:Divergent naval and commercial fleet security standards across Australia, Japan, and South Korea create compliance overhead for multi-yard operators.
- Specialized OT Talent Scarcity:Shortages of engineers trained in both maritime construction and industrial cybersecurity limit deployment velocity for integrated automation projects.
Strategic Opportunities
- Vietnamese Greenfield Yards:New shipbuilding zones in Ba Ria-Vung Tau and Hai Phong offer clean-slate digital infrastructure without legacy system migration burdens.
- Carbon Accounting Integration:China's dual carbon goals and South Korea's K-ETS compliance frameworks create demand for energy monitoring modules that track vessel lifecycle emissions.
- Cloud-Native Fleet Management:Multi-yard operators in Singapore and Hong Kong seek centralized engineering data platforms to coordinate construction across dispersed facilities.
Industry Challenges
- Interoperability Standard Delays:Japan's METI smart shipbuilding roadmaps and competing Korean data protocols have stalled unified file formats for hull design exchange between keiretsu networks.
- OT-IT Convergence Risks:Connected welding robots and crane systems expose yards to ransomware targeting operational technology networks with limited security segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Shipyard Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Maintenance, Support Technology: AI, IoT, Cloud Computing, Big Data End User: Shipbuilders, Fleet Operators, Maintenance Providers, Contractors Application: Vessel Design, Production Planning, Operations Management, Quality Control |
| Companies Covered | Dassault Systèmes, SAP, Siemens, Hexagon, Accenture, Wärtsilä, AVEVA, Hanwha Systems, BAE Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Shipyard Market Evolving Landscape
Digital twin architectures are expanding from design-phase simulation into full production lifecycle management, compressing the gap between virtual commissioning and physical hull assembly.
Digital twin technology is expanding into real-time production control systems that synchronize robotic welding stations with material flow logistics. Korean heavy builders are deploying these platforms across Ulsan and Geoje facilities to compress block assembly schedules. The technology is expanding into predictive drydock scheduling, enabling yards to promise delivery windows with tighter confidence intervals.
Japan's METI smart shipbuilding roadmaps now mandate interoperable data standards across keiretsu supplier networks, forcing tier-one yards to retrofit legacy PLM systems. The policy is accelerating API-based integration between hull design software and subcontractor ERP platforms. Small and mid-tier suppliers in Nagasaki and Kure are responding by adopting cloud-hosted collaboration tools to maintain procurement eligibility.
Buyer contracting preferences are rotating from perpetual software licenses toward subscription-based implementation-and-maintenance bundles. Fleet operators in Singapore and Hong Kong are consolidating vendor relationships to reduce integration complexity across multiple yard sites. This shift is most visible among container line customers seeking standardized data formats for vessel handover documentation.
Asia-Pacific Digital Shipyard Market Segmentation
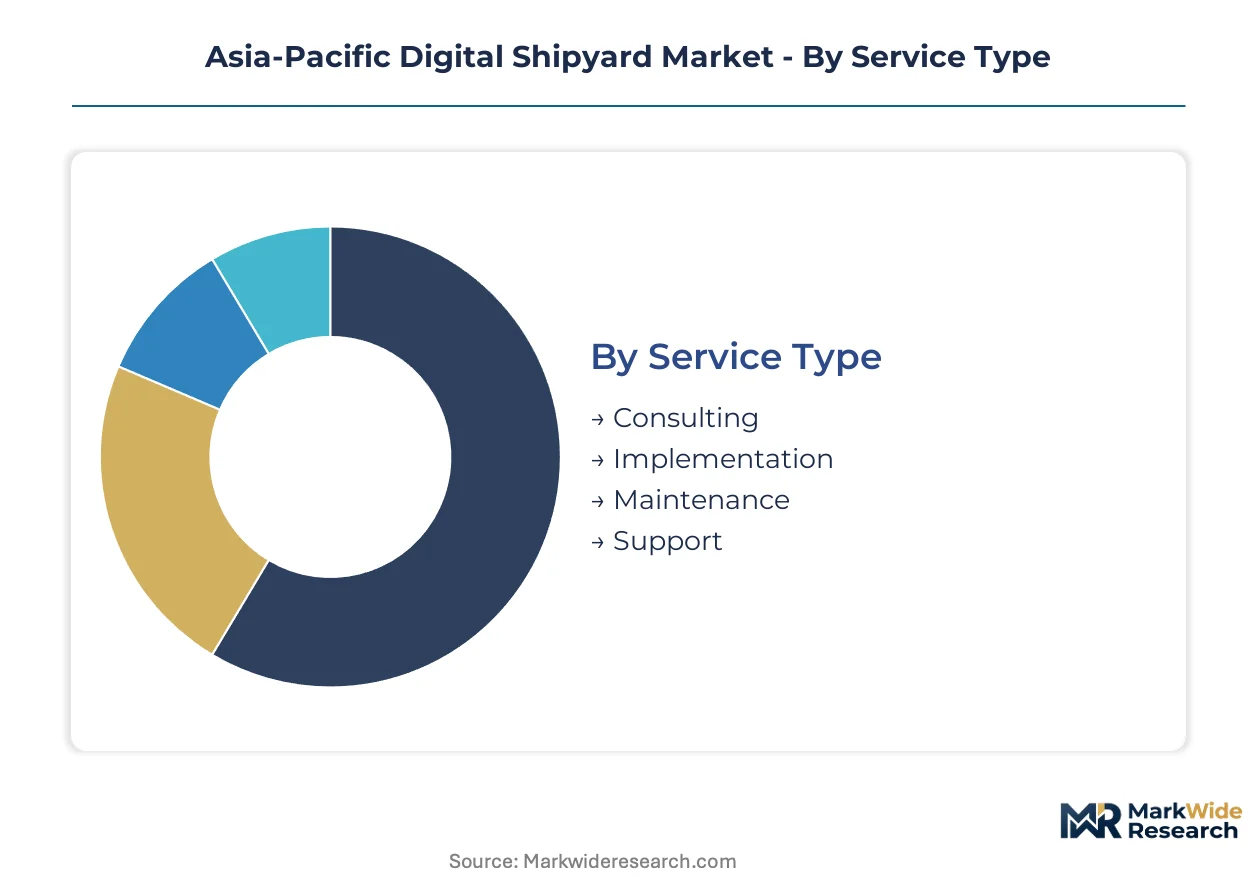
Segmentation in the Asia-Pacific Digital Shipyard Market reveals divergent procurement patterns between naval defense programs and commercial vessel construction. Service bundling preferences, technology readiness levels, and compliance mandates vary sharply across South Korean heavy builders, Japanese keiretsu networks, and Southeast Asian greenfield yards.
Service Type:
Customization intensity spans from standardized support packages to deeply tailored implementation engagements, with procurement patterns reflecting yard maturity and fleet complexity.
- Implementation:Full-stack deployment of digital twin infrastructure, IoT sensor networks, and production control systems dominates initial procurement cycles. South Korean heavy builders in Ulsan and Geoje anchor regional demand through multi-year platform rollouts mandated by MIIT and KOSHA compliance frameworks.
- Maintenance:Recurring service contracts for predictive analytics platforms and cybersecurity updates generate the stickiest revenue streams. Japanese keiretsu suppliers in Nagasaki and Kure prioritize long-term maintenance partnerships to preserve interoperability across tiered subcontractor networks.
- Consulting:Strategic advisory for digital transformation roadmaps and legacy system migration planning.
- Support:Tiered helpdesk and technical assistance for deployed shipyard automation platforms.
Most installed capacity flows through Implementation. Expansion is steepest in Maintenance.
Technology:
Investment priority correlates with measurable throughput gains, creating a clear hierarchy from proven automation tools to emerging analytics layers.
- AI:Machine vision systems for real-time hull welding quality control and predictive drydock scheduling compress construction timelines. South Korean yards deploy AI-driven production planning to reduce block assembly schedules across Ulsan-Gyeongsang facilities.
- IoT:Sensor networks monitoring crane loads, robotic welding stations, and material flow logistics enable condition-based maintenance. China's dual carbon goals accelerate IoT deployment for energy monitoring and emissions tracking in state-owned commercial yards.
- Cloud Computing:Centralized engineering data platforms for multi-yard fleet operators in Singapore and Hong Kong.
- Big Data:Historical performance analytics for vessel lifecycle optimization and carbon accounting integration.
Capital deployment concentrates in AI. Technology adoption is climbing fastest in IoT.
End User:
Buyer sophistication determines contract structure, from single-site software licenses to enterprise-wide implementation-and-maintenance bundles.
- Shipbuilders:Tier-one construction yards in South Korea and Japan drive demand for integrated digital twin platforms spanning design through commissioning. Hyundai Heavy Industries and Samsung Heavy Industries anchor regional procurement through defense and commercial vessel programs.
- Fleet Operators:Container lines and bulk carriers in Singapore and Hong Kong seek standardized data formats for vessel handover documentation and centralized fleet management.
- Maintenance Providers:Third-party repair yards and drydock operators adopting predictive maintenance modules.
- Contractors:Specialized subcontractors in Vietnamese greenfield zones deploying cloud-hosted collaboration tools.
Procurement volume centers on Shipbuilders. User category gaining share fastest is Fleet Operators.
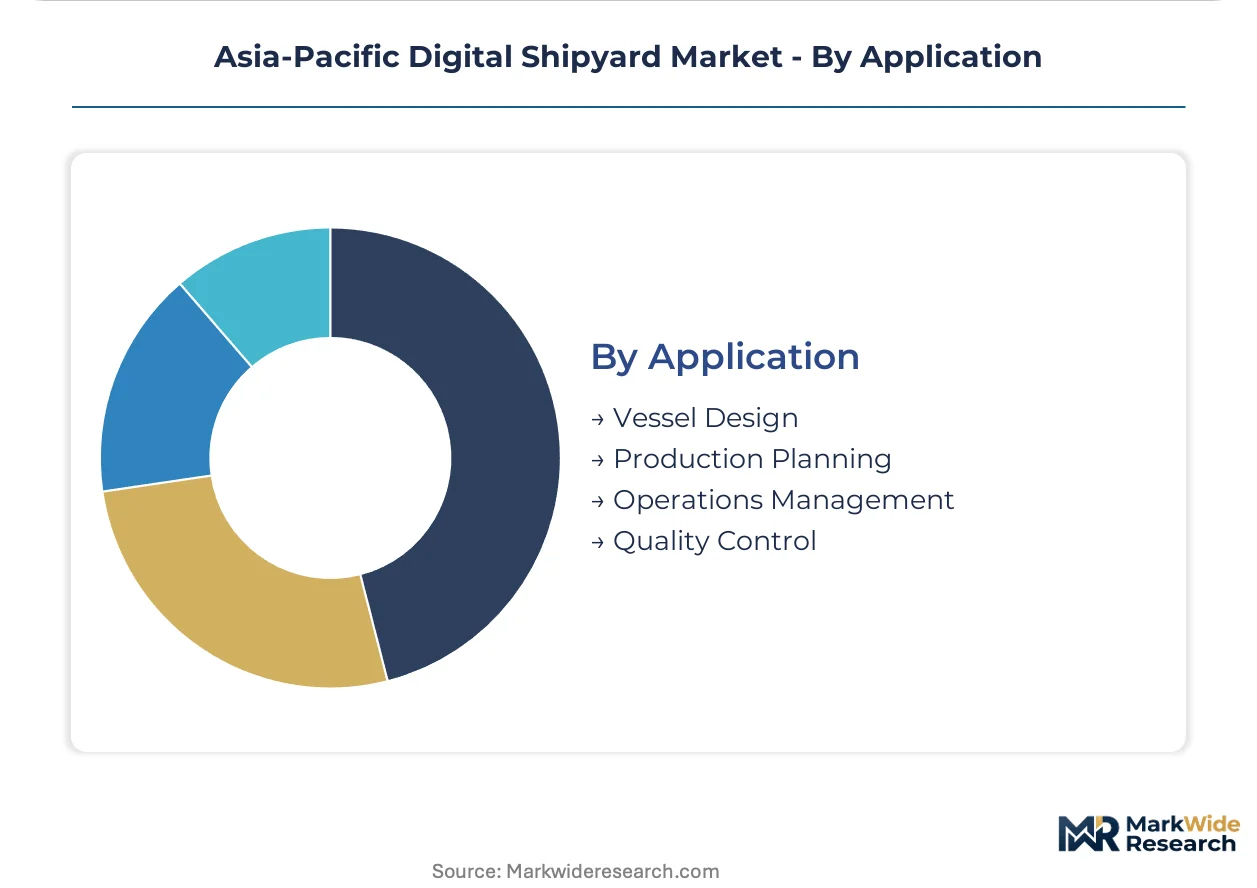
Application:
Functional deployment follows vessel complexity, with high-value naval programs demanding end-to-end integration and commercial fleets targeting point solutions.
- Production Planning:AI-driven scheduling algorithms synchronize robotic welding stations with material logistics, compressing turnaround times. Korean heavy builders deploy these systems across Ulsan and Geoje to meet compressed delivery windows for naval and commercial contracts.
- Vessel Design:Digital twin simulation platforms enable virtual commissioning before physical hull assembly. Japan's METI smart shipbuilding roadmaps mandate interoperable data standards, forcing tier-one yards to retrofit legacy PLM systems for keiretsu supplier coordination.
- Operations Management:Real-time yard logistics and resource allocation for multi-facility operators.
- Quality Control:Automated hull inspection and weld verification systems reducing rework rates.
Deployment density peaks in Production Planning. Application segment expanding most quickly is Vessel Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding digitization originated in Japanese keiretsu networks during the 1980s, migrated to South Korean heavy industrial zones in the 1990s, and now accelerates across Southeast Asian greenfield developments responding to naval and commercial fleet expansion.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor demand through defense frigate programs and LNG carrier construction. KOSHA occupational safety frameworks mandate automated monitoring systems across Ulsan-Gyeongsang facilities. The Busan-Ulsan corridor hosts the densest concentration of AI-driven welding quality deployments in the region.
China
State-owned commercial yards and private naval contractors drive simultaneous energy efficiency and automation upgrades. MIIT smart manufacturing directives compel digital twin adoption across heavy industry, including shipbuilding. The Yangtze River Delta shipbuilding clusters in Jiangsu and Zhejiang provinces compress adoption timelines for IoT-enabled yard operations.
Japan
Keiretsu supplier networks require interoperable data standards to maintain procurement eligibility with tier-one builders. METI smart shipbuilding roadmaps mandate API-based integration between hull design software and subcontractor platforms. Nagasaki and Kure industrial zones retrofit legacy PLM systems to preserve keiretsu coordination.
Vietnam
New shipbuilding zones in Ba Ria-Vung Tau and Hai Phong attract foreign joint ventures seeking clean-slate digital infrastructure. The country's national industrial development programs prioritize technology transfer partnerships with Korean and Japanese builders. Vietnamese greenfield yards avoid legacy system migration burdens that constrain retrofit investments elsewhere.
Singapore
Container lines and bulk carriers headquartered in Singapore demand standardized data formats for vessel handover documentation. The Maritime and Port Authority promotes digital port-shipyard integration standards. Multi-yard fleet operators seek centralized engineering data platforms to coordinate construction across dispersed Asian facilities.
Asia-Pacific Digital Shipyard Market Competitive Landscape
Premium-margin players sit above commodity-margin players across implementation complexity, with integrated platform vendors commanding higher contract values than point-solution specialists. The vendor base clusters around three strategic archetypes: European industrial software conglomerates with digital twin portfolios, Korean defense-focused automation specialists, and cloud-native engineering data management providers. Consolidation pressure favors acquisition of IoT sensor networks and AI welding analytics startups by established yard automation vendors.
Within the European-Asian technology transfer tier, Siemens and AVEVA occupy positions as archetypal platform providers, while Hanwha Systems exemplifies the defense-centric domestic specialist model. These three companies represent contrasting strategic postures: Siemens leverages cross-industrial digital twin expertise, AVEVA targets multi-yard fleet operators with cloud-native architectures, and Hanwha Systems sustains Korean market presence through naval shipyard automation platforms.
| Leading Market Players |
|---|
| Dassault Systèmes |
| SAP |
| Siemens |
| Hexagon |
| Accenture |
| Wärtsilä |
| AVEVA |
| Hanwha Systems |
| BAE Systems |
| Others |
Value Network & Pricing Analysis
Tier-one South Korean heavy builders in Ulsan and Geoje anchor procurement volume through multi-year implementation-and-maintenance bundles, compressing vendor margins and favoring subscription-based SaaS pricing over perpetual software licenses. This buyer concentration shifts pricing power toward yards capable of consolidating vendor relationships across defense frigate and LNG carrier programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-driven welding quality platforms from basic IoT sensor networks and legacy CAD middleware. Price differentiation rests on certification grade under KOSHA occupational safety frameworks and customization depth for keiretsu supplier integration. Cost compression in the economy tier intensifies as Vietnamese greenfield yards bypass legacy migration burdens and negotiate clean-slate deployments. Fleet operators in Singapore and Hong Kong demonstrate lowest price sensitivity due to multi-yard coordination requirements, while small Japanese subcontractors in Nagasaki face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Busan and Shanghai coordinate hub-and-spoke delivery of industrial IoT sensors, robotic welding controllers, and cloud computing infrastructure to yard sites across South Korea, China, and Japan. Component dependencies draw from Taiwanese semiconductor foundries for edge computing hardware, German industrial automation suppliers for motion control systems, and domestic Korean vendors for defense-grade cybersecurity modules. Single-source vulnerability concentrates in machine vision cameras for hull inspection systems. Distribution runs through systems integrators anchored in the Busan-Ulsan corridor and Yangtze River Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
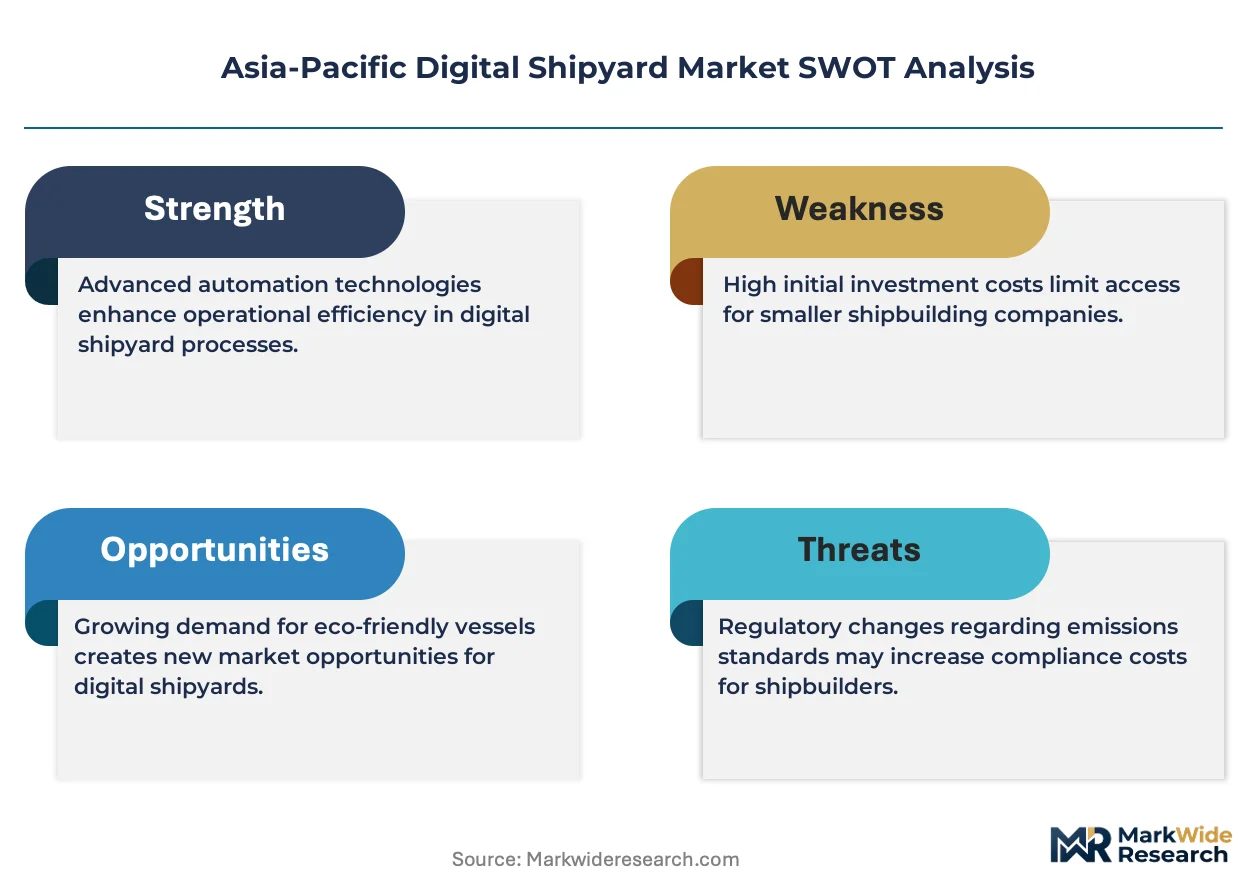
This market functions as a regulatory compounder where MIIT smart manufacturing mandates and METI interoperability roadmaps generate sustained demand for yard digitization regardless of commercial vessel order cycles.
For Market Incumbents: Cement defensive moats by acquiring AI welding analytics startups before Korean defense contractors internalize predictive quality capabilities, and deepen backward integration into IoT sensor manufacturing to offset margin pressure from subscription pricing transitions. Threat substitution looms from cloud-native engineering platforms displacing on-premise digital twin deployments. For New Entrants and Emerging Players: The mid-market price-point gap between Siemens-AVEVA enterprise platforms and localized Korean automation vendors presents viable white-space for cloud-native fleet management tools targeting Singapore-based multi-yard operators. Vietnamese greenfield yards in Ba Ria-Vung Tau offer the most penetrable geography due to absence of legacy PLM retrofit requirements. Go-to-market should emphasize API-first interoperability to satisfy METI data standard mandates. For Investors and Strategic Acquirers: Defense-focused industrial conglomerates represent the most active acquirer category in this space, seeking shipyard automation capabilities to complement naval platform manufacturing. Long-term viability hinges on regulatory durability across China's dual carbon enforcement and South Korea's K-ETS compliance expansion. Acquisition targets should display OT-IT convergence expertise with established cybersecurity certification. Watch for MIIT enforcement acceleration against state-owned yards missing digital twin adoption deadlines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-based connectivity satisfies METI interoperability mandates for keiretsu supplier networks. |
| Acquisition of Specialist Firm | Machine vision startups compress block assembly schedules for Hyundai Heavy Industries. |
| Geographic Expansion | Vietnamese greenfield zones in Hai Phong bypass legacy system migration costs entirely. |
| Strategic Partnership | Technology transfer agreements with Korean builders accelerate Vietnamese yard digitization. |
| Product Launch | Carbon accounting modules align with South Korea's K-ETS compliance framework requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with shipyard automation directors, naval procurement officers, systems integration engineers, and cloud platform architects with secondary validation against MIIT policy circulars, METI smart shipbuilding roadmaps, KOSHA safety framework updates, and customs data for industrial IoT equipment imports. Bottom-up triangulation across yard-level deployment data and top-down reconciliation against regional shipbuilding output statistics anchored value estimates.
Segment-weighting approaches distributed value across service type, technology, end user, and application dimensions, with additional modeling of compliance-driven adoption timelines under Chinese and Korean regulatory frameworks. CAGRs were derived from fitted growth curves applied to disclosed platform rollout schedules and naval procurement program milestones, incorporating energy efficiency retrofit acceleration under dual carbon enforcement.
Caveats apply where cybersecurity certification fragmentation or interoperability standard delays could materially shift the outlook for multi-yard operator deployments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Hatch Covers Market