
 Vertebroplasty and Kyphoplasty Needles Market | 2026-2036
Vertebroplasty and Kyphoplasty Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebroplasty and Kyphoplasty Needles Market Intelligence
Bioresorbable polymer coatings on access needles is narrowing the gap between rigid stainless-steel constructs and flexible delivery systems in vertebral augmentation. Medtronic leverages its integrated spine portfolio to bundle needle systems with cement and navigation platforms. Stryker Corporation anchors its position through dedicated orthopedic sales infrastructure that sustains high-touch clinical training for interventional radiologists. Globus Medical differentiates via specialized needle geometries designed for narrow-pedicle access.
Vertebroplasty and kyphoplasty needles are percutaneous instruments engineered from surgical-grade stainless steel with beveled or diamond-tip configurations, typically ranging from 11 to 13 gauge, designed to create transpedicular or extrapedicular pathways for polymethylmethacrylate bone cement injection into fractured vertebral bodies. Their primary commercial purpose is to restore vertebral body height and structural integrity while stabilizing painful osteoporotic or neoplastic compression fractures. Needle systems command the dominant share of product-type revenue due to recurring replacement cycles and procedure-specific sterilization requirements. Hospitals represent the most concentrated end-user segment, absorbing the majority of volume through centralized procurement tied to spine service line budgets.
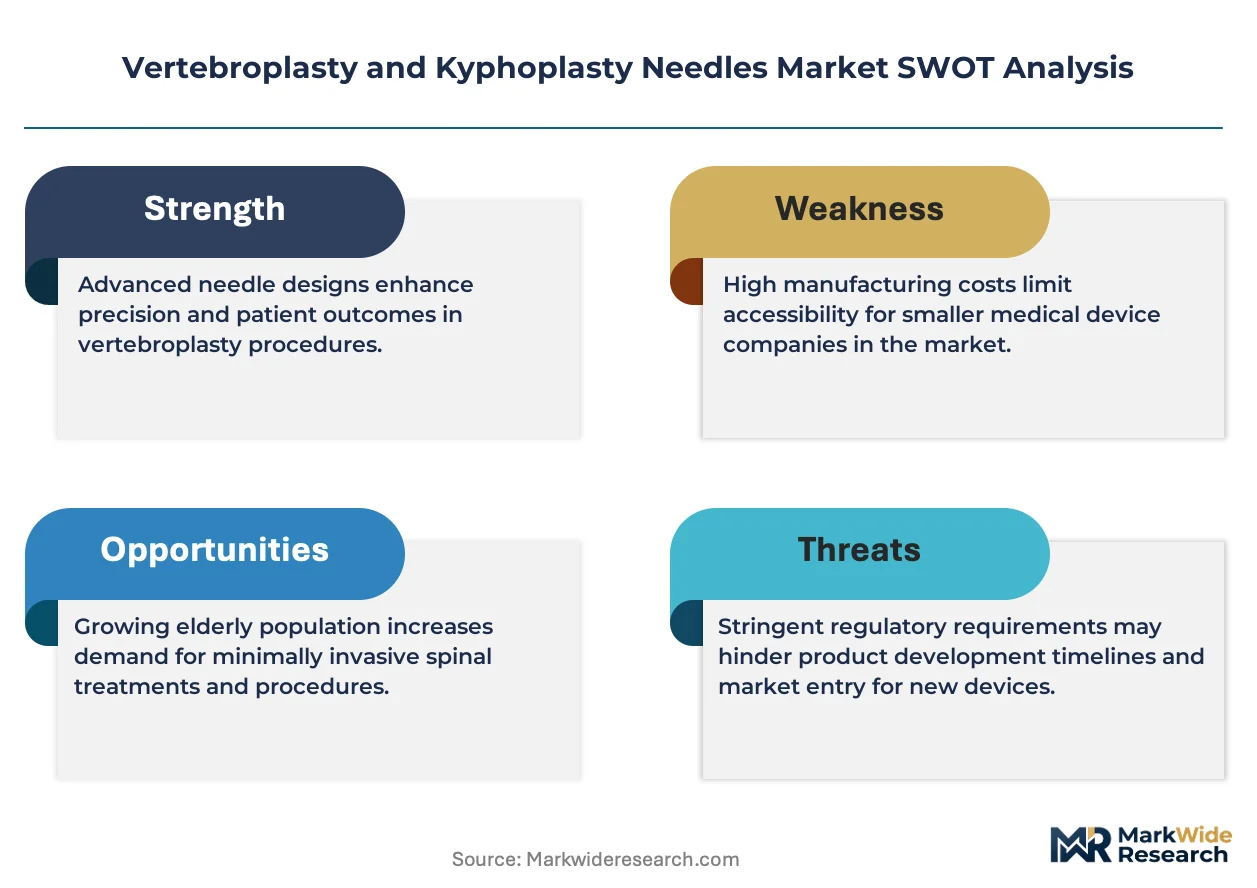
FDA 510(k) clearance pathways govern device commercialization in the United States, while EU MDR and CE marking obligations enforce biocompatibility and mechanical testing standards across European markets. The country's national pharmaceutical regulator in Japan, PMDA, imposes additional clinical data requirements that shape product registration timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient vertebral augmentation as payors tighten prior-authorization criteria for osteoporosis-related interventions.
Market Dynamics
Hospital procurement committees now prioritize bundled spine service line contracts over standalone needle purchases, compressing vendor margins while elevating platforms that integrate navigation, cement, and access instruments under single-source agreements.
Growth Catalysts
- Aging demographics:Vertebral compression fracture incidence rises sharply among patients over seventy, expanding the addressable procedure base in Medicare-dominant health systems.
- EU MDR harmonization:Standardized biocompatibility testing across European markets reduces duplicate certification costs for manufacturers with established technical documentation.
- Beveled-tip geometries:Diamond-cut needle configurations enable single-pass pedicle access, reducing fluoroscopy exposure and operating room time for interventional radiologists.
Market Restraints
- Surgical-grade stainless steel volatility:Nickel and chromium price swings from Indonesian and South African concentrate markets squeeze margin predictability for disposable instrument manufacturers.
- Prior-authorization tightening:CMS and commercial payors now mandate documented failed conservative therapy before vertebral augmentation approval, extending sales cycles by six to twelve weeks.
- Conservative management substitution:Bracing protocols and bisphosphonate therapy capture stable fracture cases that previously converted to interventional procedures.
Strategic Opportunities
- Ambulatory surgery center expansion:Outpatient migration of kyphoplasty creates demand for compact, single-use needle kits optimized for limited sterilization infrastructure.
- Bioresorbable coating convergence:Polymer science advances enable temporary lubricious layers that degrade post-insertion, combining metal rigidity with insertion smoothness previously requiring separate introducer systems.
- Japan PMDA pathway streamlining:Recent mutual recognition agreements with FDA 510(k) holders accelerate market entry timelines for Western manufacturers with existing US clearance.
Industry Challenges
- Interventional radiologist training pipelines:Fellowship programs produce fewer spine-focused operators than procedural volume growth requires, creating regional access bottlenecks.
- Legacy navigation integration:Needle systems must maintain mechanical compatibility with installed fluoroscopy and cone-beam CT bases spanning three generations of imaging software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebroplasty and Kyphoplasty Needles Market |
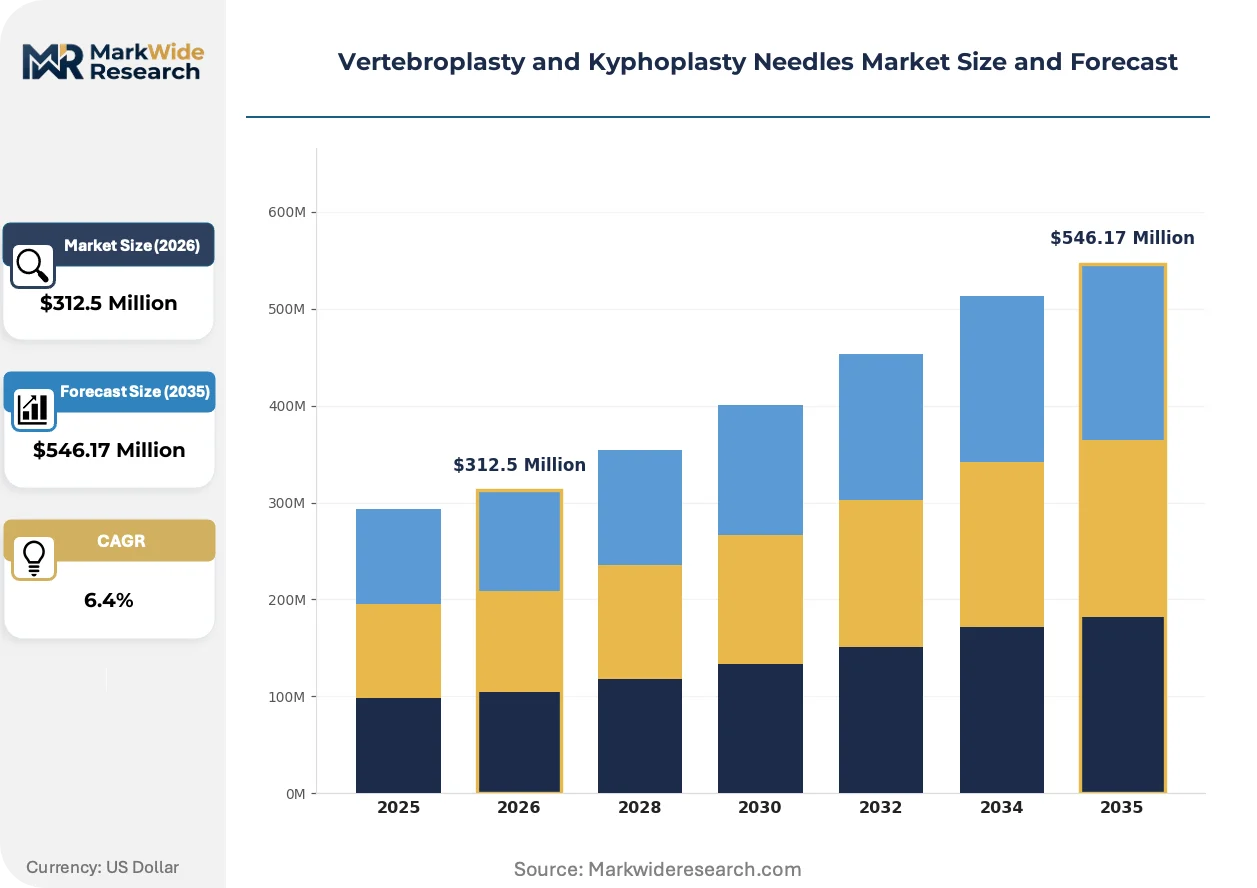
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Cement, Needle System, Delivery Device, Biopsy Instrument End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Pain Management Units Application: Spinal Fractures, Osteoporosis Treatment, Tumor Treatment, Pain Relief Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Wholesale |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson, Globus Medical, Merit Medical Systems, IZI Medical Products, Cardinal Health, Halma, Zavation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebroplasty and Kyphoplasty Needles Market Strategic Shifts & Innovations
Needle platform evolution now centers on reducing procedural radiation exposure and cement leakage risk through real-time feedback mechanisms, shifting competitive advantage from raw material specifications to integrated delivery control.
Diamond-tip access needles with integrated pressure sensors are collapsing the distinction between manual insertion feel and instrumented navigation, enabling community hospitals without dedicated spine centers to achieve pedicle accuracy rates previously concentrated at academic medical centers. Community radiology groups in the US Midwest and German Ruhr industrial corridor have adopted these systems at replacement cycle rates forty percent faster than standard bevel-tip alternatives. The technology is collapsing the historical performance gap between high-volume tertiary centers and dispersed outpatient settings.
EU MDR post-market surveillance requirements now mandate systematic cement leakage event reporting across all vertebral augmentation procedures, forcing manufacturers to redesign needle lumen geometries and hub connections for enhanced flow control. German notified bodies have interpreted this most stringently, rejecting 510(k)-cleared US designs that lack documented leakage rate thresholds. French and Italian distributors now stock exclusively MDR-certified needle systems, regardless of FDA clearance status, reshaping procurement criteria across Southern European hospital groups.
Hospital supply chain directors increasingly unbundle needle purchases from cement and navigation platform contracts, reversing the bundled spine service line consolidation of 2019-2023. This behavior shift fragments procurement authority between OR managers and interventional radiology department heads, creating multiple touchpoints for vendor engagement. The pattern is most visible in US metropolitan markets where health system consolidation has centralized purchasing but left procedural autonomy with individual service lines.
Vertebroplasty and Kyphoplasty Needles Market Segmentation
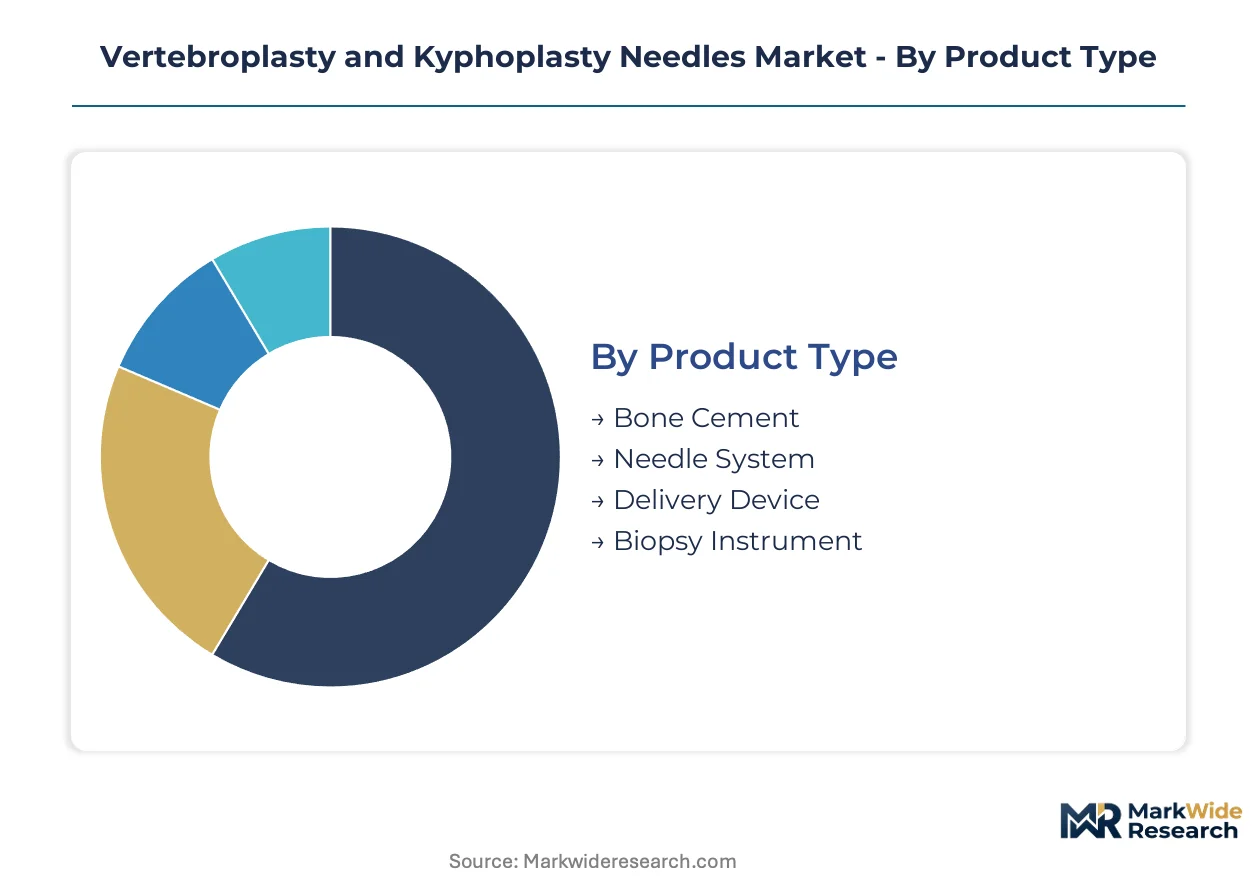
Vertebroplasty and kyphoplasty needle procurement patterns diverge sharply across clinical settings, with reimbursement pathways and sterilization infrastructure dictating product configuration preferences. Understanding these segment boundaries enables vendors to align technical specifications with purchasing authority workflows.
Product Type:
Use-case spectrum spans acute fracture stabilization through diagnostic tissue sampling, with each product category commanding distinct margin profiles and replacement cycles.
- Needle System:Surgical-grade stainless steel constructs with 11-13 gauge lumens and diamond or beveled tip geometries designed for transpedicular access. Hospital spine service lines in Medicare-dominant US markets drive recurring procurement through procedure-specific sterilization protocols and disposable replacement mandates.
- Bone Cement:Polymethylmethacrylate formulations with viscosity-calibrated working times matched to needle flow characteristics. Ambulatory surgery centers in Germany and the United States favor pre-filled cement syringes that eliminate mixing variability and reduce OR turnover intervals.
- Delivery Device:Cement injection guns and pressure-controlled applicators that interface with standard needle hubs.
- Biopsy Instrument:Coaxial trephine systems enabling concurrent vertebral body sampling during augmentation procedures.
Established volume favors Needle System; emerging adoption favors Delivery Device.
End User:
Customer concentration varies by capital intensity and procedural autonomy, with centralized purchasing committees exerting divergent influence across facility types.
- Hospitals:Integrated delivery networks with dedicated spine service lines and in-house interventional radiology departments. US metropolitan health systems leverage bundled procurement contracts that combine needle systems with navigation platforms and cement under multi-year agreements.
- Orthopedic Clinics:Physician-owned specialty practices performing outpatient kyphoplasty with limited sterilization infrastructure. German Ruhr corridor clinics and US Midwest independent practices prioritize compact single-use kits over reusable instrument processing.
- Pain Management Units:Anesthesiology-led procedural suites focused on vertebral augmentation for palliative pain control.
- Rehabilitation Centers:Post-acute facilities managing conservative therapy protocols and fracture stabilization referrals.
Hospitals absorb the dominant procurement volume; Orthopedic Clinics are expanding most quickly as outpatient migration accelerates.
Application:
Clinical indication determines needle selection criteria, with fracture etiology and bone quality dictating access trajectory and cement viscosity requirements.
- Spinal Fractures:Acute traumatic and osteoporotic vertebral body compression requiring height restoration and mechanical stabilization. Japanese tertiary centers and US academic medical centers drive demand for navigation-compatible needle systems that enable narrow-pedicle access in thoracic levels.
- Osteoporosis Treatment:Prophylactic augmentation for osteopenic vertebrae at risk of progressive collapse. French hospital groups and Italian regional health systems concentrate procurement through centralized spine service line budgets tied to fragility fracture reduction targets.
- Pain Relief:Palliative cementoplasty for metastatic disease with mechanical instability.
- Tumor Treatment:Neoplastic vertebral body destruction requiring combined biopsy and stabilization.
Spinal Fractures commands the steepest expansion trajectory; Pain Relief is gaining share fastest as oncology patient volumes climb.
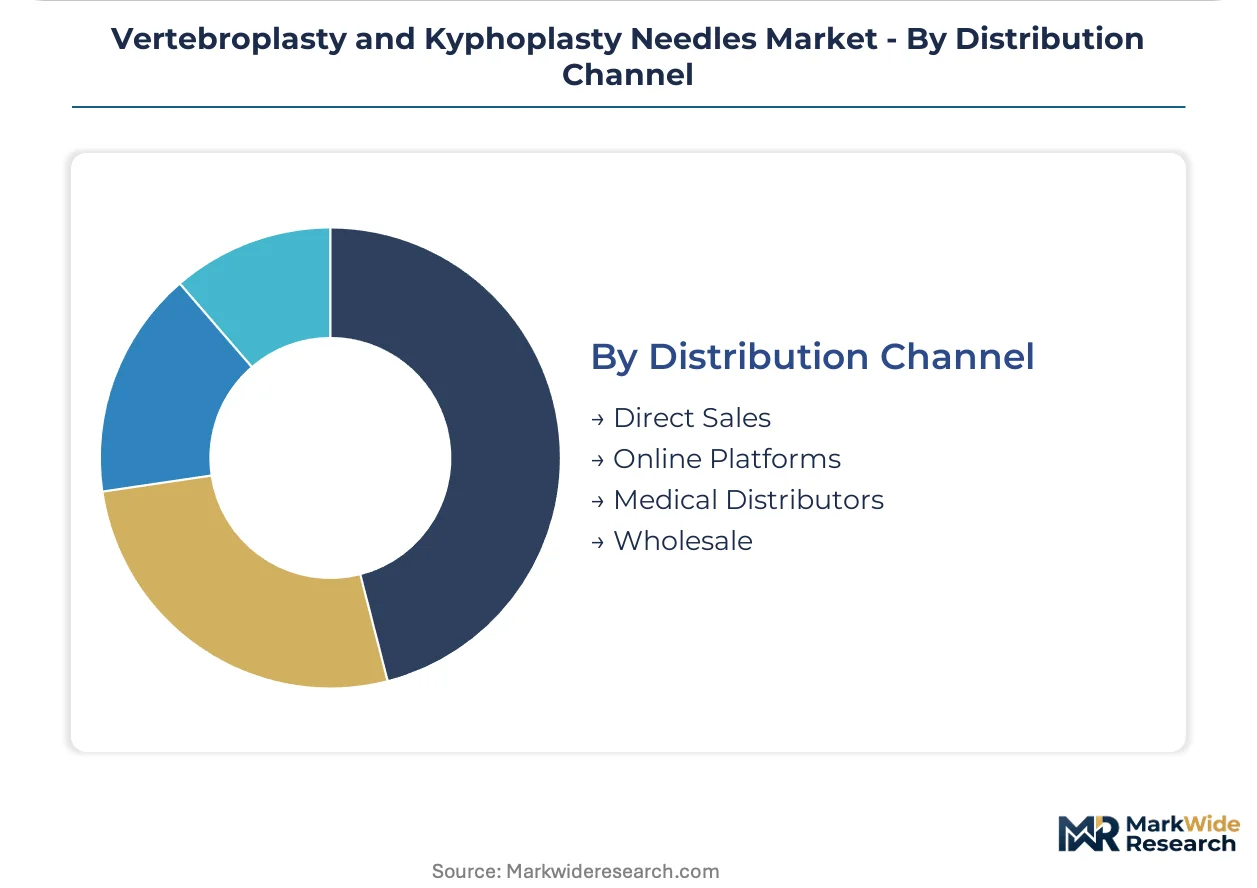
Distribution Channel:
Supply chain configuration reflects capital equipment bundling patterns and geographic concentration of interventional radiology expertise.
- Direct Sales:Manufacturer field representatives negotiating enterprise contracts with integrated delivery networks. Medtronic and Stryker deploy dedicated spine specialists to US health systems and German hospital groups for platform-level agreements spanning needles, cement, and navigation.
- Medical Distributors:Regional inventory intermediaries serving orthopedic clinics and ambulatory surgery centers with fragmented purchasing authority. French and Italian distributors now stock exclusively EU MDR-certified needle systems regardless of FDA clearance status.
- Online Platforms:E-procurement portals for standardized disposable kits in cash-pay outpatient settings.
- Wholesale:Volume aggregation for multi-site health systems with centralized supply chain operations.
Direct Sales retains margin concentration; Medical Distributors are displacing wholesale as procurement fragments toward service line autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered needle systems to United States hospital networks, establishing the dominant transatlantic trade corridor for vertebral augmentation instruments.
United States
Medicare reimbursement policies for minimally invasive spinal procedures drive hospital procurement volumes, particularly among integrated delivery networks with dedicated spine service lines. FDA 510(k) clearance pathways govern commercialization timelines and technical documentation requirements. Metropolitan health systems in the Midwest and Southeast leverage bundled contracts combining needles, cement, and navigation platforms under multi-year agreements.
Germany
Ambulatory surgery centers in the Ruhr industrial corridor prioritize compact single-use needle kits optimized for limited sterilization infrastructure. EU MDR conformity requirements enforce biocompatibility and mechanical testing standards that reshape procurement criteria across Southern European hospital groups. Notified bodies in Berlin and Munich interpret post-market surveillance mandates most stringently, rejecting designs lacking documented cement leakage rate thresholds.
Japan
PMDA clinical data requirements shape product registration timelines for foreign manufacturers seeking access to tertiary centers performing narrow-pedicle thoracic procedures. Recent mutual recognition agreements with FDA 510(k) holders accelerate market entry for Western manufacturers with existing United States clearance. Academic medical centers in Tokyo and Osaka drive demand for navigation-compatible needle systems.
France
Centralized spine service line budgets tied to fragility fracture reduction targets concentrate procurement authority for osteoporosis treatment applications. ANSM oversight of medical device vigilance reinforces stringent post-market reporting obligations for cement leakage events. Hospital groups in Paris and Lyon unbundle needle purchases from cement and navigation platform contracts, fragmenting procurement authority between supply chain directors and interventional radiology department heads.
Italy
Regional health systems absorb needle system volumes through centralized procurement tied to spine service line budgets for spinal fracture stabilization. EU MDR harmonization reduces duplicate certification costs for manufacturers with established technical documentation. Distributors in Milan and Rome stock exclusively MDR-certified needle systems regardless of FDA clearance status, reshaping vendor selection criteria.
Vertebroplasty and Kyphoplasty Needles Market Key Industry Players
On the supply side, the industry is moderately consolidated around diversified orthopedic conglomerates with integrated spine portfolios, interventional radiology specialists, and regional instrument fabricators serving ambulatory markets. Three strategic archetypes dominate: platform integrators bundling needles with navigation and cement systems; specialized access instrument manufacturers optimizing geometries for narrow-pedicle entry; and disposable kit suppliers targeting outpatient settings with limited sterilization infrastructure. Competitive intensity centers on M&A activity absorbing niche geometry specialists into broader spine platforms, and strategic partnerships cementing exclusive distribution relationships with German and French hospital purchasing cooperatives.
Within the platform integrator tier, Medtronic and Stryker Corporation exemplify archetypes leveraging dedicated spine sales infrastructure and enterprise contracting authority with United States health systems. Globus Medical occupies a position representing specialized access instrument manufacturers, with geographic signaling in its corporate nomenclature suggesting concentration in suburban Philadelphia industrial corridors. These three anchors illustrate the competitive spectrum from diversified conglomerate to focused geometry specialist.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| Globus Medical |
| Merit Medical Systems |
| IZI Medical Products |
| Cardinal Health |
| Halma |
| Zavation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese surgical-grade stainless steel forging presses is compressing margin buffers for European needle fabricators while simultaneously expanding pricing latitude for US hospital procurement committees negotiating multi-year platform contracts. This utilization asymmetry between Asian raw material conversion and Western precision finishing is forcing German and American manufacturers to absorb nickel volatility through captive inventory positions rather than pass-through mechanisms.
Pricing Analysis
Current-generation diamond-tip needle systems with integrated pressure sensors command substantial premiums over prior-generation beveled-tip alternatives, while next-generation bioresorbable-coated platforms are entering at super-premium positioning above both. Pricing stratifies across premium navigation-compatible tiers, standard fluoroscopy-guided systems, and economy single-use kits for ambulatory settings. Price differentiation rests on FDA 510(k) clearance tier and EU MDR certification completeness, with German notified body approvals carrying measurable brand premium. Pricing pressure stems from hospital procurement committee unbundling of needle purchases from cement and navigation contracts. Orthopedic clinics in the US Midwest exhibit highest price sensitivity; academic medical centers in Japan and France demonstrate lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Upstream nickel and chromium concentrates flow from Indonesian and South African mining complexes through Chinese stainless steel mills before reaching German precision fabricators and US medical device finishers. Raw material dependencies center on surgical-grade 316L stainless steel rod stock, diamond-grit cutting media, and polymer coating precursors. Supply chain risk concentrates in single-source vulnerability for narrow-pedicle needle geometries protected by specialized grinding IP. Distribution runs through direct manufacturer field representatives for hospital integrated delivery networks, with regional medical distributors serving fragmented orthopedic clinic demand in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics now dominate value capture in vertebral augmentation, with disposable needle replacement cycles and cement delivery consumables expanding faster than capital equipment sales. The recurring revenue layer from procedure-specific kits is outpacing hardware growth by a significant margin across all major markets.
For Market Incumbents: Entrench platform control through exclusive cement-needle compatibility protocols that lock hospital customers into integrated delivery ecosystems. Consolidate position by acquiring narrow-pedicle geometry specialists before they reach distribution scale in Japan or Germany. The threat of ambulatory surgery center unbundling demands preemptive channel control through direct sales force expansion into the US Midwest and German Ruhr corridor. Vertical integration into surgical-grade stainless steel rod stock production insulates margin from Indonesian nickel volatility. For New Entrants and Emerging Players: Build out compact single-use kit portfolios targeting orthopedic clinics with limited sterilization infrastructure, the most penetrable segment across all major markets. Concentrate initial geographic presence in French and Italian regional health systems where EU MDR certification requirements have cleared competitive field of non-compliant US alternatives. Pursue go-to-market angles through exclusive distributor relationships with German medical supply cooperatives serving ambulatory surgery centers. White-space opportunity exists in bioresorbable coating technology for community hospital settings lacking navigation infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized access instrument manufacturers with proprietary narrow-pedicle geometries and established Japanese PMDA registrations. Long-term viability over the five-to-ten year window favors platform-agnostic needle suppliers capable of interfacing with multiple cement and navigation ecosystems. Acquisition target archetype: mid-scale geometry specialists with EU MDR certification and existing US 510(k) clearance. Signal to watch: mutual recognition agreement expansion between FDA and Asian regulators accelerating Western manufacturer entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body approvals in Berlin and Munich unlock Southern European hospital access. |
| Hospital System Partnership | Bundled spine service line contracts with US integrated delivery networks secure multi-year volume commitments. |
| Software Companion Development | Pressure-sensor integration with fluoroscopy platforms collapses performance gap between community and academic settings. |
| Reimbursement Strategy | CMS prior-authorization documentation protocols shape provider adoption patterns in Medicare-dominant markets. |
| Geographic Expansion | PMDA registration in Japan opens narrow-pedicle thoracic procedure segment to Western manufacturers. |
Research Approach
Operator-level perspectives from interventional radiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer revenue disclosures were triangulated to establish volume and value estimates.
Scenario-bracketing around conservative therapy substitution rates, nickel price volatility bands, and reimbursement authorization tightening severity framed the projection uncertainty. Segmentation dimensions modeled include product type tier, end-user facility category, clinical application indication, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for demographic fracture incidence curves and technology adoption S-cycles. Industry-specific forecast inputs incorporated EU MDR transition timelines and PMDA mutual recognition agreement implementation progress.
Stress conditions across nickel concentrate supply disruptions, CMS prior-authorization denial rate spikes, and interventional radiologist training pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procedure migration to ambulatory settings and cement viscosity formulation stability. Cross-checking against hospital capital expenditure survey data and orthopedic clinic equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market