
 Orthopedic Bone Cement and Casting Materials Market | 2026-2036
Orthopedic Bone Cement and Casting Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Bone Cement and Casting Materials Market Intelligence
Demand from specialized orthopedic clinics is bifurcating the market away from traditional large-volume hospital procurement. This shift reflects a broader trend towards outpatient and minimally invasive procedures that favor facilities with higher procedural specialization. Stryker Corporation leverages its extensive distribution network to serve both high-volume hospitals and smaller surgical centers. Zimmer Biomet Holdings differentiates through its focus on innovative bone cement formulations for complex joint arthroplasty.
Orthopedic bone cement is a biomaterial, typically composed of poly(methyl methacrylate) (PMMA), used to affix prostheses in joint arthroplasty procedures. Casting materials, including fiberglass and polymer tapes, provide rigid external immobilization for fractures and other orthopedic injuries. Bone cement products command a significant value share, driven by their critical role in high-cost joint replacement surgeries. The casting materials segment sees higher volume, with fiberglass tapes dominating due to their strength-to-weight ratio and ease of application.
Market access hinges on stringent regulatory approvals, with the US FDA's 510(k) pathway governing many devices. In parallel, the European Union's Medical Device Regulation (MDR) and Japan's PMDA impose rigorous biocompatibility and clinical evidence requirements. Future competitive advantage will depend on balancing the development of advanced bioactive materials against persistent healthcare cost-containment pressures from both public and private payers.
Market Dynamics
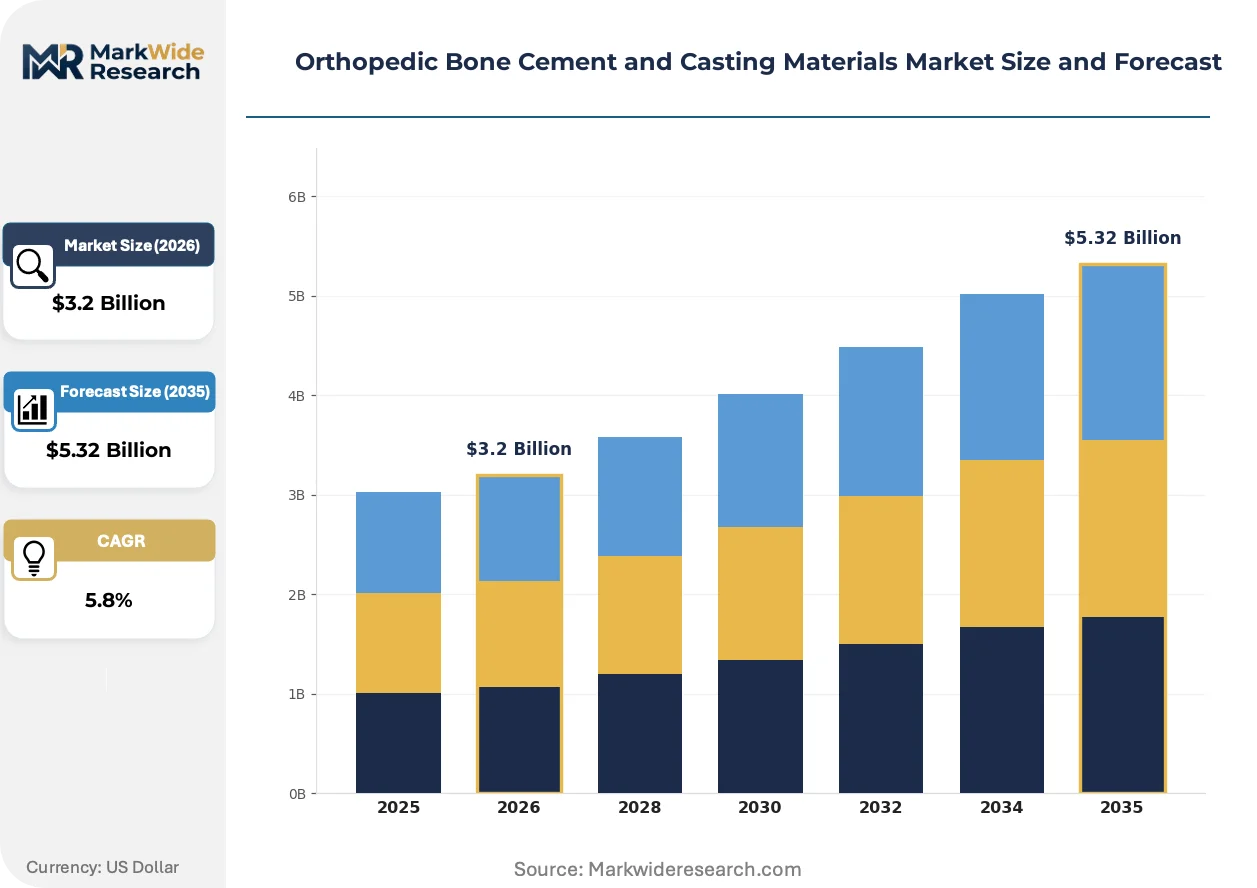
The central dynamic shaping the market is the increasing procedural volume in arthroplasty, driven by an aging global population and a higher prevalence of degenerative joint diseases. This demographic pressure interacts with a push towards value-based healthcare, creating demand for materials that improve long-term patient outcomes and reduce revision surgery rates.
Growth Catalysts
- Antibiotic-Loaded Cements:The development of bone cements incorporating antibiotics helps reduce the risk of periprosthetic joint infections, a significant driver of adoption in high-risk patient populations and revision surgeries.
- Ambulatory Surgical Centers:The rising number of procedures performed in specialized orthopedic clinics and ambulatory surgical centers expands the customer base beyond traditional hospitals, creating new sales channels.
- Aging Demographics:A growing elderly population in developed nations leads to a higher incidence of conditions like osteoarthritis and osteoporosis, directly increasing the volume of joint replacement and fracture management procedures.
Market Restraints
- Regulatory Scrutiny:Stringent and lengthy regulatory pathways, such as the EU's Medical Device Regulation (MDR) and the US FDA's 510(k) process, create high barriers to entry and increase time-to-market for new products.
- Payer Cost Pressures:Healthcare systems and private insurers increasingly exert cost-containment pressure, which can limit reimbursement for premium-priced materials and favor lower-cost alternatives, impacting manufacturer margins.
- Material-Related Complications:Potential complications associated with PMMA cements, such as aseptic loosening over time or thermal necrosis during curing, can limit their use in certain surgical scenarios or younger, more active patients.
Strategic Opportunities
- Bioactive Materials Development:There is significant opportunity in creating next-generation cements and casting materials that are bioactive or resorbable, actively promoting bone integration and healing rather than just providing inert structural support.
- Emerging Market Penetration:Expanding into healthcare markets in Asia and Latin America, where orthopedic surgical capacity is growing, offers a substantial avenue for volume growth as access to care improves.
- Expansion into Spinal Procedures:Adapting cement formulations for use in vertebral compression fractures through procedures like vertebroplasty and kyphoplasty represents a key growth vector beyond traditional joint arthroplasty.
Industry Challenges
- Surgical Technique Standardization:Ensuring consistent, optimal outcomes requires extensive surgeon training on material handling properties, such as mixing protocols and working times, to minimize application variability and associated risks.
- Sterile Supply Chain Management:Maintaining the integrity of biomaterials, particularly the liquid monomer and sterile powder components of bone cement kits, demands robust, temperature-controlled logistics and strict shelf-life management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Bone Cement and Casting Materials Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Cement, Casting Tape, Casting Padding, Orthopedic Cast Material: Poly(methyl methacrylate), Calcium Sulfate, Fiberglass, Polymer End User: Hospitals, Clinics, Rehabilitation Centers, Orthopedic Surgeons Application: Trauma Surgery, Joint Replacement, Sports Injuries, Spinal Surgery |
| Companies Covered | DePuy Synthes, 3M Health Care Ltd., Stryker Corporation, BSN Medical, DJO Global, Zimmer Biomet Holdings, Heraeus Holding GmbH, Exactech, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Bone Cement and Casting Materials Market Strategic Shifts & Innovations
Material science advancements are in a constant interplay with the practical demands of surgical efficiency and long-term clinical efficacy. This tension drives innovation toward products that offer superior mechanical properties, improved biological integration, and enhanced ease of use in the operating room, all while navigating a complex regulatory and reimbursement environment.
Antibiotic-eluting bone cements are designed to release drugs locally to prevent or treat periprosthetic joint infections. High-risk patient groups and complex revision arthroplasty procedures are seeing accelerated adoption of these materials. This technology is bifurcating the product landscape into standard cements for routine primary surgeries and premium, drug-loaded formulations for more challenging clinical cases.
The European Union's Medical Device Regulation (MDR) imposes significantly more rigorous requirements for clinical data and post-market surveillance on all medical devices. This regulatory shift increases the compliance burden and costs for manufacturers, particularly for those with legacy products. Consequently, companies are re-evaluating their portfolios, sometimes discontinuing older products that lack the robust clinical evidence now required for CE marking.
A discernible shift in purchasing patterns is moving away from large, centralized hospital procurement departments toward smaller, specialized ambulatory surgical centers. This trend disrupts traditional, high-volume distribution models, creating an opening for suppliers with agile logistics that can serve these lower-volume, higher-frequency accounts. This dynamic is most advanced in the United States and parts of Western Europe where outpatient procedures are becoming more common.
Orthopedic Bone Cement and Casting Materials Market Segmentation
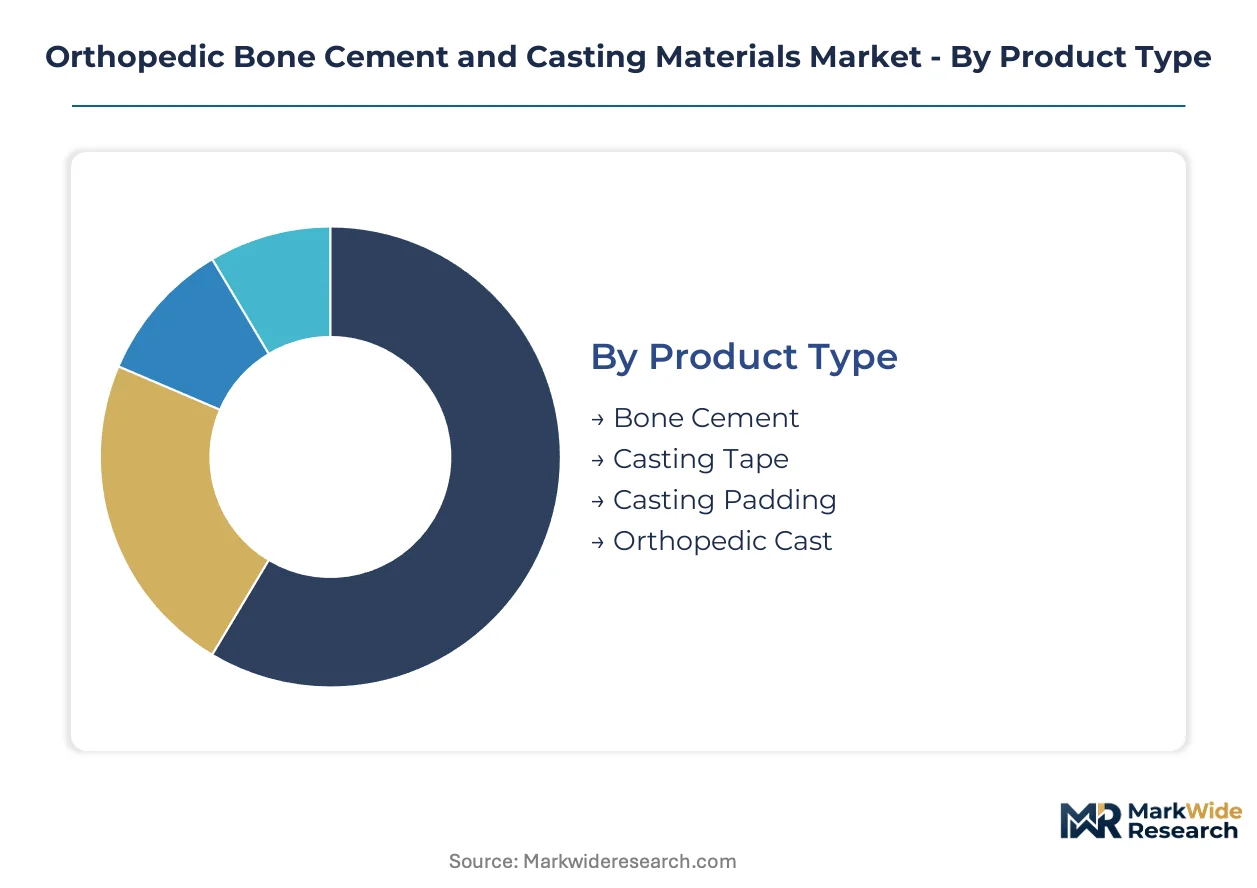
Understanding the distinct segments within the orthopedic bone cement and casting materials market is crucial for strategic planning. Each category exhibits unique demand drivers and competitive dynamics, influencing product development and market access strategies. Analyzing these segments reveals where value concentrates and how different material properties meet specific clinical needs.
Product Type:
Margin pools within the product type segment are concentrated in specialized, high-value materials that address complex surgical requirements.
- Bone Cement:This poly(methyl methacrylate) (PMMA) based biomaterial is essential for securing prosthetic implants in arthroplasty procedures. Demand in Germany is strong, driven by a high volume of joint replacement surgeries and the adoption of antibiotic-loaded variants to mitigate infection risks.
- Casting Tape:Composed primarily of fiberglass or polymer, these tapes provide rigid external immobilization for fractures and other orthopedic injuries. The United States exhibits significant volume demand due to the prevalence of sports injuries and trauma cases requiring non-surgical fixation.
- Casting Padding:Soft, protective materials placed under casting tapes to prevent skin irritation and pressure sores, enhancing patient comfort during immobilization.
- Orthopedic Cast:Traditional plaster of Paris or synthetic casts used for fracture stabilization and support, offering robust immobilization in various clinical settings.
The dominant share belongs to Bone Cement, while Casting Tape is closing the gap fastest.
Material:
The cost tier for materials varies significantly, with advanced polymers and PMMA formulations commanding higher prices due to their performance characteristics and regulatory burdens.
- Poly(methyl methacrylate):A widely used acrylic polymer forming the basis of most orthopedic bone cements, providing mechanical stability and fixation for prostheses. Its application in complex joint arthroplasty procedures in developed healthcare systems like Japan drives significant value.
- Fiberglass:Lightweight yet strong, fiberglass is a primary material for modern casting tapes, offering superior strength-to-weight ratio and water resistance compared to traditional plaster. Its widespread use in fracture management across Europe contributes to high volume.
- Calcium Sulfate:A biodegradable and biocompatible material used in some bone void fillers and as a component in certain bone cements, promoting bone regeneration.
- Polymer:A broad category encompassing various synthetic resins used in casting tapes and specialized orthopedic devices, offering flexibility and durability.
Fiberglass materials are expanding most quickly, driven by their versatility in casting applications.
End User:
The application focus of end users dictates procurement patterns, with specialized facilities requiring tailored product portfolios and distribution networks.
- Hospitals:Large medical institutions serving a broad patient base, performing a high volume of orthopedic surgeries including complex joint replacements and trauma interventions. These facilities represent a traditional high-volume purchasing channel.
- Clinics:Specialized orthopedic clinics and ambulatory surgical centers focusing on outpatient procedures and less complex cases, increasingly becoming a significant customer segment. These centers in the United States prioritize efficiency and specialized product access.
- Rehabilitation Centers:Facilities dedicated to post-operative recovery and physical therapy, where casting materials might be used for continued immobilization or support during rehabilitation.
- Orthopedic Surgeons:Individual practitioners who directly influence product selection based on surgical preference, patient needs, and clinical outcomes.
Clinics are gaining share fastest as more procedures shift to outpatient settings.
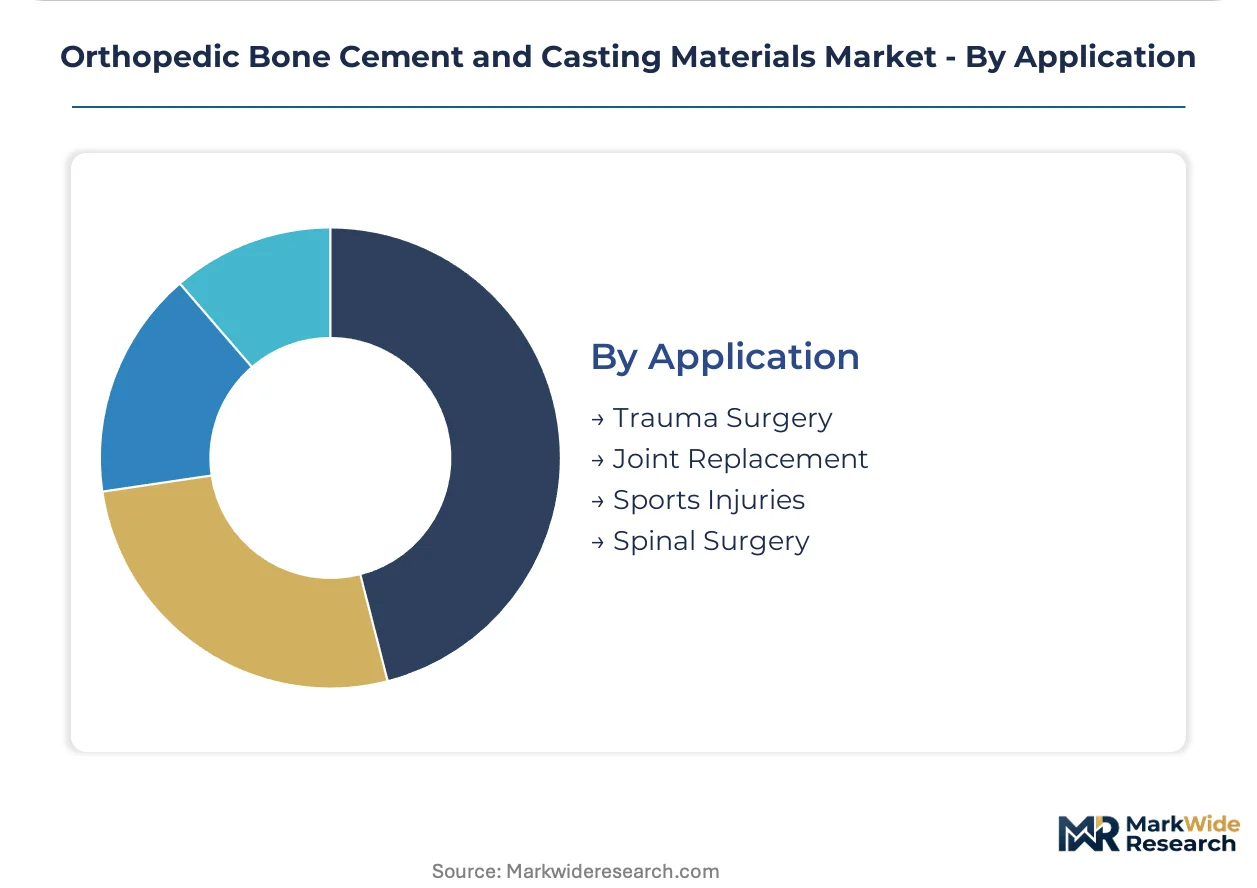
Application:
Volume drivers within applications are heavily influenced by demographic trends and the prevalence of specific orthopedic conditions across populations.
- Joint Replacement:Procedures such as total hip and knee arthroplasty, which heavily rely on bone cement for prosthetic fixation, represent a high-value segment. The aging global population and rising incidence of degenerative joint diseases in Western Europe fuel consistent demand.
- Trauma Surgery:Interventions for fractures and other acute orthopedic injuries, utilizing both bone cement for internal fixation and casting materials for external immobilization. Consistent demand exists across all geographies due to accidents and injuries.
- Sports Injuries:Orthopedic conditions resulting from athletic activities, often requiring casting materials for immobilization or specialized bone cements for repair.
- Spinal Surgery:Procedures addressing vertebral fractures or spinal instability, where specialized bone cements are used in techniques like vertebroplasty and kyphoplasty.
Joint Replacement procedures show the steepest expansion trajectory, reflecting demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant trade flow for orthopedic bone cement and casting materials moves from established manufacturing bases in Europe to high-demand healthcare systems like the United States and Japan. This global distribution network supports specialized surgical procedures and fracture management across diverse patient populations.
United States
Demand in the United States is driven by a high volume of outpatient procedures and the prevalence of sports injuries requiring non-surgical fixation. The US FDA's 510(k) pathway governs market access for many orthopedic devices, ensuring product safety and efficacy. Medical device manufacturing hubs in regions like Minneapolis-St. Paul continue to innovate in materials science and production techniques.
Germany
Germany represents a significant market for orthopedic bone cement, fueled by an aging population and a high volume of joint replacement surgeries. The European Union's Medical Device Regulation (MDR) imposes rigorous requirements for clinical data and post-market surveillance for products sold here. Specialized medical technology clusters in Southern Germany contribute to advanced biomaterial development and manufacturing.
Japan
Japan exhibits strong demand for poly(methyl methacrylate) (PMMA) formulations, particularly for complex joint arthroplasty procedures in its aging demographic. The PMDA imposes stringent biocompatibility and clinical evidence requirements for orthopedic materials. Research and development in biomaterials often concentrates in academic and industrial centers around Tokyo and Kyoto.
United Kingdom
The United Kingdom experiences consistent demand for orthopedic materials due to degenerative joint diseases and trauma surgery. Manufacturers must navigate the UKCA marking requirements for medical devices placed on the market. Medical technology clusters around Oxford and Cambridge foster innovation in both bone cements and casting materials.
Orthopedic Bone Cement and Casting Materials Market Key Industry Players
Listed leaders compete with private specialists across product innovation and distribution reach within the orthopedic materials market. The market structure is bifurcated, with large diversified medical device companies serving high-volume hospitals alongside specialized orthopedic material providers targeting ambulatory surgical centers. Companies often engage in portfolio diversification and geographic expansion to maintain competitive positioning.
At the scale-driven end, companies like Stryker Corporation and Zimmer Biomet Holdings exemplify global reach and broad product portfolios. These firms leverage extensive distribution networks to serve diverse customer segments, from large hospitals to smaller surgical clinics. Heraeus Holding GmbH, as a European-based entity, represents a specialized player with a strong focus on advanced material formulations, particularly in bone cements.
| Leading Market Players |
|---|
| DePuy Synthes |
| 3M Health Care Ltd. |
| Stryker Corporation |
| BSN Medical |
| DJO Global |
| Zimmer Biomet Holdings |
| Heraeus Holding GmbH |
| Exactech |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) gates market access and supply qualification for orthopedic materials, simultaneously influencing price differentiation based on compliance rigor and clinical evidence. This regulatory framework significantly impacts material costs and availability across Europe.
Pricing Analysis
A technology-generation pricing gap exists between established PMMA cements, newer antibiotic-loaded formulations, and nascent bioactive materials. Per-unit transactional pricing dominates, with significant price differentiation driven by clinical efficacy data and stringent regulatory approval status, particularly for premium products. Payer cost-containment pressures in healthcare systems worldwide exert downward pressure on standard material pricing. Public hospitals often exhibit high price sensitivity, while specialized orthopedic clinics prioritize advanced, outcome-improving materials for complex procedures.
Supply Chain Analysis
Inbound logistics costs, particularly for temperature-controlled transport of sterile components, influence the supply chain for orthopedic materials. Supply concentrates in established manufacturing hubs like Germany, the United States, and Japan, which draw from global sources for poly(methyl methacrylate) and fiberglass. Regulatory restrictions on biomaterials, such as those imposed by the PMDA, present a structural risk to product flow. Distribution runs through a dual model of direct sales forces to large hospitals and specialized distributors serving agile ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic bone cement and casting materials market is in an early-cycle expansion phase, driven by the persistent tailwind of an aging global population requiring increasing volumes of joint replacement procedures. This demographic shift underpins sustained demand across developed healthcare systems.
For Market Incumbents: Shield core market share by continuously innovating in bioactive materials and antibiotic-loaded cements, preempting disruption from next-generation alternatives. Incumbents should leverage their extensive distribution networks to consolidate relationships with both large hospitals and growing specialized orthopedic clinics. Strategic acquisitions of smaller, innovative material developers can mitigate competitive threats. This approach helps counter persistent payer cost-containment pressures while securing future revenue streams.
For New Entrants and Emerging Players: Differentiate on advanced material properties and superior patient outcomes to penetrate niche segments. New entrants should target underserved applications like specialized spinal procedures and focus on emerging markets in Asia where orthopedic surgical capacity is expanding. The most penetrable segment remains ambulatory surgical centers, which prioritize efficient, high-performance materials. A go-to-market angle emphasizing robust clinical evidence and value-based outcomes will resonate with these specialized facilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from large diversified medical device companies seeking to streamline non-core biomaterial portfolios. This market offers sustained growth potential over the next decade, driven by demographic trends and technological advancements. Acquisition targets should be specialized biomaterial developers with strong intellectual property in bioactive or resorbable materials. A key signal to watch is the increased regulatory approvals for these advanced bioactive materials, indicating market readiness and accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel antibiotic-loaded cements, validating safety and efficacy. |
| CE Marking Pathway | Ensures compliance with European Union Medical Device Regulation, crucial for market entry in Europe. |
| Hospital System Partnership | Secures high-volume procurement channels and strengthens product adoption within large networks. |
| Software Companion Development | Enhances surgical planning and post-operative monitoring for complex joint replacements. |
| Geographic Expansion | Penetrates growing orthopedic markets in Asia and Latin America, diversifying revenue streams. |
Research Approach
A standing panel of orthopedic surgeons, hospital procurement managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration for market sizing and trend analysis. This primary research was validated through secondary sources including US FDA filings, European Medical Device Regulation (MDR) reports, and industry association publications. A comprehensive bottom-up and top-down triangulation approach ensured data consistency across all segments.
Forecast outputs were rigorously checked for consistency against external benchmarks and historical market performance across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, end user, and application, alongside regional regulatory frameworks. Compound annual growth rates derived from historical data and projected growth drivers include arthroplasty procedural volumes and degenerative joint disease prevalence.
Material uncertainties — such as unforeseen regulatory changes, rapid shifts in surgical techniques, or global economic downturns — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Limb Salvage Systems Market