
 Bone Graft Fixation System Market | 2026-2036
Bone Graft Fixation System Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Graft Fixation System Market Analysis
Orthopedic surgical training capacity is redrawing competitive boundaries in bone graft fixation, as fellowship program bottlenecks limit the pool of surgeons qualified to perform advanced spinal and joint reconstruction procedures. Stryker Corporation leverages its integrated trauma and spine platforms to sustain broad hospital system contracts. Zimmer Biomet anchors its position through deep orthopedic surgeon relationships and extensive distributor networks across major metropolitan surgical centers. Medtronic competes by dominating navigated and robotic-assisted delivery systems that pair with fixation hardware.
Bone graft fixation systems comprise implantable mechanical devices designed to stabilize bone graft material and promote osseointegration, typically manufactured from titanium alloys with thread pitches optimized for cortical and cancellous bone engagement. These systems mechanically secure grafts during spinal fusion, fracture repair, and joint reconstruction procedures until biological union occurs. Interference screws and plates capture the largest volume share due to their versatility across anatomical sites and established reimbursement pathways. Bioabsorbable polymers represent the fastest-expanding material category as surgeons seek to eliminate secondary hardware removal procedures and reduce long-term implant-related complications. Titanium sustains premium positioning where immediate load-bearing strength and radiographic visibility drive selection criteria.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) impose substantial clinical evidence and quality system burdens on manufacturers seeking market access. ISO 5832 standards for metallic implant materials and ASTM F2077 testing protocols for spinal intervertebral body fusion devices define baseline mechanical performance thresholds that shape R&D investment priorities. Stakeholders must monitor evolving FDA guidance on bioresorbable implant degradation profiles and corresponding EU notified body interpretation consistency to anticipate certification timeline risks.
Market Dynamics
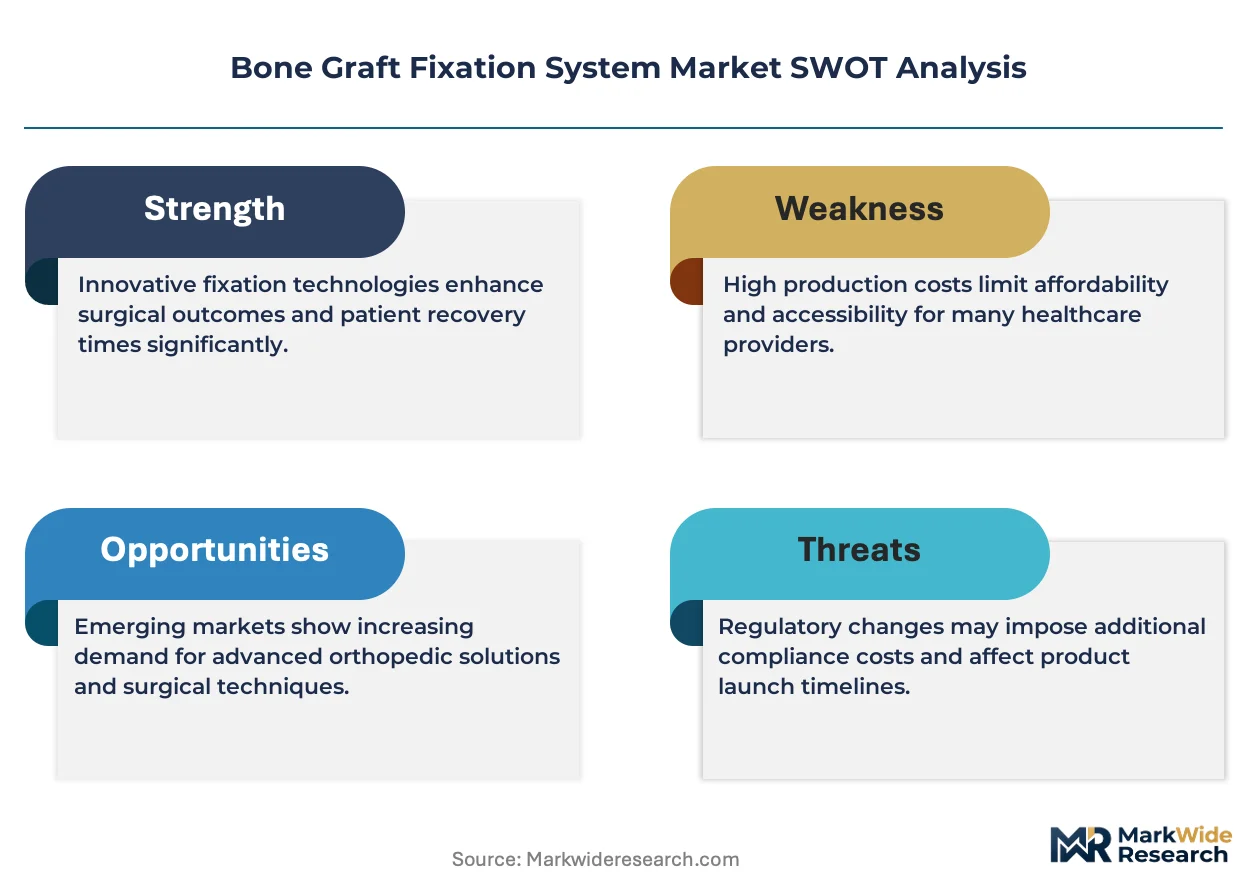
FDA 510(k) clearance timelines and EU MDR conformity assessment bottlenecks are compressing commercialization windows for bone graft fixation manufacturers, forcing parallel regulatory track strategies and early quality system investments.
Growth Catalysts
- Aging surgical populations:Medicare beneficiaries in the United States now account for over half of spinal fusion procedures, creating sustained procedural volume anchors for hospital purchasing committees.
- ISO 5832 standard harmonization:Unified metallic implant material specifications reduce retesting burdens for titanium alloy fixation systems seeking multi-regional approval.
- Bioabsorbable polymer R&D:PLGA and PCL material platforms eliminate secondary removal surgeries, reducing long-term complication liability for orthopedic surgeons.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have tightened titanium alloy input markets, elevating raw material cost volatility for implant manufacturers.
- EU MDR technical documentation:Clinical evaluation report requirements for Class III implantable devices extend conformity assessment timelines by 12-18 months versus legacy MDD pathways.
- Non-fusion motion preservation:Artificial disc replacement and dynamic stabilization systems compete for lumbar spine cases, constraining fusion fixation growth in specific anatomical segments.
Strategic Opportunities
- Outpatient ambulatory surgery centers:CMS reimbursement expansion for select spinal procedures in United States ASC settings opens volume channels outside traditional hospital purchasing.
- 3D-printed patient-specific implants:Electron beam melting and selective laser sintering convergence with digital surgical planning enables anatomic-fit fixation geometries.
- Japan PMDA Sakigake designation:Fast-track review pathways for regenerative medicine products accelerate market entry for bioabsorbable fixation systems with novel degradation profiles.
Industry Challenges
- Orthopedic fellowship pipeline constraints:Accreditation Council for Graduate Medical Education caps limit annual spine surgeon production, creating procedural capacity ceilings in high-demand metropolitan markets.
- Bioresorbable degradation validation:ASTM F1635 in vitro testing and animal model requirements for absorption rate characterization demand 24-36 month preclinical investment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Graft Fixation System Market |
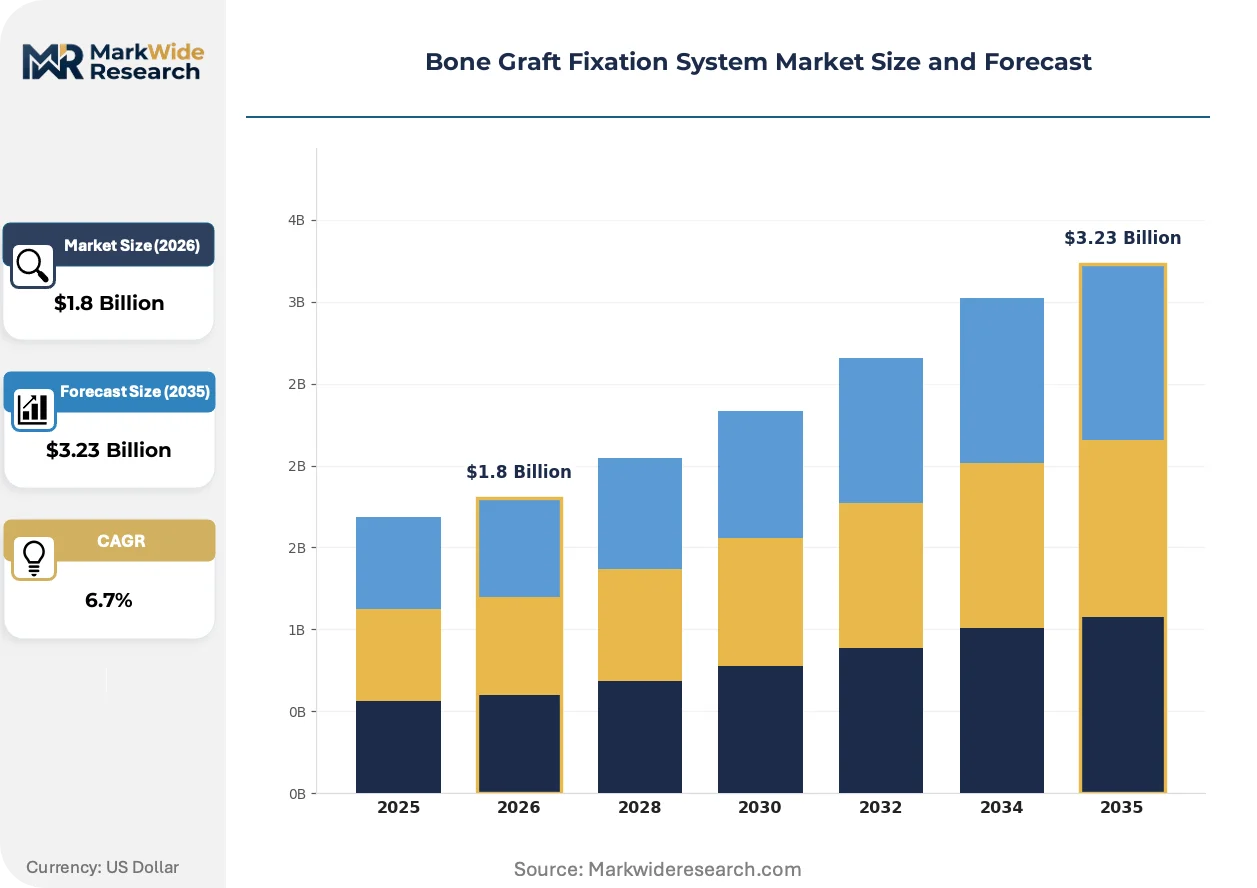
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interference Screws, Plates, Rods, Staples Material: Titanium, Stainless Steel, Bioabsorbable Polymers, Ceramics End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Trauma Centers Procedure Type: Spinal Fusion, Fracture Repair, Joint Reconstruction, Osteotomy |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, DePuy Synthes, Smith & Nephew, Orthofix Holdings, Globus Medical, Arthrex, Biocomposites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Graft Fixation System Market Emerging Trajectories
Material science convergence with digital manufacturing is restructuring competitive advantage in bone graft fixation, shifting value capture from scale economies to customization capabilities and regulatory data packages.
Miniaturized interference screw designs are penetrating cervical spine applications previously dominated by plating systems. Ambulatory surgery centers in the United States are adopting these lower-profile implants for single-level procedures. Device footprint reduction is miniaturizing surgical access requirements and enabling tissue-sparing approaches.
EU MDR Article 120 transition deadlines are forcing legacy device recertification or withdrawal decisions across European notified body jurisdictions. Manufacturers with pre-2021 certificates face compressed evidence generation timelines for clinical follow-up studies. Spinal fusion device categories with limited post-market surveillance data are experiencing the most acute notified body capacity constraints.
Hospital value analysis committees are consolidating vendor contracts and demanding bundled pricing for fixation hardware with biologics. Distributor relationships that historically carried inventory risk are being displaced by direct manufacturer consignment models. This concentration is most visible in United States integrated delivery networks where purchasing standardization across 10+ hospital campuses reduces SKU complexity.
Bone Graft Fixation System Market Segmentation
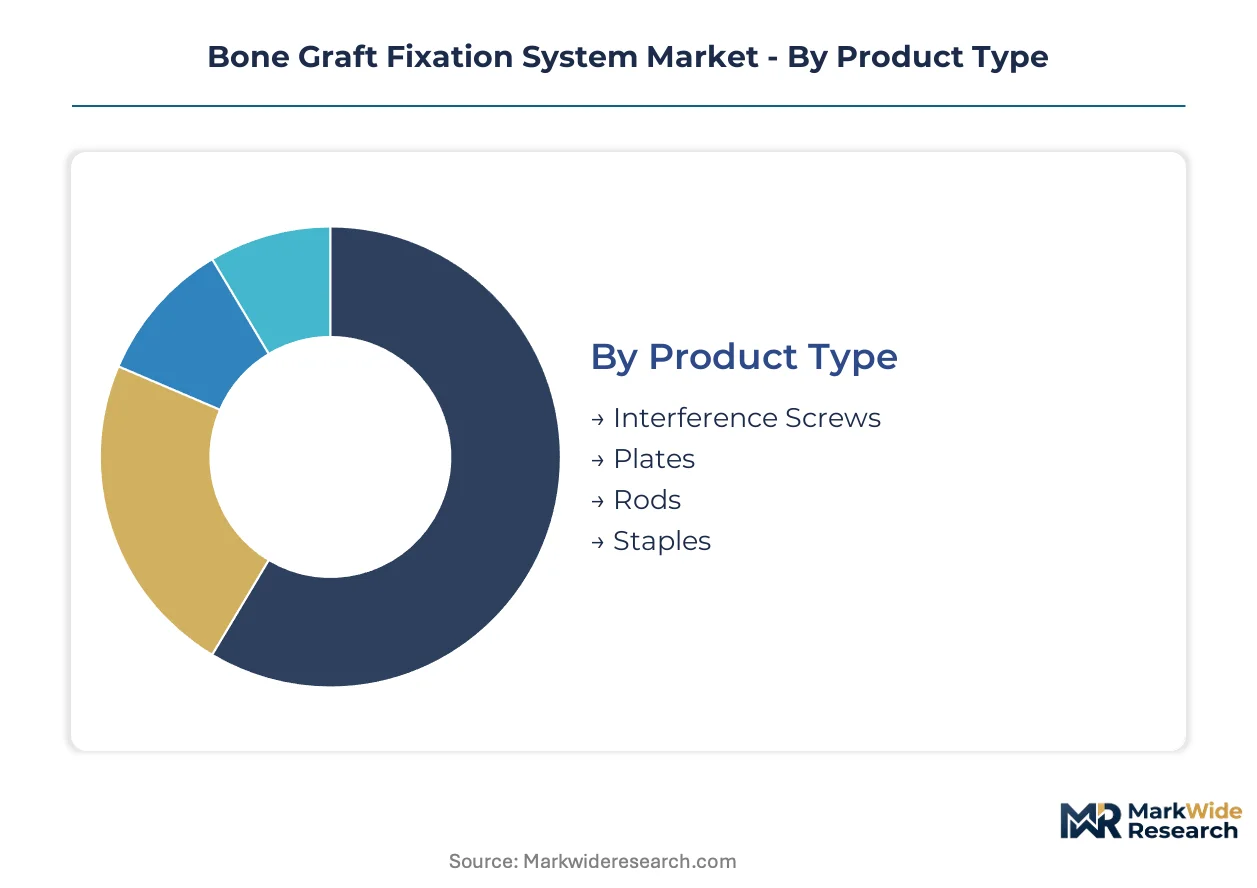
Segmentation in bone graft fixation reveals how regulatory pathways, material properties, and care settings intersect to determine commercial viability. Manufacturers must align product portfolios with distinct reimbursement codes and surgical training requirements across each dimension.
Product Type:
FDA 510(k) clearance requirements vary substantially by implant geometry, with threaded devices facing distinct mechanical testing protocols versus plate-based systems.
- Interference Screws:Tapered threaded cylinders manufactured from titanium alloys or bioabsorbable polymers secure grafts within bone tunnels. Hospital purchasing committees in the United States favor these for anterior cruciate ligament reconstruction and spinal fusion due to established CPT reimbursement codes and familiar surgical technique.
- Plates:Rigid fixation constructs with cortical screw holes stabilize fracture fragments and fusion segments. Demand concentrates in trauma centers and academic medical centers where complex multi-fragment fractures require anatomical reduction and load-bearing support during osseointegration.
- Rods:Longitudinal implants spanning multiple vertebral levels or long bone segments provide structural continuity.
- Staples:U-shaped metallic devices compress osteotomy surfaces or epiphyseal plates in pediatric applications.
Established volume favors Interference Screws; emerging adoption favors Plates as hybrid fixation techniques gain surgical acceptance.
Material:
Raw material cost tiers separate premium titanium systems from commoditized stainless steel alternatives, with bioabsorbable platforms occupying a distinct value proposition based on elimination of secondary procedures.
- Titanium:Ti-6Al-4V ELI alloy delivers strength-to-weight ratios and osseointegration properties unmatched by alternatives. United States orthopedic surgeons select titanium for load-bearing spinal fusion and joint reconstruction where radiographic visibility and long-term biocompatibility drive purchasing decisions.
- Bioabsorbable Polymers:PLGA and PCL copolymers degrade through hydrolysis, eliminating hardware removal surgeries. Ambulatory surgical centers are adopting these for pediatric osteotomies and select sports medicine procedures where implant retention risks outweigh mechanical demands.
- Stainless Steel:316L grade offers cost-effective fixation for temporary stabilization and resource-constrained settings.
- Ceramics:Hydroxyapatite and beta-tricalcium phosphate compositions provide osteoconductive scaffolds with limited mechanical load-bearing capacity.
Procurement is shifting toward Bioabsorbable Polymers in outpatient settings; Titanium sustains premium positioning in hospital-based complex reconstruction.
End User:
Site-of-care economics determine pricing tolerance and inventory requirements, with ambulatory migration reshaping distribution models.
- Hospitals:Integrated delivery networks consolidate purchasing across multiple campuses, demanding bundled contracts for fixation hardware with biologics. Value analysis committees in United States metropolitan markets standardize on two to three vendor relationships to reduce SKU complexity and leverage volume discounts.
- Ambulatory Surgical Centers:CMS reimbursement expansion for select spinal procedures enables same-day discharge protocols. These facilities prioritize lower-profile implants and disposable instrumentation kits that minimize sterilization overhead and turnover time.
- Specialty Clinics:Orthopedic-focused practices concentrate on sports medicine and hand procedures.
- Trauma Centers:Level I and II designated hospitals manage acute fracture stabilization with expedited procurement protocols.
Hospital contracts anchor current revenue; Ambulatory Surgical Centers represent the steepest expansion trajectory as procedural migration accelerates.
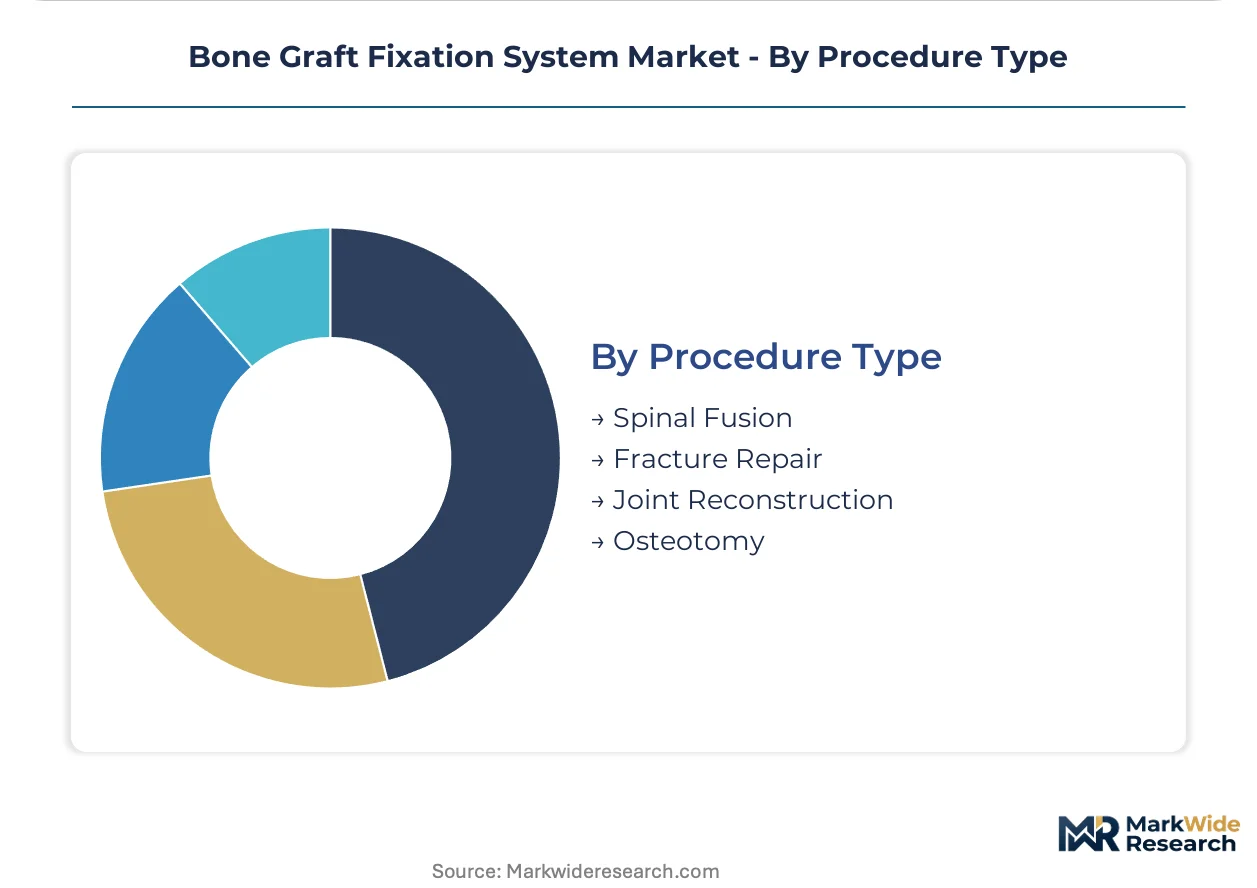
Procedure Type:
Surgical volume distribution and reimbursement intensity vary dramatically across anatomical applications, with spinal fusion commanding premium pricing per procedure.
- Spinal Fusion:Interbody and posterolateral fusion techniques require pedicle screws, rods, and interbody cages with supplemental graft fixation. Medicare beneficiaries in the United States drive procedural volume as degenerative disc disease and spondylolisthesis prevalence rises with aging demographics.
- Fracture Repair:Open reduction and internal fixation procedures stabilize traumatic and osteoporotic fractures. Demand concentrates in United States trauma centers and community hospitals where high-energy injuries and falls in elderly populations sustain case volumes.
- Joint Reconstruction:Osteochondral grafting and revision arthroplasty procedures utilize interference screws and compression staples.
- Osteotomy:Corrective bone cuts for deformity correction require rigid fixation to maintain alignment during healing.
Spinal Fusion generates the highest revenue per procedure; Fracture Repair delivers the broadest volume base across care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor commercialization strategy for implantable devices targeting United States surgical centers, while EU MDR conformity assessments reshape European market access timelines.
United States
Medicare beneficiaries drive over half of spinal fusion procedural volume as aging demographics expand degenerative disc disease treatment demand. FDA maintains stringent 510(k) premarket notification requirements for Class II implantable devices with predicate comparison obligations. Hospital value analysis committees in metropolitan surgical centers consolidate vendor contracts across integrated delivery networks exceeding ten campuses.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor complex trauma reconstruction demand for load-bearing titanium fixation systems. EU MDR notified body capacity constraints extend conformity assessment timelines twelve to eighteen months beyond legacy MDD pathways. Stuttgart and Munich industrial clusters concentrate precision machining capabilities for orthopedic implant manufacturing.
Japan
PMDA Sakigake fast-track designation accelerates market entry for bioabsorbable fixation systems with novel degradation profiles. METI industrial policy supports domestic medical device innovation through regenerative medicine product pathways. Osaka-Kobe manufacturing corridor hosts specialized polymer processing facilities for PLGA and PCL implant materials.
United Kingdom
NHS England procurement frameworks standardize spinal fusion device purchasing across regional hospital trusts. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements creates transitional certification complexity. Cambridge and Oxford medical technology clusters advance 3D-printed patient-specific implant development through university-hospital partnerships.
Australia
TGA approval pathways for Class III implantable devices require ISO 13485 quality system certification and clinical evidence packages. Public hospital purchasing through state health departments concentrates demand in Sydney and Melbourne metropolitan surgical centers. TGA alignment with EU MDR standards reduces retesting burdens for manufacturers seeking multi-regional approval.
Bone Graft Fixation System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated hospital purchasing committees favoring vendors offering bundled fixation-biologic portfolios. The vendor base fragments across regional distributors serving ambulatory surgery centers with lower-profile implant configurations. Three archetypes dominate: diversified orthopedic conglomerates with spine-trauma integration, pure-play spinal fixation specialists, and sports medicine-focused arthroscopy platform owners. Competitive moves concentrate on direct-to-hospital consignment model displacement of traditional distributor relationships and 3D-printed patient-specific implant capability acquisition.
Within the integrated orthopedic tier, Stryker Corporation and Zimmer Biomet exemplify diversified platform strategies spanning trauma, spine, and joint reconstruction hardware. Medtronic occupies a distinct position pairing navigated delivery systems with fixation hardware. These three anchors represent contrasting approaches to surgeon relationship depth, with some emphasizing broad hospital system contracts and others targeting metropolitan surgical center concentration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| DePuy Synthes |
| Smith & Nephew |
| Orthofix Holdings |
| Globus Medical |
| Arthrex |
| Biocomposites |
| Others |
Supply Flow & Price Mechanics
Bioabsorbable polymer substitution for titanium alloys is redrawing procurement geography and compressing price premiums across ambulatory surgery centers. United States hospital value analysis committees exploit this material transition to renegotiate bundled contracts with legacy titanium suppliers.
Pricing Analysis
Long-term offtake agreements dominate hospital integrated delivery network purchasing, with two to three vendor relationships standardizing SKU complexity across ten-plus campuses. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments, with bioabsorbable platforms commanding modest premiums for elimination of secondary removal procedures. Cost compression in titanium screw segments intensifies as Russian and Ukrainian titanium sponge disruptions elevate raw material volatility. Ambulatory surgical centers exhibit highest price sensitivity due to CMS reimbursement constraints, while academic medical centers prioritize radiographic visibility and load-bearing performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of titanium sponge feedstock has displaced just-in-time preferences among implant manufacturers confronting Russian supply disruptions. Manufacturing concentration centers on Germany's Stuttgart and Munich precision machining clusters, Japan's Osaka-Kobe polymer processing corridor, and United States domestic forging facilities. Raw material dependencies encompass Ti-6Al-4V ELI alloy, PLGA and PCL copolymers, and electron beam melting metal powders. Single-source vulnerability in titanium sponge supply creates acute exposure to geopolitical trade restrictions. Distribution runs through direct manufacturer consignment models displacing traditional distributor inventory risk in United States metropolitan surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioabsorbable polymer degradation science is disrupting orthopedic fixation, with FDA guidance on resorption profiles and EU MDR clinical evidence requirements creating regulatory inflection points for capital deployment.
For Market Incumbents: Fortify hospital system contracts through backward integration into PLGA polymer production and captive titanium alloy forging capacity. Stryker Corporation and Zimmer Biomet exemplify defensive positioning via deep orthopedic surgeon relationships and navigated delivery system pairings. Certification investment in EU MDR technical documentation buffers against twelve to eighteen month conformity assessment extensions threatening European revenue streams. For New Entrants and Emerging Players: Differentiate on patient-specific 3D-printed implant geometries enabled by electron beam melting convergence with digital surgical planning. White-space targets include Japan PMDA Sakigake fast-track pathways for novel degradation profiles and United States ambulatory surgery center disposable instrumentation kits. Go-to-market execution prioritizes direct consignment models bypassing traditional distributor markups in metropolitan surgical centers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed spinal fixation specialists holding pre-2021 EU MDR certificates facing compressed recertification timelines. Five to ten year viability hinges on bioabsorbable platform clinical data packages and 3D-printed manufacturing scale. The signal to watch is notified body capacity constraints forcing legacy device withdrawals across European jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Parallel predicate comparison pathways compress commercialization windows for bioabsorbable interference screws. |
| CE Marking Pathway Investment | EU MDR clinical evaluation report preparation extends twelve to eighteen months beyond legacy MDD timelines. |
| Hospital System Partnership | Integrated delivery network bundled contracts for fixation hardware with biologics reduce SKU complexity. |
| Software Companion Development | Navigated and robotic-assisted delivery systems pair with fixation hardware to differentiate surgical workflow. |
| Reimbursement Strategy | CMS expansion for spinal procedures in ambulatory surgery centers opens volume channels outside hospital purchasing. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare procedure databases, and ISO 5832 metallic implant standards. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing.
Across the analysis window, forecasts segment by product type, material composition, end-user site of care, and procedure anatomical application. CAGRs derive from demographic procedure volume projections, reimbursement policy trajectories, and material substitution elasticity coefficients. Bioabsorbable polymer adoption curves and 3D-printed implant penetration rates inform scenario-weighted outputs.
The analysis sits within stated boundaries; outcomes outside FDA 510(k) clearance timeline stability or titanium sponge supply normalization would require recalibration. Forecasts reflect assumptions regarding orthopedic fellowship pipeline expansion and EU MDR notified body capacity resolution. Revision becomes warranted when bioresorbable degradation validation timelines or ambulatory surgery center reimbursement thresholds cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market