
 Vertebroplasty and Kyphoplasty Devices Market | 2026-2036
Vertebroplasty and Kyphoplasty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebroplasty and Kyphoplasty Devices Market Outlook
North American orthopedic polymer producers is broadening output of high-viscosity bone cements to serve rising hospital procurement volumes. Medtronic plc leverages its spine portfolio depth to sustain integrated supply relationships across fluoroscopy-guided delivery systems. Stryker Corporation anchors North American distribution through specialized spine sales forces. Globus Medical, Inc. differentiates via focused R&D intensity in expandable vertebral augmentation technologies.
Vertebroplasty and kyphoplasty devices comprise bone cements, injectors, and vertebral augmentation systems designed for percutaneous stabilization of vertebral compression fractures, typically utilizing polymethyl methacrylate formulations with radiopaque additives for intraoperative visualization under fluoroscopic or CT guidance. These devices restore vertebral body height, relieve pain, and prevent progressive spinal deformity in osteoporotic or pathological fracture patients. Bone cements represent the most mature revenue pool with established pricing benchmarks, while 3D imaging guidance is capturing faster growth as hospitals upgrade interventional suites. Vertebral augmentation devices command premium positioning where height restoration outcomes justify reimbursement differentials.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for bone cement biocompatibility and device mechanical performance. ISO 5833 standards for acrylic resin cements and ASTM F451 testing protocols govern material characterization and fatigue resistance validation. Stakeholders must monitor evolving NCD and LCD determinations from Medicare contractors that directly influence ambulatory surgical center case economics and site-of-service migration patterns.
Market Dynamics
Site-of-service migration toward ambulatory surgical centers is compressing reimbursement differentials and forcing manufacturers to reconfigure device pricing and service models around lower-acuity settings.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Medicare's NCD and LCD determinations for vertebral augmentation procedures enable same-day discharge protocols. ASCs in the United States capture rising case volumes as hospital outpatient departments face capacity constraints.
- EU MDR Technical Documentation Requirements:Tightened biocompatibility standards for polymethyl methacrylate bone cements accelerate product lifecycle management investments. Manufacturers with robust clinical evidence portfolios gain accelerated market access across notified body jurisdictions.
- 3D Imaging Guidance Integration:CT-fluoroscopy hybrid navigation systems reduce radiation exposure and cement extravasation rates. Interventional suites in Germany and Japan prioritize capital upgrades toward real-time three-dimensional visualization platforms.
Market Restraints
- Methyl Methacrylate Monomer Supply Concentration:Bulk polymer precursor production clusters in Gulf Coast petrochemical corridors expose cement manufacturers to hurricane-related supply disruptions and feedstock price volatility.
- FDA 510(k) Substantial Equivalence Thresholds:Predicate device limitations constrain incremental innovation pathways for next-generation vertebral augmentation systems. Novel mechanical designs face de novo classification delays.
- Conservative Management Substitution:Bracing protocols and analgesic regimens retain clinical preference for stable compression fractures without neurological compromise. Orthopedic surgeons in cost-sensitive markets delay intervention thresholds.
Strategic Opportunities
- Underpenetrated Japanese Rural Markets:Prefecture-level osteoporosis screening gaps leave vertebral compression fractures undiagnosed in aging agricultural communities. Mobile C-arm deployment partnerships with regional health cooperatives unlock latent demand.
- Bioresorbable Cement Formulations:Calcium phosphate composites with osteoconductive properties address polymethyl methacrylate's permanent implant limitations. Research consortia in Germany advance preclinical validation toward regulatory submission pathways.
- Direct-to-Facility Distribution Models:Bypassing traditional spine distributor networks reduces ASP erosion from markup stacking. Manufacturers with captive logistics capabilities capture margin recovery in high-volume ASC accounts.
Industry Challenges
- Interventional Radiology Training Pipeline:Fellowship programs produce insufficient operators proficient in bipedicular access techniques and cement viscosity management. Academic medical centers compete for limited procedural volume to maintain competency curves.
- ISO 5833 Fatigue Testing Timelines:Acrylic resin cement mechanical characterization requires extended accelerated aging protocols. Development programs face 18-24 month validation cycles before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebroplasty and Kyphoplasty Devices Market |
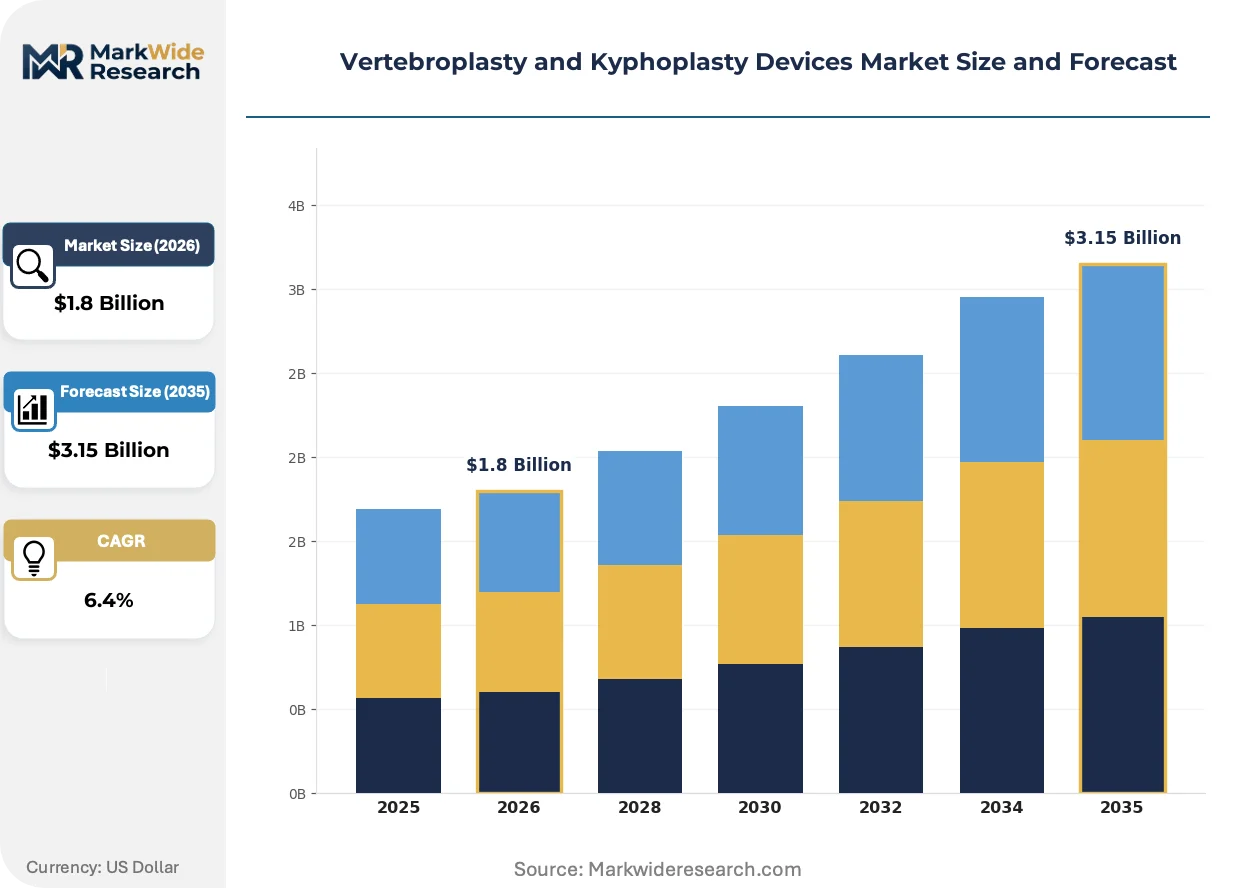
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Cements, Injectors, Accessories, Vertebral Augmentation Devices Technology: Fluoroscopy, CT Guidance, Ultrasound Guidance, 3D Imaging End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: Compression Fractures, Osteoporosis Treatment, Tumor Management, Pain Management |
| Companies Covered | Merit Medical Systems, Inc., Cardinal Health, Inc., Medtronic plc, CareFusion Corporation, Alphatec Spine, Inc., Stryker Corporation, DePuy Synthes, Globus Medical, Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebroplasty and Kyphoplasty Devices Market Strategic Shifts
Navigation-assisted delivery and cement material science advances are compressing complication rates while expanding treatable patient populations beyond traditional osteoporosis indications.
Robotic guidance platforms for percutaneous vertebral access are automating needle trajectory planning and depth control. Academic medical centers in the United States deploy these systems to reduce fluoroscopy time and operator radiation exposure. The technology is automating skill transfer from high-volume specialists to lower-cadence community practitioners, expanding addressable operator pools.
EU MDR post-market surveillance requirements mandate systematic collection of real-world performance data for bone cement implants. Manufacturers must establish periodic safety update reports and trend analysis protocols across notified body jurisdictions. High-viscosity cement formulations with modified radiopaque additives face heightened scrutiny for long-term biocompatibility profiles.
Hospital procurement committees consolidate spine device purchasing under value-analysis frameworks that bundle vertebral augmentation with broader implant portfolios. Integrated delivery networks in Germany negotiate multi-year supply agreements spanning trauma, deformity, and fracture care categories. This concentration shifts vendor selection criteria toward total cost-of-ownership metrics rather than device-level pricing.
Vertebroplasty and Kyphoplasty Devices Market Segmentation
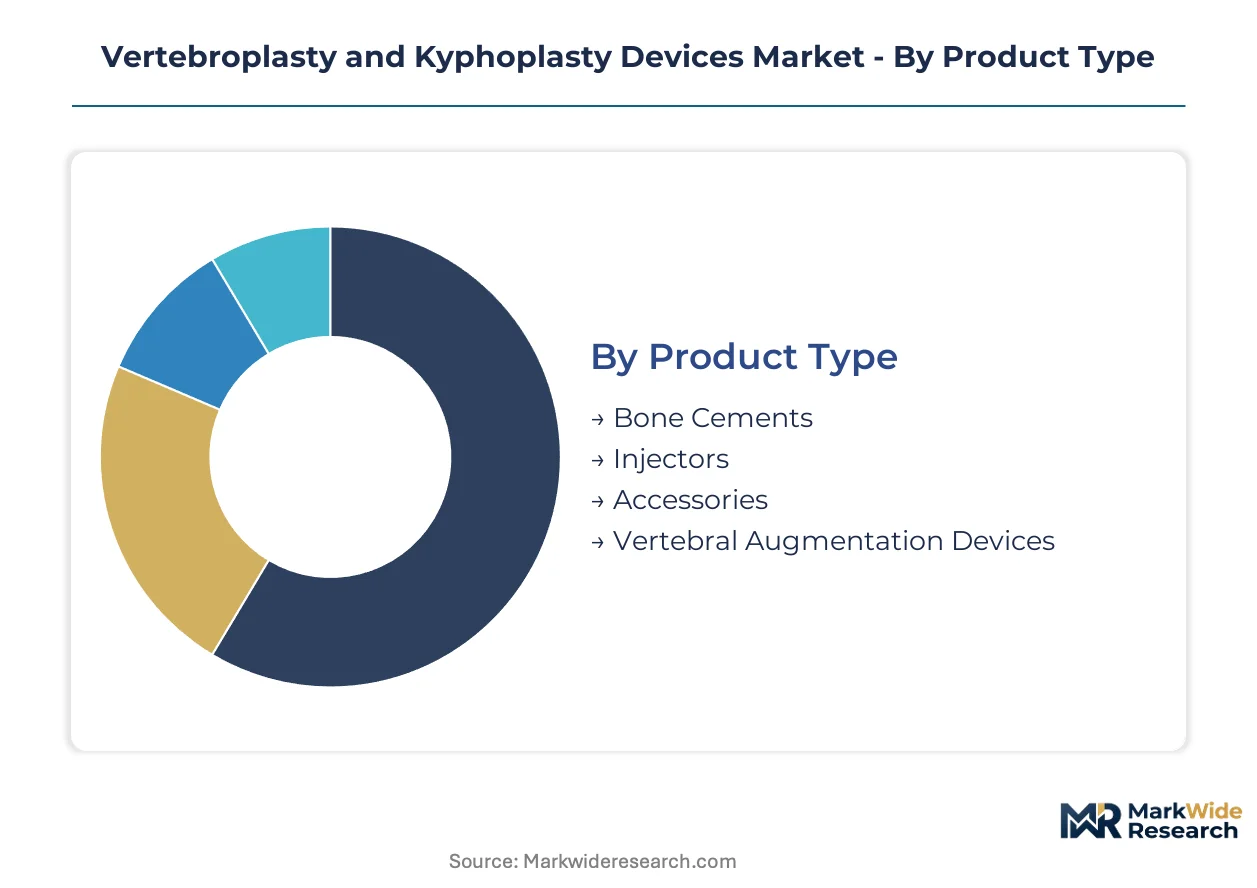
Device segmentation in vertebral augmentation reflects divergent capital intensity and reimbursement economics across care settings. Product mix and technology choices directly determine site-of-service eligibility and procedural economics.
Product Type:
Upgrade cycles for vertebral augmentation systems accelerate as ASCs demand compact, portable configurations that fit limited suite footprints.
- Bone Cements:Polymethyl methacrylate formulations with barium sulfate or zirconium oxide radiopacifiers dominate procedural volumes. Hospital procurement committees in the United States negotiate multi-year supply agreements for high-viscosity cements that reduce extravasation risk during injection.
- Vertebral Augmentation Devices:Balloon kyphoplasty systems and mechanical expandable devices command premium pricing where height restoration outcomes justify reimbursement differentials. German interventional suites prioritize integrated delivery systems that combine access needles with controlled inflation mechanisms.
- Injectors:Pressure-controlled syringe systems and gun-style applicators enable consistent cement delivery viscosity.
- Accessories:Bone biopsy needles, mixing bowls, and cement delivery tubing complete procedural kits.
Volume placements concentrate in Bone Cements; the faster expansion belongs to Vertebral Augmentation Devices.
Technology:
Capital replacement timelines for imaging guidance compress as radiation exposure protocols tighten and liability concerns mount.
- Fluoroscopy:C-arm systems remain the standard of care for real-time needle placement and cement visualization. Medicare reimbursement rates in the United States favor established fluoroscopy protocols over unproven navigation alternatives.
- 3D Imaging:CT-fluoroscopy hybrid platforms reduce radiation dose and improve cement distribution assessment. Japanese academic medical centers lead adoption of cone-beam CT integration for complex deformity cases.
- CT Guidance:Standalone computed tomography navigation serves patients with severe degenerative changes obscuring bony landmarks.
- Ultrasound Guidance:Emerging applications in cervical and upper thoracic access avoid radiation entirely.
Revenue concentration favors Fluoroscopy installations; 3D Imaging claims the steepest expansion trajectory.
End User:
Site-of-service economics reshape procurement authority as case volume migrates from hospital campuses to lower-acuity settings.
- Hospitals:Academic medical centers and community hospitals maintain high-complexity fracture referral patterns. Integrated delivery networks in Germany bundle vertebral augmentation with trauma and deformity service lines.
- Ambulatory Surgical Centers:Same-day discharge protocols and streamlined staffing models compress per-case costs. United States ASCs capture rising volumes as Medicare NCD determinations clarify coverage for outpatient vertebral augmentation.
- Clinics:Office-based pain management practices handle diagnostic workup and post-procedure monitoring.
- Research Institutions:Academic consortia validate novel cement formulations and mechanical augmentation techniques.
Procedure counts peak at Hospitals; Ambulatory Surgical Centers gain share fastest.
Application:
Patient selection criteria expand as bioresorbable materials and improved navigation enable treatment of previously excluded fracture patterns.
- Compression Fractures:Osteoporotic vertebral body collapse represents the core indication driving procedural volume. PMDA reimbursement pathways in Japan prioritize rapid intervention for acute fractures to prevent progressive kyphosis.
- Osteoporosis Treatment:Prophylactic augmentation for high-risk osteoporotic spines remains investigational. Research consortia in Germany advance preclinical validation of calcium phosphate composites toward regulatory submission.
- Tumor Management:Pathological fractures from metastatic disease require cement augmentation for palliative stabilization.
- Pain Management:Refractory axial pain without radiographic collapse challenges traditional intervention thresholds.
Compression Fractures anchor clinical volume; Osteoporosis Treatment applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymethyl methacrylate precursor production clusters along the Gulf Coast of the United States, creating supply chain exposure that shapes regional device manufacturing strategies across vertebral augmentation markets.
United States
Medicare NCD determinations for outpatient vertebral augmentation procedures accelerate same-day discharge protocols at ambulatory surgical centers. FDA 510(k) clearance pathways establish substantial equivalence benchmarks for bone cement biocompatibility testing. Academic medical centers in Boston and Minneapolis deploy robotic guidance platforms to reduce fluoroscopy exposure during percutaneous access.
Germany
Integrated delivery networks negotiate multi-year supply agreements bundling vertebral augmentation with trauma and deformity service lines. EU MDR technical documentation requirements tighten post-market surveillance obligations for polymethyl methacrylate implants. Research consortia in Munich advance preclinical validation of calcium phosphate composite formulations toward regulatory submission.
Japan
PMDA reimbursement pathways prioritize rapid intervention for acute osteoporotic fractures to prevent progressive kyphosis in aging rural prefectures. Prefecture-level osteoporosis screening gaps leave vertebral compression fractures undiagnosed in agricultural communities. Mobile C-arm deployment partnerships with regional health cooperatives in Tohoku and Hokkaido unlock latent procedural demand.
United Kingdom
NICE technology appraisals influence NHS commissioning decisions for vertebral augmentation procedures in elderly populations with pathological fractures. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for bone cement manufacturers. London-based interventional radiology training programs compete for limited procedural volume to maintain operator competency curves.
Switzerland
Swissmedic medical device regulations mandate rigorous clinical evidence portfolios for high-viscosity bone cement formulations seeking market authorization. Aging demographics in Alpine cantons drive compression fracture intervention volumes at university hospitals in Zurich and Geneva. Research institutions in Basel collaborate on bioresorbable cement material science advancing osteoconductive properties.
Vertebroplasty and Kyphoplasty Devices Market Competitive Environment
Global majors compete with regional champions across integrated spine portfolios and specialized vertebral augmentation technologies. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with captive distribution networks, mid-cap spine specialists with focused R&D intensity, and regional device fabricators serving price-sensitive procurement committees. Strategic archetypes include integrated delivery system partners, technology licensing specialists, and direct-to-facility logistics operators. Dominant competitive moves encompass backward integration into bone cement precursor supply and multi-year exclusive supply agreements with high-volume ASC accounts.
Among diversified orthopedic conglomerates, Medtronic plc and Stryker Corporation exemplify integrated portfolio depth spanning fluoroscopy-guided delivery systems and specialized spine sales forces. Globus Medical, Inc. occupies a position within the mid-cap specialist tier, representing focused R&D intensity in expandable vertebral augmentation technologies. These three entities anchor competitive positioning across North American hospital procurement and ambulatory surgical center channels.
| Leading Market Players |
|---|
| Merit Medical Systems, Inc. |
| Cardinal Health, Inc. |
| Medtronic plc |
| CareFusion Corporation |
| Alphatec Spine, Inc. |
| Stryker Corporation |
| DePuy Synthes |
| Globus Medical, Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in Germany and hospital procurement committees in the United States negotiate multi-year supply agreements that compress device-level margins while rewarding total cost-of-ownership performance across bundled spine portfolios. This buyer concentration shifts pricing power toward volume aggregators capable of consolidating vertebral augmentation with trauma and deformity service lines.
Pricing Analysis
Warranty and service bundling separates premium balloon kyphoplasty systems with dedicated clinical support from unbundled bone cement commodity offerings. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO 5833 certification grade and after-sales training intensity. Pricing pressure stems from site-of-service migration toward ambulatory surgical centers demanding lower per-procedure costs. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize outcome metrics over unit economics.
Supply Chain Analysis
Methyl methacrylate monomer supply rests on Gulf Coast petrochemical corridors in the United States, with secondary sourcing from German and Japanese specialty chemical producers. Acrylic resin precursors, radiopaque additives, and precision-machined injector components constitute critical input dependencies. Hurricane-related disruption risk concentrates in Texas-Louisiana production clusters. Distribution runs through specialized spine distributor networks and direct-to-facility logistics operators serving high-volume ASC accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in vertebral augmentation hinges on backward integration into bone cement precursor supply and captive control over fluoroscopy-guided delivery system manufacturing. Players lacking upstream polymer capabilities face margin compression as procurement consolidation accelerates.
For Market Incumbents: Anticipate reimbursement compression from Medicare NCD determinations favoring outpatient settings by securing exclusive multi-year supply agreements with high-volume ambulatory surgical center chains. Deepen captive production of high-viscosity cement formulations to defend against methyl methacrylate feedstock volatility. Prioritize EU MDR technical documentation investments to accelerate notified body clearances ahead of competitors facing extended validation cycles. For New Entrants and Emerging Players: Regional health cooperatives in Japan's Tohoku and Hokkaido prefectures represent the most penetrable channel partner type for mobile C-arm deployment partnerships addressing osteoporosis screening gaps. Target bioresorbable calcium phosphate composite formulations where German research consortia have advanced preclinical validation toward regulatory submission pathways. Pursue direct-to-facility distribution models bypassing traditional spine distributor markups to capture margin recovery in price-sensitive ASC accounts. For Investors and Strategic Acquirers: The window for entry favors mid-cap spine specialists with focused R&D intensity in expandable vertebral augmentation technologies and established CE marking portfolios. Long-term viability centers on consolidation plays that combine material science capabilities with interventional radiology training infrastructure. Watch PMDA reimbursement pathway expansions for acute fracture intervention as the inflection signal indicating Japanese rural market penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive methyl methacrylate production insulates Gulf Coast disruption exposure for cement manufacturers. |
| CE Marking Pathway Acceleration | EU MDR technical documentation readiness unlocks notified body jurisdictions ahead of competitor submissions. |
| Hospital System Partnership | Integrated delivery network bundling secures multi-year vertebral augmentation contracts across trauma service lines. |
| Software Companion Development | CT-fluoroscopy hybrid navigation integration reduces radiation exposure and cement extravasation rates in interventional suites. |
| Reimbursement Strategy | Medicare NCD alignment for outpatient vertebral augmentation captures ASC volume migration from hospital campuses. |
Study Parameters
FDA 510(k) clearance databases, EU MDR technical documentation filings, and CMS Medicare claims data formed the secondary backbone for procedure volume and reimbursement trend analysis. Primary interviews with interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated device adoption patterns and procurement decision criteria. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators produced volume and value estimates across the analysis window.
Historical trendline analysis of bone cement pricing and vertebral augmentation system placements informed the analytical framework across product type, technology, end user, and application dimensions. CAGRs derived from regression analysis of procedure growth rates, aging demographic projections, and site-of-service migration patterns. Forecast inputs incorporated ISO 5833 fatigue testing timelines, EU MDR post-market surveillance requirements, and PMDA reimbursement pathway developments specific to osteoporotic fracture intervention.
Caveats apply where Medicare LCD determinations, EU MDR notified body capacity constraints, or methyl methacrylate supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding ambulatory surgical center expansion velocity and interventional radiology training pipeline output. A small set of named triggers—hurricane season severity, FDA de novo classification delays, and Japanese prefecture-level screening program funding—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market