
 Bioresorbable Coronary Stents Market | 2026-2036
Bioresorbable Coronary Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Bioresorbable Coronary Stents Market Analytics
CE marking under the EU Medical Device Regulation (MDR) is rotating as the decisive gate for commercial entry, with only manufacturers demonstrating sustained biocompatibility and resorption-kinetics documentation securing approval timelines. Abbott Laboratories leverages its vascular portfolio depth to anchor clinical trial infrastructure across European sites. Boston Scientific Corporation competes through specialized polymer formulation expertise that differentiates its scaffold resorption profiles. BIOTRONIK sustains manufacturing scale in Germany, where it controls a significant share of regional catheterization lab supply relationships.
Bioresorbable coronary stents are implantable vascular scaffolds fabricated from polymers such as poly-L-lactic acid (PLLA) or magnesium alloys, engineered to provide transient luminal support before complete metabolic absorption within 12-36 months. Their primary purpose is restoring coronary blood flow while eliminating permanent metallic foreign-body presence that complicates future revascularization. Polymer-based stents lead the product landscape due to mature degradation-pathway data, yet metal stents—particularly magnesium platforms—represent the fastest-expanding segment as manufacturers resolve early-generation corrosion-control limitations. Among end users, hospitals retain the deepest margin pools through bundled procurement of stent-plus-delivery systems, while cardiac centers are capturing the highest volume growth as outpatient percutaneous coronary intervention capabilities expand.
The FDA governs premarket approval pathways in the United States, requiring extensive longitudinal data on late lumen loss and target-lesion failure before granting commercial authorization. The EMA coordinates centralized MDR conformity assessments across EU member states, with notified bodies in Germany and the Netherlands conducting the bulk of technical documentation reviews. Japan's PMDA maintains distinct bioresorption-rate validation standards that shape Japan-specific trial designs. Stakeholders must monitor how evolving equivalence criteria for predicate devices alter the cost and duration of regulatory submissions across these jurisdictions.
Market Dynamics
Polymer degradation kinetics documentation under EU MDR Article 10 is compressing approval timelines and forcing manufacturers to consolidate clinical evidence packages before notified body submission windows close.
Growth Catalysts
- EU MDR resorption-data mandates:Centralized CE marking requirements under the EU Medical Device Regulation are eliminating fragmented national approvals, reducing redundant clinical trials across Germany, France, and the Netherlands.
- Cardiac center outpatient expansion:Ambulatory percutaneous coronary intervention capabilities in Western European hospitals are creating dedicated bioresorbable stent procurement budgets separate from metallic stent contracts.
- Magnesium alloy corrosion control:Resolved early-generation pitting limitations in magnesium platforms are unlocking faster resorption profiles for patients requiring shorter dual-antiplatelet therapy duration.
Market Restraints
- PLLA raw material concentration:Poly-L-lactic acid supply chains cluster among three specialty polymer producers in Germany and Switzerland, exposing stent manufacturers to input cost volatility and allocation risk.
- PMDA bioresorption-rate divergence:Japan's Pharmaceuticals and Medical Devices Agency maintains distinct validation standards requiring Japan-specific trial designs, fragmenting global clinical development programs.
- Metallic drug-eluting stent substitution:Established cobalt-chromium platforms with decade-long safety databases continue capturing price-sensitive hospital procurement tenders in Southern Europe.
Strategic Opportunities
- Eastern European reimbursement maturation:Poland and Czech Republic are piloting diagnosis-related group carve-outs for bioresorbable scaffolds, creating first-mover positioning ahead of full national reimbursement.
- Polymer-magnesium hybrid architectures:Converging PLLA structural layers with magnesium radiopaque markers is enabling thinner strut profiles without sacrificing fluoroscopic visibility during deployment.
- Direct-to-catheterization-lab distribution:Bypassing traditional hospital procurement committees through specialized cardiovascular distributor networks is reducing tender friction and accelerating adoption in high-volume cardiac centers.
Industry Challenges
- Bioresorption kinetics modeling expertise:The scarcity of computational chemists capable of predicting polymer molecular weight decay curves in vivo is extending product development cycles and inflating R&D compensation costs.
- Notified body queue congestion:Technical documentation reviews for MDR Class III devices at German and Dutch designated bodies are stretching submission-to-certificate timelines, delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioresorbable Coronary Stents Market |
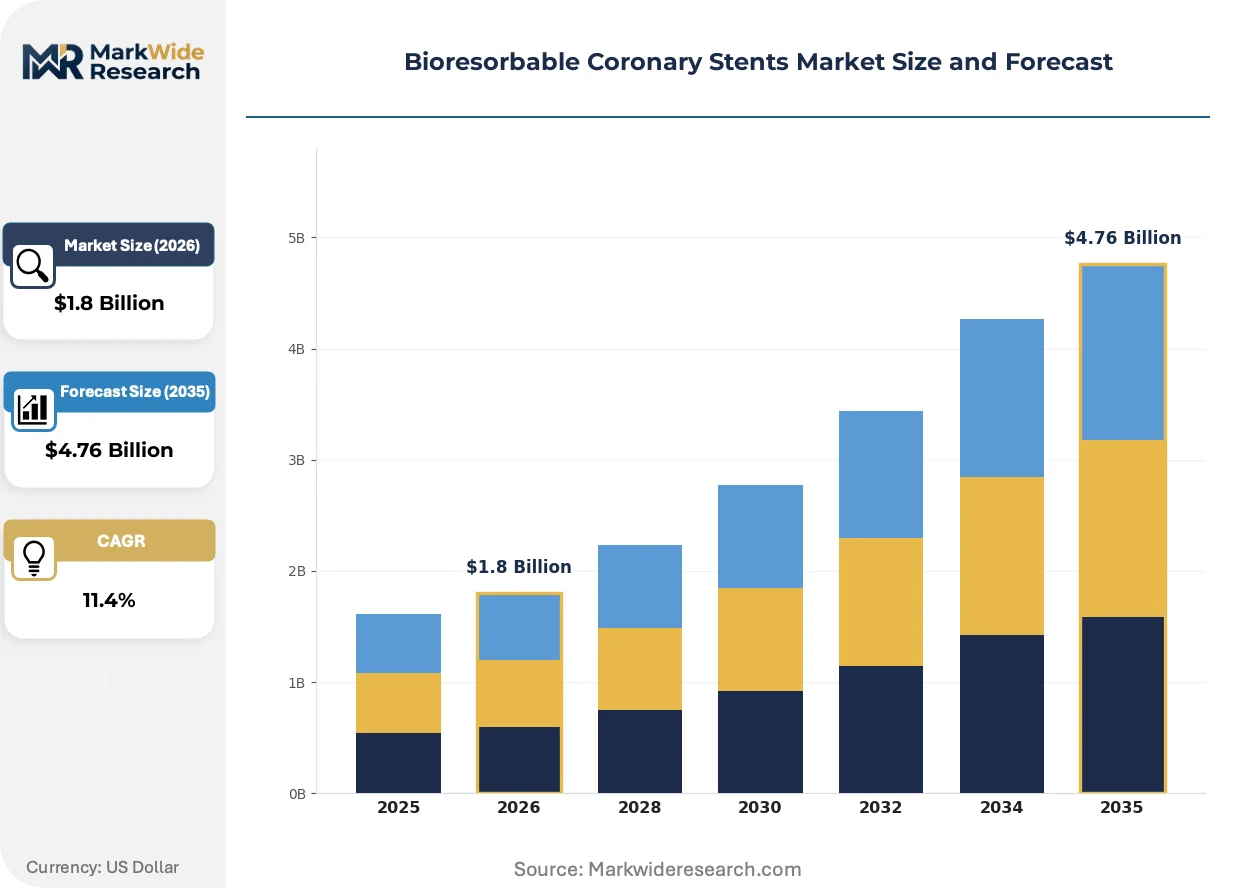
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based Stents, Metal Stents, Hybrid Stents, Coated Stents Delivery Mode: Transcatheter, Balloon-expandable, Self-expanding, Manual End User: Hospitals, Cardiac Centers, Specialty Clinics, Research Institutions Indication: Coronary Artery Disease, Angina, Myocardial Infarction, Others |
| Companies Covered | Boston Scientific Corporation, Terumo Corporation, MicroPort Scientific Corporation, BIOTRONIK, REVA Medical, Elixir Medical Corporation, Abbott Laboratories, Lepu Medical, Meril Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioresorbable Coronary Stents Market Evolving Landscape
Strut thickness reduction and radiopacity enhancement are converging to reshape competitive positioning, with manufacturers racing to demonstrate non-inferiority against latest-generation metallic platforms in head-to-head optical coherence tomography studies.
Polymer-magnesium hybrid stent platforms are miniaturizing strut dimensions below 100 microns while maintaining radial strength through selective magnesium alloy reinforcement at hinge points. High-volume cardiac centers in Germany and the Netherlands are adopting these platforms for complex bifurcation lesions where deliverability determines procedural success. The structural consequence is compressing the performance gap with cobalt-chromium benchmarks, forcing metallic stent manufacturers to defend position through price concessions rather than clinical differentiation.
CE marking under the EU Medical Device Regulation is rotating as the decisive gate for commercial entry, with only manufacturers demonstrating sustained biocompatibility and resorption-kinetics documentation securing approval timelines. Industrial consequence includes consolidation of notified body relationships, as stent manufacturers abandon multi-body strategies to concentrate resources on single technical documentation packages. Western European cardiac centers are responding by tightening vendor qualification criteria to prioritize MDR-certified suppliers with demonstrated post-market surveillance infrastructure.
Hospital procurement committees are unbundling stent-plus-delivery system contracts, separating device pricing from catheter and guidewire bundles that previously obscured true stent costs. Specialized cardiovascular distributors are displacing general hospital supply agreements in France and Belgium, offering consignment inventory and procedure-based replenishment. This channel shift is most visible in Belgium, where cardiac center networks have consolidated purchasing through preferred distributor partnerships that guarantee same-day delivery for emergency interventions.
Bioresorbable Coronary Stents Market Segmentation
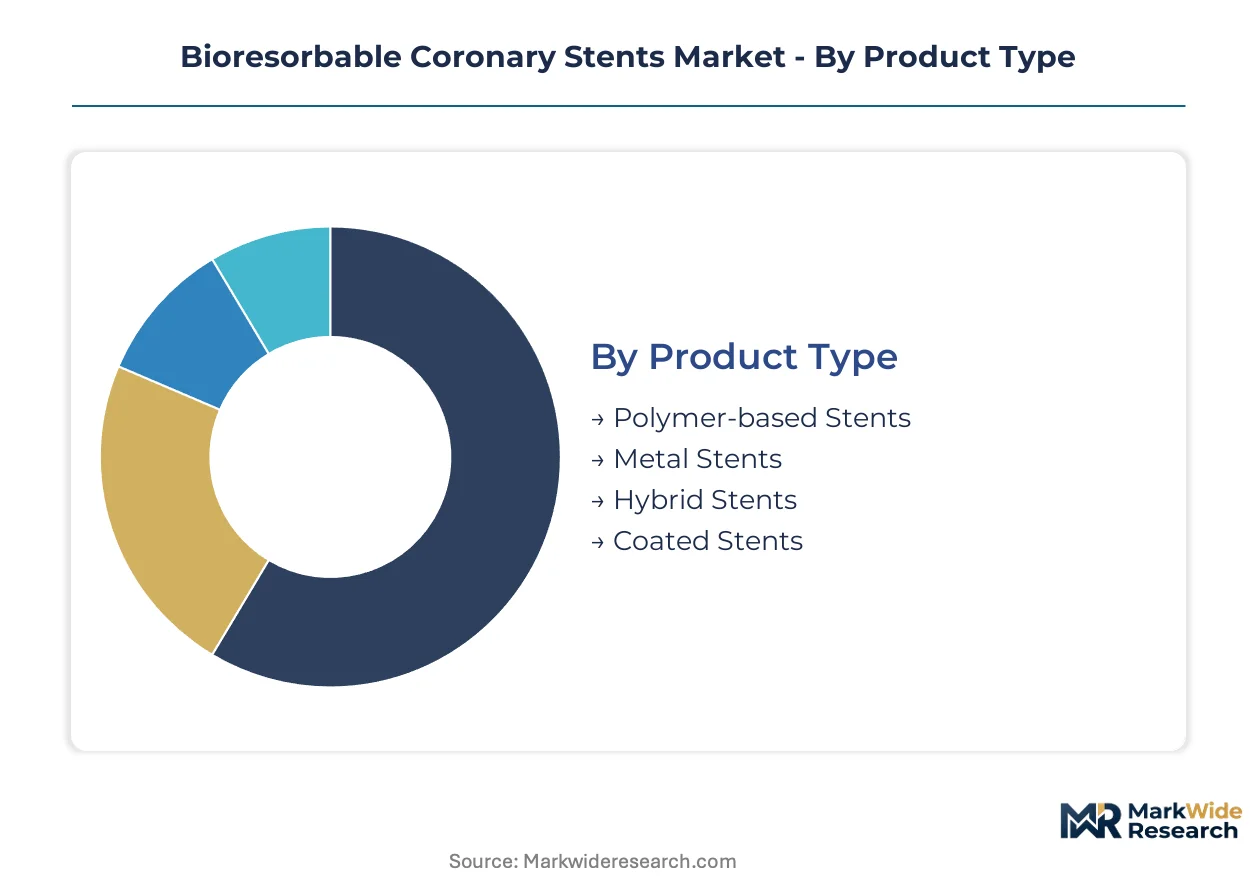
Bioresorbable coronary stent procurement patterns diverge sharply across clinical settings and lesion complexity, with polymer platforms dominating Western European cardiac centers while metal alloys capture emerging markets seeking shorter dual-antiplatelet protocols. Understanding these segment boundaries reveals where manufacturers must align technical specifications with reimbursement pathways and procedural workflows.
Product Type:
German and Swiss manufacturing clusters supply polymer-based platforms to domestic cardiac centers, while magnesium alloy development concentrates in export-oriented facilities serving Japan and South Korea.
- Polymer-based Stents:Fabricated from poly-L-lactic acid (PLLA) or polyglycolic acid (PGA), these scaffolds degrade through hydrolysis into lactic acid metabolites over 24-36 months. Demand clusters in German and Dutch catheterization labs where MDR-certified suppliers control procurement relationships and long-term resorption data satisfies notified body surveillance requirements.
- Metal Stents:Magnesium alloy platforms corrode through controlled electrochemical dissolution, offering complete absorption within 12-18 months with faster endothelialization. Japanese cardiac centers are driving volume expansion here as PMDA bioresorption-rate standards favor predictable magnesium degradation kinetics over polymer hydrolysis variability.
- Hybrid Stents:PLLA structural layers combined with magnesium radiopaque markers enable sub-100-micron strut profiles.
- Coated Stents:Drug-eluting surface modifications on polymer or metal substrates target restenosis reduction in complex lesions.
Polymer-based stents hold the largest share; momentum sits with metal stents.
Delivery Mode:
Cost tiering separates premium integrated delivery systems from economy manual configurations, with bundled pricing obscuring true device margins in hospital procurement tenders.
- Transcatheter:Integrated catheter-stent systems with pre-mounted scaffolds on rapid-exchange or over-the-wire platforms enable single-operator deployment. Cardiac centers in Belgium and France are consolidating purchasing through specialized distributors offering consignment inventory and procedure-based replenishment for these systems.
- Balloon-expandable:Crimped stent-on-balloon configurations deliver precise diameter expansion against calcified lesions. German catheterization labs favor these platforms for bifurcation procedures where controlled expansion determines side-branch patency.
- Self-expanding:Nickel-titanium or shape-memory polymer stents deploy without balloon inflation in tortuous anatomy.
- Manual:Bare stent crimping onto physician-selected balloons offers lowest unit cost for price-sensitive tenders.
Transcatheter systems command premium positioning; balloon-expandable configurations are gaining share fastest in complex lesion applications.
End User:
Volume concentration differs from margin capture, with hospitals retaining deepest procurement pools while cardiac centers generate steepest growth trajectories through outpatient percutaneous coronary intervention expansion.
- Hospitals:Integrated health systems bundle stent procurement with catheter, guidewire, and contrast agent contracts, obscuring true device costs in consolidated tenders. Bundled payment structures in France and Germany incentivize metallic stent substitution for price-sensitive episodes.
- Cardiac Centers:Dedicated interventional cardiology facilities with ambulatory surgery designation are carving out separate bioresorbable stent budgets distinct from metallic stent contracts. Western European centers in the Netherlands and Germany lead this unbundling trend.
- Specialty Clinics:Private outpatient facilities concentrate on diagnostic angiography with selective intervention capabilities.
- Research Institutions:Academic medical centers conduct head-to-head optical coherence tomography studies against metallic benchmarks.
Hospitals hold the largest share; momentum sits with cardiac centers.
Indication:
Maturity gradients separate established coronary artery disease applications from emerging acute myocardial infarction protocols where resorption kinetics must align with healing timelines.
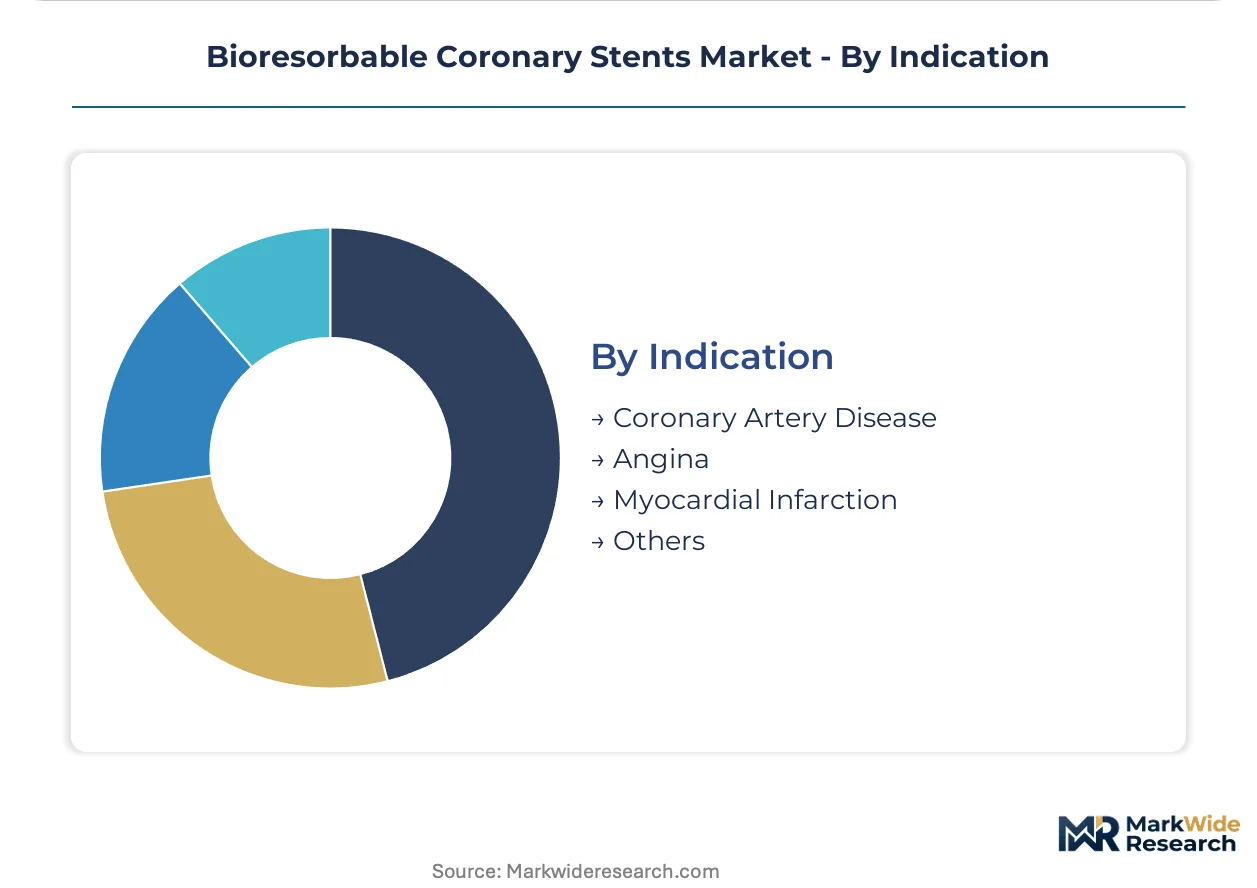
- Coronary Artery Disease:Stable atherosclerotic lesions in single or multivessel presentations constitute the bulk of elective percutaneous coronary intervention volume. German reimbursement pathways for bioresorbable scaffolds have matured earliest for this indication category.
- Angina:Symptomatic ischemia without acute infarction drives elective stenting in cardiac centers with rapid patient turnover.
- Myocardial Infarction:Acute ST-elevation and non-ST-elevation presentations require stent platforms with immediate radial strength and predictable endothelialization. Magnesium alloy platforms are penetrating this segment as shorter dual-antiplatelet therapy duration reduces bleeding risk in polypharmacy patients.
- Others:In-stent restenosis and saphenous vein graft lesions represent niche applications.
Coronary artery disease holds the largest share; myocardial infarction represents the fastest-expanding indication as acute protocols adopt bioresorbable platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Medical Device Regulation reimbursement carve-outs are accelerating cardiac center procurement across Western Europe, while Japan's PMDA maintains distinct bioresorption-rate validation standards that fragment global clinical development timelines.
Germany
Bavarian catheterization labs in Munich and Erlangen are expanding bioresorbable scaffold volumes under streamlined G-BA reimbursement pathways. CE marking under EU MDR Article 10 compresses approval timelines for polymer-based platforms. BIOTRONIK's manufacturing scale in Bülach anchors regional supply relationships with cardiac centers in Baden-Württemberg.
United States
Cleveland Clinic and Mayo Clinic cardiac centers are piloting magnesium alloy platforms for complex bifurcation lesions. FDA premarket approval pathways require extensive longitudinal data on late lumen loss before granting commercial authorization. Boston Scientific Corporation leverages vascular portfolio depth to anchor clinical trial infrastructure across Midwestern sites.
Japan
Tokyo and Osaka cardiac centers are driving magnesium alloy volume expansion as PMDA bioresorption-rate standards favor predictable degradation kinetics. Japan-specific trial designs fragment global clinical development programs for polymer platforms. Terumo Corporation's domestic manufacturing presence reinforces catheterization lab supply relationships in Kanto and Kansai regions.
Netherlands
Amsterdam and Rotterdam cardiac centers are consolidating purchasing through specialized distributors offering consignment inventory for transcatheter systems. Dutch notified bodies conduct bulk technical documentation reviews under EMA-coordinated MDR conformity assessments. Unbundled procurement contracts separate stent pricing from catheter bundles in university hospital networks.
China
Shanghai and Beijing tertiary hospitals are evaluating polymer-magnesium hybrid architectures for sub-100-micron strut profiles. NMPA biocompatibility documentation requirements are converging toward EU MDR standards for imported platforms. MicroPort Scientific Corporation and Lepu Medical anchor domestic manufacturing capacity in Jiangsu and Guangdong provinces.
Bioresorbable Coronary Stents Market Competitive Landscape
Player mix skews toward diversified cardiovascular conglomerates with polymer formulation expertise and specialized scaffold manufacturers with magnesium alloy capabilities. Tiered competition separates MDR-certified suppliers with post-market surveillance infrastructure from emerging entrants navigating notified body queue congestion. Strategic archetypes include integrated device-delivery system architects, polymer degradation kinetics specialists, and regional manufacturing scale players. Dominant competitive moves center on MDR technical documentation consolidation and direct-to-catheterization-lab distribution partnerships.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation and Abbott Laboratories occupy positions as integrated platform architects with vascular portfolio breadth. BIOTRONIK exemplifies the regional manufacturing scale archetype through German production infrastructure. Terumo Corporation anchors the Asia-Pacific specialist tier with domestic Japanese regulatory navigation capabilities. These three entities represent divergent strategic postures: integrated R&D depth, geographic manufacturing concentration, and regional regulatory specialization.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| BIOTRONIK |
| REVA Medical |
| Elixir Medical Corporation |
| Abbott Laboratories |
| Lepu Medical |
| Meril Life Sciences |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Swiss polymer synthesis facilities shapes both input cost floors and manufacturer pricing power across the bioresorbable stent value chain. MDR certification timelines compress procurement windows, forcing cardiac centers to absorb premium pricing for CE-marked inventory while manufacturers face margin pressure from PLLA raw material allocation constraints.
Pricing Analysis
Certification level creates the primary spread between MDR-certified polymer platforms and uncertified metal alternatives awaiting notified body review. Three-tier pricing structure across MDR-premium, transitional-standard, and economy-manual configurations separates integrated delivery systems from bare stent configurations. Pricing pressure stems from metallic drug-eluting stent substitution in Southern European hospital tenders. Hospitals exhibit highest price sensitivity through bundled procurement committees, while cardiac centers accept premium positioning for outpatient procedure efficiency.
Supply Chain Analysis
Strategic stockpiling of PLLA resin dominates inventory strategy as German and Swiss specialty polymer producers control global supply. Manufacturing concentration in Germany, Switzerland, and Japan feeds downstream catheterization labs through specialized cardiovascular distributors. Raw material dependencies center on poly-L-lactic acid monomer, magnesium alloy billets, and radiopaque marker compounds. Single-source vulnerability in PLLA precursor supply exposes manufacturers to allocation risk during notified body submission surges. Distribution runs through preferred distributor partnerships guaranteeing same-day emergency delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational modeling expertise for bioresorption kinetics prediction represents the critical capability gap constraining product development velocity and inflating R&D compensation costs across the competitive landscape.
For Market Incumbents: Fortify notified body relationships through concentrated technical documentation packages rather than fragmented multi-body strategies. Secure captive PLLA supply agreements with German and Swiss polymer producers to defend against raw material allocation risk during MDR submission windows. Channel control through direct-to-catheterization-lab distribution partnerships displaces general hospital supply agreements. For New Entrants and Emerging Players: Lead with polymer-magnesium hybrid architectures targeting Eastern European markets where Poland and Czech Republic pilot diagnosis-related group carve-outs ahead of full national reimbursement. The most penetrable white space sits in acute myocardial infarction protocols where magnesium platforms reduce dual-antiplatelet therapy duration. Position through specialized cardiovascular distributors offering consignment inventory and procedure-based replenishment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with demonstrated MDR post-market surveillance infrastructure over early-stage platform developers facing notified body queue congestion. Long-term viability hinges on computational chemistry capabilities for in vivo molecular weight decay prediction. The acquisition target archetype combines polymer formulation expertise with established CE marking relationships. Watch magnesium alloy corrosion-control resolution rates as the inflection indicator for platform substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Consolidation | Single-body submission strategies compress approval timelines at German and Dutch notified bodies. |
| Polymer-Magnesium Hybrid Platform Development | Sub-100-micron strut profiles with selective magnesium reinforcement close performance gaps with cobalt-chromium benchmarks. |
| Direct-to-Catheterization-Lab Distribution Partnership | Specialized cardiovascular distributors in Belgium and France bypass hospital procurement committee friction. |
| PLLA Raw Material Supply Security | Captive agreements with German and Swiss polymer producers mitigate allocation risk during submission surges. |
| Japan-Specific Trial Design Investment | PMDA bioresorption-rate validation standards favor predictable magnesium degradation kinetics over polymer variability. |
Research Methodology
A standing panel of interventional cardiologists, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA premarket approval filings, EMA MDR submission databases, ClinicalTrials.gov entries, and hospital procurement contract registries. Bottom-up demand modeling across cardiac center volumes and top-down supply validation against manufacturing capacity disclosures were triangulated to converge estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and indication complexity alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves applied to base-year estimates. Forecast inputs incorporated MDR certification timeline assumptions and PMDA bioresorption-rate validation standards.
The analysis sits within stated boundaries; outcomes outside sustained MDR approval throughput or PLLA supply stability would require recalibration. Forecasts reflect documented assumptions regarding notified body queue resolution and cardiac center outpatient expansion trajectories. Revision becomes warranted when metallic drug-eluting stent substitution rates or magnesium corrosion-control breakthroughs cross threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Cardiac Cryoablation Device Market