
 Asia-Pacific Kyphoplasty Market | 2026-2036
Asia-Pacific Kyphoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Kyphoplasty Market Insights
Multi-source procurement for bone cement and balloons is hardening as hospital networks across the Asia-Pacific region diversify supplier relationships to mitigate disruption risk. Medtronic leverages its integrated spine platform to sustain premium positioning in Japan and Australia. Stryker anchors its regional footprint through dedicated kyphoplasty training centers for interventional radiologists in South Korea and India.
Kyphoplasty is a minimally invasive surgical procedure that restores vertebral body height using an inflatable bone tamp followed by injection of polymethyl methacrylate cement under image guidance, typically performed under local or general anesthesia with fluoroscopic monitoring. The intervention stabilizes fractured vertebrae, relieves pain from vertebral compression fractures, and prevents progressive spinal deformity in osteoporotic or pathologic bone. Bone cement generates the dominant revenue stream due to recurring consumption per procedure, while fluoroscopy-based technology leads procedural volume owing to widespread cath lab availability and lower capital requirements than navigation systems. Ambulatory surgical centers represent the fastest-expanding end user channel as same-day discharge protocols gain acceptance across Thailand, Malaysia, and Taiwan.
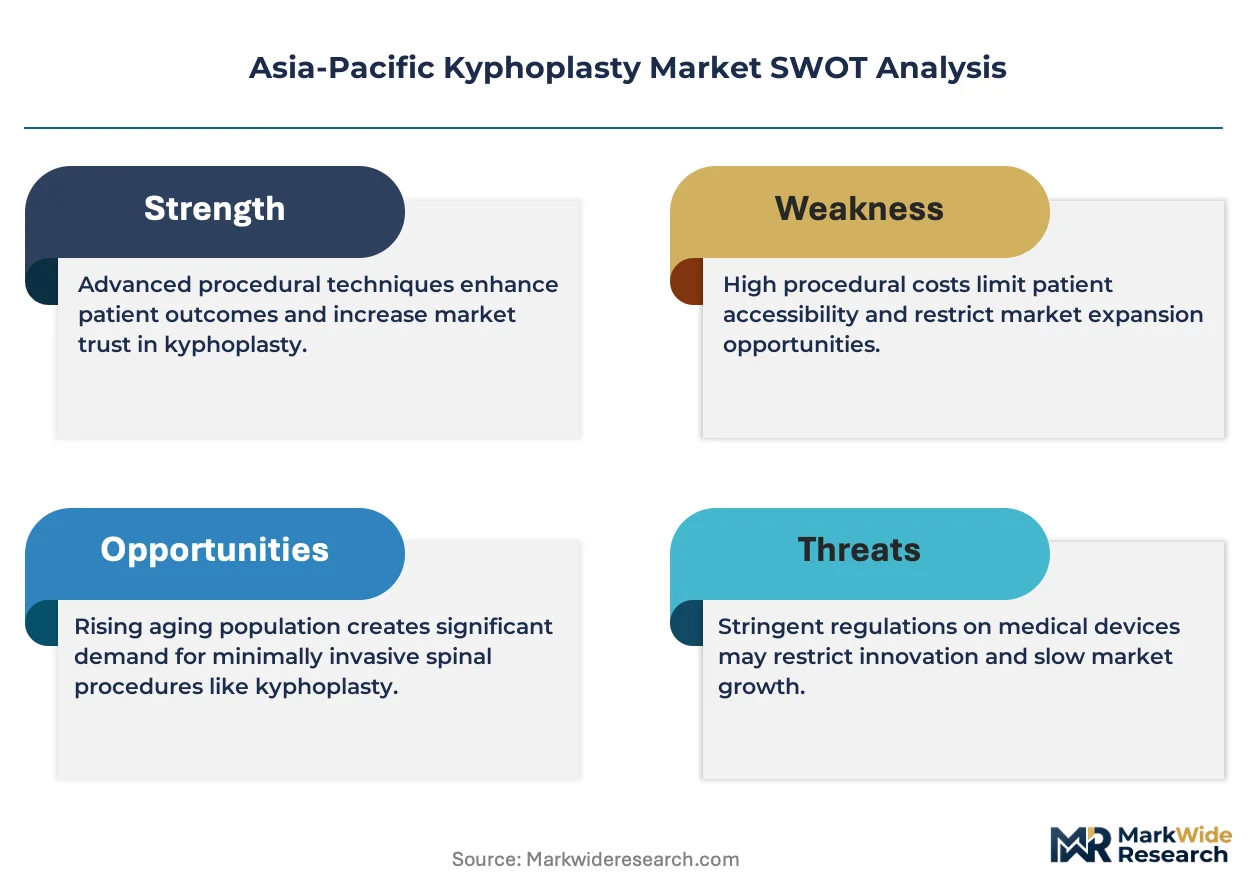
Japan's PMDA, Australia's TGA, and China's NMPA each enforce distinct biocompatibility and mechanical performance standards for bone cement, creating fragmented compliance obligations that favor manufacturers with dedicated regulatory affairs teams in each jurisdiction. India's CDSCO has tightened import licensing for orthopedic implants, prompting domestic assembly partnerships among multinational suppliers. Stakeholders must monitor reimbursement harmonization negotiations between ASEAN member states, as unified coverage decisions would reshape patient access and manufacturer prioritization across Southeast Asian markets.
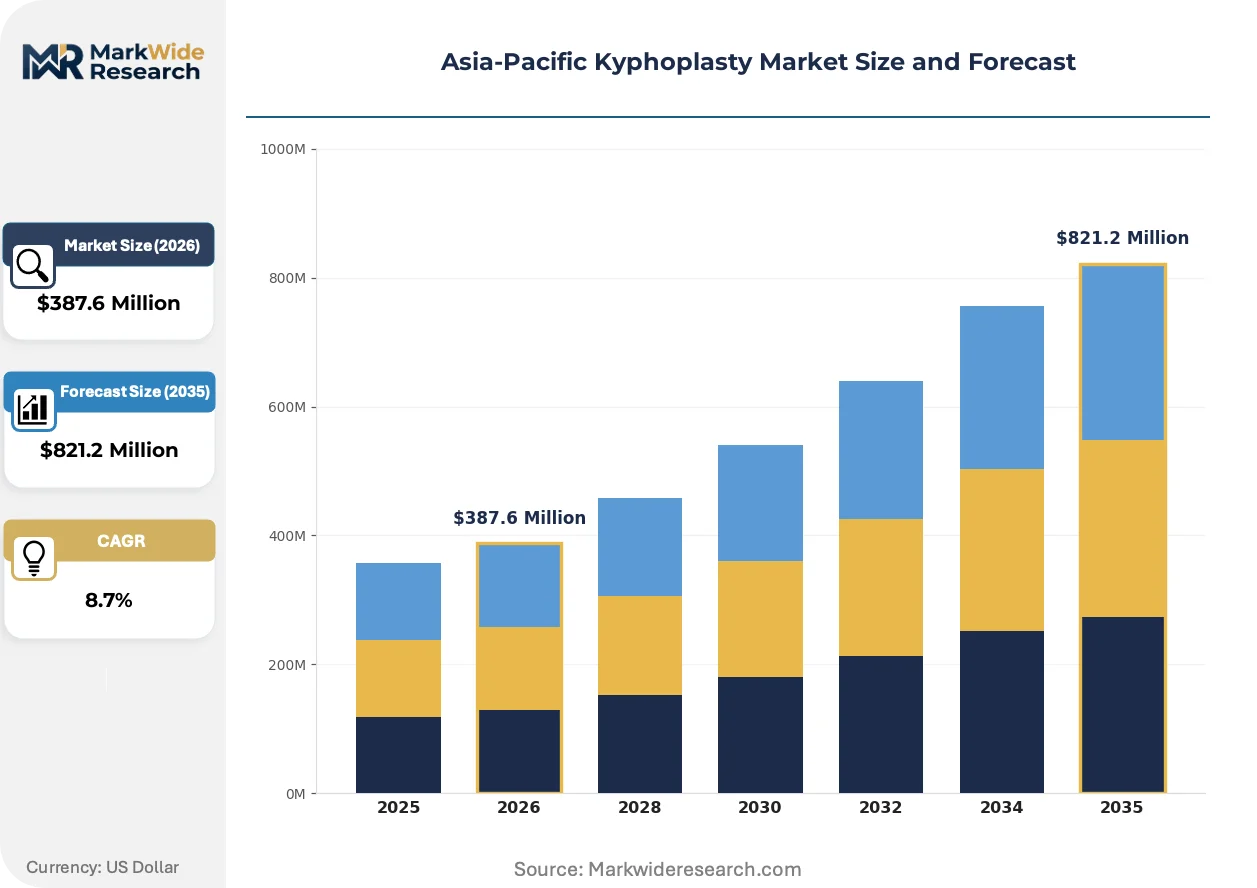
Market Dynamics
Vertebral compression fracture volumes across China, Japan, and South Korea are accelerating procedural demand for kyphoplasty, while hospital procurement consolidation in Australia and Thailand is compressing vendor margins and forcing supplier diversification strategies.
Growth Catalysts
- Aging demographics in China:The country's expanding geriatric population is generating sustained clinical need for osteoporotic fracture intervention, with provincial hospitals scaling spine surgery departments to capture rising caseloads.
- PMDA streamlined pathways:Japan's pharmaceutical and medical device agency has reduced orthopedic device registration timelines, accelerating market entry for next-generation bone cement formulations and inflatable tamp systems.
- Fluoroscopy infrastructure:Widespread cath lab availability across South Korea and Taiwan enables low-capital kyphoplasty deployment, expanding procedural access beyond tertiary academic centers into community hospital networks.
Market Restraints
- PMMA price volatility:Methyl methacrylate monomer supply disruptions from petrochemical feedstock fluctuations are squeezing bone cement manufacturing economics and pressuring hospital contract renegotiations.
- Import licensing friction:India's CDSCO has tightened orthopedic implant import controls, forcing multinational suppliers into domestic assembly partnerships that extend lead times and compliance costs.
- Conservative management substitution:Bracing protocols and bisphosphonate pharmacotherapy retain strong clinician adherence in rural Vietnam and Indonesia, limiting procedural penetration outside urban corridors.
Strategic Opportunities
- Malaysia ambulatory expansion:Same-day discharge protocols are gaining regulatory acceptance in Kuala Lumpur and Penang, positioning ambulatory surgical centers as high-margin channel alternatives to inpatient settings.
- Navigation-fluoroscopy convergence:Hybrid image-guidance systems combining 3D navigation with conventional fluoroscopy are opening premium positioning for precision kyphoplasty in Japanese and Australian private hospital groups.
- ASEAN reimbursement harmonization:Ongoing coverage negotiation frameworks between member states could unify patient access standards, enabling manufacturers to prioritize Southeast Asian markets with scaled distribution investments.
Industry Challenges
- Interventional radiologist training pipelines:South Korea and India face acute shortages of specialists credentialed for percutaneous vertebral augmentation, constraining procedural volume growth despite installed base expansion.
- Tri-jurisdictional compliance burden:Divergent biocompatibility standards enforced by Japan's PMDA, Australia's TGA, and China's NMPA require dedicated regulatory affairs teams, elevating fixed costs for market participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Kyphoplasty Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Cement, Instrumentation, Injectors, Accessories End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, Specialty Clinics Application: Vertebral Fractures, Osteoporosis Treatment, Pain Management, Tumor Treatment Technology: Fluoroscopy, CT Guidance, Navigation Systems, Ultrasound |
| Companies Covered | Medtronic, Stryker, DePuy Synthes, Merit Medical Systems, IZI Medical Products, Joimax GmbH, Joline GmbH & Co. KG, Johnson & Johnson, Globus Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Kyphoplasty Market Trends and Innovations
Radiopaque bone cement formulations and augmented fluoroscopy systems are displacing conventional workflows across the Asia-Pacific kyphoplasty landscape, compressing procedure times while elevating precision requirements for surgical teams.
Radio-opaque barium sulfate loading in next-generation PMMA cements is integrating real-time visualization capabilities that reduce cement leakage risk during vertebral body filling. Tertiary hospitals in Tokyo, Shanghai, and Sydney are adopting these formulations at accelerated procurement cycles. The technology is integrating risk-mitigation protocols into standard-of-care guidelines, forcing legacy cement suppliers to reformulate or cede premium positioning.
China's NMPA has tightened mechanical performance testing requirements for orthopedic bone cements under revised GB standards, mandating fatigue resistance documentation that exceeds prior biocompatency-only submissions. Domestic manufacturers in Suzhou and Shenzhen are absorbing extended validation timelines, while multinational suppliers with established testing infrastructure are capturing accelerated approvals. Imported premium cement categories are consolidating market presence as local competitors retest formulations.
Hospital network procurement in Thailand, Malaysia, and Taiwan is consolidating vendor relationships into dual-source frameworks that unbundle device and consumable purchasing. Interventional radiology departments in Bangkok and Kuala Lumpur are negotiating direct balloon catheter contracts separate from bone cement supply agreements. This pattern is most visible in Taiwan's National Health Insurance contracted facilities, where procurement officers are compressing supplier rosters to extract volume discounts.
Asia-Pacific Kyphoplasty Market Segmentation
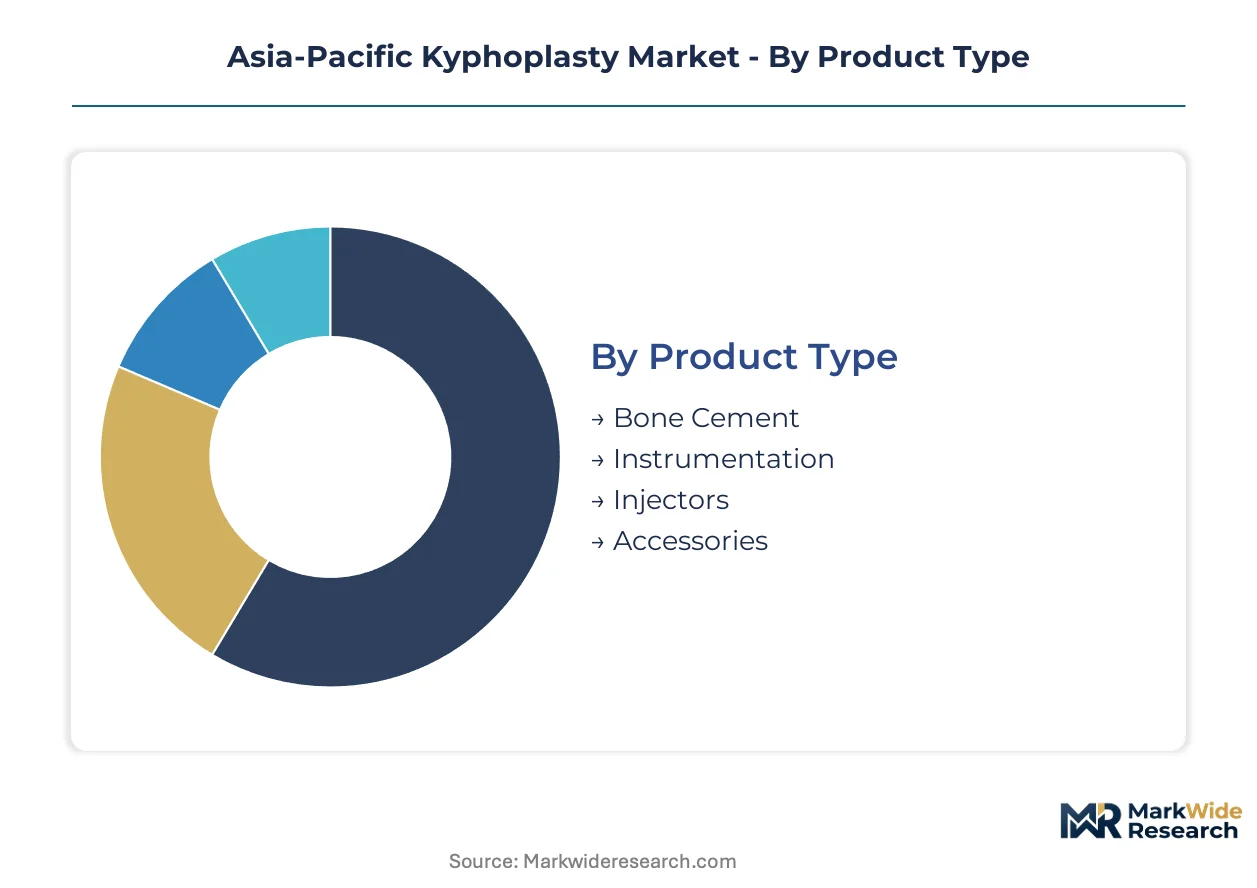
Kyphoplasty market segmentation reveals divergent procurement patterns across the Asia-Pacific region. Hospital networks prioritize consumable economics while ambulatory channels emphasize capital efficiency. Understanding these splits enables targeted positioning for bone cement suppliers and device manufacturers.
Product Type:
Buyer differentiation hinges on recurring consumption versus durable equipment procurement cycles.
- Bone Cement:Polymethyl methacrylate formulations loaded with radiopaque barium sulfate dominate procedural economics through per-case consumption. Provincial hospitals across China and Japan negotiate multi-year cement supply agreements to lock in pricing amid methyl methacrylate monomer volatility.
- Instrumentation:Inflatable bone tamps and vertebral access tools represent capital investments with 3-5 year replacement cycles. Australian private hospital groups are consolidating instrumentation purchases into bundled spine platform contracts with integrated service coverage.
- Injectors:Disposable cement delivery systems with controlled-flow mechanisms reduce extravasation risk during vertebral filling. South Korean distributors stock high-volume injector SKUs for same-day cath lab procedures.
- Accessories:Mixing bowls, cement preparation kits, and sterile drapes complete procedural sets. Thai hospital procurement officers unbundle accessory purchasing from device contracts to capture volume discounts through generic sourcing.
Volume sits with Bone Cement; growth tilts toward Instrumentation as hybrid navigation-fluoroscopy systems penetrate Japanese and Australian tertiary centers.
End User:
Site-of-care economics separate inpatient reimbursement frameworks from outpatient efficiency models.
- Hospitals:Tertiary and secondary acute care facilities perform complex kyphoplasty cases requiring overnight observation. China's provincial hospitals are scaling dedicated spine surgery departments to capture aging-driven vertebral compression fracture volumes.
- Ambulatory Surgical Centers:Same-day discharge protocols in Kuala Lumpur, Penang, and Taipei enable high-margin outpatient kyphoplasty. Malaysia's Ministry of Health has streamlined ASC licensing for vertebral augmentation procedures.
- Rehabilitation Centers:Post-procedural recovery facilities manage mobility restoration protocols. Japan's geriatric rehabilitation networks coordinate with acute hospitals for bundled osteoporosis fracture care pathways.
- Specialty Clinics:Interventional radiology and pain management practices perform select cases outside hospital systems. India's metro area specialty clinics are acquiring refurbished fluoroscopy units to capture direct-pay kyphoplasty volume.
Procedure concentration remains in Hospitals; expansion accelerates most quickly in Ambulatory Surgical Centers as regulatory acceptance spreads across Southeast Asia.
Application:
Clinical indication severity determines reimbursement tiering and technology selection intensity.
- Vertebral Fractures:Acute osteoporotic and traumatic compression fractures constitute the core kyphoplasty indication. China's NMPA has aligned mechanical performance testing requirements with vertebral fracture stabilization outcomes under revised GB standards.
- Osteoporosis Treatment:Prophylactic vertebral augmentation in high-risk geriatric patients combines with bisphosphonate pharmacotherapy. Japan's PMDA streamlined orthopedic device registration pathways accelerate next-generation cement approvals for osteoporotic bone.
- Pain Management:Refractory vertebral pain without clear fracture progression drives diagnostic kyphoplasty demand. Taiwan's National Health Insurance covers pain-management kyphoplasty under restricted prior authorization protocols.
- Tumor Treatment:Pathologic vertebral body stabilization for metastatic disease requires cement augmentation with tumor ablation. Australian private oncology centers are adopting navigation-guided kyphoplasty for precise tumor margin targeting.
Case volume clusters in Vertebral Fractures; steepest expansion trajectory appears in Tumor Treatment as hybrid ablation-augmentation protocols gain reimbursement traction.
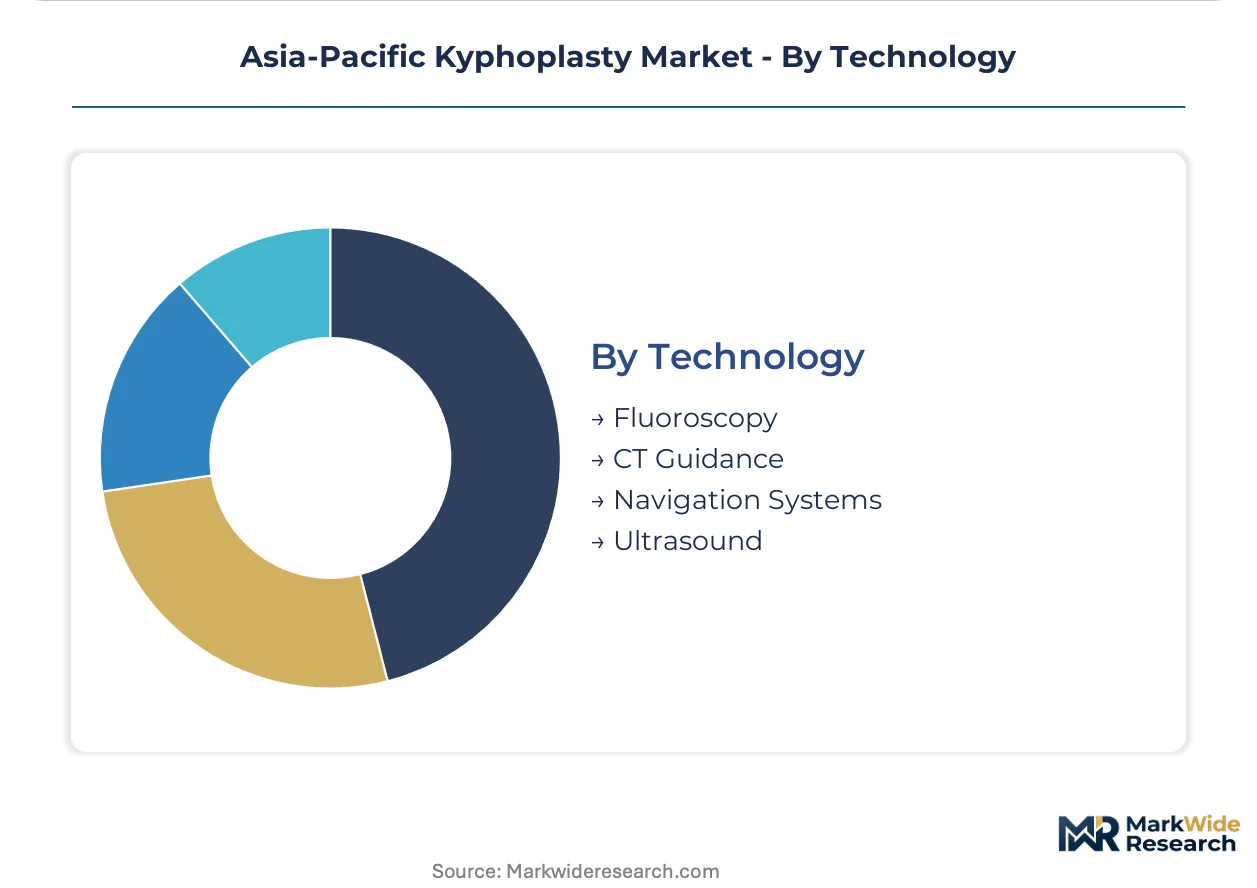
Technology:
Capital deployment thresholds and precision requirements segment technology adoption across facility tiers.
- Fluoroscopy:Real-time X-ray guidance leverages existing cath lab infrastructure with minimal incremental capital. Widespread fluoroscopy availability across South Korea and Taiwan enables community hospital kyphoplasty deployment.
- CT Guidance:Pre-procedural planning and intraoperative cone-beam CT improve cement trajectory planning. China's tertiary centers are integrating CT-fluoroscopy fusion systems for complex multi-level vertebral augmentation.
- Navigation Systems:Electromagnetic or optical tracking enables 3D trajectory planning with sub-millimeter accuracy. Japanese and Australian private hospital groups are piloting navigation-fluoroscopy convergence for premium positioning.
- Ultrasound:Emerging guidance modality for select vertebral access applications reduces radiation exposure. Research hospitals in Sydney and Tokyo are evaluating ultrasound-assisted kyphoplasty for pediatric and pregnant patient populations.
Installed base concentrates in Fluoroscopy; Navigation Systems are gaining share fastest as precision requirements intensify in premium private hospital segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methyl methacrylate monomer supply chains from South Korean and Japanese petrochemical complexes anchor bone cement manufacturing economics across the Asia-Pacific kyphoplasty landscape.
China
Provincial hospitals in Jiangsu and Guangdong are scaling dedicated spine surgery departments to capture rising vertebral compression fracture caseloads from aging demographics. NMPA's revised GB standards mandate fatigue resistance documentation for orthopedic bone cements, extending validation timelines for domestic manufacturers in Suzhou and Shenzhen. Shanghai's tertiary medical centers are piloting CT-fluoroscopy fusion systems for complex multi-level vertebral augmentation procedures.
Japan
PMDA streamlined orthopedic device registration pathways accelerate market entry for next-generation bone cement formulations and inflatable tamp systems. Tokyo's geriatric rehabilitation networks coordinate with acute hospitals for bundled osteoporosis fracture care pathways. Kansai region private hospital groups are adopting navigation-fluoroscopy convergence systems for premium precision kyphoplasty positioning.
South Korea
Widespread cath lab availability enables community hospital kyphoplasty deployment beyond tertiary academic centers. MFDS regulatory frameworks align with international biocompatibility standards for bone cement approvals. Seoul Capital Area distributors stock high-volume injector SKUs for same-day interventional radiology procedures.
Australia
TGA biocompatibility and mechanical performance standards create compliance obligations favoring manufacturers with dedicated regulatory affairs teams. Private hospital groups in Sydney and Melbourne are consolidating instrumentation purchases into bundled spine platform contracts. Research hospitals in Sydney evaluate ultrasound-assisted kyphoplasty for pediatric and pregnant patient populations.
India
CDSCO tightened orthopedic implant import controls force multinational suppliers into domestic assembly partnerships extending lead times. Metro area specialty clinics in Mumbai and Delhi acquire refurbished fluoroscopy units to capture direct-pay kyphoplasty volume. Interventional radiologist training pipelines face acute specialist shortages constraining procedural growth despite installed base expansion.
Asia-Pacific Kyphoplasty Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and distribution infrastructure. The Asia-Pacific kyphoplasty market structures around three tiers: integrated spine platform vendors, specialized vertebral augmentation device manufacturers, and domestic assembly partners serving import-restricted markets. Consolidation pressures intensify as hospital procurement networks compress vendor rosters into dual-source frameworks. Strategic moves center on dedicated training center establishment for interventional radiologist credentialing and multi-year cement supply agreements locking in pricing amid methyl methacrylate volatility.
Among integrated platform vendors, Medtronic and Stryker exemplify contrasting regional anchoring strategies. Medtronic leverages its spine platform for premium positioning in Japan and Australia. Stryker anchors through dedicated kyphoplasty training centers for interventional radiologists in South Korea and India. Merit Medical Systems occupies a position among specialized vertebral augmentation device manufacturers with focused interventional radiology channel penetration.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| DePuy Synthes |
| Merit Medical Systems |
| IZI Medical Products |
| Joimax GmbH |
| Joline GmbH & Co. KG |
| Johnson & Johnson |
| Globus Medical |
| Others |
Pricing and Supply Chain Analysis
Methyl methacrylate monomer feedstock from South Korean and Japanese petrochemical complexes flows through bone cement manufacturing tiers, with pricing stratifying across premium radiopaque formulations, standard PMMA cements, and economy unbranded alternatives as hospital procurement networks consolidate vendor rosters.
Pricing Analysis
Warranty and service bundling separates integrated spine platform contracts from unbundled consumable purchasing, with Australian private hospital groups negotiating multi-year instrumentation agreements covering preventive maintenance while Thai procurement officers split balloon catheter and cement supply into distinct tenders. Price differentiation hinges on PMDA registration status versus unregistered imports, with NMPA fatigue-testing certification commanding measurable premiums. Cost compression in economy cement tiers is intensifying because provincial Chinese hospitals are forcing annual contract renegotiations. Public hospital networks in Vietnam and Indonesia exhibit the highest price sensitivity, while Japanese tertiary centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Barium sulfate radiopacifier supply rests on Chinese specialty chemical producers and German pharmaceutical-grade suppliers, with inflatable tamp manufacturing concentrated in Germany, the United States, and Japan. Raw material dependencies include methyl methacrylate monomer, surgical-grade stainless steel, and medical-grade silicone for balloon membranes. Single-source vulnerability in barium sulfate loading creates exposure to China's export licensing fluctuations for strategic minerals. Distribution runs through South Korean and Indian distributors holding regional inventory positions for same-day cath lab fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across Southeast Asia and Australia is compressing vendor margins, forcing subscale manufacturers into exit or acquisition scenarios as dual-source frameworks become mandatory.
For Market Incumbents: To counter unbundled procurement strategies from Bangkok to Kuala Lumpur, cement suppliers should deepen backward integration into methyl methacrylate monomer production through captive South Korean petrochemical partnerships, while instrumentation vendors must secure multi-year service contracts with Australian private hospital groups to lock in replacement cycles. For New Entrants and Emerging Players: Begin with India's metro area specialty clinics acquiring refurbished fluoroscopy units, where CDSCO import friction has created domestic assembly partnerships as the most penetrable entry channel, then layer direct-pay kyphoplasty services before seeking hospital system contracts. For Investors and Strategic Acquirers: ASEAN reimbursement harmonization negotiations reaching draft framework agreement is the leading indicator that scaled distribution investments will yield priority market positioning, suggesting five-to-ten year viability for regional logistics platforms serving vertebral augmentation devices, with acquisition targets clustering around Indian domestic assembly partners holding CDSCO licenses and South Korean distributor networks with MFDS-aligned inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation-Fluoroscopy Convergence Development | Hybrid systems enable premium positioning in Japanese and Australian private hospital groups. |
| Domestic Assembly Partnership Formation | CDSCO-compliant Indian manufacturing sidesteps import licensing friction for multinational suppliers. |
| Interventional Radiologist Training Center Establishment | Credentialing pipelines in South Korea and India address specialist shortages constraining volume growth. |
| Radiopaque Cement Formulation Reformulation | Barium sulfate loading integrates real-time visualization into Tokyo and Shanghai standard-of-care protocols. |
| Ambulatory Surgical Center Licensing Strategy | Malaysia's Ministry of Health streamlined ASC protocols enable same-day discharge margin capture. |
Research Methodology
Document review covered PMDA orthopedic device registration filings, NMPA GB standard revisions, and ASEAN procurement tender databases, complemented by interviews with interventional radiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineering directors across China, Japan, South Korea, and Australia. Secondary validation drew from customs trade records, TGA biocompatibility guidance documents, and CDSCO import licensing bulletins. Bottom-up procedure volume estimates triangulated against top-down bone cement consumption data from South Korean and Japanese petrochemical disclosures.
Cross-referencing historical procurement cycle patterns with panel input from distributor inventory managers and spine platform commercial leads anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user site-of-care economics, clinical application severity, and image-guidance technology tier. CAGRs were derived from procedure volume trajectories weighted by cement consumption per case and navigation system replacement cycles, incorporating NMPA mechanical testing timeline impacts and PMDA streamlined pathway acceleration effects.
PMMA monomer supply disruptions, ASEAN reimbursement negotiation delays, and interventional radiologist training pipeline bottlenecks are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions about regulatory timeline adherence and hospital procurement consolidation velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market