
 Global Syringes and Needles Market | 2026-2036
Global Syringes and Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Syringes and Needles Market Foresight
Chinese polymer-to-device manufacturers is expanding sterile injection device output to serve government stockpiling programs across Southeast Asia. Becton, Dickinson and Company leverages backward integration into precision molding to sustain margin control across safety-engineered product lines. B. Braun Melsungen anchors European hospital supply chains through dedicated production facilities in Germany and Malaysia. Terumo Corporation differentiates via proprietary silicone-coating technology that reduces needlestick friction during vascular access procedures.
Syringes and needles constitute single-use hollow instruments engineered from medical-grade polypropylene barrels, stainless-steel cannulas, and bonded elastomer plunger tips, manufactured through high-speed injection molding and automated needle-assembly processes to enable sterile parenteral drug administration and fluid extraction. Prefilled syringes command premium positioning as biologics manufacturers seek to eliminate dosing errors and reduce preparation time in clinical settings. Safety needles attract regulatory-driven replacement demand as OSHA bloodborne pathogen standards and EU sharps directives mandate engineered injury-protection features across hospital procurement contracts.
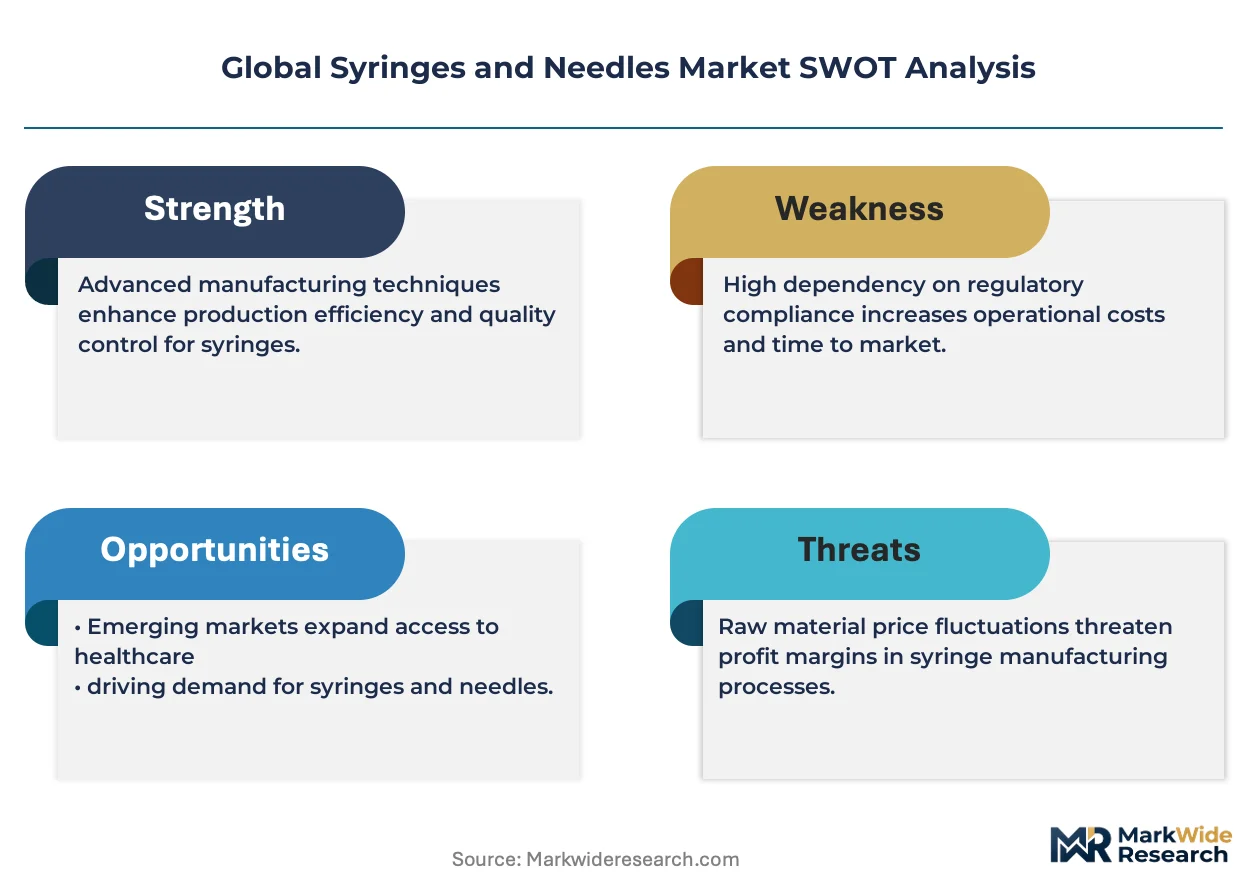
The FDA enforces Quality System Regulation and 510(k) premarket notification requirements that govern device biocompatibility and sterility assurance levels for US market entry. EMA's Medical Device Regulation imposes Unique Device Identification and post-market surveillance obligations that extend compliance costs for non-European manufacturers seeking CE marking. WHO prequalification standards shape procurement eligibility for multilateral vaccine programs in low-income countries. Stakeholders must monitor evolving polymer supply constraints and sterilization capacity bottlenecks as electrification of ethylene production reshapes feedstock economics for disposable medical plastics.
Market Dynamics
Safety-engineered device mandates are compressing procurement timelines across hospital systems, forcing rapid conversion from conventional to retractable and shielded needle designs that satisfy OSHA bloodborne pathogen standards and EU sharps directives simultaneously.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturers receive production-linked incentives that expand sterile syringe output for government immunization programs and export markets across Southeast Asia.
- WHO prequalification standards:Multilateral vaccine procurement eligibility hinges on meeting these benchmarks, channeling investment into quality systems for manufacturers serving Gavi and UNICEF supply contracts.
- Prefilled syringe adoption for biologics:Biopharma manufacturers specify these formats to eliminate dosing errors and reduce preparation time in oncology and autoimmune therapy administration.
Market Restraints
- Polypropylene feedstock volatility:Electrification of ethylene production is reshaping polymer economics, creating margin pressure for high-volume disposable device manufacturers dependent on medical-grade resin supply.
- Sterilization capacity bottlenecks:Gamma and ethylene oxide sterilization facilities concentrate in Germany, the United States, and Japan, limiting geographic diversification options for manufacturers seeking redundant processing pathways.
- EMA MDR compliance costs:Unique Device Identification and post-market surveillance obligations extend certification timelines and documentation burdens for non-European manufacturers pursuing CE marking.
Strategic Opportunities
- Home healthcare self-injection:Diabetes and hormone therapy patients are migrating from clinic-based administration to autoinjector and pen needle formats that enable subcutaneous drug delivery without professional supervision.
- Silicone-coating technology convergence:Proprietary lubrication processes that reduce needlestick friction during vascular access are creating differentiation vectors for manufacturers serving interventional cardiology and dialysis segments.
- Government stockpiling programs:Pandemic preparedness initiatives across Indonesia, Vietnam, and the Philippines are generating multi-year supply contracts for sterile injection devices held in strategic reserves.
Industry Challenges
- Precision molding talent scarcity:High-speed injection molding of polypropylene barrels with tight dimensional tolerances requires specialized toolmaking expertise that concentrates in southern Germany and western Japan.
- 510(k) notification timelines:FDA premarket review for safety-engineered needle designs extends development cycles, compressing competitive response windows when rivals introduce novel injury-prevention mechanisms.
- Legacy ERP integration:Automated needle-assembly lines must interface with existing manufacturing execution systems, creating data architecture friction during facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Syringes and Needles Market |
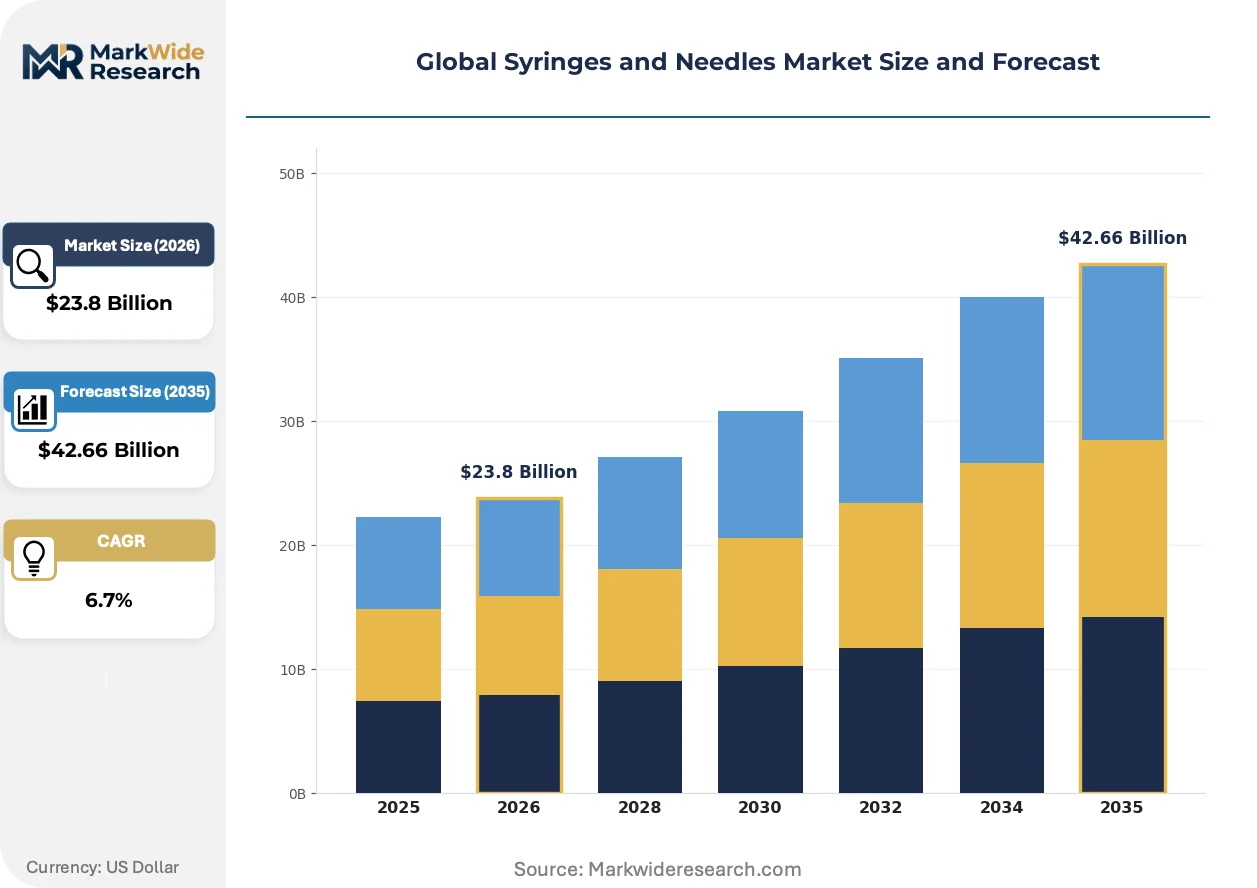
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypodermic Syringes, Safety Needles, Insulin Syringes, Auto-Disable Syringes, Prefilled Syringes Application: Vaccination, Diabetes Management, Anesthesia, Blood Sampling, Drug Delivery End User: Hospitals, Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Blood Banks Packaging Type: Blister Pack, Bulk Pack, Sterile Individual Wrap, Vial Pack, Cartridge Pack |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen, Terumo Corporation, Cardinal Health, Nipro Corporation, Smiths Medical, Embecta Corp., Hindustan Syringes & Medical Devices Ltd., Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Syringes and Needles Market Shifts & Advancements
Digital traceability systems and passive safety mechanisms are converging to reshape how sterile injection devices are specified, tracked, and deployed across healthcare networks. These shifts are compressing supplier qualification cycles while elevating performance requirements.
Passive safety needle designs that deploy protective shields without user activation are decentralizing injury-prevention responsibility from healthcare workers to device engineering. Hospital systems in California and Texas are specifying these formats for nursing staff protection. The technology is decentralizing procurement authority from centralized materials management to infection control committees that prioritize staff safety metrics.
EMA's Medical Device Regulation imposes Unique Device Identification mandates that extend from manufacturing through point-of-care scanning. European hospital networks must now reconcile device serial numbers with patient electronic health records. Safety syringe manufacturers serving Germany, France, and Italy are restructuring labeling operations to embed machine-readable codes at production speeds exceeding 600 units per minute.
Consolidated buying groups are displacing individual hospital contracting for safety-engineered devices across the United States. Integrated delivery networks in Pennsylvania and Ohio are aggregating demand across 15-40 facilities to extract volume pricing from manufacturers. This concentration is most visible in the Midwest, where Catholic health systems and for-profit chains have centralized procurement decisions to regional supply chain offices.
Global Syringes and Needles Market Segmentation
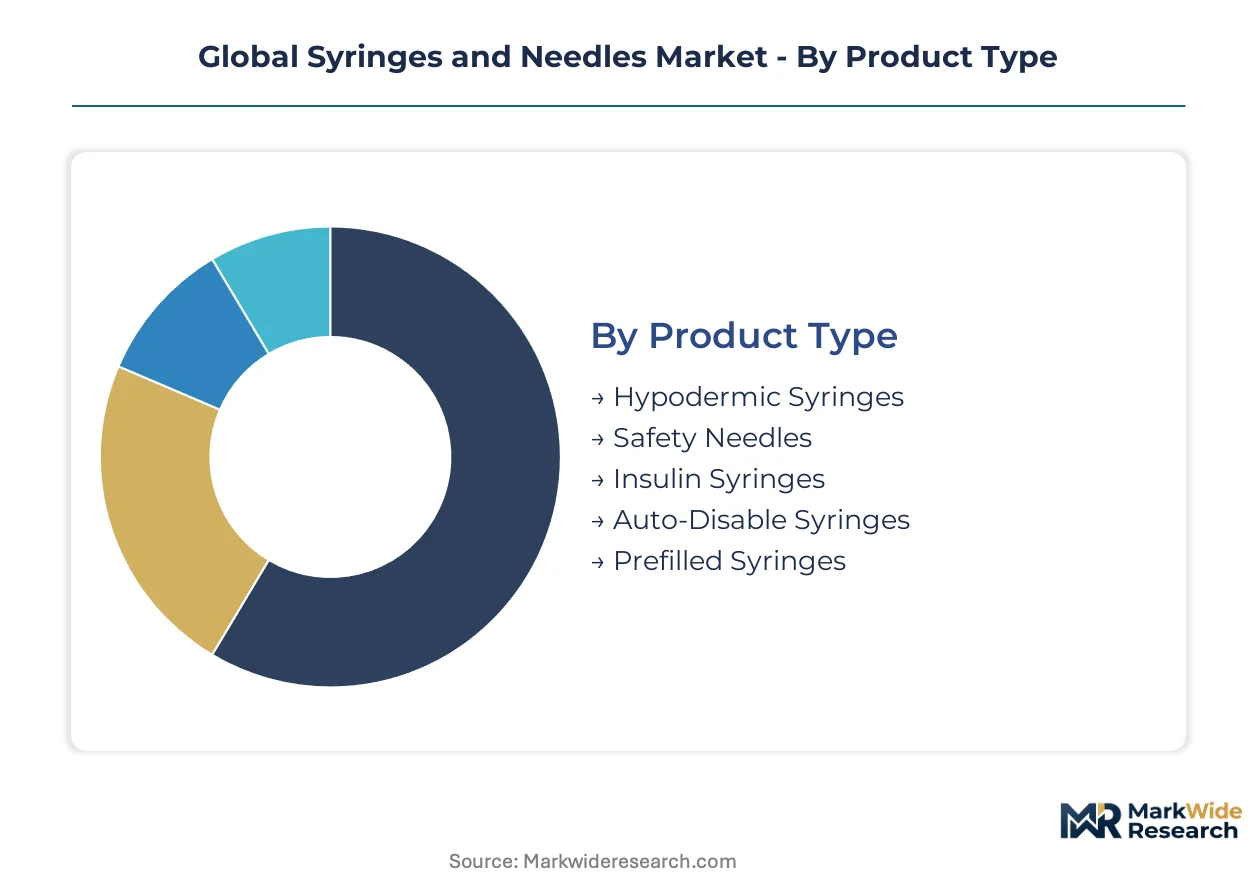
Device specification, clinical application, and procurement channel each create distinct margin profiles and compliance requirements across sterile injection markets. Manufacturers configure production lines around specific segment demands rather than pursuing undifferentiated volume.
Product Type:
Technical sophistication separates commodity formats from premium-engineered devices, with safety mechanisms and prefill integration commanding distinct pricing tiers.
- Hypodermic Syringes:Standard Luer-lock polypropylene barrels with bonded stainless-steel cannulas serve general-purpose fluid administration across hospital wards and outpatient clinics. Demand concentrates in India's government immunization infrastructure, where CDSCO-mandated quality standards for domestic procurement have tightened resin purity specifications.
- Safety Needles:Retractable and shielded designs incorporate passive or active injury-prevention mechanisms that satisfy OSHA bloodborne pathogen standards and EU sharps directives. Procurement in California and Texas hospital systems is converting rapidly to these formats as nursing unions negotiate staff protection clauses into supply contracts.
- Insulin Syringes:Low-dead-space U-100 calibrated barrels with permanently attached 29-31 gauge needles enable precise subcutaneous dosing for diabetes patients. Home healthcare channels in Germany and Japan specify these for self-administration programs.
- Auto-Disable Syringes:Single-use mechanical locks prevent retraction and reuse, meeting WHO prequalification requirements for Gavi-funded vaccine campaigns across sub-Saharan Africa and Southeast Asia.
- Prefilled Syringes:Glass or cycloolefin polymer barrels preloaded with biologics eliminate dosing errors and reduce preparation time in oncology infusion centers.
Hypodermic syringes lead on scale; prefilled syringes lead on momentum.
Application:
Clinical setting determines sterility assurance levels, volume requirements, and device complexity, with chronic disease management creating recurring demand streams distinct from acute intervention.
- Vaccination:High-volume disposable syringes with fixed-needle designs serve mass immunization campaigns and routine pediatric schedules. UNICEF procurement specifications drive demand concentration in India and Indonesia, where PLI scheme incentives have expanded domestic sterile output for export eligibility.
- Diabetes Management:Pen needles and insulin syringes enable multiple daily subcutaneous injections for Type 1 and insulin-dependent Type 2 patients. Home healthcare adoption in the United States and Germany is accelerating as pharmacy benefit managers expand self-injection reimbursement.
- Anesthesia:Spinal and epidural needles with proprietary tip geometries reduce post-dural puncture headache incidence in surgical settings. European hospital networks specify these for orthopedic and obstetric procedures.
- Blood Sampling:Vacutainer-compatible needles and winged infusion sets serve phlebotomy and donor collection workflows. Diagnostic laboratory consolidation in Japan and South Korea is standardizing procurement around safety-engineered formats.
- Drug Delivery:Specialty needles for intramuscular, intravenous, and intrathecal routes support biologics administration in hospital infusion centers.
Vaccination dominates procurement volume; diabetes management expands most quickly through home healthcare channels.
End User:
Facility type dictates purchasing authority, safety mandate intensity, and inventory turnover velocity, with integrated delivery networks centralizing decisions across multi-site health systems.
- Hospitals:Acute care facilities with centralized materials management specify safety-engineered devices across emergency, surgical, and medical-surgical units. OSHA compliance audits in US hospital systems are accelerating conversion from conventional to retractable needle designs.
- Clinics:Outpatient and primary care settings with lower patient acuity prioritize cost-efficient standard syringes for routine injections. India's Ayushman Bharat health centers are expanding sterile device procurement under government supply contracts.
- Diagnostic Laboratories:High-throughput phlebotomy operations require winged infusion sets and multi-sample needles with consistent penetration performance. German and Japanese reference laboratories specify silicone-coated cannulas to reduce hemolysis rates.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited storage space favor compact packaging and pre-assembled sterile kits. US Medicare reimbursement policies shape device selection for outpatient arthroscopy and ophthalmology.
- Blood Banks:Donor collection networks require large-gauge needles with minimal vessel trauma for whole blood and apheresis procedures.
Hospitals concentrate procurement authority; ambulatory surgical centers are gaining share fastest through outpatient procedure migration.
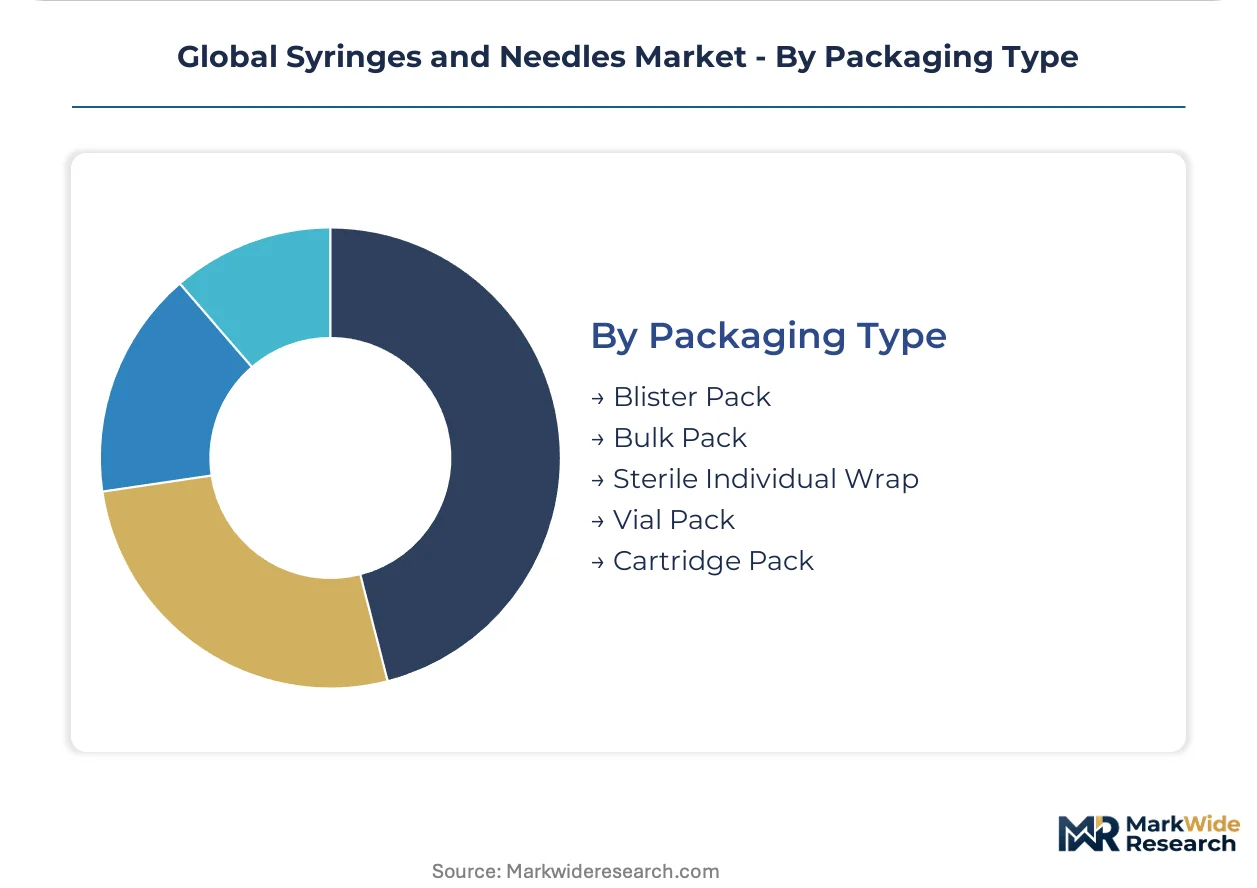
Packaging Type:
Unit economics and sterility maintenance requirements vary sharply with packaging configuration, influencing logistics costs and point-of-care workflow efficiency.
- Blister Pack:Individual thermoformed cavities with Tyvek lids provide tamper-evident sterile barriers for single-unit dispensing in emergency and operating room settings. US hospital pharmacies specify these for controlled substance syringes requiring chain-of-custody documentation.
- Bulk Pack:Polyethylene bags containing 25-100 non-sterile or terminally sterilized units minimize per-unit packaging cost for high-volume purchasers. India's government immunization warehouses utilize bulk formats for district-level distribution.
- Sterile Individual Wrap:Peel-apart pouches with chevron seals enable aseptic presentation in surgical and interventional suites. Japanese hospital infection control committees mandate these for invasive procedures.
- Vial Pack:Pre-assembled syringe-needle combinations with medication vials reduce preparation steps in chemotherapy and biologics administration.
- Cartridge Pack:Pen needle cartridges and autoinjector cassettes support chronic disease self-management in home healthcare.
Bulk pack leads on scale; sterile individual wrap leads on momentum through infection control prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's government immunization infrastructure absorbs syringe volumes comparable to entire European hospital networks, while Germany's sterilization facility concentration creates supply chain dependencies that Southeast Asian manufacturers actively circumvent.
United States
OSHA bloodborne pathogen standards and nursing union contract clauses are accelerating hospital conversions to retractable needle designs across California and Texas health systems. FDA 510(k) notification timelines extend development cycles for safety-engineered devices. The Midwest integrated delivery network corridor spanning Pennsylvania and Ohio concentrates procurement authority through consolidated buying groups.
Germany
EMA Medical Device Regulation compliance costs and Unique Device Identification mandates reshape labeling operations for manufacturers serving hospital networks in Bavaria and North Rhine-Westphalia. Sterilization capacity concentrates in Frankfurt and Munich industrial zones. B. Braun Melsungen anchors European supply chains through dedicated production facilities in Melsungen and Penang.
India
CDSCO-mandated quality standards for domestic procurement and PLI scheme production-linked incentives expand sterile syringe output for government immunization programs and UNICEF export eligibility. Ayushman Bharat health centers drive demand across Maharashtra and Gujarat manufacturing clusters. Hindustan Syringes & Medical Devices Ltd. exemplifies domestic capacity expansion.
Japan
METI industrial policy and PMDA quality frameworks support silicone-coating technology development for vascular access applications. Home healthcare self-injection programs in Tokyo and Osaka metropolitan areas accelerate pen needle adoption. Terumo Corporation's proprietary lubrication processes reduce needlestick friction in interventional cardiology segments.
China
NMPA medical device registration requirements and government stockpiling programs across Southeast Asia expand sterile injection device output from Yangtze River Delta manufacturing bases. Polymer-to-device producers in Jiangsu and Zhejiang provinces serve pandemic preparedness initiatives in Indonesia and Vietnam. Domestic manufacturers compete for Gavi and UNICEF supply contract eligibility.
Global Syringes and Needles Market Competitive Landscape
United States and German producers anchor the premium safety-engineered tier; Japanese and Indian specialists hold differentiated positions in coating technology and high-volume immunization supply respectively. The vendor structure concentrates around three strategic archetypes: integrated multinationals with backward integration into precision molding, regional champions serving government procurement channels, and technology specialists with proprietary surface treatments. Competitive dynamics center on M&A consolidation among mid-cap sterilization service providers and capacity expansion into redundant gamma processing corridors.
Within the integrated multinational tier, Becton, Dickinson and Company and B. Braun Melsungen exemplify backward integration strategies that sustain margin control across safety-engineered product lines. Terumo Corporation occupies a specialist position anchored by proprietary silicone-coating technology. These three entities represent distinct competitive vectors: precision molding dominance, European hospital supply chain anchoring, and vascular access friction reduction respectively.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen |
| Terumo Corporation |
| Cardinal Health |
| Nipro Corporation |
| Smiths Medical |
| Embecta Corp. |
| Hindustan Syringes & Medical Devices Ltd. |
| Teleflex |
| Others |
Supply & Pricing Matrix
Backward integration into precision molding anchors both supply security and margin control for safety-engineered device manufacturers serving US and European hospital networks. Polypropylene resin procurement and captive sterilization capacity determine pricing power across retractable needle and prefilled syringe tiers, with OSHA compliance mandates converting procurement specifications faster than cost curves can flatten.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard hypodermic syringes serving government immunization contracts and UNICEF export eligibility. Three-tier pricing structure across premium safety-engineered, standard Luer-lock, and economy bulk-pack formats separates FDA 510(k)-cleared devices from CDSCO-mandated domestic procurement tiers. Cost compression in the economy segment is intensifying because PLI scheme subsidies attract new domestic entrants. Government procurement offices exhibit highest price sensitivity; biopharma manufacturers specifying prefilled syringes for biologics administration show lowest.
Supply Chain Analysis
Medical-grade polypropylene supply rests on petrochemical complexes in Saudi Arabia, South Korea, and the US Gulf Coast, with electrification of ethylene production reshaping feedstock economics. Stainless-steel cannula wire draws from specialty steel producers in Germany and Japan; silicone lubricants for coating processes concentrate with chemical specialists in the Tokyo-Osaka corridor. Single-source vulnerability runs through gamma sterilization facilities concentrated in Frankfurt, Munich, and Chicago industrial zones. Distribution runs through consolidated buying groups in the US Midwest and government medical supply corporations in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory conversion waves, with OSHA bloodborne pathogen standards and EU MDR compliance deadlines forcing rapid device replacement cycles across hospital procurement contracts.
For Market Incumbents: Hedge sterilization capacity concentration by establishing redundant ethylene oxide processing corridors in Southeast Asia, insulating against single-facility regulatory shutdowns. Anchor margin control through backward integration into medical-grade polypropylene compounding, countering resin price volatility from electrification-driven feedstock shifts. Prioritize FDA 510(k) notification pipeline density to compress competitive response windows when rivals introduce novel injury-prevention mechanisms. For New Entrants and Emerging Players: The price-point gap between premium safety-engineered devices and economy bulk-pack syringes creates white-space opportunity for mid-tier retractable needle formats serving India's Ayushman Bharat health centers and Southeast Asian government stockpiling programs. Target silicone-coating technology licensing for vascular access applications, where interventional cardiology and dialysis segments reward friction-reduction performance. Pursue WHO prequalification pathway as go-to-market anchor for Gavi and UNICEF supply contract eligibility. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap sterilization service providers because gamma and ethylene oxide facility scarcity concentrates bargaining power with device manufacturers seeking geographic redundancy. Five-to-ten year viability hinges on pandemic preparedness program durability across Indonesia, Vietnam, and the Philippines. Watch government stockpiling contract announcement velocity as inflection indicator for capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Notification | Accelerates market entry for retractable needle designs before OSHA compliance audits tighten. |
| CE Marking Pathway | Unlocks procurement eligibility across German and French hospital networks under MDR mandates. |
| Hospital System Partnership | Secures volume commitment from integrated delivery networks in Pennsylvania and Ohio corridors. |
| Backward Integration into Molding | Captures margin control for safety-engineered product lines serving premium tier specifications. |
| Reimbursement Strategy | Aligns autoinjector formats with US pharmacy benefit manager self-injection coverage expansion. |
Research Methodology
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterilization facility operators grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, WHO prequalification lists, and Indian CDSCO domestic procurement specifications. Bottom-up demand modeling triangulated against top-down macro healthcare expenditure trends across the analysis window.
Bottom-up segment modeling projected volume and value outputs across product type, application, end user, and packaging format dimensions, with geographic regulatory clusters layered as cross-cutting variable. CAGRs derived from iterative reconciliation between historical shipment data and forward-looking procurement contract visibility. Forecast inputs incorporated PLI scheme capacity expansion timelines and government stockpiling program announcement pipelines.
Caveats apply where polymer feedstock price volatility, sterilization facility regulatory actions, or pandemic preparedness budget reallocations could materially shift the outlook. Forecasts reflect assumptions about OSHA enforcement intensity and EU MDR notification backlog clearance. A small set of named triggers—gamma sterilization facility shutdowns, polypropylene supply disruption, or WHO prequalification standard revision—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Swab Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Suture Wire Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Lavage Kits Market
Medical Supplies
North America Intravenous Solutions Market