
 Vertebroplasty Needles Market | 2026-2036
Vertebroplasty Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebroplasty Needles Market Analytics
A shift from single-source procurement to multi-source qualification is pivoting how hospital systems evaluate vertebroplasty needle suppliers. Medtronic plc leverages its spine portfolio breadth to sustain contracted access across integrated delivery networks. Stryker Corporation anchors its position through dedicated interventional spine sales infrastructure in major metropolitan markets.
Vertebroplasty needles are percutaneous instruments engineered from stainless steel or polymer composites, typically ranging from 11 to 13 gauge with beveled or diamond tips designed to penetrate cortical bone while minimizing cement extravasation during polymethylmethacrylate delivery. Their commercial purpose centers on restoring vertebral body height and stabilizing compression fractures in osteoporotic or pathological bone. Bone biopsy needles command the mature volume base in product type segmentation, while coated steel variants in material segmentation capture expanding margin pools due to enhanced fluoroscopic visibility. Ambulatory surgical centers represent the fastest-growing end user channel as same-day spine procedures migrate from inpatient settings.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation burdens for manufacturers serving dual markets. ISO 13485 quality system compliance and ASTM F2077 testing standards further constrain design flexibility while elevating barriers for new entrants. Stakeholders must monitor how CMS reimbursement determinations for outpatient vertebral augmentation interact with hospital capital allocation priorities for interventional suites.
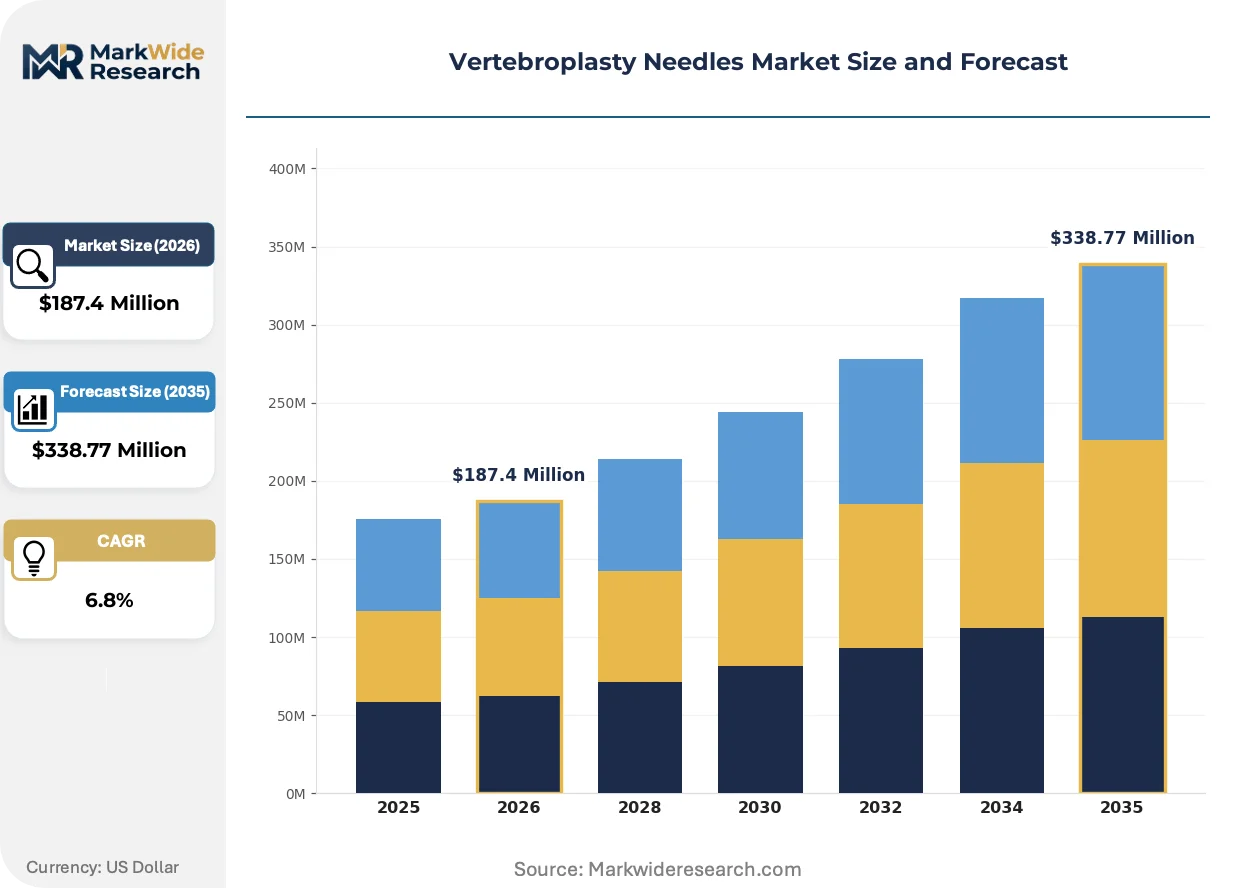
Market Dynamics
Hospital procurement consolidation and EU MDR technical documentation burdens are compressing supplier margins while elevating compliance costs for vertebroplasty needle manufacturers serving dual-regulated markets.
Growth Catalysts
- Aging demographics:Osteoporotic vertebral compression fracture incidence rises sharply in populations over 70, expanding the addressable patient base in Japan, Italy, and Germany.
- EU MDR Article 10:Strengthened post-market surveillance requirements for Class IIa devices accelerate replacement cycles for legacy needle inventories across German and French hospital networks.
- Fluoroscopic visibility coatings:Radiopaque polymer composites reduce procedural time and cement extravasation risk, driving preference shifts in interventional radiology departments.
Market Restraints
- Nickel-titanium alloy dependency:Superelastic needle shaft materials concentrate sourcing through a limited supplier base in Western Pennsylvania and Solingen, Germany.
- FDA 510(k) predicate limitations:Substantial equivalence pathways for novel tip geometries encounter reviewer pushback, extending clearance timelines by 8-14 months.
- Kyphoplasty balloon systems:Alternative vertebral augmentation techniques capture margin-rich cases in academic medical centers with hybrid operating suites.
Strategic Opportunities
- CMS ASC payment expansion:Outpatient vertebral augmentation reimbursement parity with hospital outpatient departments accelerates same-day procedure migration to ambulatory surgical centers in Texas and Florida.
- Biopsy-needle platform convergence:Dual-purpose instruments combining bone marrow aspiration with cement delivery address cost-containment pressures in integrated delivery networks.
- Saudi Vision 2030 healthcare privatization:Greenfield hospital construction in Riyadh and Jeddah creates first-mover advantages for interventional spine capital equipment suppliers.
Industry Challenges
- Sterilization validation bottlenecks:Ethylene oxide residual limits under ISO 10993-7 require redundant bioburden testing, compressing production throughput for gamma-sterilized needle lots.
- Interventional radiology fellowship scarcity:Vertebroplasty procedural volume growth outpaces accredited training program output in Midwestern and Southeastern US markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebroplasty Needles Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Biopsy Needles, Vertebroplasty Needles, Cannulae, Osteoporosis Needles Material: Stainless Steel, Polymer, Coated Steel, Composite Materials End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Specialty Clinics Application: Spinal Surgery, Pain Management, Biopsy Procedures, Tumor Treatment |
| Companies Covered | Medtronic plc, Stryker Corporation, DePuy Synthes Inc., Cook Medical LLC, Merit Medical Systems Inc., Globus Medical Inc., Argon Medical Devices Inc., OptiMed GmbH, Teknimed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebroplasty Needles Market Evolving Landscape
Material science advances and regulatory harmonization pressures are reshaping how vertebroplasty needles are designed, sterilized, and procured across hospital systems.
Carbon fiber-reinforced PEEK composite needle shafts are converging with traditional stainless steel platforms in premium device segments. Academic medical centers in Boston and Heidelberg pilot these instruments for MRI-guided procedures where metal artifacts obscure soft tissue visualization. This convergence is compressing the performance gap between polymer and metal platforms while forcing stainless steel suppliers to defend position through cost engineering.
EU MDR Annex I general safety and performance requirements now mandate clinical evidence for all Class IIa devices regardless of predicate history. German notified bodies apply heightened scrutiny to biocompatibility data packages, particularly for devices with prolonged bone contact. Manufacturers with legacy CE certificates under the Medical Devices Directive face compressed transition timelines that favor organizations with established quality management systems.
Hospital value analysis committees now unbundle needle procurement from cement and delivery system contracts. Interventional radiology departments in California and New York negotiate standalone needle pricing through group purchasing organizations, displacing bundled spine portfolio agreements. This behavioral shift concentrates purchasing power among procurement professionals rather than clinical champions, elevating total cost of ownership documentation requirements.
Vertebroplasty Needles Market Segmentation
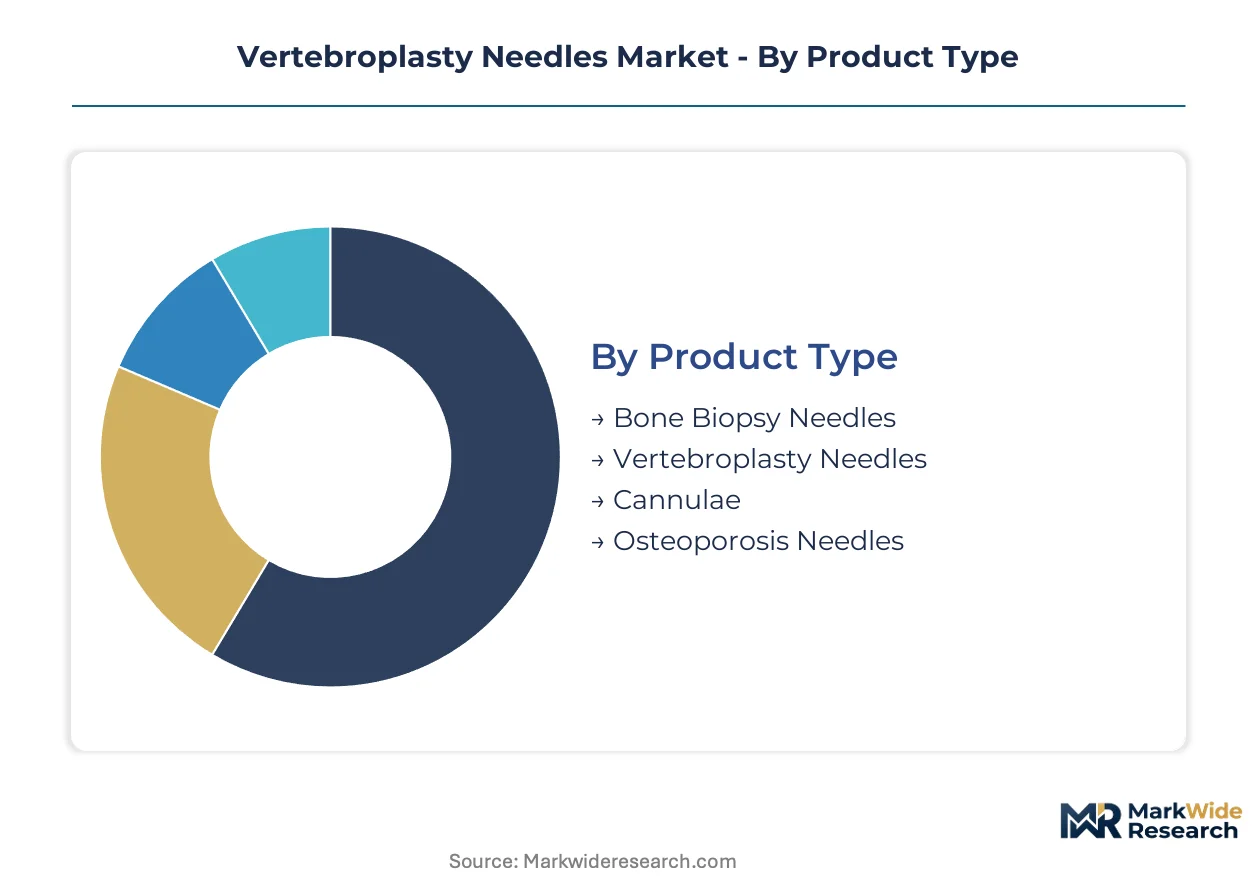
Vertebroplasty needle procurement decisions diverge sharply across clinical settings, with material specifications governing reimbursement eligibility and product type determining whether procedures migrate to outpatient facilities. Hospital value analysis committees now dissect these four category dimensions independently rather than accepting bundled spine portfolio contracts.
Product Type:
Procedure volume and reimbursement tier separate high-utilization instruments from specialized variants in purchasing negotiations.
- Bone Biopsy Needles:These dual-purpose instruments incorporate 11-13 gauge stainless steel cannulae with diamond or beveled tips engineered for cortical penetration and marrow extraction. Demand concentrates in German and United States hospital systems where integrated delivery networks prioritize single-instrument efficiency for cost containment. FDA 510(k) predicate pathways favor established geometries, compressing innovation cycles for tip design modifications.
- Vertebroplasty Needles:Purpose-built for polymethylmethacrylate delivery, these devices feature radiopaque depth markers and Luer-lock cement interfaces. Ambulatory surgical centers in Texas and Florida are expanding procurement of these instruments as CMS reimbursement parity accelerates same-day procedure migration from inpatient settings.
- Cannulae:Accessory cannulae provide working channels for cement delivery and biopsy retrieval in multi-step procedures. Academic medical centers specify these for complex pathological fracture cases requiring staged intervention.
- Osteoporosis Needles:Specialized variants address osteoporotic bone density with modified tip geometries reducing cortical breach risk. Japanese hospital networks show concentrated demand tied to aging demographic fracture incidence.
Volume sits with bone biopsy needles; growth tilts toward vertebroplasty needles.
Material:
Fluoroscopic visibility and sterilization compatibility determine material selection for interventional radiology departments.
- Stainless Steel:Austenitic 304 and 316L grades dominate procurement budgets with proven biocompatibility and gamma sterilization tolerance. German notified bodies under EU MDR apply heightened scrutiny to surface finish documentation for prolonged bone contact devices.
- Coated Steel:Radiopaque polymer coatings enhance fluoroscopic visibility without compromising mechanical properties. These variants command expanding procurement share in California and New York hospital systems where interventional radiology departments prioritize procedural time reduction.
- Polymer:High-performance thermoplastics enable MRI-guided procedures where metal artifacts compromise soft tissue visualization. Boston and Heidelberg academic centers pilot these for navigation-compatible interventions.
- Composite Materials:Carbon fiber-reinforced PEEK shafts merge radiolucency with structural rigidity. Premium positioning limits deployment to research-intensive institutions with capital equipment flexibility.
Stainless steel anchors procurement volume; coated steel captures expanding share fastest.
End User:
Capital equipment infrastructure and reimbursement classification shape channel-specific demand patterns.
- Hospitals:Inpatient surgical suites and interventional radiology departments maintain the installed base of C-arm fluoroscopy systems required for vertebral augmentation. German and United States hospital networks drive replacement cycles for legacy needle inventories under tightened EU MDR post-market surveillance.
- Ambulatory Surgical Centers:Same-day spine procedure capabilities expand in Texas and Florida as CMS payment determination parity eliminates reimbursement disincentives. These facilities prioritize single-use sterile packaging and compact instrument footprints.
- Research Institutions:Academic medical centers in Boston and Heidelberg evaluate next-generation polymer composite platforms for MRI-guided applications. Procurement volumes remain limited but influence technology adoption curves.
- Specialty Clinics:Pain management practices perform vertebroplasty for palliative fracture stabilization. Reimbursement variability across state Medicaid programs constrains instrument investment in this channel.
Hospitals retain procedure volume dominance; ambulatory surgical centers show steepest expansion trajectory.
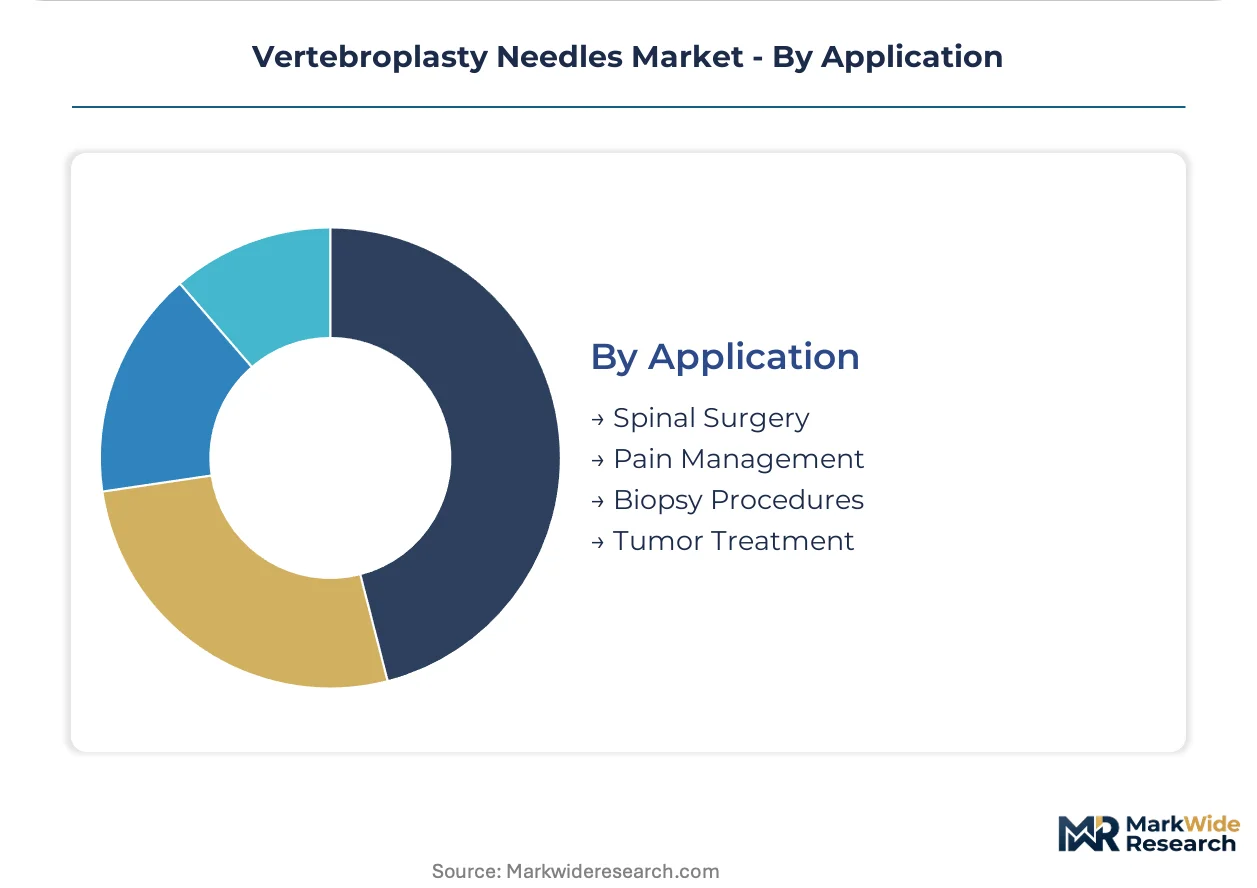
Application:
Clinical indication severity and reimbursement coding precision determine application-specific procurement priorities.
- Spinal Surgery:Vertebral compression fracture stabilization in osteoporotic and pathological bone represents the core commercial indication. Japanese and Italian healthcare systems face expanding patient bases as populations over 70 drive incidence curves upward.
- Pain Management:Palliative cement augmentation for metastatic disease addresses quality-of-life endpoints rather than structural restoration. Academic medical centers with hybrid operating suites increasingly compete with kyphoplasty balloon systems for these cases.
- Biopsy Procedures:Bone marrow aspiration and lesion sampling utilize vertebroplasty needle platforms with modified cannulae. Integrated delivery networks favor dual-purpose instruments reducing per-procedure supply costs.
- Tumor Treatment:Pathological fracture prevention in metastatic spine disease requires specialized needle geometries for lytic lesion navigation. Case volumes concentrate in tertiary referral centers with oncology service lines.
Spinal surgery anchors clinical utilization; pain management applications gain share through palliative care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
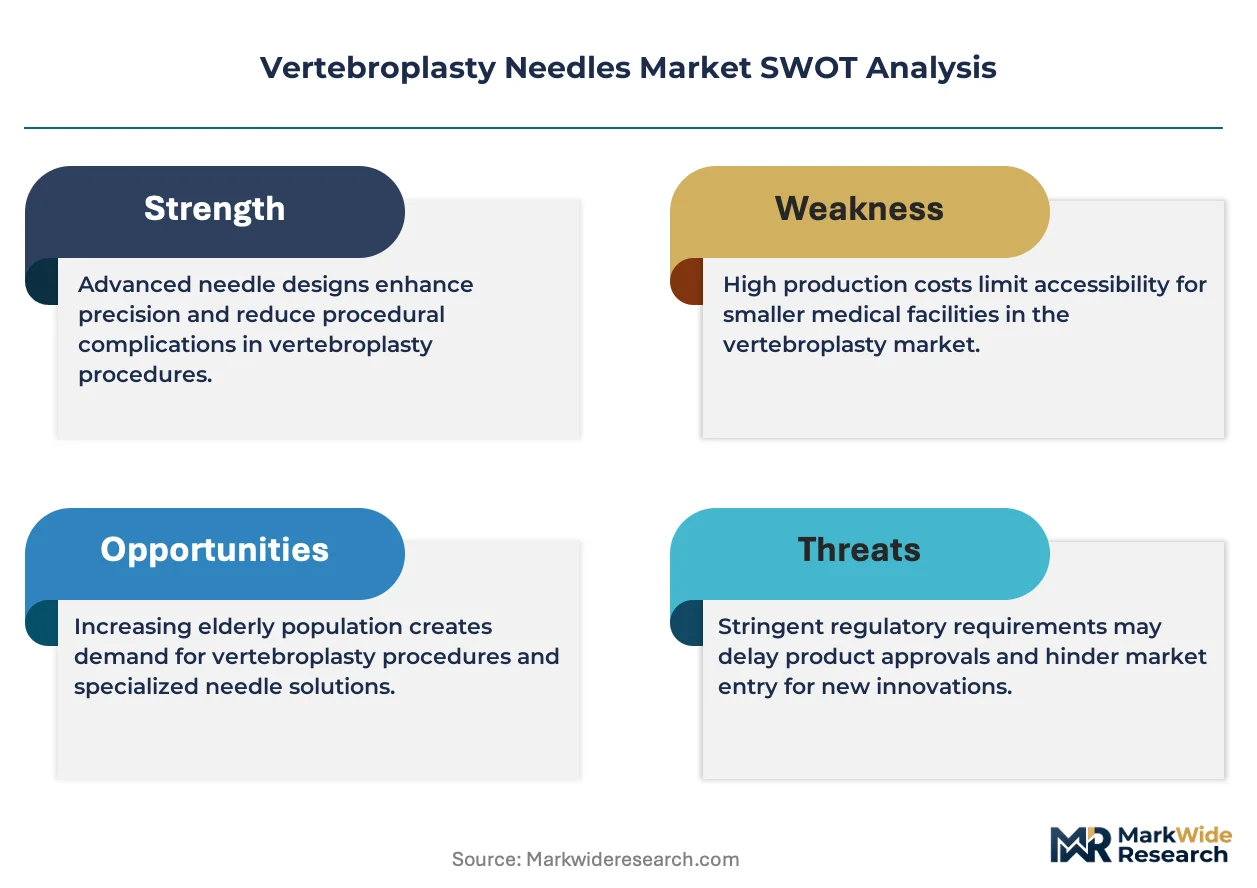
Nickel-titanium alloy sourcing from Western Pennsylvania and Solingen, Germany anchors vertebroplasty needle manufacturing geography. Hospital procurement consolidation and regulatory transition timelines concentrate demand across five national markets with divergent compliance burdens and reimbursement structures.
United States
Ambulatory surgical centers in Texas and Florida drive fastest channel expansion as CMS reimbursement parity eliminates outpatient disincentives. FDA 510(k) predicate limitations for novel tip geometries extend clearance timelines, compressing innovation cycles for domestic manufacturers. Minneapolis and Memphis hospital systems anchor interventional radiology training pipelines that constrain procedural volume growth.
Germany
EU MDR Article 10 post-market surveillance requirements accelerate replacement cycles for legacy needle inventories across hospital networks. Notified bodies apply heightened biocompatibility scrutiny to surface finish documentation for prolonged bone contact devices. Heidelberg academic medical centers pilot carbon fiber-reinforced PEEK platforms for MRI-guided navigation compatibility.
Japan
Aging demographics above age 70 expand osteoporotic vertebral compression fracture incidence curves faster than procedural capacity growth. PMDA regulatory harmonization with FDA 510(k) pathways reduces dual-market development burdens for multinational manufacturers. Tokyo and Osaka hospital networks concentrate interventional spine fellowship training programs.
China
NMPA Class II medical device registration reforms compress approval timelines for domestically manufactured instruments. Provincial hospital procurement centralization in Jiangsu and Guangdong provinces elevates cost-containment pressures on imported needle suppliers. Yangtze River Delta manufacturing clusters expand polymer composite processing capabilities.
Saudi Arabia
Vision 2030 healthcare privatization constructs greenfield hospital capacity in Riyadh and Jeddah without legacy interventional radiology infrastructure constraints. SFDA medical device registration requirements for imported Class IIa instruments favor established multinational quality management systems. Eastern Province oil industry health benefits sustain premium instrument procurement budgets.
Vertebroplasty Needles Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and hospital contracting infrastructure. Market structure tilts toward consolidated supply relationships within integrated delivery networks, with three to five suppliers capturing majority procurement volume in mature markets. Diversified spine portfolio conglomerates, interventional radiology specialists, and regional manufacturing champions constitute three dominant archetypes. Competitive moves concentrate on M&A for interventional spine sales infrastructure and strategic partnerships for EU MDR technical documentation capabilities.
Among diversified medical technology conglomerates, Medtronic plc and Stryker Corporation occupy positions anchored by spine portfolio breadth and dedicated interventional sales infrastructure respectively. DePuy Synthes Inc. exemplifies the orthopedic-rooted archetype extending into percutaneous spinal instrumentation. Merit Medical Systems Inc. and Argon Medical Devices Inc. represent interventional radiology-native specialists with concentrated vascular and bone access expertise. OptiMed GmbH and Teknimed anchor European regional manufacturing capabilities with notified body relationship advantages under MDR transition timelines.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| DePuy Synthes Inc. |
| Cook Medical LLC |
| Merit Medical Systems Inc. |
| Globus Medical Inc. |
| Argon Medical Devices Inc. |
| OptiMed GmbH |
| Teknimed |
| Others |
Value Network & Pricing Analysis
EU MDR sterilization validation requirements for Class IIa devices gate qualified supply access and premium-tier pricing for vertebroplasty needle manufacturers serving dual-regulated markets. Hospital value analysis committees now unbundle needle procurement from cement delivery systems, shifting pricing power toward procurement professionals who demand total cost of ownership documentation.
Pricing Analysis
Service-bundling unbundling now separates instrument warranties from standalone needle pricing in hospital negotiations. Three-tier pricing structure across premium, standard, and economy levels stratifies by fluoroscopic visibility grade and EU MDR certification tier. Cost compression in standard-grade stainless steel segments is intensifying because German notified bodies apply heightened surface finish scrutiny. Ambulatory surgical centers in Texas and Florida show highest price sensitivity, while academic medical centers in Boston and Heidelberg prioritize premium polymer composite platforms regardless of cost.
Supply Chain Analysis
Freight cost volatility from Western Pennsylvania nickel-titanium alloy suppliers and Solingen, Germany precision machining clusters elevates landed cost uncertainty for North American manufacturers. Raw material sourcing draws from austenitic 304/316L stainless steel mills, radiopaque polymer coating formulators, and gamma sterilization service providers. Single-source vulnerability concentrates in superelastic needle shaft materials from limited Western Pennsylvania and Solingen supplier bases. Distribution runs through integrated delivery network group purchasing organizations and interventional radiology department direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertebroplasty needles market sits in a material-transition phase as carbon fiber-reinforced PEEK composite platforms displace legacy stainless steel instruments in MRI-guided procedural settings.
For Market Incumbents: Acquire interventional spine sales infrastructure in metropolitan markets to consolidate contracted access before EU MDR transition timelines compress. Deepen backward integration into nickel-titanium alloy sourcing from Western Pennsylvania and Solingen to mitigate single-source vulnerability. Defend against kyphoplasty balloon system substitution by embedding dual-purpose biopsy-needle platforms in integrated delivery network contracts. For New Entrants and Emerging Players: Polymer composite MRI-compatibility offers a technology-first wedge into academic medical center procurement in Boston and Heidelberg where metal artifact elimination commands premium positioning. Target ambulatory surgical center channels in Texas and Florida where CMS reimbursement parity accelerates same-day procedure migration and sterile packaging simplicity matters. Pursue group purchasing organization standalone needle contracts rather than bundled spine portfolio agreements. For Investors and Strategic Acquirers: EU MDR notified body backlog clearance is the leading indicator that quality management system capabilities will separate viable acquisition targets from stranded legacy manufacturers. The 5-10 year viability window favors interventional radiology-native specialists with concentrated bone access expertise over diversified orthopedic conglomerates. Monitor SFDA registration progress in Saudi Arabia as Vision 2030 greenfield hospital construction creates first-mover infrastructure advantages.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates legacy CE certificate transition timelines before notified body capacity constraints harden. |
| Carbon Fiber-Reinforced PEEK Platform Development | Enables MRI-guided procedural positioning in Boston and Heidelberg academic medical centers. |
| Ambulatory Surgical Center Distribution Partnership | Captures CMS reimbursement parity migration in Texas and Florida same-day spine channels. |
| Dual-Purpose Biopsy-Needle Convergence | Addresses integrated delivery network cost-containment pressures through single-instrument efficiency. |
| Nickel-Titanium Alloy Supply Security | Mitigates Western Pennsylvania and Solingen single-source concentration risk for superelastic shaft materials. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certificate transition status, and CMS reimbursement determination patterns anchored the trend analysis, supplemented by interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) database filings, EU MDR notified body public certificates, CMS Medicare payment determinations, and hospital procurement database extracts. Bottom-up instrument demand modeling triangulated against top-down spine procedure volume projections.
Segment-weighting across product type, material composition, end user channel, and application indication governed value distribution throughout the forecast period. CAGRs derived from procedure volume elasticity to aging demographic curves, reimbursement parity adoption rates, and material substitution trajectories. Industry-specific inputs incorporated fluoroscopic visibility coating penetration, gamma sterilization throughput constraints, and interventional radiology fellowship program output.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints and nickel-titanium alloy supply disruptions. Forecasts reflect documented assumptions regarding CMS ASC payment expansion timing and polymer composite platform clinical adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market