
 Vertebroplasty and Kyphoplasty Market | 2026-2036
Vertebroplasty and Kyphoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebroplasty and Kyphoplasty Market Outlook
Hospital procurement of vertebroplasty and kyphoplasty systems is tilting toward bundled contract arrangements that favor vendors with full-line capabilities. Medtronic plc leverages its integrated spine portfolio to sustain preferred vendor status across major health systems. Stryker Corporation competes through specialized kyphoplasty balloon technologies that differentiate its offering in outpatient settings.
Vertebroplasty and kyphoplasty constitute minimally invasive spinal interventions wherein bone cement—typically polymethylmethacrylate—is injected into fractured vertebral bodies under image guidance to restore structural integrity and alleviate pain. Fluoroscopy dominates the technology dimension due to real-time visualization and established workflow integration, while robotics represents the fastest-growing technology segment as surgeons seek enhanced precision in cement delivery. The end-user landscape shows ambulatory surgery centers gaining share as procedural volumes migrate from inpatient hospitals, though hospitals retain the largest absolute volume pool and corresponding margin concentration.
The FDA governs bone cement and delivery instrument premarket notifications under 510(k) and PMA pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for spinal implantable devices. These frameworks elevate barriers for new entrants and compel established manufacturers to maintain robust quality management systems. Stakeholders must monitor reimbursement policy shifts at CMS and private payers, as coverage determinations for vertebral augmentation directly influence physician adoption and site-of-care migration.
Market Dynamics
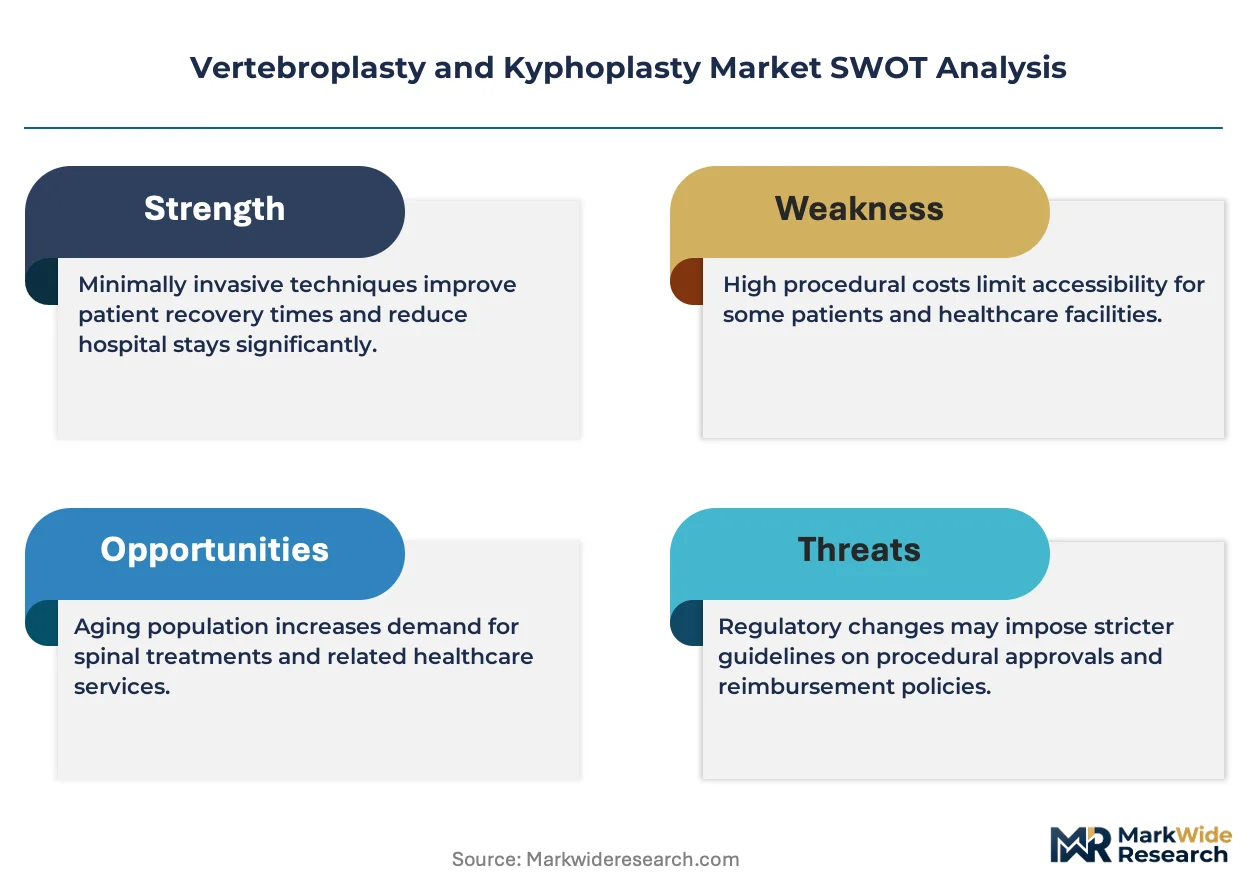
Site-of-care migration from inpatient hospitals to ambulatory surgery centers is compressing procedural economics and forcing vendors to reconfigure their go-to-market infrastructure around outpatient workflow requirements.
Growth Catalysts
- Aging demographics:The United States population aged 65 and above expands the addressable patient pool for osteoporotic vertebral compression fractures, driving procedural volume expansion in Medicare-eligible cohorts.
- Fluoroscopy-guided cement delivery:Real-time imaging integration enables same-day discharge protocols that satisfy ambulatory surgery center efficiency mandates and reduce total episode costs.
- CMS reimbursement stability:Established CPT codes for percutaneous vertebral augmentation preserve physician practice revenue and sustain hospital investment in dedicated interventional radiology suites.
Market Restraints
- Polymethylmethacrylate cost volatility:Petroleum-derived monomer feedstock prices fluctuate with crude oil markets, compressing bone cement gross margins for manufacturers without backward integration into chemical supply.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for spinal implantable devices extend regulatory timelines and elevate compliance expenditures for CE marking maintenance.
- Cement leakage complications:Extravasation rates during vertebroplasty procedures generate malpractice exposure and constrain physician willingness to expand indication boundaries beyond conservative fracture patterns.
Strategic Opportunities
- Robotic navigation systems:Computer-assisted cement delivery platforms address precision limitations in complex spinal anatomy and command premium pricing in academic medical centers.
- Japan's super-aged society:The world's highest proportion of citizens over 80 creates concentrated demand for minimally invasive fracture management in a reimbursement environment favoring cost-effective interventions.
- Bioresorbable cement formulations:Next-generation materials that integrate with native bone remodeling processes could displace permanent PMMA implants and capture long-term follow-up revenue streams.
Industry Challenges
- Interventional radiology workforce constraints:Fellowship-trained specialists capable of complex spinal navigation remain concentrated in tertiary centers, limiting procedural access in community hospital settings.
- Legacy EMR integration:Ambulatory surgery centers deploying vertebral augmentation workflows face interoperability friction with hospital-based electronic medical record systems during patient handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebroplasty and Kyphoplasty Market |
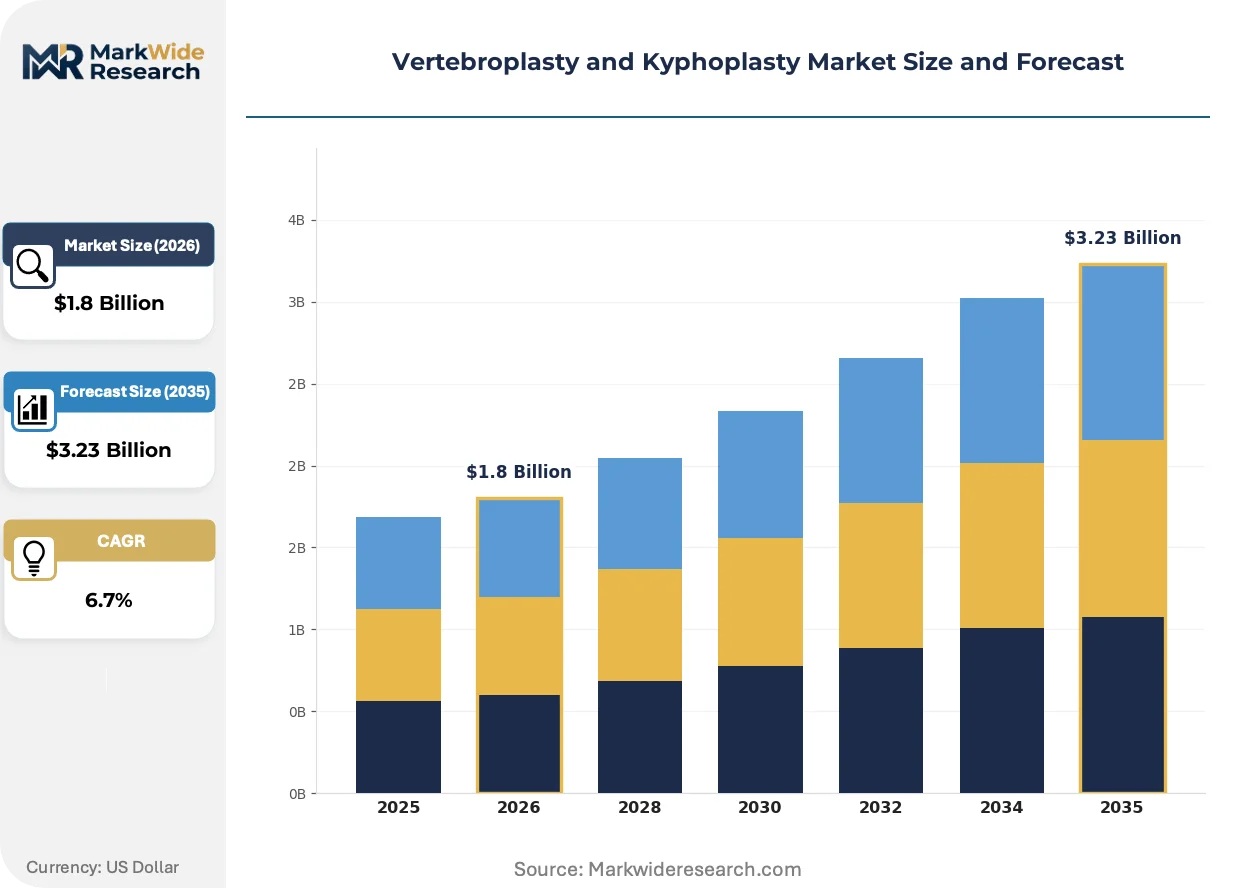
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cements, Injectables, Instruments, Imaging Systems End User: Hospitals, Outpatient Clinics, Ambulatory Surgery Centers, Rehabilitation Centers Application: Back Pain Treatment, Bone Fracture Repair, Spinal Stabilization, Osteoporosis Management Technology: Fluoroscopy, CT Guidance, Ultrasound Guidance, Robotics |
| Companies Covered | Johnson & Johnson Services, Inc., Globus Medical, Inc., Medtronic plc, CareFusion Corporation, Cardinal Health, Inc., Stryker Corporation, Merit Medical Systems, Inc., Alphatec Spine, Inc., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebroplasty and Kyphoplasty Market Strategic Shifts
Precision instrumentation and intelligent navigation systems are displacing conventional manual techniques across vertebral augmentation workflows, altering capital allocation patterns among surgical device purchasers.
High-viscosity bone cement formulations are migrating from academic demonstration settings to standard ambulatory surgery center protocols. Outpatient facilities in the United States adopt these materials aggressively to reduce polymethylmethacrylate leakage rates and accelerate room turnover. The technology is migrating from premium positioning toward commoditized inclusion in bundled procedural kits, compressing standalone cement pricing power.
The FDA's 510(k) substantial equivalence pathway for bone cement delivery instruments faces intensifying scrutiny as predicate device limitations accumulate in adverse event databases. Manufacturers now invest in prospective clinical data generation to support de novo classification requests for next-generation systems. Spinal implant divisions within diversified orthopedic portfolios absorb the highest compliance burden from this regulatory recalibration.
Hospital supply chain directors consolidate vendor relationships around full-line spine capabilities rather than maintaining point-solution contracts for vertebral augmentation alone. Integrated delivery networks in the United States increasingly mandate single-source purchasing agreements that bundle kyphoplasty balloons with interbody cages and pedicle screw systems. This concentration dynamic favors manufacturers with comprehensive thoracolumbar portfolios and captive distribution infrastructure.
Vertebroplasty and Kyphoplasty Market Segmentation
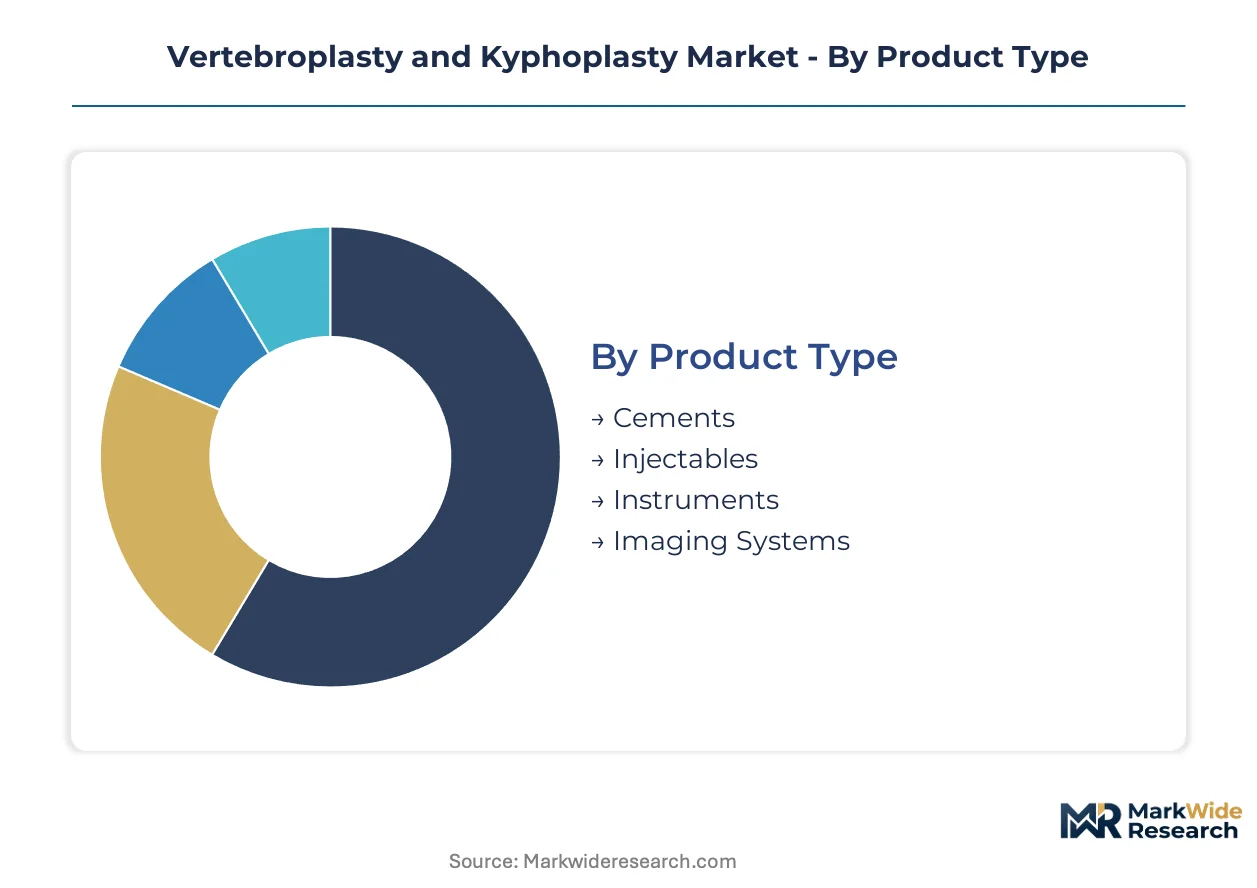
Segmentation in vertebral augmentation reveals divergent procurement rhythms across product categories. Cements and instruments turn over rapidly in high-volume ambulatory settings, while imaging systems anchor capital cycles measured in years. Understanding these velocity differentials shapes vendor inventory strategies and customer targeting priorities.
Product Type:
Cycle times vary dramatically: bone cement replenishes monthly in busy centers, whereas imaging platforms depreciate over seven-to-ten-year horizons. This temporal spread forces manufacturers to balance consumable recurring revenue against capital equipment financing complexity.
- Cements:Polymethylmethacrylate formulations dominate procedural economics, with high-viscosity variants commanding preference in United States ambulatory surgery centers seeking reduced leakage rates. Demand concentrates in Medicare-reimbursed vertebral compression fracture cases where same-day discharge protocols prioritize rapid polymerization kinetics.
- Instruments:Delivery cannulas, bone biopsy needles, and cement mixers constitute the fastest-turning hardware category, with single-use disposables displacing reprocessed tools amid infection control tightening. Hospital supply chains in the United States negotiate these as bundled line items within broader spine contracts.
- Injectables:Bone void fillers and alternative cement chemistries occupy niche positioning for complex fracture patterns.
- Imaging Systems:C-arm fluoroscopy units represent capital-intensive infrastructure with extended replacement cycles.
Cements anchor the volume base while robotics-integrated imaging gains share at the steepest rate.
End User:
Procurement authority fragments across organizational types with divergent budget authority and clinical throughput. Hospitals retain capital equipment decision rights; ambulatory surgery centers drive consumable velocity through case volume concentration.
- Hospitals:Tertiary medical centers maintain the deepest case backlogs for complex multi-level fractures, with interventional radiology suites representing high-fixed-cost infrastructure that demands utilization maximization. United States health systems consolidate purchasing through integrated delivery networks that favor full-line spine vendors.
- Ambulatory Surgery Centers:Freestanding facilities capture migrating procedural volumes through streamlined workflows and lower overhead structures. These sites prioritize disposable-heavy kits that eliminate reprocessing delays and support rapid room turnover.
- Outpatient Clinics:Office-based settings handle diagnostic workup and post-procedural follow-up rather than acute intervention.
- Rehabilitation Centers:Post-acute facilities manage conservative care and recovery monitoring without direct procedural involvement.
Hospitals retain absolute volume concentration while ambulatory surgery centers expand most quickly as site-of-care migration accelerates.
Application:
Clinical indication breadth determines reimbursement pathway stability and physician training requirements. Pain-focused applications align with interventional radiology expertise; structural stabilization demands orthopedic spine collaboration.
- Back Pain Treatment:Palliative cement augmentation for osteoporotic vertebral compression fractures constitutes the foundational volume driver, with Medicare coverage determinations in the United States cementing procedural access for elderly cohorts. Pain clinics and interventional radiologists dominate this indication.
- Spinal Stabilization:Kyphoplasty balloon tamp procedures restore vertebral body height in traumatic or pathologic fractures, commanding premium reimbursement when bundled with deformity correction. Academic medical centers deploy these techniques for neoplastic spinal involvement.
- Bone Fracture Repair:Traumatic vertebral fractures in younger populations represent a smaller addressable pool with distinct clinical pathways.
- Osteoporosis Management:Preventive pharmacologic protocols compete with procedural intervention for fracture risk reduction.
Back pain treatment anchors the volume base while spinal stabilization climbs the fastest as oncology and trauma indications expand.
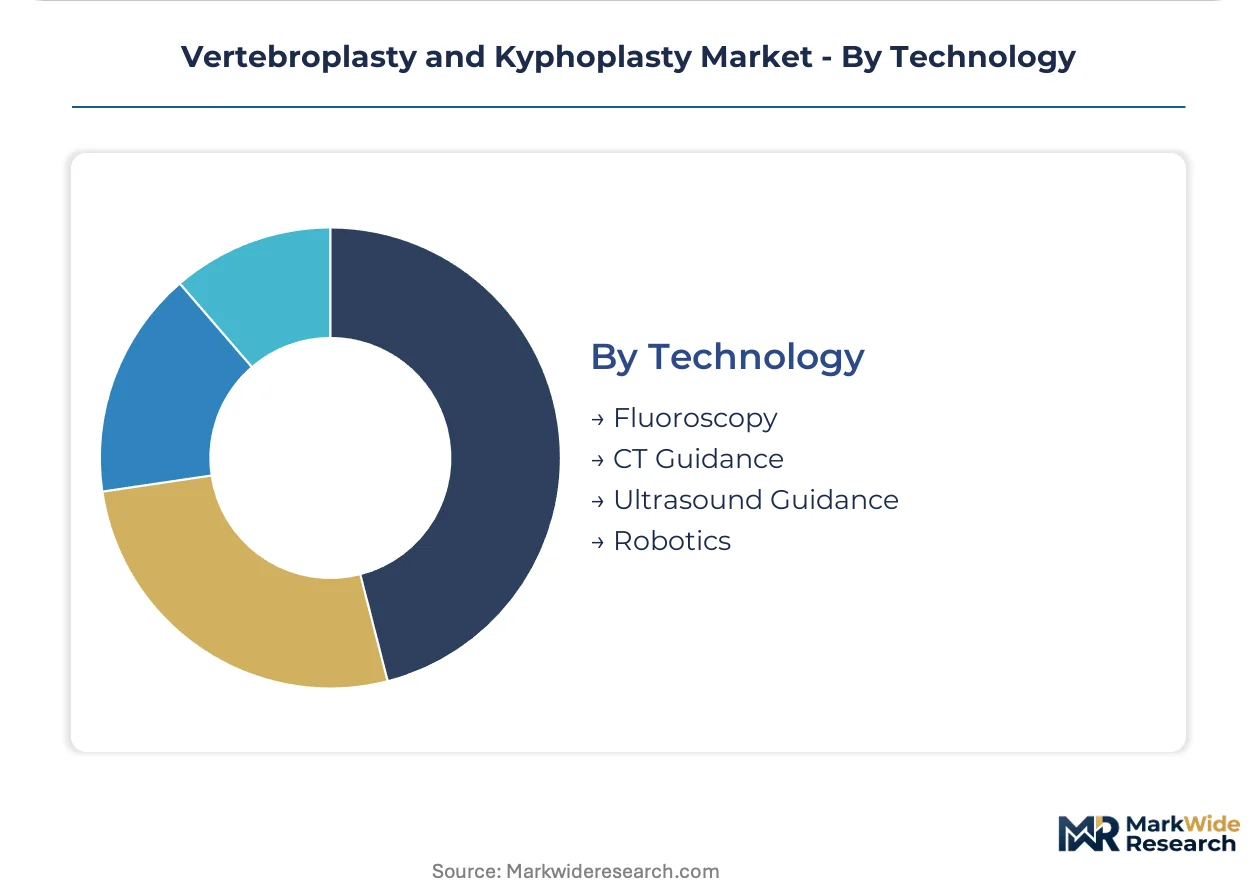
Technology:
Visualization modality selection shapes capital deployment, training requirements, and procedural precision. Established imaging platforms face displacement pressure from navigation-enhanced alternatives.
- Fluoroscopy:Real-time X-ray guidance remains the workflow standard, with C-arm positioning enabling bilateral transpedicular access under continuous visualization. United States ambulatory surgery centers favor this modality for its speed and established technician familiarity.
- Robotics:Computer-assisted navigation platforms address cement delivery precision in complex spinal anatomy, with trajectory planning software reducing radiation exposure and leakage risk. Academic medical centers in the United States pilot these systems for research differentiation.
- CT Guidance:Cross-sectional imaging offers superior soft-tissue resolution for challenging anatomy but extends procedure duration.
- Ultrasound Guidance:Acoustic visualization avoids ionizing radiation but remains limited by bone impedance in vertebral applications.
Fluoroscopy anchors the volume base while robotics gains share at the steepest rate as precision demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in vertebral augmentation concentrates in the United States, where Medicare reimbursement stability supports premium cement formulations, while Japanese procurement emphasizes cost-effective interventions for its super-aged demographic.
United States
The United States captures the largest absolute procedural volume for osteoporotic vertebral compression fractures, driven by expanding Medicare-eligible cohorts and established CPT reimbursement codes. The FDA governs bone cement premarket approvals through 510(k) and PMA pathways, elevating compliance barriers for new entrants. Interventional radiology suites in academic medical centers across the Northeast and California pilot robotic navigation systems for research differentiation.
Japan
Japan's super-aged society generates concentrated demand for minimally invasive fracture management, with the highest global proportion of citizens over 80. The PMDA maintains stringent clinical evidence requirements for spinal implantable devices under pharmaceutical and medical device regulations. Tokyo and Osaka medical centers drive adoption of fluoroscopy-guided cement delivery for same-day discharge protocols.
Germany
Germany anchors European procedural volume through its dense network of specialized orthopedic and interventional radiology departments. The EU Medical Device Regulation imposes stricter post-market surveillance obligations, extending regulatory timelines for CE marking maintenance. Industrial clusters in Bavaria and North Rhine-Westphalia host manufacturing operations for high-viscosity bone cement formulations.
China
China's aging population and expanding hospital infrastructure create accelerating demand for vertebral augmentation procedures in tier-one cities. The NMPA oversees bone cement registration through medical device classification pathways that increasingly align with international standards. Beijing and Shanghai medical centers concentrate adoption of imported fluoroscopy systems alongside domestic cement production.
United Kingdom
The United Kingdom demonstrates growing procedural migration toward ambulatory settings within its National Health Service framework. NICE technology appraisals influence coverage determinations for vertebral augmentation, creating variability in regional access. London and the Southeast concentrate private-pay procedural volumes, while Midlands hospital networks consolidate purchasing through integrated delivery systems.
Vertebroplasty and Kyphoplasty Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in cement and disposable instrumentation. The vendor base organizes around three structural tiers: diversified orthopedic conglomerates with full-line spine portfolios, specialized vertebral augmentation firms with focused kyphoplasty technologies, and regional manufacturers supplying commodity bone cement formulations. Competitive dynamics center on M&A activity to capture ambulatory surgery center distribution channels and strategic partnerships to integrate robotics with existing fluoroscopy installations.
Among diversified platform integrators, Medtronic plc and Stryker Corporation exemplify the full-line spine archetype that hospital procurement directors favor for bundled contract arrangements. Johnson & Johnson Services, Inc. occupies a position within the orthopedic device conglomerate tier, leveraging broad surgical portfolio synergies. These three entities anchor the competitive structure through their capacity to offer integrated thoracolumbar solutions spanning interbody cages, pedicle screw systems, and vertebral augmentation technologies.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Globus Medical, Inc. |
| Medtronic plc |
| CareFusion Corporation |
| Cardinal Health, Inc. |
| Stryker Corporation |
| Merit Medical Systems, Inc. |
| Alphatec Spine, Inc. |
| DePuy Synthes |
| Others |
Value Chain & Pricing Dynamics
Bavarian industrial clusters anchor European bone cement production capacity, with polymerization facility utilization rates directly shaping margin structures for high-viscosity formulations destined for United States ambulatory surgery centers. Petroleum-derived methyl methacrylate monomer costs transmit volatility from crude benchmarks into downstream pricing power, compressing returns for manufacturers lacking captive chemical supply.
Pricing Analysis
The customization-premium spread separates robotic navigation-integrated systems from standard fluoroscopy-guided kits, with academic medical centers absorbing configured-to-order pricing while ambulatory surgery centers negotiate standard tier rates. Price differentiation hinges on FDA 510(k) clearance tier and bundled contract scale, with integrated delivery networks extracting volume discounts that squeeze standalone vendors. Pricing pressure stems from polymethylmethacrylate raw material cost swings, with hospital procurement committees becoming most price-sensitive as site-of-care migration accelerates.
Supply Chain Analysis
Upstream methyl methacrylate monomer production concentrates in Germany, the United States, and Japan, with specialty chemical manufacturers controlling feedstock access for medical-grade polymerization. Bone cement formulation draws from petroleum derivatives, barium sulfate radiopacifiers, and initiator chemicals, creating multi-point cost exposure. Single-source vulnerability in high-purity monomer supply elevates risk during energy price spikes. Distribution runs through orthopedic device distributors and direct hospital contracting channels, with ambulatory surgery centers increasingly procuring through GPO-negotiated kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertebral augmentation sector rewards mastery of interventional radiology workflow integration and regulatory navigation, capabilities that remain scarce outside established spine portfolios. Manufacturers lacking fellowship-trained specialist relationships or CE marking maintenance infrastructure face structural barriers to margin capture.
For Market Incumbents: Harden defensive positions by deepening backward integration into methyl methacrylate monomer supply and locking ambulatory surgery center distribution through disposable-heavy kit configurations. Cement leakage liability exposure and EU MDR post-market surveillance obligations threaten non-compliant vendors; prioritize quality management system investments that accelerate de novo classification timelines for next-generation delivery instruments. For New Entrants and Emerging Players: Build out presence in Japan's super-aged fracture management segment, where cost-effective fluoroscopy protocols outpace robotic adoption and reimbursement favors streamlined interventions. White-space exists in bioresorbable cement formulations for academic medical center research partnerships; pursue software companion development pathways that attach navigation revenue to existing C-arm installations rather than competing on capital equipment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with full-line spine portfolios over point-solution kyphoplasty specialists, as hospital procurement consolidation accelerates single-source contracting. Long-term viability rests on capturing ambulatory surgery center channel density before site-of-care migration saturates. Watch FDA adverse event database accumulation against predicate devices as the signal indicating regulatory pathway difficulty for robotic navigation entrants.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines for spinal implantable device approvals. |
| Hospital System Partnership | Integrated delivery network bundling secures preferred vendor status across vertebral augmentation and deformity correction. |
| Software Companion Development | Navigation algorithms for cement delivery precision differentiate capital equipment in academic medical centers. |
| Backward Integration | Captive methyl methacrylate production insulates margins from petroleum feedstock volatility. |
| Reimbursement Strategy | CMS coverage determination alignment preserves physician practice revenue for Medicare-eligible fracture cohorts. |
Study Parameters
Cross-validation between primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and EU MDR notified body documentation. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation across product type, end user, application, and technology dimensions.
Calibration against historical procedural migration patterns and reimbursement stability indicators shapes the analytical framework across the projection horizon. Segmentation modeling incorporates product type velocity differentials, site-of-care shift trajectories, and technology adoption curves for fluoroscopy versus robotic navigation. CAGRs derive from procedure volume expansion in Medicare-eligible demographics and ambulatory surgery center capacity buildout, with regulatory pathway timelines and raw material cost indices serving as industry-specific forecast inputs.
Stress conditions across polymethylmethacrylate monomer price bands, EU MDR enforcement intensity, and interventional radiology workforce growth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding CMS reimbursement continuity and ambulatory surgery center regulatory licensing expansion. Cross-checking against hospital capital expenditure surveys and orthopedic distributor inventory data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
North America Knee Cartilage Repair Market