
 Polyethylene Orthopaedic Insert Market | 2026-2036
Polyethylene Orthopaedic Insert Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Orthopaedic Insert Market Analytics
Cross-linked polyethylene grade advancement is unwinding traditional material hierarchies in joint replacement. Stryker leverages in-house polymer processing to secure supply continuity for implant manufacturers. Zimmer Biomet anchors its portfolio on vitamin E-stabilized polyethylene formulations that reduce oxidative degradation. DSM Biomedical differentiates through biomedical-grade resin purification that exceeds ISO 5834 implant standards.
Polyethylene orthopaedic inserts are bearing surfaces machined from ultra-high molecular weight polyethylene or cross-linked variants, typically measuring 8-12 mm thickness with sub-micron surface finish requirements, designed to articulate against metallic or ceramic femoral components in total joint arthroplasty. Modular inserts dominate hospital procurement due to surgeon preference for intraoperative flexibility and revision adaptability. Cross-linked polyethylene represents the fastest-expanding material category as oxidation-resistant formulations extend implant longevity and defer revision surgery. Fixed inserts retain share in cost-sensitive outpatient facilities where procedure standardization limits customization needs.
FDA 510(k) clearance pathways govern polyethylene insert commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for CE marking. ISO 5834 standards define acceptable wear rates and mechanical properties for implantable polyethylene, directly shaping resin formulation priorities among manufacturers. Stakeholders must monitor evolving sterilization regulations, particularly gamma irradiation dose limits, as these determine cross-linking density specifications and finished product shelf life.
Market Dynamics
Cross-linked polyethylene formulations are compressing revision surgery timelines and reconfiguring supplier relationships across implant manufacturing. Hospitals now specify oxidation-resistant grades in procurement contracts, forcing resin processors to validate mechanical performance under accelerated aging protocols.
Growth Catalysts
- Aging demographics in OECD markets:Germany, Japan, and the United States sustain elevated knee arthroplasty volumes as cohorts aged 65-plus expand. Joint replacement backlogs from deferred procedures continue clearing through hospital systems.
- Vitamin E stabilization technology:Antioxidant-infused polyethylene grades extend implant functional life beyond fifteen years. Surgeons increasingly specify these formulations for younger, more active patients.
- ISO 5834-1 revisions:Updated mechanical property thresholds for implantable polyethylene are accelerating qualification of advanced resin grades. Manufacturers reformulating to meet these standards capture preferred supplier status with original equipment manufacturers.
Market Restraints
- Medical-grade UHMWPE resin concentration:Three specialized polymer processors control over eighty percent of biomedical-grade feedstock. Any disruption at these facilities propagates through implant supply chains within weeks.
- Gamma sterilization dose constraints:FDA and EU MDR restrictions on irradiation exposure limit cross-linking density achievable in finished inserts. Manufacturers must balance oxidative stability against wear resistance.
- Ceramic-on-ceramic bearing substitution:Hard-on-hard articulation surfaces eliminate polyethylene wear debris entirely. Younger patients with higher activity demands increasingly select ceramic femoral head and acetabular combinations.
Strategic Opportunities
- Outpatient surgery center expansion:Ambulatory surgical facilities in the United States now perform over fifty percent of primary knee replacements. Fixed-bearing inserts with simplified instrumentation match their cost and throughput requirements.
- India's medical device PLI scheme:Production-linked incentives for domestic implant manufacturing are attracting polyethylene processors to establish compounding operations near Mumbai and Hyderabad surgical clusters.
- Additive manufacturing convergence:Powder-bed fusion of polyethylene is enabling patient-specific insert geometries. Early adopters in academic medical centers are validating wear characteristics of printed bearing surfaces.
Industry Challenges
- Biomedical polymer engineering talent scarcity:Cross-linking chemistry expertise resides at a handful of academic programs. Manufacturers compete for PhD-level formulators who understand both rheology and implant biomechanics.
- FDA 510(k) predicate device drift:Substantial equivalence pathways for novel polyethylene grades narrow as predicate devices age. New formulations increasingly require premarket approval with full clinical trials.
- Legacy sterilization asset stranding:Ethylene oxide and gamma facilities face environmental compliance upgrades. Capex requirements for alternative sterilization technologies compress margins at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Orthopaedic Insert Market |
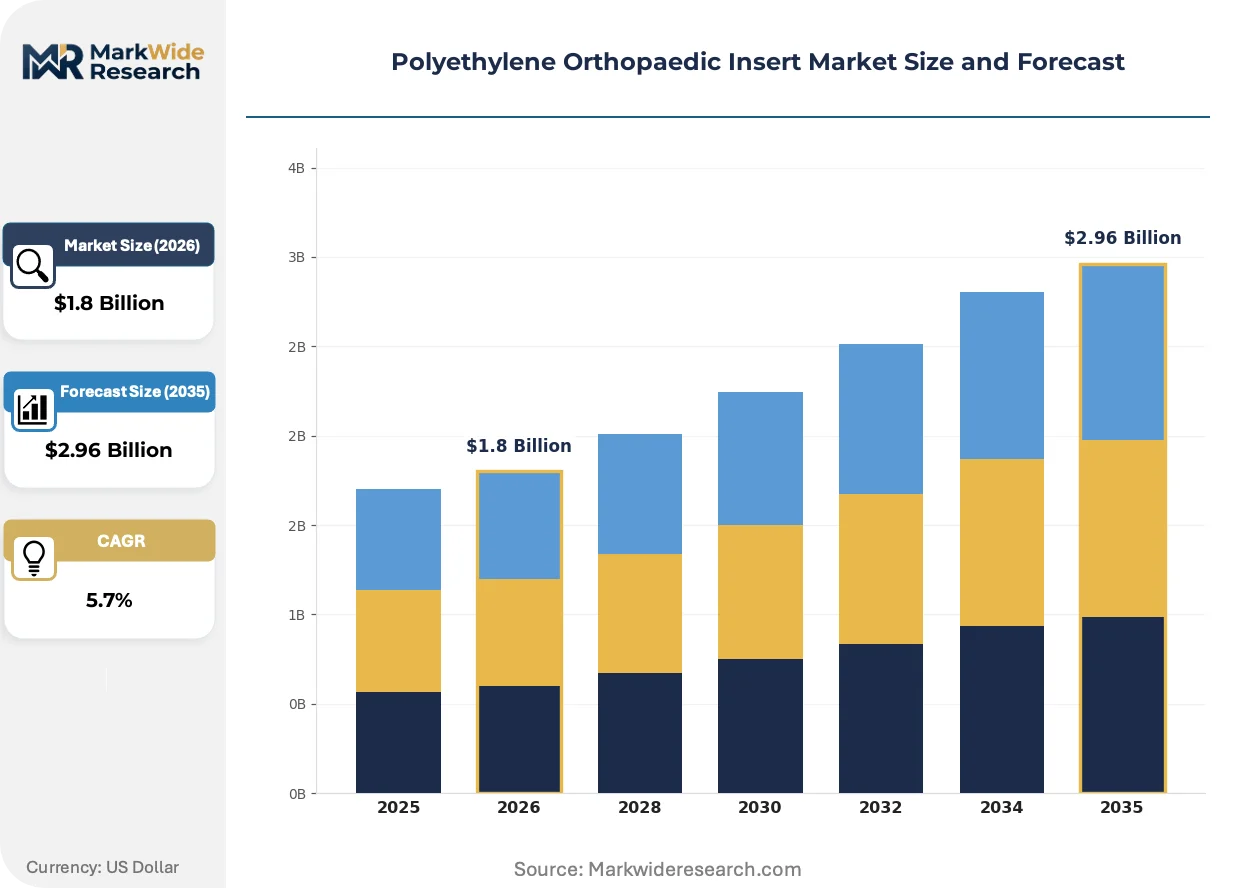
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Inserts, Fixed Inserts, Expandable Inserts, Customized Inserts End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Facilities Material: Ultra-High Molecular Weight Polyethylene, Cross-Linked Polyethylene, Low-Density Polyethylene, Others Manufacturing Stage: Raw Material Processing, Molding, Sterilization, Packaging |
| Companies Covered | Celanese Corporation, DSM Biomedical, Orthoplastics Ltd, Stryker, Zimmer Biomet, Johnson & Johnson MedTech, Smith & Nephew, Asahi Kasei Corporation, Quadrant Engineering Plastic Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Orthopaedic Insert Market Evolving Landscape
Material science breakthroughs and regulatory recalibration are converging to redefine polyethylene insert performance benchmarks. Manufacturing processes and clinical validation protocols are both tightening simultaneously.
Sequential annealing after radiation cross-linking is supplanting conventional thermal treatment protocols in premium insert production. Academic medical centers in Boston and Rotterdam specify sequentially annealed polyethylene for high-demand knee revisions. This thermal processing is supplanting first-generation cross-linked materials in surgeon preference rankings.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III implants are extending CE marking timelines by twelve to eighteen months. Manufacturers must now submit wear simulator data alongside biocompatibility documentation. Knee implant portfolios face the steepest compliance burden due to higher revision consequence severity.
Hospital value analysis committees now mandate ten-year implant survival data before adding polyethylene grades to formulary. Procurement departments in integrated delivery networks are consolidating supplier rosters to three preferred vendors. This concentration is most pronounced in the United States Midwest, where Catholic health systems and for-profit chains dominate regional volume.
Polyethylene Orthopaedic Insert Market Segmentation
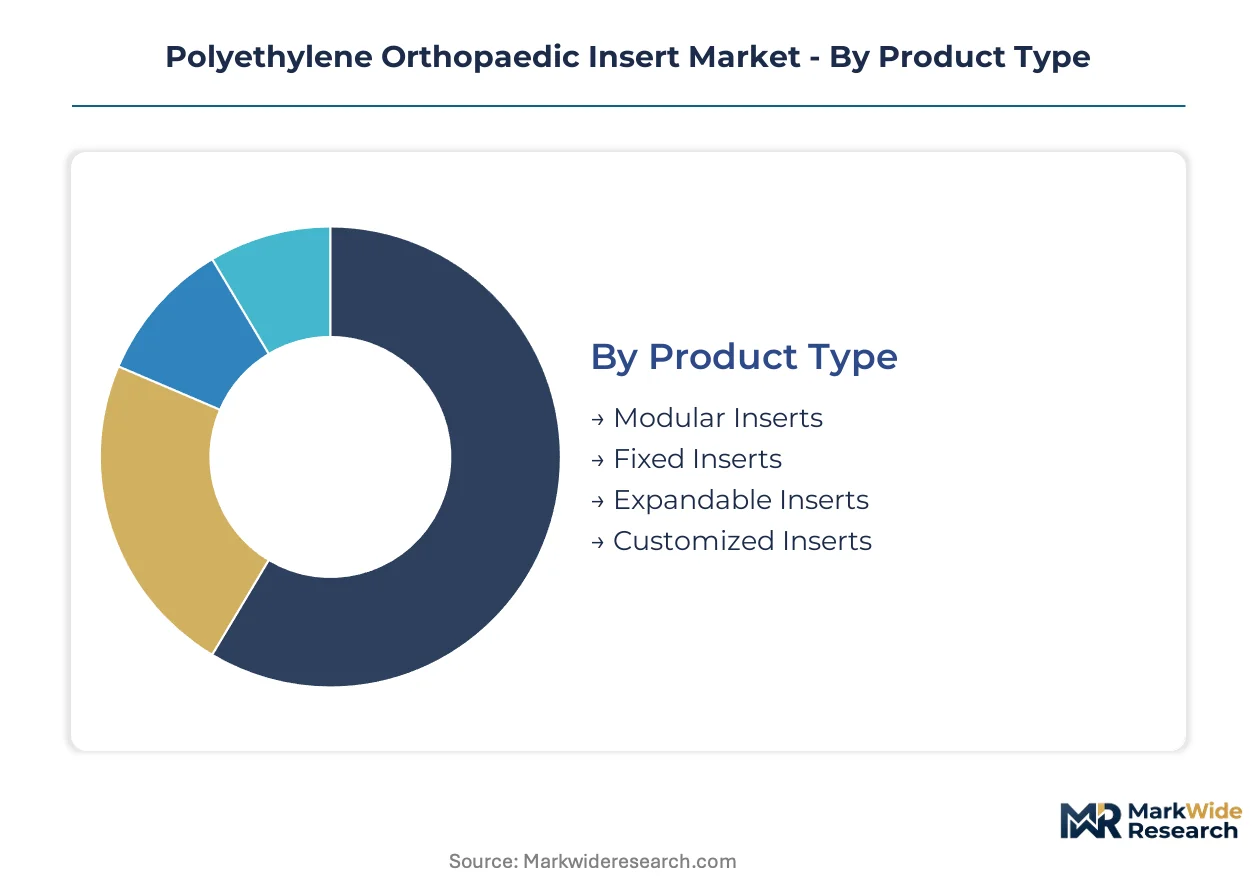
Polyethylene orthopaedic insert segmentation reveals how material science, surgical venue economics, and regulatory compliance create divergent commercial trajectories. Procurement patterns differ sharply between hospital systems and ambulatory facilities, while cross-linking technology is fragmenting the material hierarchy.
Product Type:
Substitution pressure from ceramic-on-ceramic bearings hits fixed-bearing designs hardest, while modular architectures defend share through revision-cycle adaptability.
- Modular Inserts:These bearing surfaces feature locking mechanisms enabling intraoperative thickness adjustment and future component exchange without femoral stem removal. Demand concentrates at academic medical centers in the United States and Germany where complex primary and revision knee procedures generate preference for intraoperative flexibility. Surgeon training programs at Mayo Clinic and Charité Berlin institutionalize modular system familiarity.
- Fixed Inserts:Monoblock polyethylene bearings with molded or press-fit fixation offer lower per-unit cost and simplified instrumentation. Outpatient surgery centers in Florida and Texas specify fixed designs for standardized primary knee arthroplasty where procedure throughput trumps customization. Cost-sensitive procurement contracts favor these configurations.
- Expandable Inserts:Adjustable-height bearings accommodate ligament balancing without component exchange. Limited adoption in Japan's precision-oriented surgical culture.
- Customized Inserts:Patient-specific geometries from preoperative imaging data serve complex deformity cases. Restricted to quaternary referral centers.
Fixed inserts anchor the volume base through ambulatory expansion while modular designs gain share at the steepest rate among revision specialists.
End User:
Volume concentration follows surgical venue economics, with reimbursement differentials dictating where polyethylene consumption concentrates geographically.
- Hospitals:Inpatient facilities perform complex primary and revision arthroplasty requiring extended recovery monitoring. Tertiary hospitals in the United States, Germany, and Japan account for disproportionate cross-linked polyethylene utilization due to younger patient demographics and higher activity demands. Value analysis committees at these institutions mandate ten-year survival data before formulary inclusion.
- Orthopedic Clinics:Specialized surgical facilities combine operating capacity with focused musculoskeletal expertise. Clinics in the Netherlands and Switzerland leverage direct-to-implant manufacturer relationships to secure vitamin E-stabilized formulations ahead of hospital system procurement cycles.
- Rehabilitation Centers:Post-acute facilities influence implant selection through readmission risk contracts. Bundled payment models in Medicare jurisdictions.
- Outpatient Facilities:Ambulatory surgery centers now perform the majority of primary knee replacements in the United States. Same-day discharge protocols favor fixed-bearing inserts with streamlined instrumentation kits.
Hospital systems dominate absolute consumption while outpatient facilities expand their share most aggressively under site-of-service payment reform.
Material:
Margin structures diverge sharply between commodity resin grades and oxidation-stabilized formulations requiring specialized compounding expertise.
- Cross-Linked Polyethylene:Radiation-processed UHMWPE with enhanced wear resistance extends implant functional life beyond fifteen years. Academic medical centers in Boston and Rotterdam specify sequentially annealed variants for high-demand revisions. Vitamin E stabilization addresses residual free radical concerns from irradiation protocols.
- Ultra-High Molecular Weight Polyethylene:Conventional GUR 1020 and 1050 resins serve cost-sensitive applications and emerging markets. First-generation implants and developing country procurement.
- Low-Density Polyethylene:Limited orthopaedic applications due to inferior mechanical properties. Experimental additive manufacturing feedstock trials.
- Others:Antioxidant-infused and highly cross-linked experimental grades under clinical evaluation. Early-adopter academic protocols.
Conventional UHMWPE retains volume leadership in price-sensitive segments while cross-linked formulations capture the steepest expansion trajectory among premium implant portfolios.
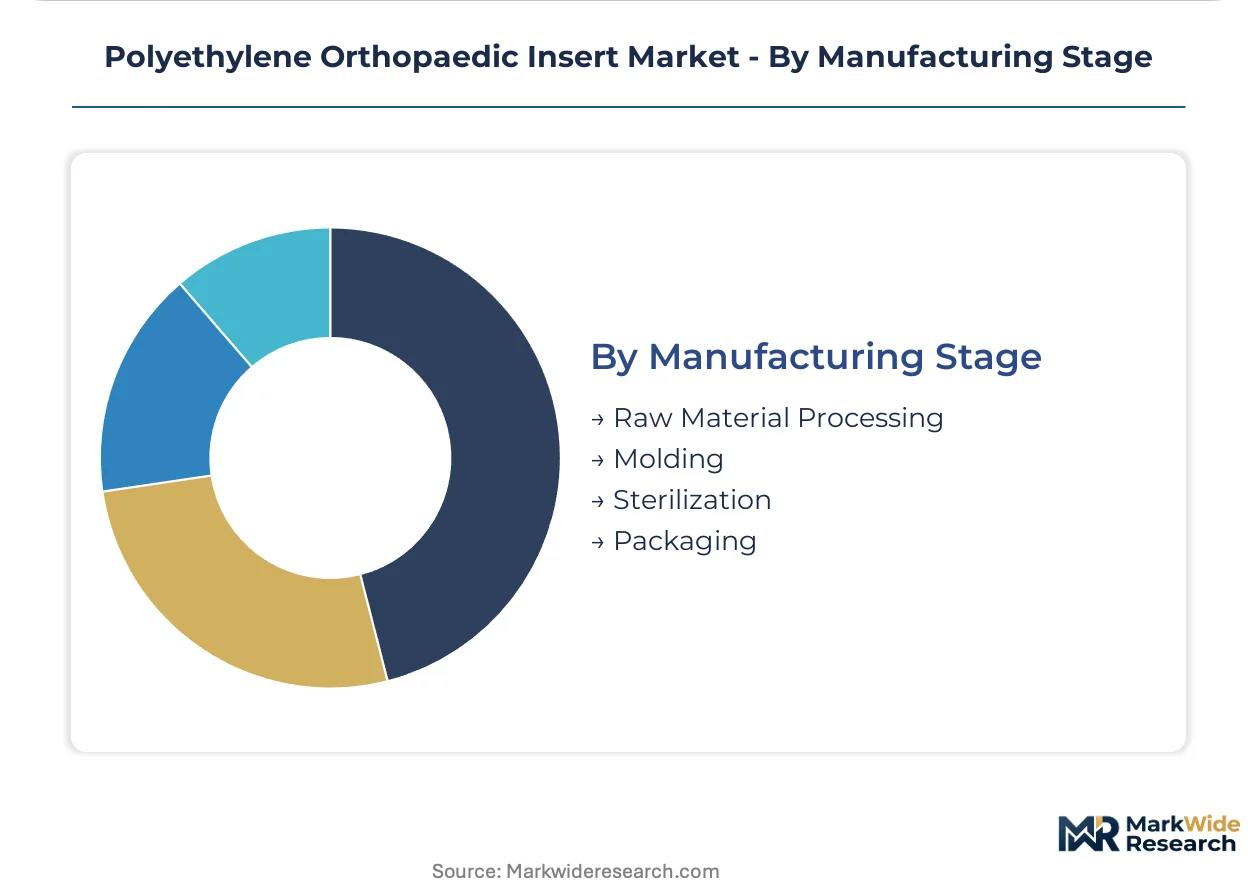
Manufacturing Stage:
Regulatory scrutiny intensifies downstream, with sterilization validation and packaging integrity determining market access timelines.
- Sterilization:Gamma irradiation and ethylene oxide protocols must balance microbial elimination against polyethylene oxidative degradation. FDA dose restrictions and EU MDR validation requirements extend qualification timelines. Alternative technologies face environmental compliance pressures.
- Raw Material Processing:Biomedical-grade resin purification exceeds ISO 5834 implant standards. Three specialized polymer processors control the majority of feedstock supply.
- Molding:Compression and injection molding of bearing surfaces with sub-micron surface finish requirements. Machining centers near surgical device clusters.
- Packaging:Barrier systems maintaining sterility through distribution and shelf life. Tyvek and foil configurations for gamma stability.
Raw material processing anchors supply security concerns while sterilization stages face the steepest regulatory compliance cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany demonstrate the lowest price elasticity, accepting premium formulations for longevity gains, while outpatient facilities in the United States and procurement systems in India prioritize cost containment over material sophistication.
United States
Academic medical centers in Boston and the Mayo Clinic system drive specification of sequentially annealed cross-linked polyethylene for complex revisions. FDA 510(k) clearance pathways govern commercialization timelines, with dose restrictions on gamma irradiation limiting cross-linking density. Ambulatory surgery centers in Florida and Texas now perform the majority of primary knee replacements, favoring fixed-bearing inserts with streamlined instrumentation.
Germany
Charité Berlin and university hospitals anchor European demand for modular insert systems enabling intraoperative flexibility. EU Medical Device Regulation imposes enhanced clinical evidence requirements for CE marking, extending qualification timelines by twelve to eighteen months. The Rhine-Ruhr surgical device cluster concentrates polymer processing expertise and sterilization validation capacity.
Japan
PMDA oversight maintains stringent biocompatibility documentation requirements for implantable polyethylene. METI industrial policy supports domestic resin purification capabilities exceeding ISO 5834 standards. Tokyo and Osaka metropolitan areas concentrate quaternary referral centers specifying vitamin E-stabilized formulations for younger patient cohorts.
India
CDSCO medical device regulations are harmonizing with international standards under the Medical Devices Rules framework. The Production-Linked Incentive scheme attracts polyethylene processors to establish compounding operations near Mumbai and Hyderabad surgical clusters. Cost-sensitive procurement at government hospitals sustains demand for conventional UHMWPE grades.
United Kingdom
NHS England value analysis committees mandate ten-year implant survival data before formulary inclusion of novel polyethylene grades. MHRA post-Brexit regulatory autonomy is recalibrating conformity assessment procedures for implant materials. The Midlands surgical device corridor hosts machining centers serving European OEM supply chains.
Polyethylene Orthopaedic Insert Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized polymer processors commanding premium positions through biomedical-grade resin purification while commodity compounders serve price-sensitive segments. The market exhibits tiered concentration: three specialized processors control the majority of medical-grade UHMWPE feedstock, implant OEMs integrate backward into insert finishing, and regional fabricators compete on sterilization turnaround. Dominant competitive moves include strategic partnerships between resin processors and implant manufacturers for supply continuity, and capacity expansion in India under production-linked incentive schemes.
Among diversified implant OEMs, Stryker and Zimmer Biomet exemplify integrated architectures spanning polymer procurement through finished insert sterilization. DSM Biomedical occupies a specialist position as a biomedical-grade resin purifier supplying formulation-ready materials to device manufacturers. Celanese Corporation represents the chemical-industrial tier with commodity and specialty polymer capabilities serving multiple medical device verticals beyond orthopaedics.
| Leading Market Players |
|---|
| Celanese Corporation |
| DSM Biomedical |
| Orthoplastics Ltd |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson MedTech |
| Smith & Nephew |
| Asahi Kasei Corporation |
| Quadrant Engineering Plastic Products |
| Others |
Value Network & Pricing Analysis
ISO 5834 certification gates both supplier qualification and price differentiation in polyethylene orthopaedic inserts, forcing resin processors to absorb validation costs that separate biomedical-grade feedstock from commodity alternatives. Hospitals and GPOs leverage this certification barrier to consolidate procurement around validated suppliers, while cost-sensitive outpatient facilities source conventional UHMWPE grades through secondary channels.
Pricing Analysis
After-sales revenue from revision component exchanges and extended warranty contracts drives lifetime value for implant manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects cross-linking density and antioxidant stabilization grades. Pricing pressure stems from ambulatory surgery centers demanding fixed-bearing configurations with streamlined instrumentation kits. Academic medical centers in Boston and Germany show lowest price sensitivity, accepting vitamin E-stabilized formulations at substantial premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement, though strategic stockpiling of biomedical-grade resin concentrates among three specialized polymer processors in the United States, Germany, and Japan. Supply chains draw from GUR 1020/1050 resin purification, radiation cross-linking equipment, and gamma sterilization facilities. Single-source vulnerability at specialized compounding operations propagates disruption risk through implant OEMs within weeks. Distribution runs through implant manufacturer direct sales forces and GPO contracts to hospital value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in polyethylene orthopaedic inserts center on revision surgery component programs and sterilization validation services, both expanding faster than primary implant hardware as implant longevity extends patient follow-up timelines.
For Market Incumbents: Consolidate backward integration into biomedical-grade resin purification to secure supply continuity against feedstock concentration risk. Deepen hospital system partnerships through ten-year survival data commitments that lock out emerging competitors from formulary inclusion. For New Entrants and Emerging Players: Anchor in India's Production-Linked Incentive surgical clusters near Mumbai and Hyderabad, where domestic compounding operations serve cost-sensitive government hospital procurement. Target fixed-bearing insert manufacturing for ambulatory surgery centers with simplified instrumentation kits. For Investors and Strategic Acquirers: EU Medical Device Regulation's enhanced clinical evidence requirements reshape the acquisition landscape toward processors with pre-validated sterilization protocols and established CE marking dossiers. Acquisition targets should demonstrate captive biomedical resin supply or exclusive surgeon training program relationships. Watch FDA 510(k) predicate device drift thresholds as the signal for when premarket approval requirements trigger capital-intensive clinical trial obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Biomedical-Grade Resin Purification Investment | ISO 5834-1 compliance secures preferred supplier status with Stryker and Zimmer Biomet. |
| Sequential Annealing Process Adoption | Rotterdam and Boston academic centers specify thermally treated polyethylene for complex revisions. |
| Vitamin E Stabilization Formulation | Fifteen-year functional life claims differentiate premium portfolios for younger patient cohorts. |
| India PLI Scheme Manufacturing Footprint | Domestic compounding near surgical clusters captures government hospital procurement volume. |
| Gamma Sterilization Alternative Validation | EPA environmental compliance upgrades strand legacy ethylene oxide assets at mid-tier processors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR CE marking databases, ISO 5834 standard revision documentation, and hospital GPO contract disclosures. Primary interviews engaged biomedical engineers at implant OEMs, polymer processing technical directors, hospital purchasing committee members, and sterilization validation specialists. Bottom-up demand modeling from procedure volume data triangulates against top-down resin consumption estimates from specialized polymer processors.
Segmentation dimensions modeled include material grade tier, insert architecture type, end-user facility category, and regional regulatory cluster across the analysis window. CAGRs derive from surgical procedure volume trajectories, implant longevity assumptions, and material substitution elasticities. Cross-linking density specifications and gamma sterilization dose constraints inform supply-side capacity modeling.
Decision-makers should treat outputs as directional under assumptions of stable OECD reimbursement for joint replacement procedures and continued FDA gamma irradiation dose limits; material deviation would warrant model refresh. Revision becomes warranted when ceramic-on-ceramic bearing substitution crosses fifteen percent of primary hip arthroplasty volume or when biomedical resin supply disruption exceeds sixty-day continuity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market