
 Venipuncture Needles and Syringes Market | 2026-2036
Venipuncture Needles and Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Venipuncture Needles and Syringes Market Analytics
Hospital group purchasing organizations is reconfiguring how venipuncture products reach end users, consolidating contracts across integrated delivery networks. Becton Dickinson and Company leverages its safety needle portfolio to anchor multi-year supply agreements with major health systems. Smiths Medical competes through specialized blood collection systems designed for high-throughput laboratory environments. Terumo Corporation extends its geographic footprint across Asian markets through localized manufacturing and regulatory registration capabilities.
Venipuncture needles and syringes comprise hollow-bore steel instruments paired with cylindrical barrels, typically manufactured from medical-grade polypropylene or glass, designed for percutaneous vascular access and fluid aspiration or injection. Stainless steel safety needles command premium positioning due to OSHA bloodborne pathogen compliance requirements and integrated retractable or shielded mechanisms that reduce needlestick injuries. Disposable delivery modes dominate volume throughput in hospital settings where single-use protocols eliminate cross-contamination risk, while manual injection systems retain cost advantages in resource-limited clinic environments.
FDA sharp-injury prevention regulations, EU MDR device classification requirements, and ISO 7864 needle performance standards collectively determine product design specifications and market access pathways for manufacturers. The EU MDR transition has forced re-certification timelines that favor established players with dedicated regulatory affairs infrastructure over smaller competitors. Stakeholders must monitor evolving needlestick prevention legislation in emerging markets and assess whether safety feature investments align with procurement budget trajectories in publicly funded health systems.
Market Dynamics
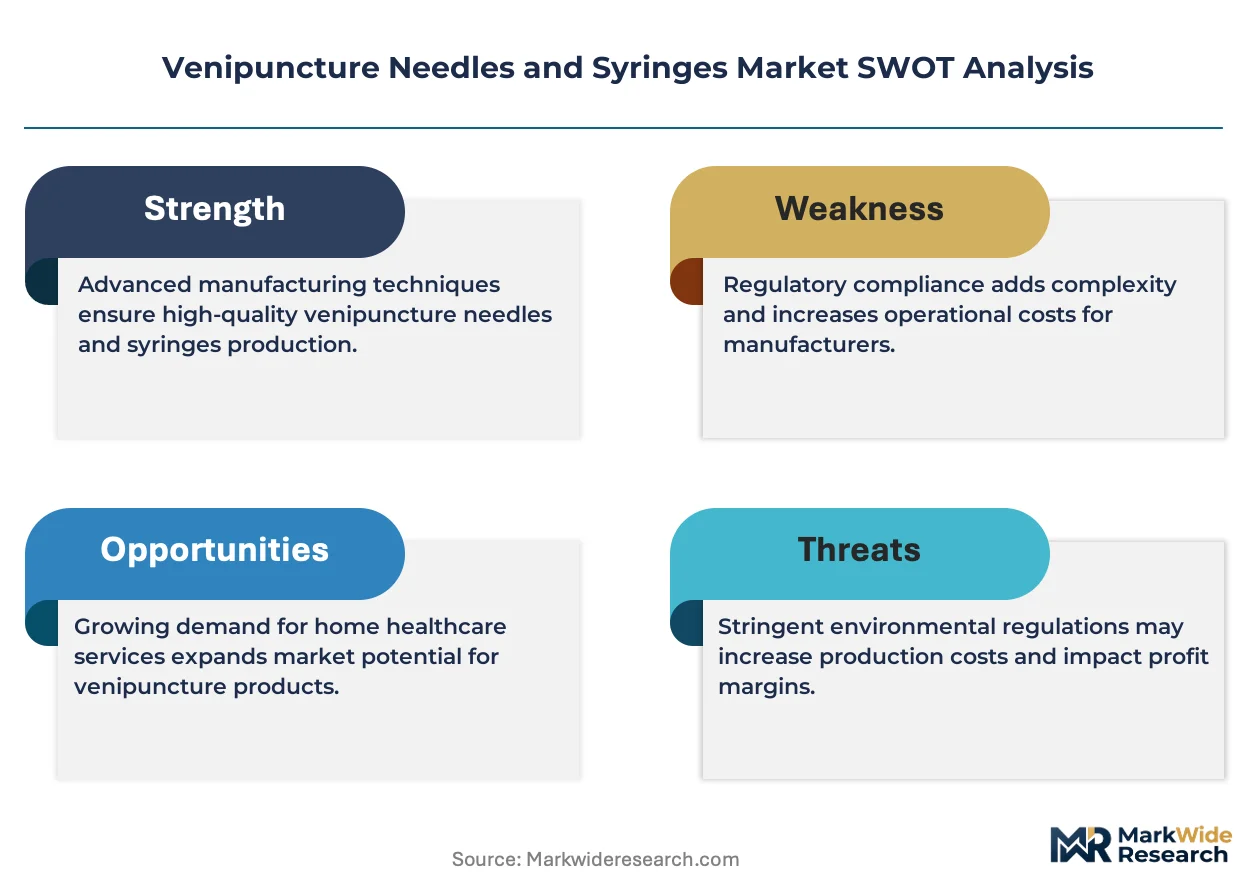
Hospital group purchasing organizations are consolidating venipuncture device contracts across integrated delivery networks, compressing supplier margins while elevating safety-engineered product specifications as non-negotiable procurement criteria.
Growth Catalysts
- EU MDR re-certification mandates:The Medical Device Regulation transition forces healthcare systems to replace legacy needle inventories with compliant safety devices, accelerating replacement cycles across European hospital networks.
- OSHA bloodborne pathogen enforcement:Workplace safety inspections in US acute care facilities drive mandatory adoption of retractable and shielded needle mechanisms, embedding safety features as baseline procurement requirements.
- High-throughput laboratory automation:Clinical diagnostic centers in Japan and Germany deploy integrated blood collection systems that demand precision-engineered needles compatible with robotic handling protocols.
Market Restraints
- Medical-grade stainless steel price volatility:Needle manufacturers face margin pressure from fluctuating nickel and chromium input costs, with specialty alloy suppliers concentrated in Chinese and Russian production zones.
- EU MDR technical documentation burden:Smaller manufacturers lack dedicated regulatory affairs infrastructure to navigate extended conformity assessment timelines, ceding shelf space to established players.
- Safety mechanism complexity premiums:Integrated retractable and shielded designs add 40-60% production cost overhead compared to conventional needles, limiting penetration in publicly funded health systems with fixed reimbursement rates.
Strategic Opportunities
- Indian diagnostic laboratory expansion:Private pathology chains in Mumbai, Delhi, and Bangalore seek automated blood collection systems as patient volumes surge, creating demand for precision venipuncture devices.
- ISO 7864 performance standard convergence:Harmonized needle specification requirements across ASEAN markets reduce regulatory fragmentation, enabling single-SKU strategies for manufacturers with regional distribution networks.
- Home healthcare nursing protocols:Aging-in-place programs in Germany and Japan require simplified safety needle designs for non-clinical settings, opening channels beyond traditional hospital procurement.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at accredited laboratories, extending product launch timelines for novel polymer barrel formulations.
- Legacy sterilization infrastructure:Ethylene oxide facility closures in the US and Europe force manufacturers to validate alternative terminal sterilization methods, requiring capital-intensive process requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venipuncture Needles and Syringes Market |
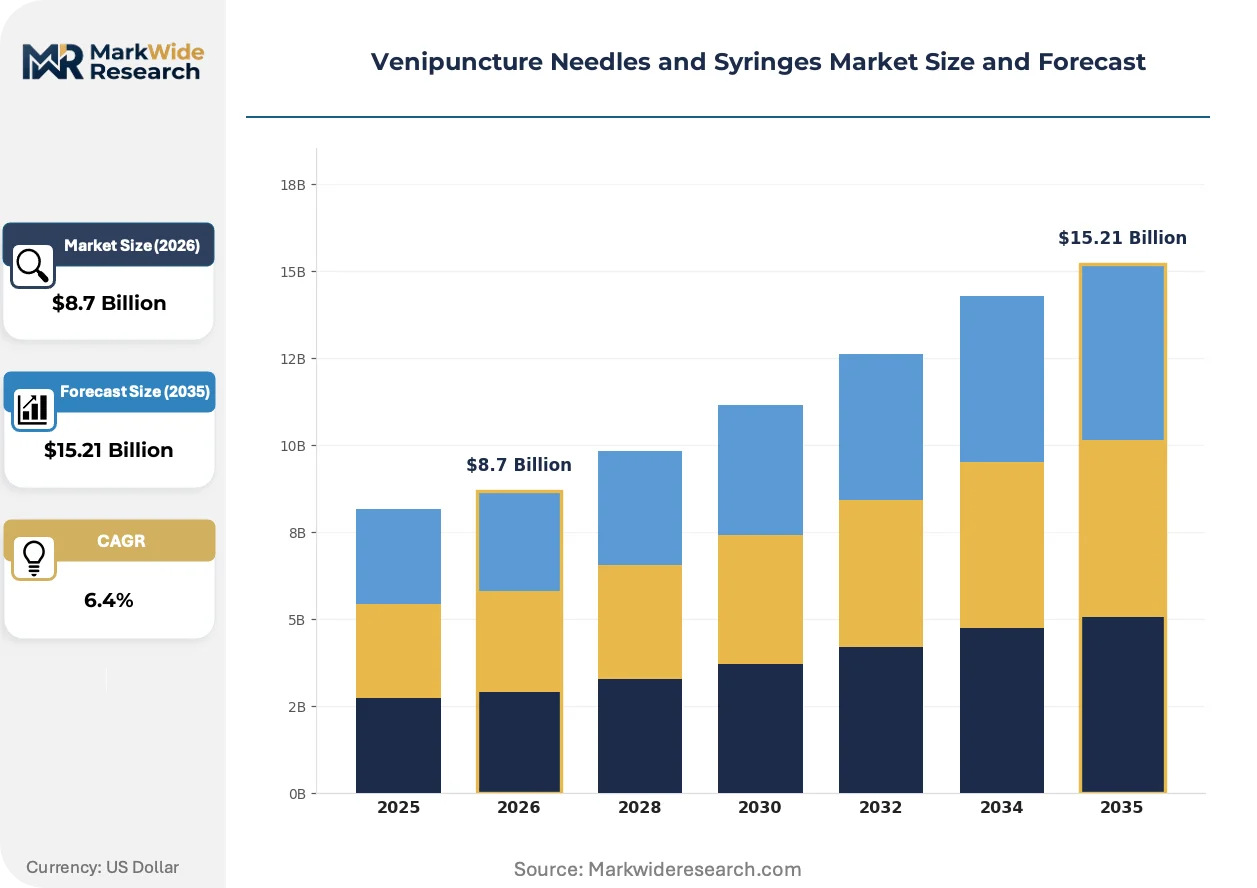
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Needles, Conventional Needles, Insulin Syringes, Blood Collection Tubes Material: Stainless Steel, Plastic, Glass, Rubber End User: Hospitals, Clinics, Homecare, Laboratories Delivery Mode: Manual Injection, Automatic Injection, Reusable, Disposable |
| Companies Covered | Becton Dickinson and Company, Smiths Medical, B. Braun Medical, Cardinal Health, Terumo Corporation, Greiner Bio-One International GmbH, Sarstedt AG & Co. KG, Medline Industries, NIPRO Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venipuncture Needles and Syringes Market Evolving Landscape
Active needle safety mechanisms are displacing passive designs as the dominant engineering paradigm, while regulatory harmonization efforts and procurement centralization reshape competitive positioning across venipuncture device categories.
Retractable needle systems are collapsing the distinction between conventional and safety-engineered devices by embedding automatic retraction triggers within standard injection workflows. Hospital systems in the United States and Germany now specify these mechanisms as default requirements in multi-year supply agreements. The technology is collapsing price premiums historically attached to standalone safety accessories, forcing manufacturers to absorb feature costs within base product pricing.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines from 12 to 36 months for Class IIa needle devices. Established manufacturers with dedicated regulatory affairs teams capture shelf space as smaller competitors withdraw from European markets. Blood collection system suppliers with notified body pre-certification relationships secure preferred vendor status in German and French hospital tenders.
Integrated delivery networks are unbundling device procurement from pharmaceutical distribution contracts, creating direct manufacturer-to-hospital contracting channels. Group purchasing organizations in the United States now negotiate venipuncture device agreements separately from drug formularies, compressing distributor margins. This pattern is most visible in California and Texas health systems where IDN consolidation has concentrated purchasing authority within centralized supply chain functions.
Venipuncture Needles and Syringes Market Segmentation
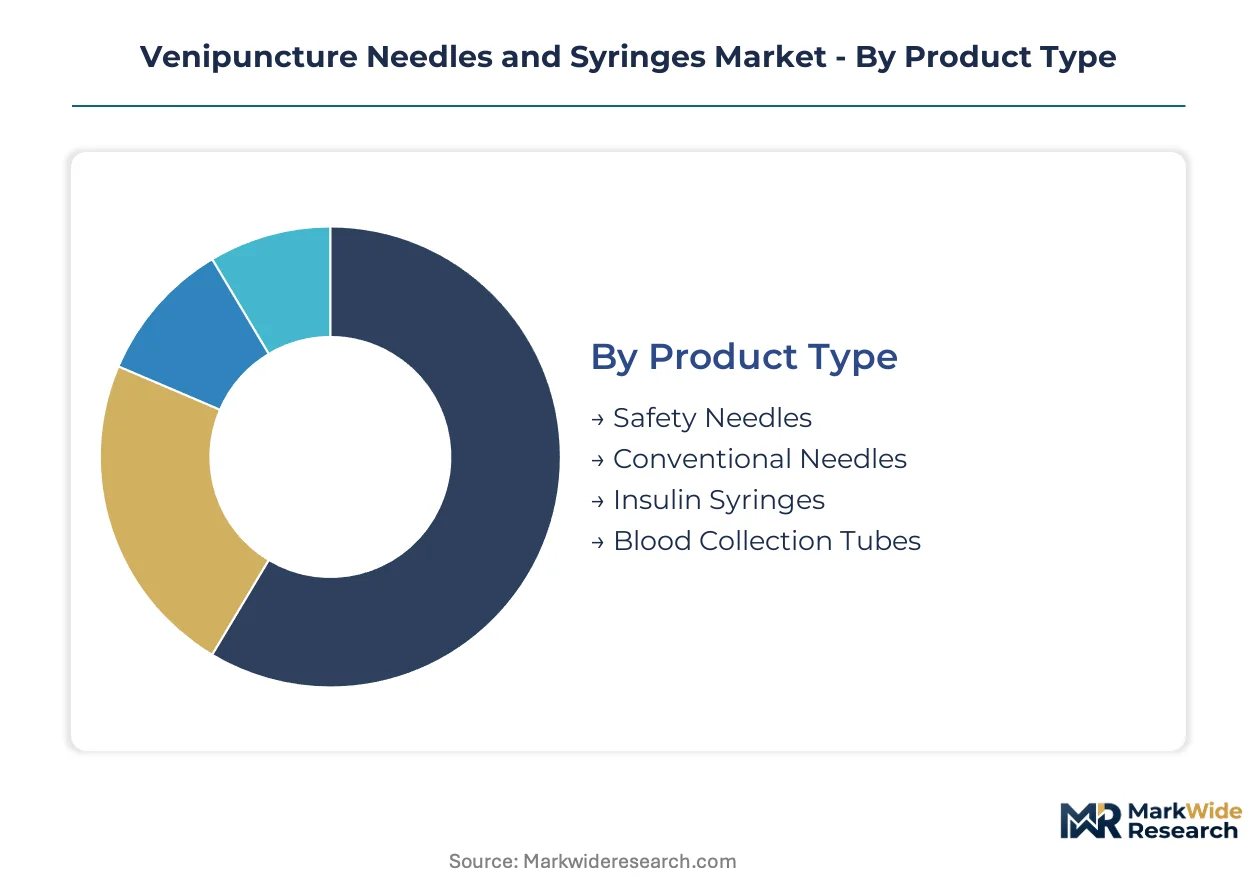
Venipuncture device procurement varies sharply across clinical settings, with safety mandates and throughput requirements driving divergent product specifications. Understanding segment boundaries reveals where manufacturers must prioritize compliance investments versus cost engineering.
Product Type:
Mature safety-engineered designs dominate hospital procurement specifications, while emerging automation-compatible formats reshape laboratory workflows.
- Safety Needles:Stainless steel instruments integrate retractable or shielded mechanisms meeting OSHA bloodborne pathogen standards. United States hospital systems mandate these devices in multi-year supply agreements, embedding injury-prevention features as baseline procurement criteria.
- Conventional Needles:Basic hollow-bore designs without active safety mechanisms retain cost advantages in resource-limited environments. Clinics in publicly funded health systems with fixed reimbursement rates continue sourcing these devices despite regulatory pressure to convert.
- Insulin Syringes:Calibrated barrels with ultra-fine gauge needles optimized for subcutaneous delivery in diabetes management protocols.
- Blood Collection Tubes:Evacuated or open-system containers paired with multi-sample needles for diagnostic laboratory workflows.
Safety Needles handles the majority of throughput; Conventional Needles is the fastest mover on share as emerging markets delay conversion timelines.
Material:
Cost tier differentiation separates premium-grade alloys from commodity polymers in procurement specifications.
- Stainless Steel:Medical-grade alloys with nickel and chromium content deliver structural integrity for precision-ground bevel geometries. German and Japanese manufacturers source specialty steel from concentrated supplier zones, exposing production schedules to raw material price volatility.
- Plastic:Medical-grade polypropylene barrels dominate disposable syringe production through injection-molded manufacturing economies.
- Glass:Borosilicate formulations retain niche applications for drug compatibility requirements in specialized therapeutic injections.
- Rubber:Elastomer plunger tips and needle shields provide seal integrity across temperature variation ranges.
Stainless Steel commands the highest unit economics; Plastic is expanding most quickly as single-use protocols proliferate.
End User:
Customer type determines whether procurement flows through centralized group purchasing or fragmented direct purchasing channels.
- Hospitals:Acute care facilities with integrated delivery network membership consolidate venipuncture device contracts across multi-facility systems. California and Texas health systems concentrate purchasing authority within centralized supply chain functions, compressing distributor margins.
- Clinics:Outpatient settings with lower procedure volumes source through regional distributors rather than direct manufacturer agreements.
- Homecare:Aging-in-place programs in Germany and Japan require simplified safety needle designs for non-clinical administration by patients or family caregivers.
- Laboratories:High-throughput diagnostic centers in Japan deploy automated blood collection systems demanding precision-engineered needles compatible with robotic handling protocols.
Hospitals anchor procurement volume concentration; Homecare is gaining share fastest as chronic disease management shifts outside institutional settings.
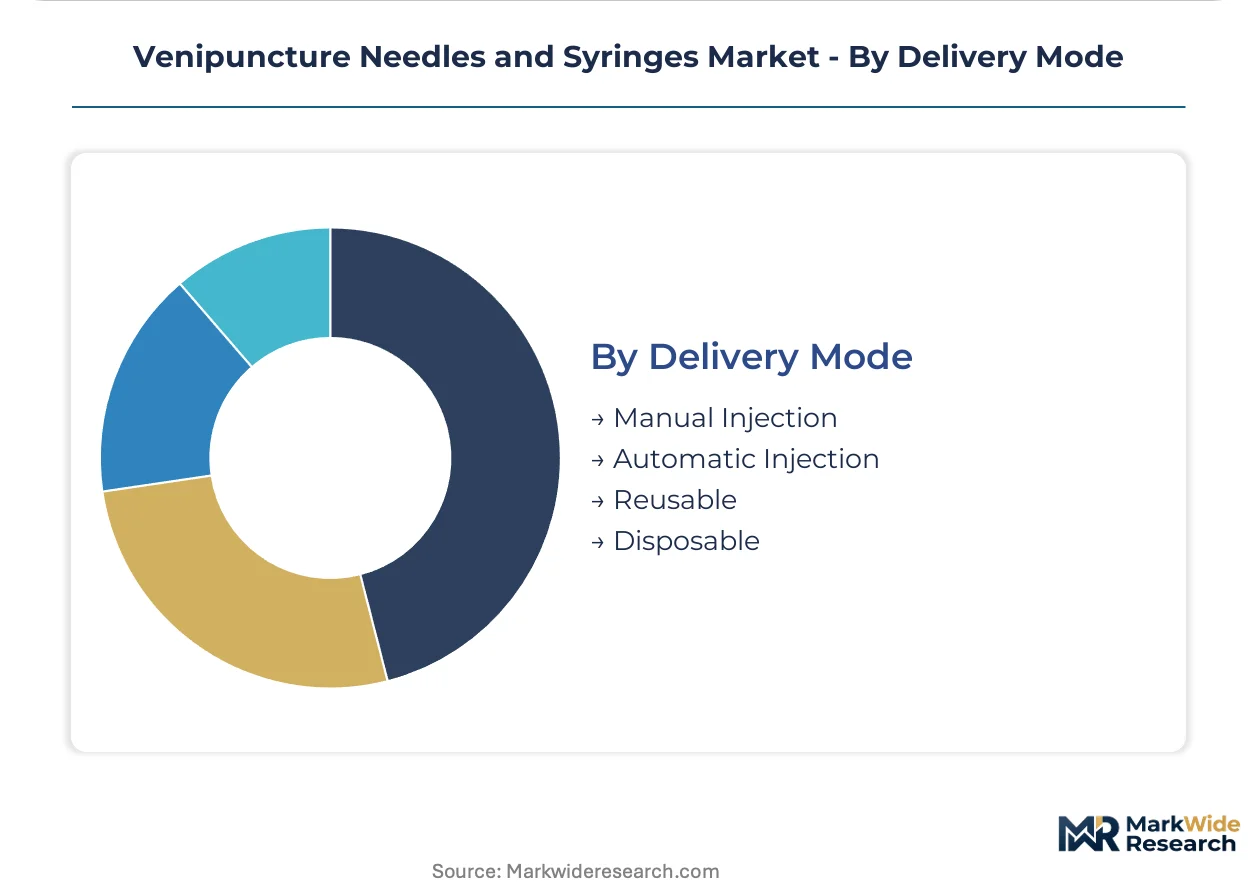
Delivery Mode:
Volume scale separates mass-disposable formats from capital-intensive reusable systems in manufacturing footprint allocation.
- Manual Injection:Hand-actuated plunger mechanisms retain cost advantages in clinic environments where procedure volumes do not justify automation infrastructure.
- Automatic Injection:Spring-loaded or gas-powered devices deliver fixed dosing in emergency medicine and mass vaccination campaigns.
- Reusable:Sterilizable glass-and-metal systems persist in limited veterinary and research applications despite healthcare sector single-use protocol dominance.
- Disposable:Pre-sterilized single-unit packaging eliminates cross-contamination risk in hospital settings where infection control protocols mandate one-device-one-patient workflows.
Disposable formats capture the steepest expansion trajectory; Manual Injection retains residual share in budget-constrained procurement environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese procurement channels where safety-engineered specifications command premium positioning, while Indian and Brazilian markets operate on compressed margins driven by volume-scale negotiations and public tender constraints.
United States
Hospital group purchasing organizations in California and Texas consolidate venipuncture device contracts across integrated delivery networks, compressing distributor margins while elevating OSHA bloodborne pathogen compliance to non-negotiable status. FDA sharp-injury prevention regulations mandate retractable or shielded needle mechanisms in acute care facilities. The Boston-Cambridge corridor anchors high-throughput laboratory automation demand from clinical diagnostic centers.
Germany
Aging-in-place programs across Bavaria and North Rhine-Westphalia generate demand for simplified safety needle designs suitable for non-clinical administration by patients or family caregivers. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines, favoring established manufacturers with dedicated regulatory infrastructure. The Rhine-Ruhr industrial cluster concentrates precision blood collection system production for European hospital networks.
Japan
High-throughput diagnostic centers in Tokyo and Osaka deploy automated blood collection systems requiring precision-engineered needles compatible with robotic handling protocols. METI industrial standards harmonize with ISO 7864 needle performance specifications, streamlining domestic manufacturer certification. The Kansai region hosts specialized production facilities serving Asian laboratory automation markets.
India
Private pathology chains in Mumbai, Delhi, and Bangalore seek automated blood collection systems as patient volumes surge through tier-1 urban diagnostic networks. CDSCO medical device registration requirements tighten quality documentation standards for imported venipuncture products. The Maharashtra-Gujarat pharmaceutical manufacturing corridor expands domestic production capacity for disposable syringe exports.
Brazil
Public health system procurement through ANVISA-regulated tenders prioritizes cost-engineered conventional needles over safety-engineered alternatives, delaying conversion timelines. São Paulo and Rio de Janeiro hospital networks consolidate supply agreements with regional distributors rather than direct manufacturer contracts. The Southeast industrial zone concentrates injection-molded polypropylene barrel production for Latin American markets.
Venipuncture Needles and Syringes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in needle fabrication and barrel molding. The vendor base separates into consolidated multinational manufacturers with full regulatory infrastructure and mid-scale regional fabricators serving price-sensitive procurement channels. Three archetypes dominate: safety-engineered platform developers, high-throughput laboratory system integrators, and commodity disposable producers. Competitive moves center on M&A for regulatory asset acquisition and strategic partnerships for geographic distribution expansion.
Within the platform integrator tier, Becton Dickinson and Company and Terumo Corporation exemplify multinational manufacturers with established notified body relationships and multi-year hospital supply agreements. Smiths Medical occupies a position among laboratory system specialists serving automated blood collection workflows. These three anchors represent divergent strategic postures: safety portfolio breadth, Asian market localization, and diagnostic automation compatibility respectively.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Smiths Medical |
| B. Braun Medical |
| Cardinal Health |
| Terumo Corporation |
| Greiner Bio-One International GmbH |
| Sarstedt AG & Co. KG |
| Medline Industries |
| NIPRO Medical Corporation |
| Others |
Value Network & Pricing Analysis
The Maharashtra-Gujarat pharmaceutical manufacturing corridor anchors global disposable syringe production capacity, concentrating polypropylene barrel molding and stainless steel needle fabrication that feeds downstream pricing power into European and North American hospital procurement channels. This geographic concentration creates asymmetric leverage where supply disruptions ripple immediately into contract renegotiations.
Pricing Analysis
Configured-to-order safety needle systems command 40-60% premiums over standard conventional needles, with pricing stratifying across premium, standard, and economy tiers driven by OSHA compliance certification and volume scale. Stainless steel grade differentiation and integrated retractable mechanism complexity anchor price spreads. Pricing pressure stems from group purchasing organization consolidation compressing distributor margins. Publicly funded health systems exhibit highest price sensitivity; integrated delivery networks in California and Texas demonstrate lowest sensitivity due to bundled safety compliance requirements.
Supply Chain Analysis
Upstream medical-grade stainless steel feedstock draws from concentrated Chinese and Russian nickel-chromium production zones, while medical-grade polypropylene resin sources from petrochemical complexes in the United States, Germany, and Saudi Arabia. Raw material dependencies center on specialty alloy suppliers, polymer resin producers, and sterilization gas providers. Single-source vulnerability in ethylene oxide terminal sterilization infrastructure poses structural risk following facility closures in the United States and Europe. Distribution runs through hospital group purchasing organizations and regional medical distributors serving clinic and laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as EU MDR re-certification mandates force replacement of legacy needle inventories across European hospital networks, triggering capital expenditure cycles that favor compliant manufacturers.
For Market Incumbents: Entrench safety-engineered platform dominance through backward integration into stainless steel needle fabrication and captive sterilization capacity. Expand regulatory affairs infrastructure to capture shelf space as smaller competitors withdraw from EU MDR extended conformity timelines. Prioritize multi-year supply agreement renewals with integrated delivery networks before contract windows close. For New Entrants and Emerging Players: Establish a beachhead in Indian private pathology chains seeking automated blood collection systems, where CDSCO registration requirements create defensible moats against multinational incumbents. Target tier-2 diagnostic laboratory segments with simplified safety needle designs bypassing complex retractable mechanisms. Pursue regulatory partnerships with established notified bodies to accelerate market access timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because safety mandate expansion across emerging markets creates durable demand for certified manufacturers. Acquisition targets should concentrate on mid-scale regional fabricators with existing ISO 7864 certification and Asian distribution networks. Watch for EU MDR notified body pre-certification relationships as the inflection signal for preferred vendor status in German and French hospital tenders.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Pre-Certification | Secures 36-month conformity assessment timelines and preferred vendor status in German hospital tenders. |
| Backward Integration into Needle Fabrication | Captures stainless steel processing margins and insulates against Chinese and Russian alloy price volatility. |
| Hospital System Direct Partnership | Bypasses distributor compression in California and Texas integrated delivery network procurement channels. |
| Automated Blood Collection System Integration | Aligns with Tokyo and Osaka laboratory robotics protocols driving Japanese diagnostic center demand. |
| Alternative Sterilization Method Validation | Reduces ethylene oxide facility dependency following closures in United States and European production zones. |
Research Methodology
A standing panel of hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs directors provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract repositories, and ISO certification registries. Bottom-up demand modeling triangulated against top-down macro healthcare expenditure trends.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling venipuncture device demand by product type, end-user setting, material grade, and regional regulatory cluster. CAGRs derived from procedure volume growth rates, replacement cycle acceleration, and safety conversion penetration curves. Industry-specific inputs incorporated OSHA inspection enforcement patterns and EU MDR re-certification completion rates.
Sensitivities concentrate around EU MDR technical documentation bottlenecks, ethylene oxide sterilization capacity constraints, and nickel price volatility in specialty stainless steel supply. Forecasts reflect documented assumptions regarding regulatory timeline adherence and procurement budget trajectories in publicly funded health systems. Cross-checking against CMS Medicare outpatient procedure databases and German hospital procurement association contract awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Global Swab Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Global Urinary Drainage Bags Market