
 Prosthetics and Orthotics Market | 2026-2036
Prosthetics and Orthotics Market Size, Share, and Industry Trends Forecast 2026-2036
Prosthetics and Orthotics Market Intelligence
Sports facilities is restructuring demand patterns across the prosthetics and orthotics landscape, pulling manufacturers toward performance-oriented limb systems. Ottobock leverages its biomechanics heritage to dominate high-activity prosthetic segments. Össur anchors its position through sustained R&D intensity in carbon fiber foot and knee systems. Fillauer specializes in upper-limb componentry, competing on customization depth rather than volume scale.
Prosthetics and orthotics encompass custom-fabricated and prefabricated devices that replace or support musculoskeletal functions, typically utilizing carbon fiber composites, titanium alloys, thermoplastic polymers, and silicone liners manufactured through CAD/CAM workflows, vacuum forming, and additive fabrication to restore mobility or correct biomechanical alignment. Orthotic braces and prosthetic limbs command the largest revenue pools, with orthotic braces benefiting from chronic condition prevalence and prosthetic limbs capturing premium margins through microprocessor-controlled joints. 3D printing is displacing conventional carving in socket production, while smart sensors represent the fastest-growing technology segment as real-time gait feedback becomes reimbursable in select markets.
FDA breakthrough device designations and the EU MDR framework are tightening clinical evidence requirements for smart prosthetics, reshaping how manufacturers structure premarket submissions. ISO 10328 structural testing standards and WHO prosthetic guidelines establish baseline safety benchmarks that determine market access eligibility across developed and developing health systems. Stakeholders must monitor reimbursement coding evolution for sensor-enabled devices, as payment policy lags behind technical capability in most jurisdictions.
Market Dynamics
Microprocessor-controlled joint systems are compressing product lifecycles as manufacturers race to integrate real-time gait feedback capabilities before reimbursement codes stabilize. This technical arms race is restructuring competitive positioning around sensor-integrated platforms rather than mechanical componentry.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated approval track for smart sensor-integrated prosthetics is compressing time-to-market for biomechanical innovators, enabling faster clinical validation of microprocessor knees.
- Sports Medicine Facilities:Performance-oriented limb systems are pulling manufacturers toward carbon fiber foot designs optimized for high-activity users, creating premium pricing power in athletic rehabilitation centers.
- Aging Demographics in Japan:Japan's super-aged population and universal health coverage framework are sustaining demand for orthotic braces addressing chronic musculoskeletal conditions.
Market Restraints
- Titanium Alloy Supply Concentration:Aerospace and medical device competition for titanium mill products creates input cost volatility for socket and pylon manufacturers.
- EU MDR Clinical Evidence Burden:The EU MDR framework's tightened premarket submission requirements for Class IIb prosthetics are extending certification timelines and inflating regulatory compliance costs.
- Silicone Liner Durability Limitations:Current elastomer formulations require replacement every 6-18 months, creating persistent after-market service costs that constrain total cost-of-ownership optimization.
Strategic Opportunities
- Additive Manufacturing Convergence:3D printing is converging with AI-driven socket design to enable same-day prosthetic fitting in underserved rural clinics, compressing the traditional multi-visit fabrication process.
- Germany's Reimbursement Leadership:The German statutory health insurance system's early adoption of sensor-enabled device codes creates a testbed for value-based prosthetic pricing models.
- Pediatric Orthotics White Space:Rapid-growth adjustable brace systems for adolescent scoliosis remain underpenetrated, with current offerings failing to match anatomical progression rates.
Industry Challenges
- Prosthetist Training Pipeline Gap:Accredited orthotics and prosthetics programs graduate fewer certified clinicians than replacement demand requires, particularly for CAD/CAM workflow proficiency.
- Legacy Electronic Health Record Integration:Gait sensor data formats lack standardization across hospital systems, forcing manufacturers to maintain multiple software interfaces.
- ISO 10328 Testing Capex:Structural fatigue validation equipment for lower-limb prosthetic components requires substantial capital investment that mid-scale fabricators struggle to absorb.
Report Scope
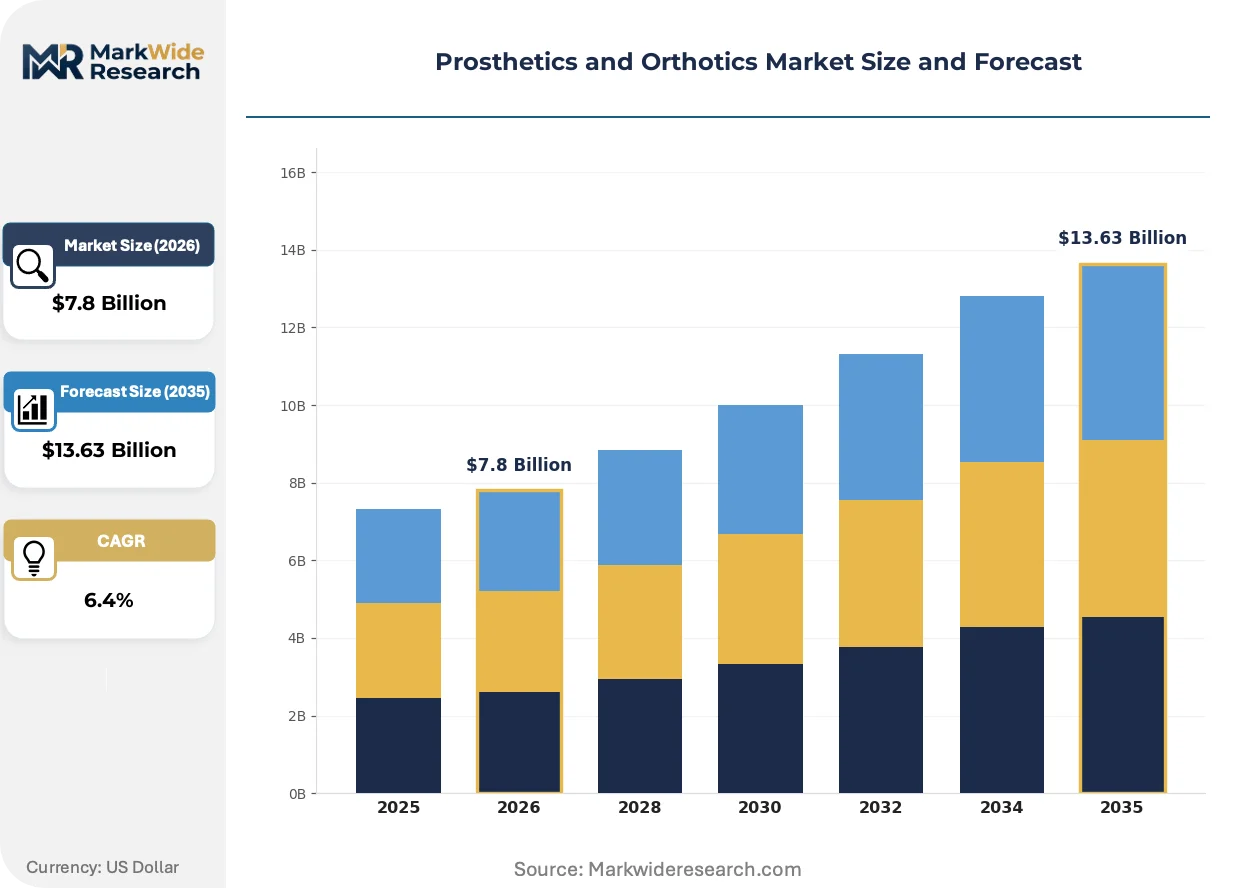
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prosthetics and Orthotics Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Limbs, Orthotic Braces, Artificial Joints, Foot Insoles Technology: CNC Machining, 3D Printing, Biomechanics, Smart Sensors End User: Hospitals, Rehabilitation Centers, Home Care, Sports Facilities Distribution Channel: Direct Sales, Online Retail, Wholesalers, Clinics |
| Companies Covered | Fillauer, Freedom Innovations, Ottobock, Proteor, Hanger, Össur, College Park Industries, Coloplast, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prosthetics and Orthotics Market Strategic Shifts & Innovations
Real-time biomechanical feedback systems are compressing the gap between prosthetic prescription and functional optimization. This shift is pulling R&D investment toward software-enabled platforms rather than purely mechanical componentry.
Machine learning algorithms are converging with socket pressure mapping to enable predictive fit adjustments before tissue breakdown occurs. Veterans Affairs medical centers are piloting these systems for transtibial amputees, with early deployments showing reduced revision rates. The technology is converging with remote monitoring infrastructure to enable prosthetist intervention without clinic visits.
The EU MDR's post-market surveillance requirements are forcing manufacturers to maintain active implant registries for microprocessor joints. This policy is compressing profit margins for legacy mechanical knee suppliers while accelerating consolidation around data-capable platform vendors. German and French notified bodies are processing Class III prosthetic submissions with extended clinical follow-up demands.
Hospital procurement committees are unbundling after-sales service from device acquisition, creating standalone maintenance contract markets. This pattern is visible most acutely in United States academic medical centers, where orthopedic service lines now negotiate socket replacement schedules separately from initial limb fitting. Independent orthotic facilities are responding with subscription-based liner replacement programs.
Prosthetics and Orthotics Market Segmentation
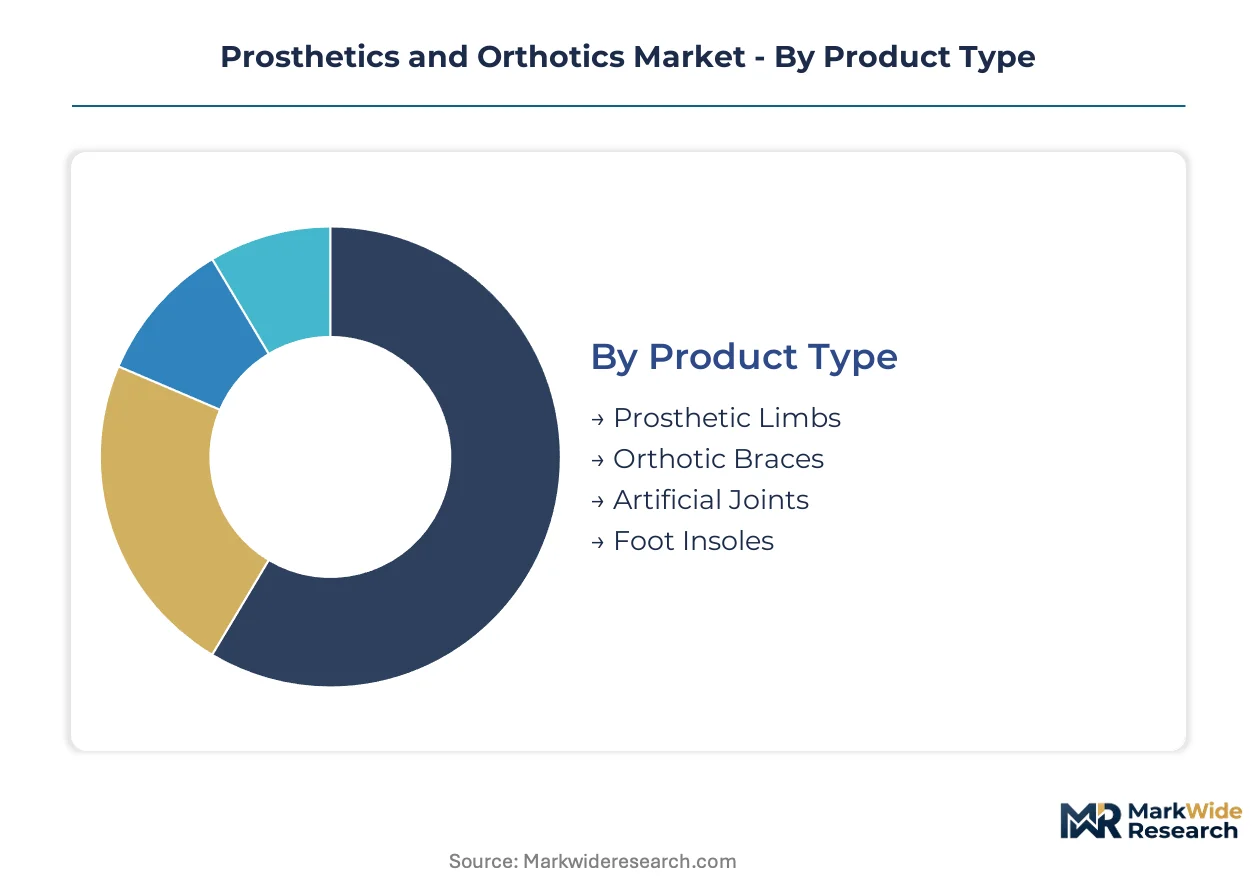
Segmentation in prosthetics and orthotics reveals how technical specifications reshape procurement patterns across clinical and consumer channels. Manufacturers calibrate their portfolios around fabrication method, care setting, and distribution economics rather than device function alone.
Product Type:
Material composition and reimbursement coding determine margin structure across device categories.
- Prosthetic Limbs:Carbon fiber pylons and titanium socket connectors constitute the premium tier, with microprocessor knee units commanding extended clinical validation timelines. Demand concentrates in United States Veterans Affairs medical centers and German statutory insurance networks where value-based procurement frameworks reward functional outcomes over device acquisition cost.
- Orthotic Braces:Thermoplastic ankle-foot orthoses and custom-molded spinal braces address chronic musculoskeletal conditions in aging populations. Japan's universal coverage system sustains volume for prefabricated lumbar supports, while German rehabilitation clinics drive adoption of sensor-integrated posture correction systems.
- Artificial Joints:Silicone metacarpophalangeal implants and mechanical digit prostheses serve traumatic injury reconstruction.
- Foot Insoles:CAD/CAM-milled orthotic inserts compete with pressure-mapped prefabricated alternatives in podiatry clinics.
Prosthetic limbs lead on scale; smart sensor-integrated variants gain share fastest.
Technology:
Manufacturing workflow selection dictates capital intensity and customization depth for fabricators.
- CNC Machining:Subtractive manufacturing of titanium pylons and aluminum knee joints delivers dimensional precision for high-load applications. German and Swiss component suppliers maintain capacity leadership, though tooling costs constrain same-day fabrication economics.
- 3D Printing:Selective laser sintering of nylon sockets and fused deposition modeling of check sockets compress multi-visit fitting protocols. United States rural health clinics and Indian charitable prosthetic camps deploy these systems to circumvent prosthetist shortages.
- Biomechanics:Gait laboratory motion capture and finite element modeling inform prescription decisions in academic medical centers.
- Smart Sensors:Strain gauges and inertial measurement units embedded in prosthetic feet transmit real-time loading data.
CNC machining anchors current fabrication volume; 3D printing expands most quickly in underserved access points.
End User:
Care setting determines reimbursement pathway and service bundling requirements.
- Hospitals:Acute care orthopedic departments and level-1 trauma centers manage immediate post-amputation fitting and complex revision surgeries. United States academic medical centers unbundle device procurement from prosthetist services, creating standalone maintenance contract markets.
- Rehabilitation Centers:Specialized gait training facilities and vocational rehabilitation programs optimize functional outcomes for insured working-age amputees. German and Japanese statutory frameworks cover extended therapy episodes.
- Home Care:Direct-to-consumer liner replacement and remote socket adjustment services bypass traditional clinic visits.
- Sports Facilities:Performance-oriented carbon fiber sprinting prostheses and rock-climbing terminal devices serve athletic rehabilitation segments.
Hospitals dominate revenue concentration; sports facilities climb fastest as athletic prosthetics gain reimbursement traction.
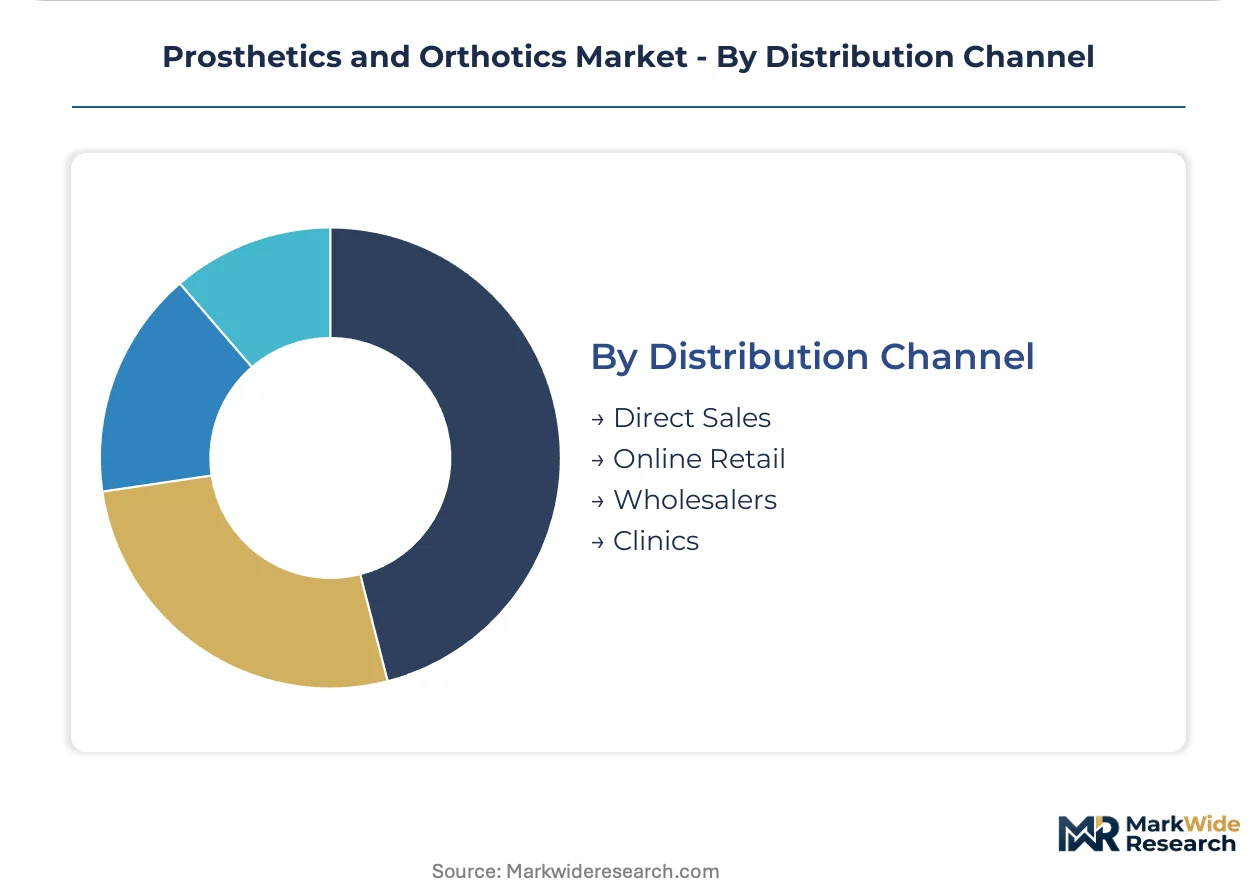
Distribution Channel:
Channel selection reflects customer technical sophistication and regulatory compliance burden.
- Direct Sales:Manufacturer-employed prosthetists and orthotists deliver custom-fabricated devices in owned clinics, capturing full margin stack. Ottobock and Össur operate flagship fitting centers in Munich and Reykjavik.
- Online Retail:Prefabricated ankle braces and compression garments reach consumers through orthopedic supply portals. United States durable medical equipment suppliers navigate HIPAA compliance for remote patient data collection.
- Wholesalers:Regional medical device distributors stock prefabricated components for independent orthotic facilities.
- Clinics:Independent prosthetic practices and hospital-affiliated orthotic departments serve as primary prescription fulfillment points.
Direct sales commands premium pricing power; online retail scales fastest in standardized product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling prosthetic manufacturing toward jurisdictions with streamlined medical device frameworks. Fabricators migrate certification costs across borders while maintaining proximity to reimbursement-rich patient pools.
United States
Veterans Affairs medical centers and academic hospital networks sustain premium demand for microprocessor-controlled limbs. FDA breakthrough device designations compress approval timelines for sensor-integrated systems. The Minneapolis-Saint Paul corridor concentrates independent prosthetic fabrication shops serving upper-midwest rehabilitation networks.
Germany
Statutory health insurance frameworks cover sensor-enabled device codes earlier than peer markets, creating pricing testbeds for value-based models. EU MDR notified bodies in Berlin and Munich process Class III prosthetic submissions with extended clinical follow-up requirements. The Duderstadt cluster anchors Ottobock's flagship fitting centers and biomechanics R&D.
Japan
Super-aged demographics and universal coverage sustain orthotic brace volume for chronic musculoskeletal conditions. METI standards harmonization with ISO 10328 structural testing benchmarks streamlines import pathways for foreign manufacturers. Osaka-Kobe industrial corridors host precision machining suppliers for titanium pylon components.
United Kingdom
NHS procurement unbundling separates device acquisition from prosthetist services, fragmenting traditional supply relationships. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR compliance timelines for smart prosthetics. London teaching hospitals pilot remote gait monitoring integration with electronic health records.
India
Charitable prosthetic camps and rural health clinics deploy 3D-printed check sockets to circumvent certified prosthetist shortages. CDSCO medical device rules classify lower-limb prosthetics under notified category standards with simplified registration. Jaipur and Chennai host nonprofit fabrication networks serving amputee populations outside formal reimbursement systems.
Prosthetics and Orthotics Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers expand beyond mechanical componentry into software-enabled platforms. The vendor base separates into three tiers: integrated multinationals with owned clinic networks, specialized component suppliers competing on customization depth, and regional fabricators serving price-sensitive institutional contracts. Two strategic archetypes define positioning: sensor-integrated platform vendors capturing extended service revenue, and carbon fiber specialists defending premium athletic segments. M&A activity concentrates on digital health capabilities, while capacity expansion targets additive manufacturing for same-day socket production.
Among European-anchored multinationals, Ottobock GmbH and Össur hf exemplify divergent specialization strategies within the premium tier. Ottobock's Munich heritage situates it within the biomechanics-integrated archetype, while Össur's Reykjavik origins align with carbon fiber performance-system positioning. Fillauer LLC represents the North American component-specialist archetype, competing on upper-limb customization rather than volume scale. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic moves.
| Leading Market Players |
|---|
| Fillauer |
| Freedom Innovations |
| Ottobock |
| Proteor |
| Hanger |
| Össur |
| College Park Industries |
| Coloplast |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Microprocessor knee certification tiers split the prosthetics landscape into reimbursement-gated premium segments and commodity mechanical alternatives, with FDA breakthrough designation status determining whether manufacturers capture value-based pricing or compete on socket fabrication cost. This bifurcation concentrates supply chain investment around German and United States distribution hubs serving statutory insurance networks, while Indian charitable camps and rural clinics absorb lower-tier components through decentralized 3D printing nodes.
Pricing Analysis
Distributor margins for prefabricated orthotic braces compress pricing power at the mid-tier, while direct-to-clinic sales of microprocessor-controlled limbs sustain premium capture through bundled prosthetist service contracts. Pricing stratifies across premium, standard, and economy tiers based on ISO 10328 structural testing certification and silicone liner material grade. Cost compression in standard mechanical knees is intensifying because titanium alloy input volatility forces socket manufacturers to absorb margin erosion. Hospital procurement committees exhibit highest price sensitivity for prefabricated ankle-foot orthoses, whereas Veterans Affairs medical centers prioritize functional outcome metrics over device acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for carbon fiber composite prepregs and titanium mill products, with last-mile fabrication shifting toward owned clinic networks. Raw material dependencies center on aerospace-grade titanium alloys from Japanese and German suppliers, carbon fiber from Toray's global production base, and medical-grade silicone elastomers. Single-source vulnerability concentrates in microprocessor joint controller boards sourced from concentrated electronics manufacturing clusters. Distribution runs through manufacturer-employed prosthetists in flagship fitting centers, supplemented by independent orthotic facilities stocking prefabricated components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in prosthetics and orthotics rests on additive manufacturing cost-down trajectories compressing socket production labor content, alongside sensor-integrated device codes unlocking premium reimbursement bandwidth in German statutory frameworks.
For Market Incumbents: Deepen backward integration into carbon fiber prepreg manufacturing to defend margin position against aerospace demand competition for titanium mill products. Prioritize ISO 10328 testing equipment captive ownership to accelerate certification timelines for microprocessor knee platforms. Secure exclusive prosthetist training pipeline partnerships to constrain CAD/CAM workflow talent availability for emerging competitors. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for biomechanical innovators to compress clinical validation timelines and capture early reimbursement code establishment for real-time gait feedback systems. Target pediatric orthotics white space in rapid-growth adjustable scoliosis brace systems where current offerings fail to match anatomical progression rates. Deploy direct-to-consumer remote socket adjustment services to bypass established clinic network gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fabricators struggle to absorb EU MDR post-market surveillance compliance costs for microprocessor joint registries. Long-term viability favors platform vendors capturing extended service revenue over mechanical component suppliers facing unbundled procurement trends. Watch German reimbursement coding evolution for sensor-enabled devices as the inflection indicator for value-based pricing model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Early engagement with German statutory health insurance codes for sensor-enabled devices secures premium pricing testbed positioning. |
| Software Companion Development | Gait sensor data platform integration with Veterans Affairs electronic health record systems creates proprietary data moats. |
| Hospital System Partnership | Academic medical center orthopedic service line alliances enable unbundled maintenance contract capture beyond initial device sale. |
| CE Marking Pathway | EU MDR Class III prosthetic submissions with extended clinical follow-up requirements filter out undercapitalized competitors. |
| Manufacturing Scale-Up | Selective laser sintering socket production capacity expansion targets same-day fitting economics in underserved rural markets. |
Research Approach
Multiple input streams — prosthetist interviews at Veterans Affairs medical centers, regulatory affairs discussions with notified bodies, and procurement committee dialogues at academic hospital networks — were reconciled against secondary validation from FDA 510(k) filings, EU MDR submission databases, and German statutory health insurance reimbursement code records. Bottom-up fabrication volume estimates from Ottobock and Össur facility footprints were triangulated with top-down spending analysis from CMS Medicare prosthetic claims data and Japanese universal coverage orthotic brace utilization statistics.
Data-stream reconciliation across product type, technology adoption curve, end-user care setting, and regional reimbursement framework dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical prosthetic limb and orthotic brace shipment trajectories, with cross-segment elasticity parameters capturing substitution effects between 3D-printed sockets and CNC-machined alternatives. Microprocessor knee adoption rates and sensor-integrated device code expansion timelines served as primary demand-side forecast inputs.
Revisions become necessary when FDA breakthrough device designation criteria shift, EU MDR notified body processing capacity constraints intensify, or titanium alloy aerospace demand spikes disrupt medical device supply allocations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market