
 Europe Kyphoplasty Market | 2026-2036
Europe Kyphoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kyphoplasty Market Insights
German orthopedic cement manufacturers is realigning production priorities toward high-viscosity formulations for vertebral augmentation. Medtronic leverages its integrated spine portfolio to sustain channel dominance across European hospital purchasing consortia. Stryker Corporation anchors its position through specialized balloon catheter systems designed for lumbar and thoracic procedures. Joimax GmbH competes with German-engineered endoscopic navigation platforms that integrate with kyphoplasty workflows.
Kyphoplasty is a percutaneous vertebral augmentation procedure in which an inflatable bone tamp creates a cavity within a fractured vertebral body, followed by injection of polymethylmethacrylate cement under fluoroscopic guidance to restore height and mechanical stability. Balloon kyphoplasty systems command premium positioning due to controlled cavity creation and reduced cement leakage risk compared to conventional vertebroplasty. Hospitals represent the dominant end-user channel, though ambulatory surgical centers are capturing faster volume growth as minimally invasive procedure protocols shorten recovery timelines. Osteoporotic fracture applications constitute the mature revenue base, while tumor-related fracture indications present higher-margin expansion opportunities.
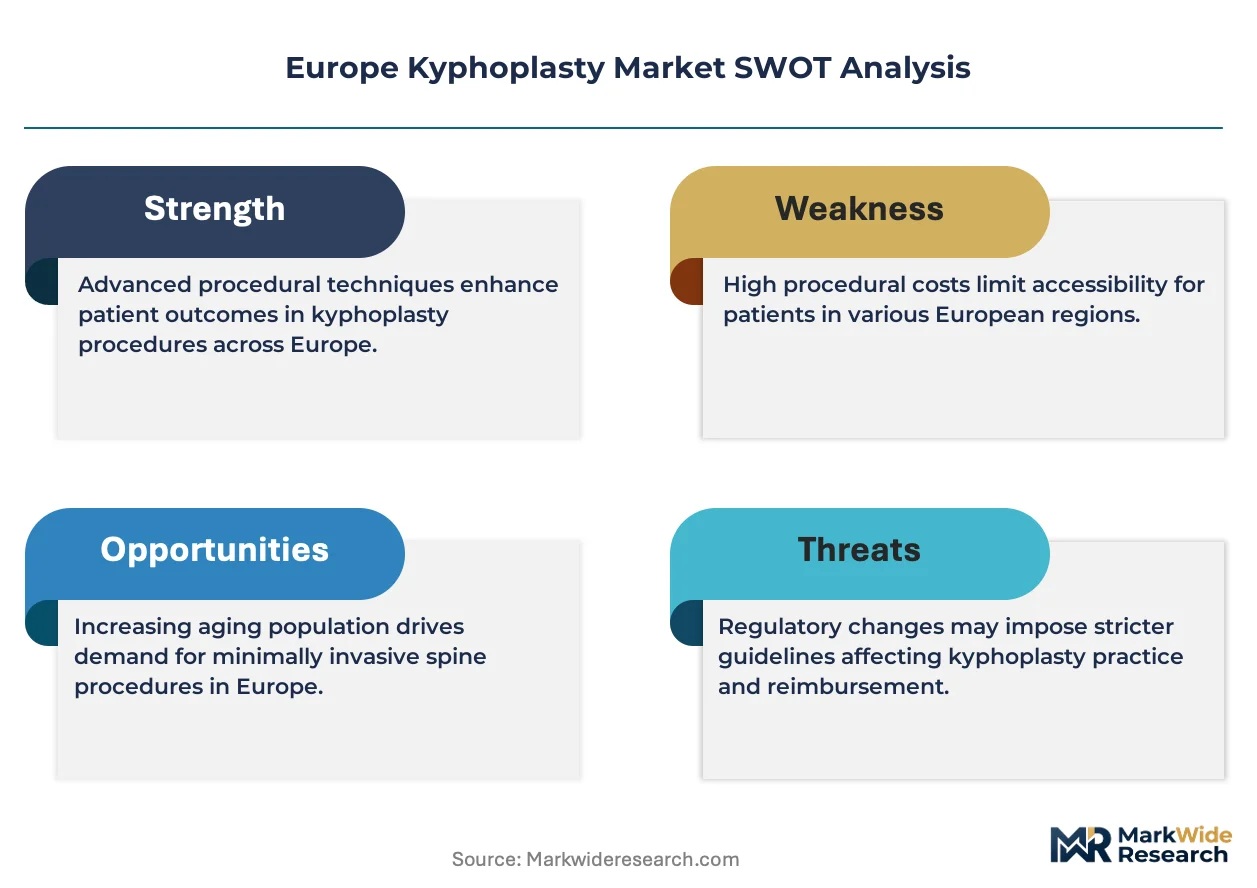
EMA oversight through the Medical Device Regulation mandates clinical performance data for Class III implantable devices, extending approval timelines for new bone cement formulations. CE marking requirements under MDR strengthen barriers for non-European manufacturers seeking European market access. The EU Green Deal pressures suppliers to reduce packaging waste and evaluate biodegradable alternatives in procedure kits. Stakeholders must monitor reimbursement parity between kyphoplasty and vertebroplasty across national health technology assessment frameworks.
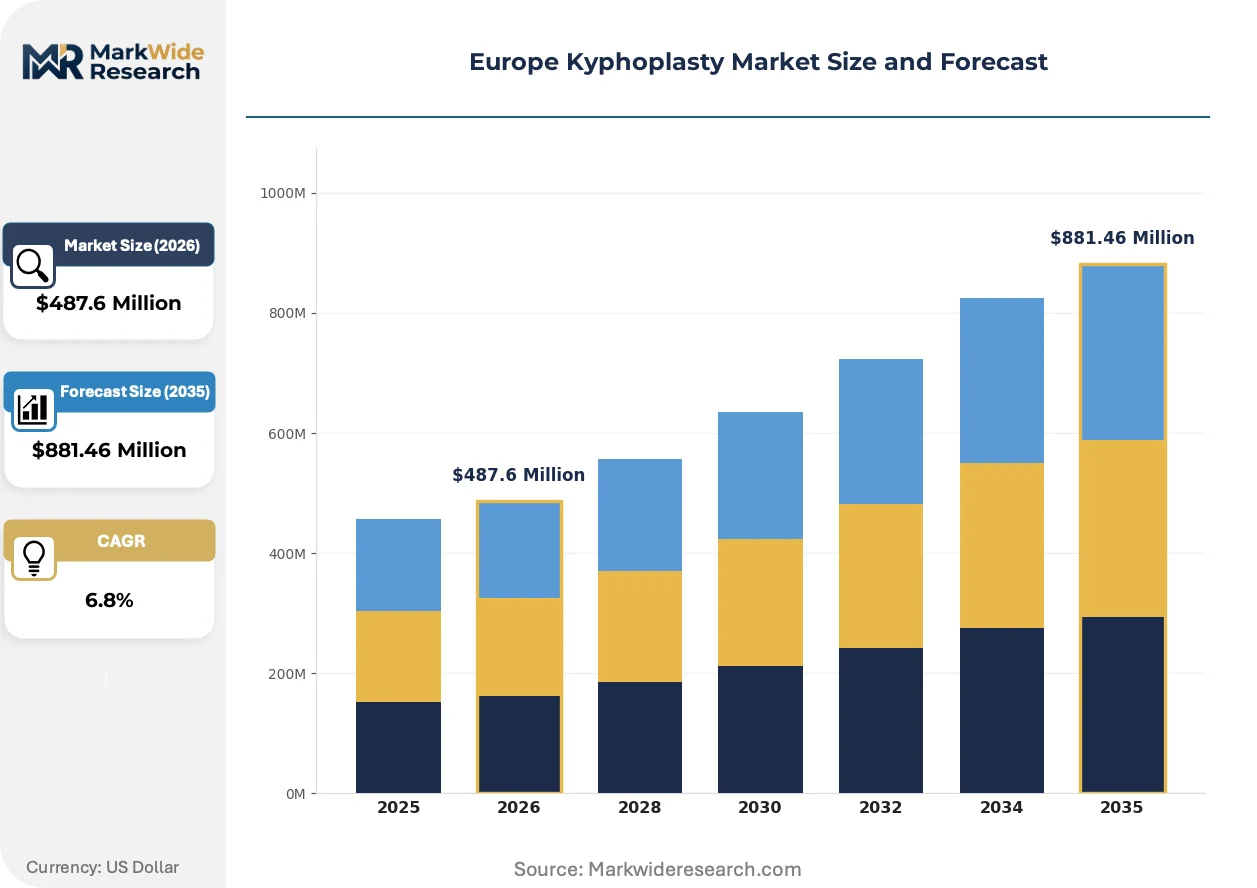
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines for bone cement formulations while hospital purchasing consortia in Germany and France consolidate procurement power around integrated spine portfolios.
Growth Catalysts
- Aging demographics:Western European populations over 65 drive surgical volumes for osteoporotic vertebral compression fractures, expanding the addressable patient base in France, Italy, and Spain.
- MDR clinical evidence pathways:The EU Medical Device Regulation's structured post-market surveillance requirements create competitive moats for manufacturers with established clinical data repositories.
- Ambulatory migration:Minimally invasive protocols enable same-day discharge procedures, unlocking capacity expansion in independent surgical centers across the Netherlands and Belgium.
Market Restraints
- Polymethylmethacrylate cost volatility:Petrochemical feedstock fluctuations squeeze margin structures for cement manufacturers dependent on methacrylate monomer supply chains.
- Single-source balloon catheter dependence:Concentrated supply of medical-grade silicone membranes for inflatable bone tamps creates vulnerability to regional production disruptions.
- Vertebroplasty substitution:Unaugmented cement injection procedures retain reimbursement parity in several national health technology assessment frameworks, limiting kyphoplasty conversion.
Strategic Opportunities
- Eastern European infrastructure buildout:Poland and Czech Republic hospital networks are installing dedicated spine suites with fluoroscopy capabilities previously concentrated in Western capitals.
- Tumor indication expansion:Pathological fracture applications from metastatic lesions command premium pricing and shorter sales cycles than degenerative indications.
- EU Green Deal compliance:Biodegradable packaging mandates for single-use procedure kits create first-mover positioning for suppliers with redesigned sterile barrier systems.
Industry Challenges
- Interventional radiology staffing:Shortages of physicians cross-trained in fluoroscopic navigation and cement injection techniques constrain procedure throughput in regional hospitals.
- MDR technical documentation:Extended clinical evaluation report preparation timelines delay CE marking renewals for legacy product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kyphoplasty Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Kyphoplasty, Vertebroplasty Cement, Surgical Instruments, Imaging Systems End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Procedure Type: Minimally Invasive, Open Surgical, Elective, Emergency Application: Osteoporotic Fractures, Tumor-Related Fractures, Traumatic Fractures, Others |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson (DePuy Synthes), MicroPort Scientific Corporation, Merit Medical Systems, Smith & Nephew, Globus Medical, Joimax GmbH, CareFusion Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kyphoplasty Market Trends and Innovations
Device manufacturers are reconfiguring product architectures around cement viscosity control, navigation integration, and sterile field efficiency to align with evolving procurement criteria and surgical workflow demands.
High-viscosity bone cement formulations are electrifying competitive positioning by reducing extravasation risk during vertebral body injection. German orthopedic cement producers are prioritizing these rheology-modified products in their R&D pipelines. Hospital purchasing committees are electrifying their supplier scorecards toward cement performance metrics over balloon system differentiation.
The EU Medical Device Regulation's Class III implantable device requirements are extending clinical evidence obligations for polymethylmethacrylate products. Manufacturers must generate post-market clinical follow-up data that was previously exempt under the Medical Devices Directive. Smaller cement suppliers without established PMCF infrastructure face disproportionate compliance burdens relative to diversified spine portfolios.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts encompassing balloons, cement, and delivery systems. Independent surgical centers in the Netherlands and Switzerland are displacing traditional distributor networks with direct manufacturer agreements. This channel compression concentrates volume with integrated suppliers capable of kit-level sterile packaging and consignment inventory management.
Europe Kyphoplasty Market Segmentation
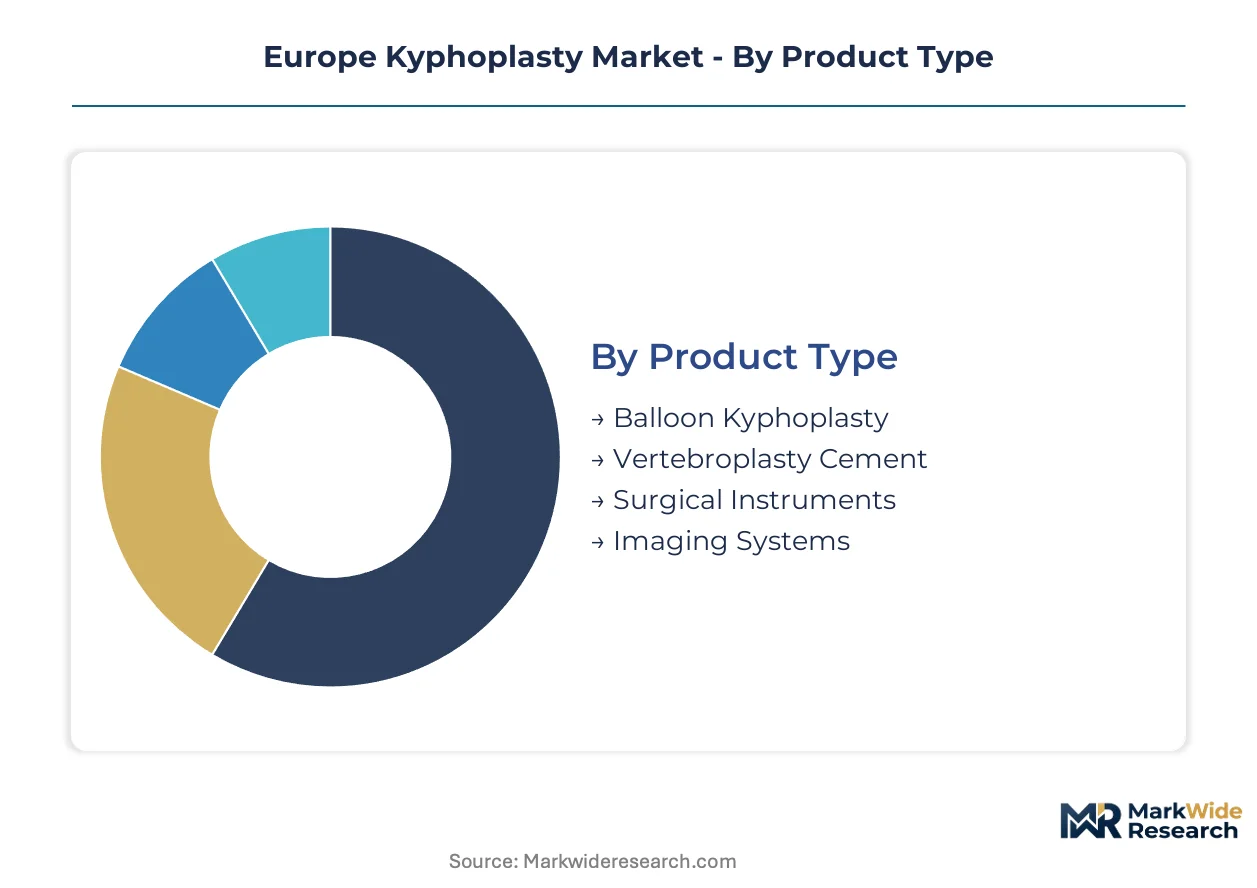
Kyphoplasty procurement patterns diverge sharply across European healthcare systems based on facility infrastructure, reimbursement frameworks, and physician training pathways. Product mix and channel selection reflect these structural variations in national spine care delivery models.
Product Type:
Upgrade cycles for balloon systems and cement formulations are compressing as MDR compliance costs force portfolio rationalization among mid-tier suppliers.
- Balloon Kyphoplasty:Inflatable bone tamp systems with controlled cavity creation command premium positioning in German and French hospital purchasing consortia. Demand concentrates in academic medical centers with dedicated spine suites where fluoroscopic navigation infrastructure supports complex thoracic and lumbar procedures.
- Vertebroplasty Cement:High-viscosity polymethylmethacrylate formulations with modified rheology properties are displacing conventional cements in Western European markets. French orthopedic cement manufacturers are prioritizing these products to meet EMA post-market surveillance requirements for reduced extravasation risk documentation.
- Surgical Instruments:Cement delivery cannulas and bone biopsy needles with integrated stylet designs serve secondary procurement tiers in Poland and Czech Republic expansion markets.
- Imaging Systems:Mobile C-arm fluoroscopy units with dedicated spine software packages anchor capital equipment budgets in Netherlands ambulatory surgical centers.
Volume placements concentrate in balloon kyphoplasty systems; the faster expansion belongs to high-viscosity cement formulations.
End User:
Channel economics vary substantially across facility types, with reimbursement differentials and procedure throughput requirements shaping vendor selection criteria.
- Hospitals:Tertiary care institutions in Germany, France, and Italy dominate procedure volumes through integrated spine service lines with 24-hour interventional radiology coverage. These facilities negotiate full-procedure contracts encompassing balloons, cement, and delivery systems under centralized procurement frameworks.
- Ambulatory Surgical Centers:Same-day discharge protocols are gaining reimbursement parity in Belgium and Switzerland, enabling volume capture by independent surgical centers with streamlined sterile processing capabilities. These channels are displacing traditional distributor relationships with direct manufacturer agreements for kit-level consignment inventory.
- Specialty Clinics:Orthopedic and pain management clinics in Spain and Portugal perform selective kyphoplasty procedures under referral arrangements with regional hospitals.
- Rehabilitation Centers:Post-acute facilities in Nordic countries manage non-surgical fracture stabilization patients, generating limited demand for revision procedure referrals.
Hospital networks retain the dominant revenue share; ambulatory surgical centers are climbing the fastest in annual procedure growth rates.
Procedure Type:
Minimally invasive protocol adoption is reshaping training pathways and capital allocation across European spine programs.
- Minimally Invasive:Percutaneous access techniques with local anesthesia and conscious sedation are standard in Western European markets, enabling same-day discharge and reduced intensive care utilization. Italian hospital networks are expanding these protocols to regional facilities previously limited to conservative management.
- Open Surgical:Direct vertebral body access with posterior instrumentation remains indicated for severe spinal deformity cases in academic referral centers.
- Elective:Scheduled procedures for stable osteoporotic compression fractures dominate volume planning in France and Germany.
- Emergency:Acute traumatic fracture stabilization with kyphoplasty augmentation captures limited share in Level I trauma centers.
Minimally invasive techniques absorb the majority of annual procedures; emergency applications show the steepest expansion trajectory from a low base.
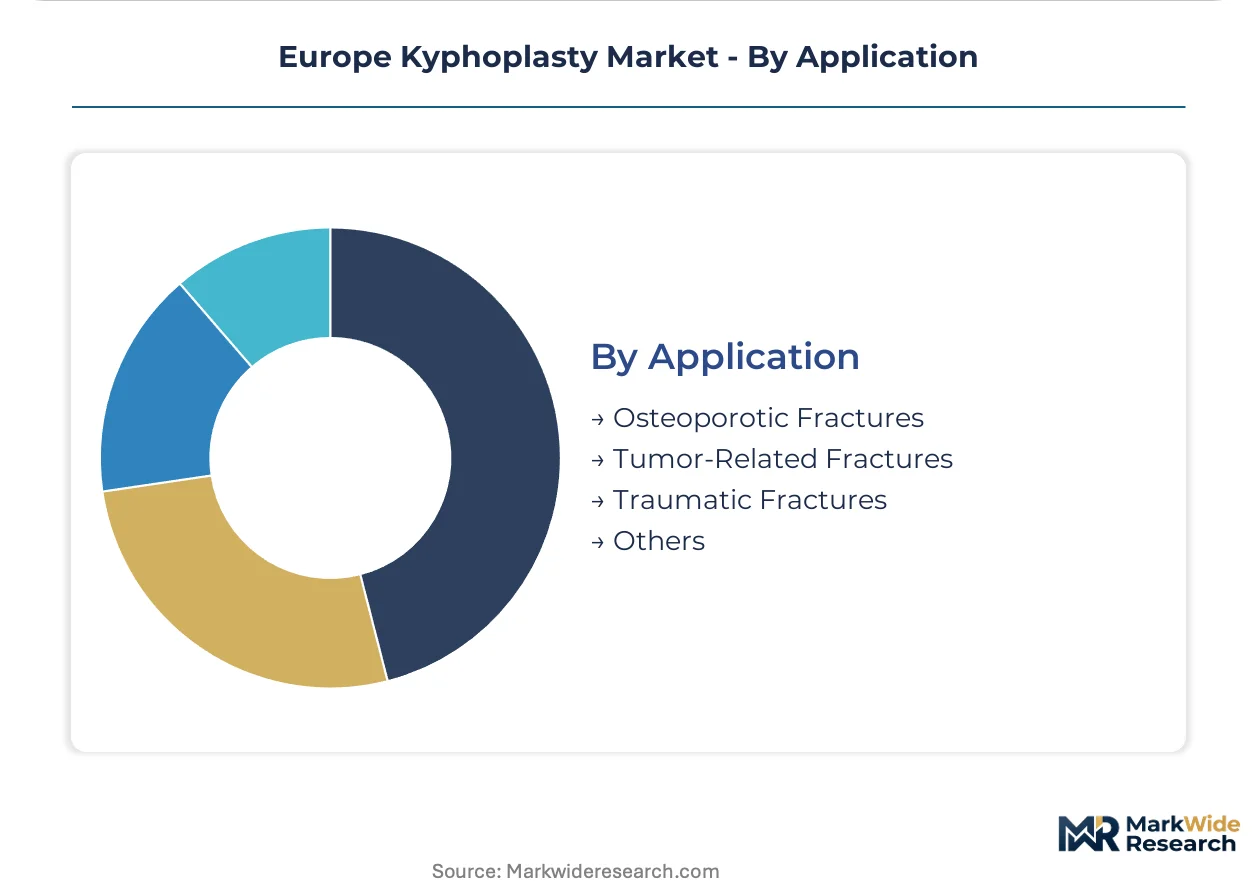
Application:
Indication mix determines margin profiles and sales cycle duration, with pathological fractures commanding distinct commercial approaches.
- Osteoporotic Fractures:Age-related vertebral compression fractures in patients over 65 constitute the mature revenue base across Western Europe. Spanish and Italian health technology assessment frameworks maintain reimbursement parity with vertebroplasty, constraining kyphoplasty conversion rates in these markets.
- Tumor-Related Fractures:Metastatic lesion stabilization in breast, prostate, and lung cancer patients generates premium pricing and shorter sales cycles through oncology-spine multidisciplinary programs. German university hospitals are expanding these indications through integrated tumor board protocols.
- Traumatic Fractures:High-energy vertebral body injuries in younger patient populations represent niche applications with specialized instrumentation requirements.
- Others:Osteonecrosis and benign tumor indications capture minimal volume in specialized referral pathways.
Osteoporotic fracture applications anchor installed base maintenance; tumor-related indications are gaining share fastest through oncology integration programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymethylmethacrylate monomer supply chains through the Port of Rotterdam anchor cement formulation logistics for vertebral augmentation procedures across Western Europe.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive balloon kyphoplasty volumes through integrated spine service lines. The MDR's post-market clinical follow-up requirements compress approval timelines for high-viscosity cement formulations. Berlin-based purchasing consortia negotiate full-procedure contracts that bundle balloons, cement, and delivery systems under single-source agreements.
France
Aging demographics in Île-de-France and Auvergne-Rhône-Alpes expand the addressable patient base for osteoporotic fracture interventions. ANSM oversight aligns with EMA Class III implantable device standards, extending clinical evidence obligations for bone cement products. Lyon hospital clusters are installing dedicated fluoroscopy suites to support minimally invasive vertebral augmentation protocols.
Italy
Lombardy and Emilia-Romagna health technology assessment frameworks maintain reimbursement parity between kyphoplasty and vertebroplasty, constraining conversion rates. Regional hospital networks are expanding percutaneous access capabilities to regional facilities previously limited to conservative management. Milan academic medical centers anchor spine surgery training pathways for interventional radiology cross-training.
Spain
Madrid and Catalonia orthopedic cement demand concentrates in tertiary institutions with 24-hour interventional radiology coverage. The EU Green Deal's packaging waste mandates pressure suppliers to redesign sterile barrier systems for single-use procedure kits. Barcelona hospital consortia are consolidating vendor relationships around kit-level consignment inventory management.
Netherlands
Same-day discharge protocols in Randstad ambulatory surgical centers unlock capacity expansion through streamlined sterile processing capabilities. Direct manufacturer agreements are displacing traditional distributor networks for balloon catheter and cement procurement. Eindhoven Region independent surgical centers capture faster volume growth than hospital channels through minimally invasive procedure standardization.
Europe Kyphoplasty Market Competitive Landscape
Global majors compete with regional champions across integrated spine portfolios and specialized balloon catheter systems. Market structure tilts toward consolidated procurement power as hospital purchasing consortia in Germany and France bundle full-procedure contracts. Three archetypes dominate: diversified spine portfolios with cement-to-instrument integration, specialized balloon catheter engineers, and high-viscosity cement formulators with German chemical heritage. Competitive moves concentrate on M&A for fluoroscopic navigation capabilities and strategic partnerships for MDR compliance infrastructure.
Within the diversified spine portfolio tier, Medtronic and Stryker Corporation occupy positions anchored by integrated product ecosystems. Joimax GmbH represents the specialized engineering archetype with German-origin endoscopic navigation platforms. These three entities exemplify the competitive tension between full-procedure bundling and component specialization that shapes vendor selection criteria across European hospital purchasing committees.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| MicroPort Scientific Corporation |
| Merit Medical Systems |
| Smith & Nephew |
| Globus Medical |
| Joimax GmbH |
| CareFusion Corporation |
| Others |
Pricing and Supply Chain Analysis
German hospital purchasing consortia bundling full-procedure contracts for balloon systems and cement formulations are forcing suppliers to consolidate kit-level production and absorb sterilization costs, compressing margin structures for mid-tier manufacturers without integrated sterile barrier capabilities.
Pricing Analysis
Warranty and technical service bundling separates premium balloon catheter suppliers from commodity cement competitors in European procurement scorecards. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier differentiation and after-sales clinical training inclusion. Pricing pressure stems from ANSM and BfArM post-market surveillance documentation requirements that inflate compliance overhead. Ambulatory surgical centers in Belgium and the Netherlands exhibit highest price sensitivity due to direct manufacturer negotiation leverage, while German university hospitals prioritize performance metrics over unit cost.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany operate hub-and-spoke patterns for just-in-time delivery to hospital consortia. Manufacturing concentrates in Germany, France, and Switzerland for balloon catheter systems, while polymethylmethacrylate monomer production draws from petrochemical complexes at the Port of Rotterdam and Antwerp. Supply chain risk centers on single-source medical-grade silicone membrane suppliers for inflatable bone tamps. Distribution runs through specialized medical device distributors with consignment inventory agreements at major hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over high-viscosity cement formulation capabilities and sterile kit assembly determines procurement contract eligibility. Players are pursuing backward integration into polymethylmethacrylate monomer supply to defend margin structures.
For Market Incumbents: Hedge against vertebroplasty substitution by locking multi-year full-procedure contracts with German purchasing consortia before MDR compliance costs fully propagate. Acquire specialized high-viscosity cement formulators in France to secure EMA clinical data repositories. Channel control through direct ambulatory surgical center agreements in the Netherlands displaces vulnerable distributor relationships. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry path around consolidated distributor networks. Target Poland and Czech Republic hospital networks installing first-generation fluoroscopy suites with simplified balloon catheter offerings. White-space exists in biodegradable sterile barrier systems for EU Green Deal compliance ahead of mandated packaging transitions. For Investors and Strategic Acquirers: The window for entry favors specialized high-viscosity cement formulators with established PMCF infrastructure and German chemical heritage. Long-term viability hinges on MDR compliance scalability rather than product differentiation alone. Monitor ANSM and BfArM approval velocity for new bone cement formulations as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class III implantable device compliance secures hospital procurement eligibility across EU member states. |
| Backward Integration into Monomer Supply | Captive polymethylmethacrylate production insulates margin structures from Rotterdam petrochemical price volatility. |
| Hospital System Partnership | Direct consignment agreements with Bavarian university networks displace traditional distributor intermediaries. |
| Biodegradable Packaging Transition | EU Green Deal-compliant sterile barrier redesign captures first-mover positioning in Spanish hospital consortia. |
| Reimbursement Strategy | Health technology assessment alignment with French ANSM standards accelerates tumor indication premium capture. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer surveys, and GPO contract database analysis underwrites the qualitative findings. Primary fieldwork engaged spine surgeons, interventional radiologists, hospital procurement managers, and EMA regulatory affairs specialists across Germany, France, Italy, and the Netherlands. Secondary validation drew from EMA MDR guidance documents, national health technology assessment frameworks, hospital capital equipment procurement records, and orthopedic cement manufacturer technical filings. Bottom-up procedure volume estimates triangulated against top-down market size reconstructions.
Comparable-period anchoring to historical kyphoplasty adoption curves in Western European markets calibrated the projection horizon. The analytical framework modeled segmentation across product type, end-user channel, procedure approach, and application indication. CAGRs derived from logistic diffusion curves for minimally invasive procedure penetration and linear extrapolation of MDR compliance cost impacts. Forecast inputs incorporated interventional radiology workforce growth projections and ambulatory surgical center reimbursement parity timelines.
The model holds under stable MDR implementation timelines and continued reimbursement parity evolution; deviation in EMA regulatory enforcement intensity or national health technology assessment reversals would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Kyphoscoliosis Treatment Market