
 Personalized Orthopaedic Implant Market | 2026-2036
Personalized Orthopaedic Implant Market Size, Share, and Industry Trends Forecast 2026-2036
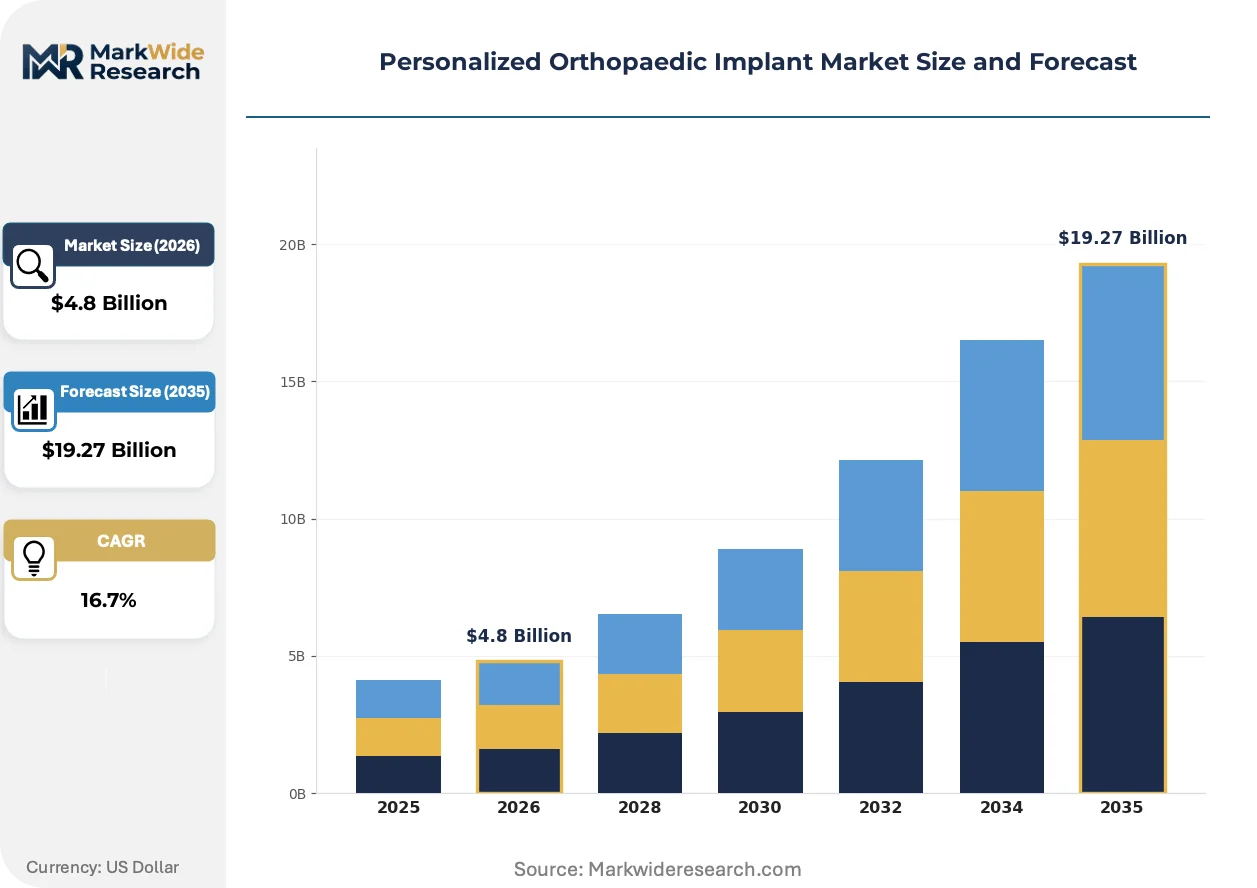
Personalized Orthopaedic Implant Market Outlook
Implant design-to-order workflows is reconfiguring how margin pools migrate from standardized inventory toward digital surgical planning and patient-specific production. Stryker Corporation leverages its additive manufacturing footprint to anchor high-value knee and hip reconstruction lines. Zimmer Biomet Holdings, Inc. sustains competitive density through CAD/CAM-integrated operating-room systems that lock in hospital preference. DePuy Synthes differentiates by controlling titanium powder supply chains and in-house electron-beam melting capacity.
Personalized orthopaedic implants are individually engineered prostheses fabricated from patient imaging data to match unique anatomical geometry, typically produced through additive manufacturing of titanium alloys or cobalt-chrome with porosity gradients engineered for osseointegration. Their primary commercial purpose is to reduce implant loosening, improve joint kinematics, and cut revision rates relative to off-the-shelf alternatives. Custom Implants command the dominant share of current revenue as hip and knee replacements absorb the bulk of hospital orthopaedic spending, while Additive Manufacturing represents the fastest-expanding technology segment as powder-bed fusion costs decline and build speeds improve. Joint Replacement applications concentrate the deepest margin pools due to procedure volume and bundled-payment incentives that reward lower complication rates.
FDA 510(k) and de novo pathways govern market entry in the United States, while EMA medical device regulation and MDR conformity requirements shape European commercialization timelines and clinical-evidence burdens. Japan's PMDA reviews patient-specific devices under accelerated assessment frameworks that demand domestic manufacturing partnerships. Stakeholders must monitor whether reimbursement authorities in Germany, France, and the United Kingdom will unbundle pre-operative planning from implant pricing, as this decision would redistribute profitability across the value chain.
Market Dynamics
Hospital procurement of patient-matched joint replacements is accelerating as health systems seek to reduce revision-surgery burden. FDA breakthrough device designation pathways and parallel EMA adaptive pathways are compressing time-to-market for additive-manufactured implants.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed review timelines for additive-manufactured implants are pulling patient-specific knee and hip replacements into earlier commercial availability. Orthopaedic surgeons in high-volume US hospital systems are gaining faster access to custom geometries.
- Electron-beam melting cost curves:Powder-bed fusion build speeds and titanium powder recyclability improvements are collapsing unit production economics for porous implant structures. Mid-sized health systems are now qualifying in-house production partnerships.
- Germany's bundled reimbursement:The G-DRG system rewards lower complication rates from patient-matched implants, concentrating hospital procurement preference toward pre-operative planning software bundled with custom production.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V powder production clusters among a handful of plasma-atomization facilities in the United States and Germany, creating input cost volatility when aerospace demand spikes.
- EMA MDR clinical-evidence burdens:Patient-specific implants face heightened post-market surveillance requirements and notified-body bottlenecks that extend European commercialization timelines relative to standardized alternatives.
- Off-the-shelf implant substitution:Modular revision systems with adjustable offsets and sizes capture price-sensitive cases where CT-to-implant workflows face insurance pre-authorization friction.
Strategic Opportunities
- Japan's PMDA accelerated assessment:Domestic manufacturing partnerships unlock fast-track review for patient-specific devices, creating first-mover advantage for hospitals in Tokyo and Osaka clusters.
- Software-hardware convergence:CAD/CAM-integrated operating-room systems are merging pre-operative planning with real-time surgical navigation, opening margin pools beyond the physical implant.
- Shoulder and ankle expansion:Complex revision cases in upper extremity and foot-ankle reconstruction remain underpenetrated by patient-matched solutions relative to hip and knee saturation.
Industry Challenges
- Biomedical engineer scarcity:Health systems lack personnel trained in DICOM segmentation, implant design validation, and additive manufacturing parameter optimization for Class II/III devices.
- Legacy PACS integration:Hospital IT infrastructure requires costly middleware development to connect radiology archives with proprietary surgical planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Orthopaedic Implant Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Implants, Patient-Specific Instruments, Fixation Devices, Biomaterials End User: Hospitals, Orthopaedic Clinics, Rehabilitation Centers, Surgical Centers Technology: Additive Manufacturing, CAD/CAM Systems, 3D Printing, Computer-Aided Design Application: Joint Replacement, Sports Injuries, Trauma Cases, Spine Surgery |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes, Smith & Nephew Plc, Medtronic Plc, Exactech, Inc., NuVasive, Inc., Globus Medical, Inc., Arthrex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Orthopaedic Implant Market Strategic Shifts
Pre-operative planning software is virtualizing the traditional implant sizing workflow, collapsing the boundary between diagnostic imaging and production engineering. Three developments are concentrating competitive advantage in digital surgical ecosystems.
Generative design algorithms are virtualizing the manual CAD iteration process that previously required days of biomedical engineer labor. High-volume orthopaedic centers in the United States are deploying topology optimization to automatically generate porous lattice structures matched to patient bone density maps. This compression of design-cycle time is pulling margin from standardized implant distributors toward captive software platforms.
EMA's Medical Device Regulation is tightening post-market clinical follow-up requirements for patient-specific implants with permanent contact duration. Notified bodies in Germany and the Netherlands are demanding extended registry data that smaller manufacturers struggle to generate, consolidating commercial access among firms with established European vigilance infrastructure. Hip reconstruction applications face the steepest documentation burdens.
Hospital buying committees are unbundling surgical planning software licenses from implant purchase orders. German university hospitals pioneered this separation, forcing vendors to compete on standalone pre-operative workflow value rather than hardware bundling. The shift is visible in United States academic medical centers where procurement teams now evaluate software subscriptions through separate IT governance channels.
Personalized Orthopaedic Implant Market Segmentation
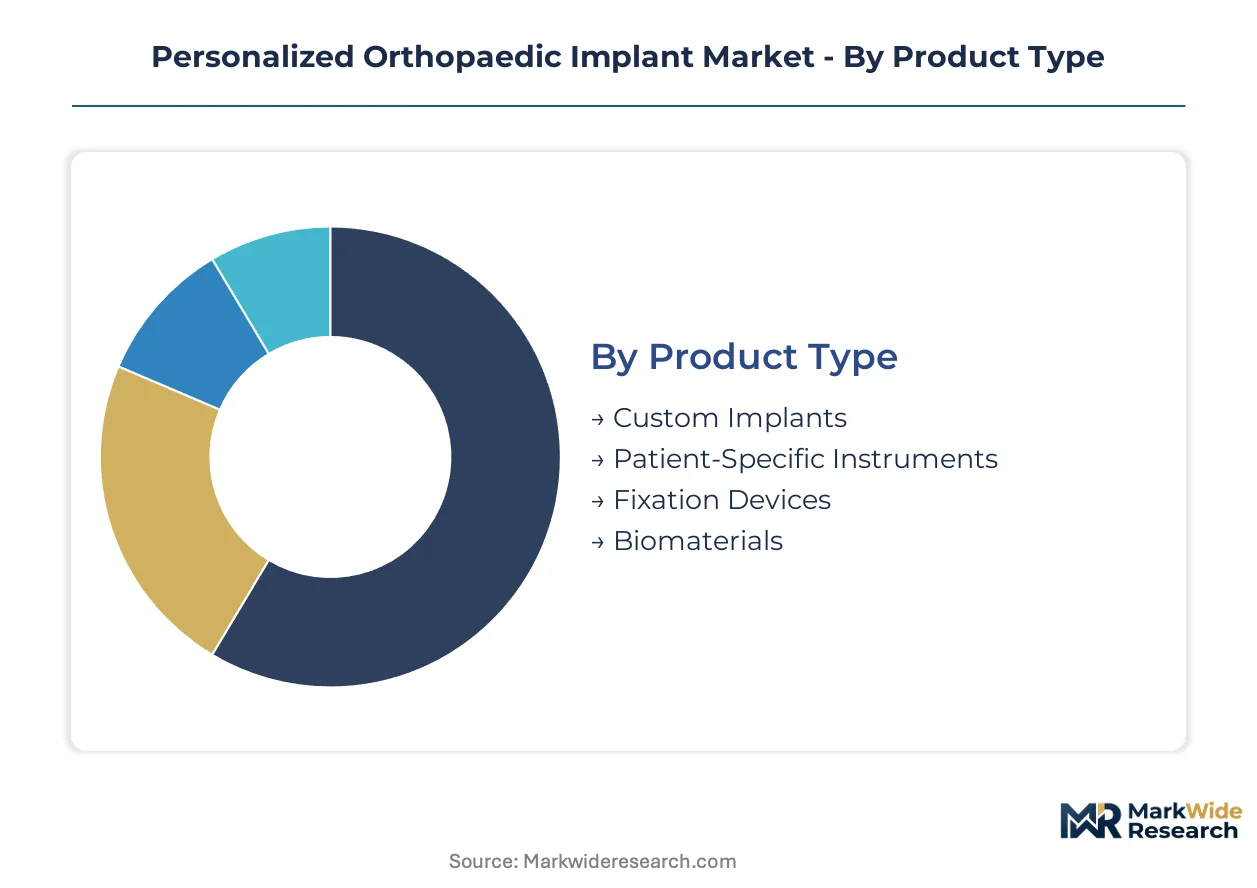
Segmentation in personalized orthopaedic implants reveals how margin pools migrate across hardware, software, and service layers. Distinct procurement patterns emerge between high-volume joint replacement centers and specialized trauma units.
Product Type:
After-sales-service intensity varies dramatically across product categories, with software-enabled segments demanding continuous calibration support and hardware lines requiring revision-surgery coverage.
- Custom Implants:Titanium alloy and cobalt-chrome prostheses engineered from patient CT/MRI data with porosity gradients for osseointegration. Hospital procurement in the United States and Germany concentrates here as bundled-payment incentives reward lower revision rates.
- Patient-Specific Instruments:Disposable cutting guides and alignment jigs manufactured to match individual anatomy. Demand clusters in academic medical centers where surgical training programs require reproducible outcomes for credentialing.
- Fixation Devices:Patient-matched plates and screws for complex fracture reconstruction.
- Biomaterials:Custom bone graft substitutes and resorbable scaffolds.
By volume, Custom Implants leads. By growth pace, Patient-Specific Instruments is ahead.
End User:
Customer concentration shapes pricing power, with integrated health systems extracting steeper discounts than fragmented clinic networks.
- Hospitals:High-volume arthroplasty centers with captive biomedical engineering teams and in-house 3D printing partnerships. Procurement in the United States and Japan favors bundled contracts spanning planning software through implant delivery.
- Orthopaedic Clinics:Specialized private practices with direct-to-manufacturer relationships. German outpatient clinics drive demand for rapid-turnaround custom instruments under DRG reimbursement frameworks.
- Rehabilitation Centers:Post-acute facilities requiring compatibility with implanted hardware.
- Surgical Centers:Ambulatory settings focused on outpatient joint replacement.
Hospitals dominate absolute spend. Surgical Centers show the steepest expansion trajectory.
Technology:
Capital intensity and technical personnel requirements create divergent margin structures across digital fabrication methods.
- Additive Manufacturing:Powder-bed fusion of titanium alloys with electron-beam or laser melting. Build speed improvements and powder recyclability gains are collapsing unit economics for porous structures in the United States.
- CAD/CAM Systems:Integrated design-to-manufacturing platforms merging DICOM segmentation with machining toolpaths. German university hospitals pioneered unbundled software procurement, forcing standalone subscription pricing.
- 3D Printing:Material extrusion and vat polymerization for surgical planning models.
- Computer-Aided Design:Legacy parametric modeling tools for implant geometry development.
Additive Manufacturing commands the deepest R&D investment. CAD/CAM Systems is climbing the fastest.
Application:
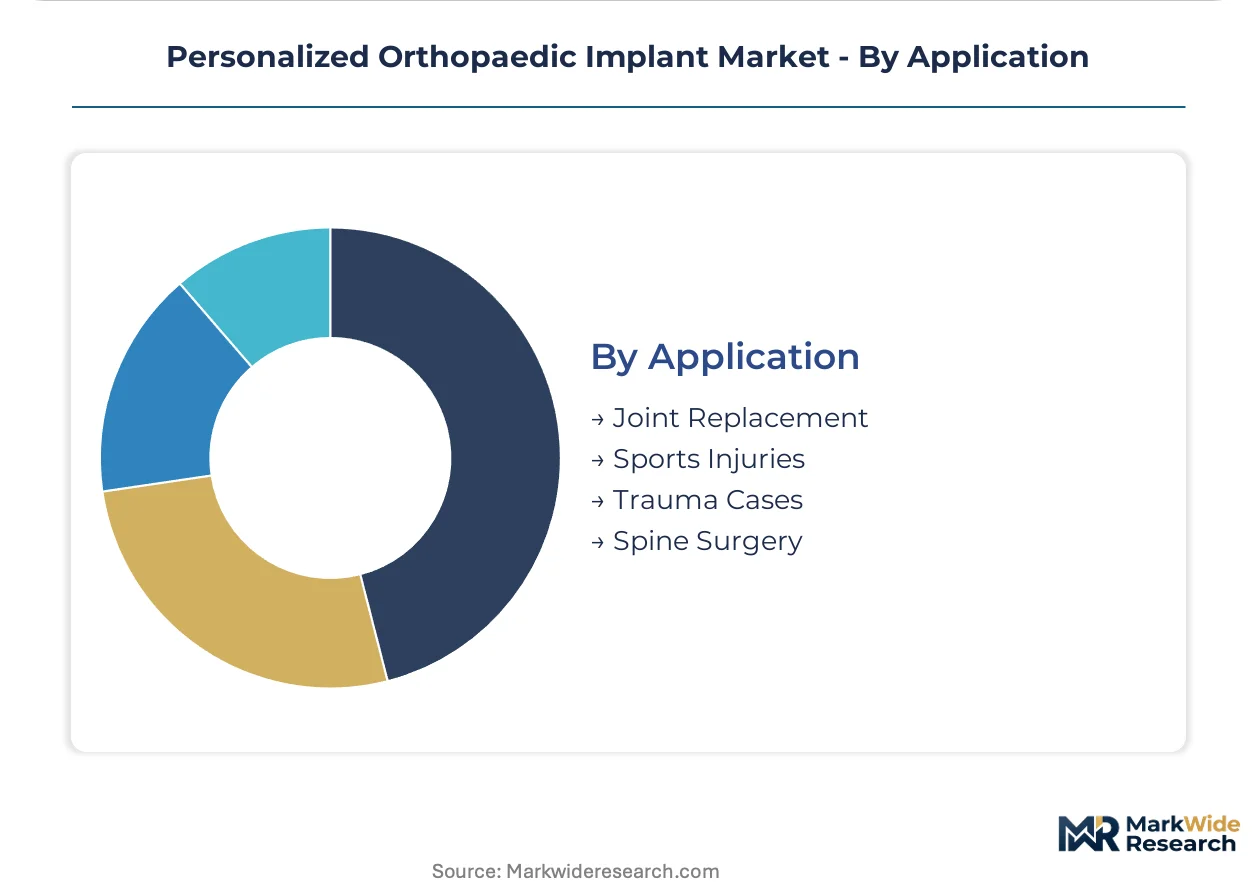
Procedure reimbursement rates and complication risk profiles determine willingness to absorb premium pricing for patient-matched solutions.
- Joint Replacement:Hip and knee arthroplasty with custom acetabular cups and femoral stems. United States health systems concentrate procurement here as Medicare bundled payments reward reduced readmission rates.
- Sports Injuries:Ligament reconstruction and osteochondral grafting in athlete populations. Tokyo and Osaka medical centers in Japan drive demand under PMDA accelerated assessment pathways.
- Trauma Cases:Complex fracture fixation with patient-matched plates.
- Spine Surgery:Custom interbody cages and pedicle screw trajectories.
Joint Replacement anchors revenue concentration. Sports Injuries is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States hospitals prioritize bundled-payment optimization through custom implants, while German procurement teams unbundle software from hardware. Japanese demand clusters around accelerated regulatory pathways requiring domestic manufacturing partnerships.
United States
Medicare bundled-payment incentives drive hospital procurement toward patient-matched knee and hip replacements with proven revision-rate reduction. FDA breakthrough device designation compresses review timelines for additive-manufactured implants. High-volume arthroplasty centers in Cleveland Clinic and Hospital for Special Surgery anchor demand concentration.
Germany
G-DRG reimbursement rewards lower complication rates, concentrating university hospital procurement toward pre-operative planning software. EMA MDR clinical-evidence burdens extend commercialization timelines for smaller manufacturers. The Munich-Düsseldorf corridor hosts the deepest concentration of notified-body infrastructure and titanium powder atomization capacity.
Japan
PMDA accelerated assessment frameworks demand domestic manufacturing partnerships for patient-specific device approval. Tokyo and Osaka medical clusters drive demand for custom sports-injury reconstruction under fast-track review. METI industrial policy supports local electron-beam melting facility qualification.
United Kingdom
NHS procurement frameworks evaluate patient-matched implants through cost-per-quality-adjusted-life-year metrics. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways. London teaching hospitals and Oxford-Cambridge biomedical clusters concentrate software-hardware integration trials.
Switzerland
Swissmedic streamlined review processes attract orthopedic technology development despite small domestic market volume. Basel-Zurich corridor hosts precision manufacturing subcontractors serving EU and US markets. Cantonal hospital procurement favors premium-tier custom instrumentation for complex revision cases.
Personalized Orthopaedic Implant Market Competitive Environment
Capability concentration sits with specialized additive manufacturing tiers; scale advantage sits with diversified orthopedic conglomerates. The vendor base stratifies across three layers: integrated health-technology giants with captive powder supply chains, mid-sized CAD/CAM platform specialists, and regional contract manufacturers serving single-hospital partnerships. Dominant competitive moves include backward integration into titanium powder atomization and software-hardware bundling to lock hospital procurement committees.
Within the integrated health-technology tier, Stryker Corporation, Zimmer Biomet Holdings, Inc., and DePuy Synthes exemplify divergent strategic positioning. Stryker anchors high-value reconstruction lines through additive manufacturing footprint control. Zimmer Biomet occupies a position defined by CAD/CAM-integrated operating-room systems that sustain hospital preference density. DePuy Synthes represents upstream supply-chain control through captive titanium powder sourcing and in-house electron-beam melting capacity. These three entities collectively illustrate how margin migration from standardized inventory toward digital surgical planning reshapes competitive architecture.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes |
| Smith & Nephew Plc |
| Medtronic Plc |
| Exactech, Inc. |
| NuVasive, Inc. |
| Globus Medical, Inc. |
| Arthrex, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's titanium powder logistics costs directly shape margin distribution between plasma-atomization suppliers in Germany and additive-manufacturing implant producers in the United States, concentrating pricing power among health systems with captive electron-beam melting partnerships while forcing spot-market buyers toward standardized implant alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement between high-volume US hospital systems and integrated manufacturers, locking in titanium alloy pricing across multi-year bundled-payment cycles. Price differentiation stems from FDA breakthrough designation tier and vertical integration depth, with captive powder supply commanding premium positioning. Cost compression in mid-tier custom instruments is intensifying because German university hospitals unbundled software licenses from hardware orders. Academic medical centers show highest price sensitivity due to separate IT governance budgets, while integrated health systems absorb premium pricing for revision-rate guarantees.
Supply Chain Analysis
Export controls on electron-beam melting equipment under US Commerce Department restrictions limit powder-bed fusion machine flows to Chinese and Russian end-users, tightening equipment availability for qualified biomedical manufacturers. Supply concentrates in the United States, Germany, and Japan for spherical Ti-6Al-4V powder, with raw material dependencies on plasma-atomization feedstock, electron-beam melting capacity, and DICOM segmentation software licenses. Single-source vulnerability concentrates in aerospace-competing titanium powder allocations during demand spikes. Distribution runs through hospital GPO contracts and direct manufacturer partnerships with high-volume arthroplasty centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA breakthrough pathways and EMA MDR vigilance infrastructure creates durable competitive shelter for incumbents with established clinical-evidence generation capabilities.
For Market Incumbents: Build data-network moats by integrating pre-operative planning software with hospital PACS infrastructure, locking in switching costs that resist modular revision system substitution. Deepen backward integration into titanium powder atomization to insulate margin from aerospace demand volatility. Prioritize EMA MDR post-market surveillance investment to exploit notified-body bottlenecks that exclude smaller competitors from European commercialization.
For New Entrants and Emerging Players: Establish a beachhead in shoulder and ankle reconstruction applications where patient-matched solutions remain underpenetrated relative to hip and knee saturation. Target Japanese domestic manufacturing partnerships under PMDA accelerated assessment frameworks to bypass entrenched US and German procurement relationships. Lead with CAD/CAM-integrated operating-room systems that merge surgical navigation with implant delivery, capturing standalone software subscription revenue before hardware qualification.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to monetize non-core additive manufacturing divisions lacking hospital-system distribution density. Long-term viability centers on software-hardware convergence plays with recurring revenue streams rather than transactional implant sales. Watch for unbundling decisions by German, French, and UK reimbursement authorities that would redistribute profitability across planning software versus implant production value chains.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compressed review timelines pull patient-specific knee replacements into earlier commercial availability for high-volume US hospital systems. |
| Domestic Manufacturing Partnership | PMDA accelerated assessment in Japan requires local electron-beam melting facility qualification, creating first-mover advantage in Tokyo-Osaka clusters. |
| Software-Hardware Bundling | CAD/CAM-integrated operating-room systems lock hospital procurement preference through merged pre-operative planning and real-time surgical navigation. |
| Titanium Powder Backward Integration | Captive plasma-atomization capacity insulates margin from aerospace demand spikes and input cost volatility in spherical Ti-6Al-4V supply. |
| EMA MDR Vigilance Infrastructure | Extended registry data generation capabilities consolidate commercial access among firms with established European post-market surveillance systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and de novo clearance databases, EMA MDR notified-body conformity assessments, hospital GPO contract filings, and CMS Medicare bundled-payment program documentation. Interviews with orthopaedic surgeons, hospital purchasing committee directors, biomedical engineers at high-volume arthroplasty centers, titanium powder procurement leads, and regulatory affairs specialists at additive-manufacturing device firms informed demand-side and supply-side calibration. Bottom-up segmentation modeling triangulated against top-down macro healthcare expenditure trends across the analysis window.
Forecast inputs span procedure volume trajectories, reimbursement framework evolution, powder-bed fusion cost curve assumptions, and regulatory pathway timeline compression factors. Segmentation dimensions include product type, end-user archetype, fabrication technology, and application area with regional regulatory cluster overlays. CAGRs derive from fitted growth curves applied to base-year sizing with cross-validation against analogous medical device adoption patterns. Industry-specific inputs incorporate electron-beam melting build speed improvements and titanium powder recyclability gains.
Sensitivities concentrate around reimbursement unbundling decisions in Germany, France, and the United Kingdom, FDA breakthrough designation pipeline velocity, and aerospace demand spillover into titanium powder allocation. Forecasts reflect documented assumptions regarding hospital procurement committee software evaluation governance shifts. Material shifts in EMA MDR notified-body capacity or PMDA domestic manufacturing partnership requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Hip Resurfacing Implants Market