
 Adult Orthopedic Insole Market | 2026-2036
Adult Orthopedic Insole Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Orthopedic Insole Market Insights
Diabetic patients is reorganizing demand within the adult orthopedic insole landscape, pulling manufacturers toward medically certified product lines. Superfeet leverages its biomechanical R&D infrastructure to serve athletic and clinical channels simultaneously. Bauerfeind anchors its position through German-engineered manufacturing scale and direct relationships with orthopedic specialists. Aetrex Worldwide differentiates via 3D scanning technology that bridges retail accessibility with clinical-grade customization.
Adult orthopedic insoles are engineered footbed devices constructed from layered composites of ethylene-vinyl acetate foam, thermoplastic resins, or viscoelastic gels, designed to redistribute plantar pressure, correct gait abnormalities, and mitigate musculoskeletal strain during ambulation. Custom insoles command premium positioning due to podiatrist-directed workflows and CAD-CAM fabrication requirements, while soft insoles address higher volume everyday use channels with faster inventory turns. Gel and thermoplastic materials capture growing preference in diabetic care applications where shear reduction and thermal stability prove clinically critical.
The US FDA classifies therapeutic insoles as Class I medical devices, mandating quality system registration for manufacturers claiming clinical efficacy. Germany's statutory health insurance framework, administered through umbrella associations of sickness funds, reimburses prescribed orthopedic insoles contingent upon podiatrist certification. ISO 13485 certification increasingly functions as a market access threshold for suppliers seeking entry into European and North American clinical procurement channels. Stakeholders must monitor evolving reimbursement coding structures and biomaterial biocompatibility standards as decisive variables for portfolio allocation.
Market Dynamics
German statutory health insurance reimbursement frameworks are compressing price points across European clinical procurement channels while elevating ISO 13485 certification from optional advantage to mandatory market access threshold.
Growth Catalysts
- Diabetes prevalence expansion:Aging demographics across OECD member states are swelling the addressable patient pool requiring pressure-redistributing insole systems for neuropathic foot care.
- US FDA Class I device pathways:Streamlined quality system registration for therapeutic claims is accelerating manufacturer entry into reimbursable clinical channels.
- Ethylene-vinyl acetate foam innovations:Advanced viscoelastic formulations with tunable durometer gradients are enabling single-insole solutions that previously required multi-layer custom fabrication.
Market Restraints
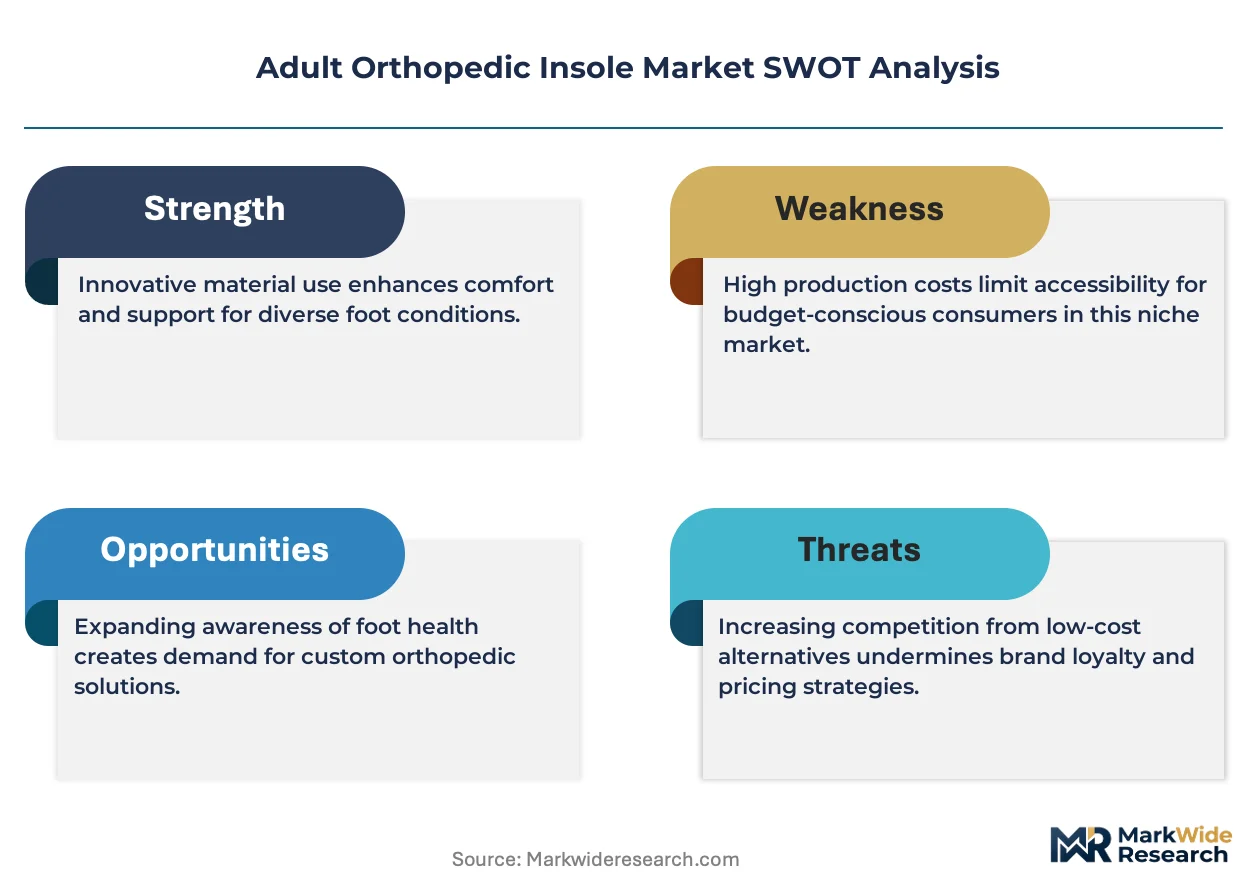
- Petrochemical feedstock volatility:Ethylene and vinyl acetate monomer price swings transmit directly to EVA foam input costs, compressing margin stability for mid-tier manufacturers.
- Podiatrist capacity constraints:Certified prescribers concentrate in urban agglomerations, creating geographic access barriers that slow patient onboarding in rural catchment areas.
- Over-the-counter orthotic substitution:Mass-market gel insoles priced at one-tenth clinical equivalents capture price-sensitive consumers before they enter professional care pathways.
Strategic Opportunities
- Remote 3D scanning penetration:Smartphone photogrammetry applications are collapsing the geographic radius for custom insole prescription, opening rural and exurban patient populations previously unreachable by podiatrist networks.
- Japanese METI silver economy frameworks:National longevity technology procurement incentives subsidize assistive device adoption among septuagenarian demographics with elevated orthopedic comorbidity rates.
- Athletic-clinical convergence:Running specialty retailers are installing pressure-mapping platforms that capture biomechanical data for both performance optimization and early pathology detection.
Industry Challenges
- CAD-CAM technician scarcity:Digital orthotic fabrication requires hybrid skill sets spanning podiatric anatomy, 3D modeling software, and CNC machining protocols that training pipelines have not yet scaled to meet.
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for novel gel formulations extend product development cycles by 18-24 months before European MDR technical documentation submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Orthopedic Insole Market |
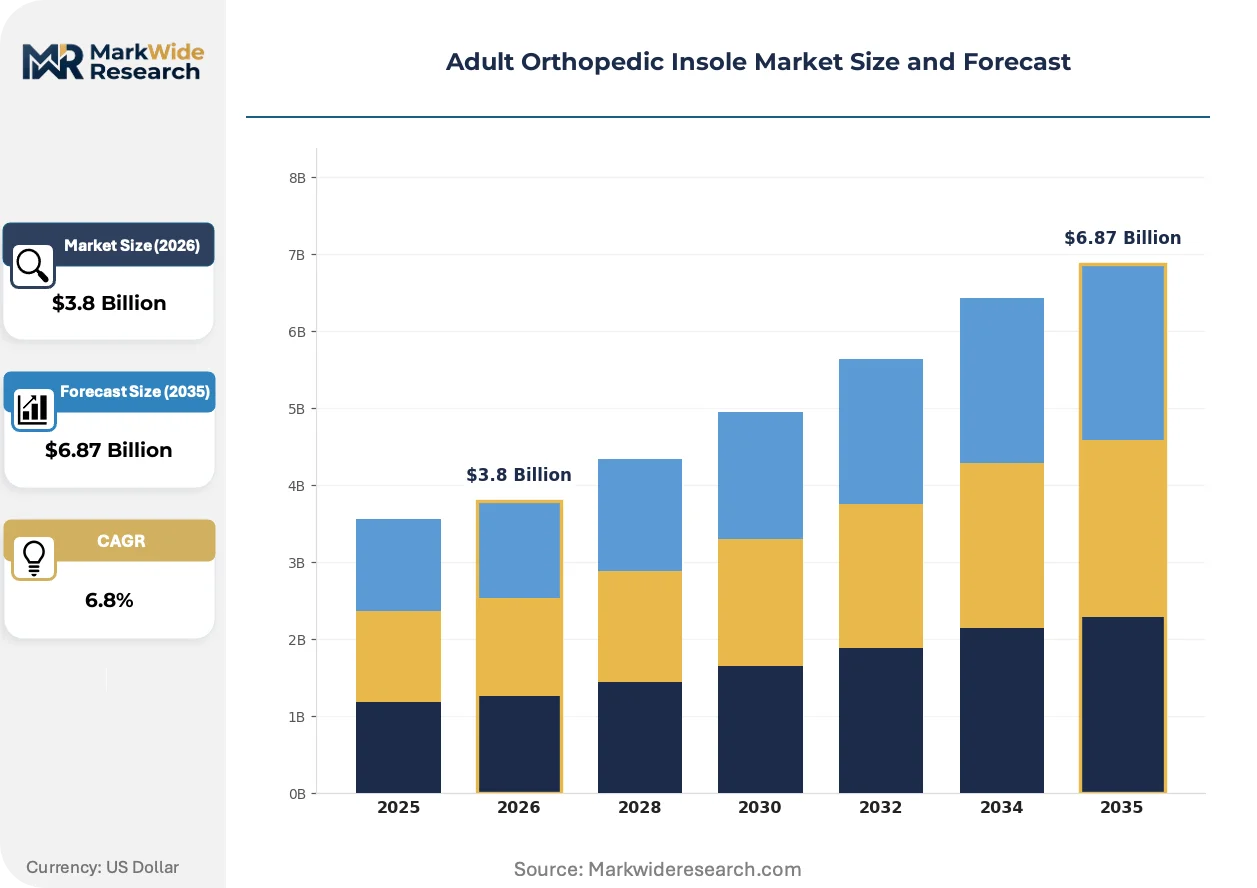
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Insoles, Rigid Insoles, Soft Insoles, Arch Supports Material: Foam, Gel, Thermoplastic, Leather End User: Athletes, Diabetic Patients, Seniors, General Population Application: Sports, Everyday Use, Therapeutic, Diabetic Care |
| Companies Covered | Dr. Scholl's, Superfeet, Aetrex Worldwide, PowerStep, Bauerfeind, Ottobock, Implus, Hanger Clinic, Sidas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Orthopedic Insole Market Trends and Innovations
Digital fabrication workflows are collapsing the traditional boundary between retail-accessible and clinically prescribed insole categories, forcing incumbent manufacturers to rebuild competency architectures around data capture rather than physical distribution.
Additive manufacturing with selective laser sintering of thermoplastic polyurethane is decomposing the economies of scale that historically protected centralized production facilities. Podiatry clinics in Australia and the Netherlands are deploying benchtop SLS units for same-day custom fabrication, compressing patient wait times from three weeks to four hours and eliminating freight costs from distributed supply chains.
EU MDR 2017/745 recast requirements for medical device technical documentation are elevating post-market surveillance obligations for Class I insole manufacturers claiming therapeutic efficacy. German notified bodies are demanding clinical evidence portfolios that exceed prior MEDDEV guidance, driving consolidation among suppliers lacking regulatory affairs infrastructure while creating procurement advantages for ISO 13485-certified competitors with established quality management systems.
Direct-to-consumer subscription models for replacement insole programs are disrupting traditional retail replenishment cycles. Diabetic patients in the United States are enrolling in quarterly delivery services that automate therapeutic insole replacement at Medicare-reimbursable intervals, bypassing brick-and-footwear channels while capturing longitudinal adherence data that manufacturers leverage for product development prioritization.
Adult Orthopedic Insole Market Segmentation
Segmentation in the adult orthopedic insole market determines reimbursement pathways, manufacturing workflows, and channel strategy. Material selection and end-user targeting separate premium clinical products from mass-market alternatives.
Product Type:
Margin pools concentrate in prescription-grade categories where podiatrist certification unlocks insurance reimbursement and pricing premiums.
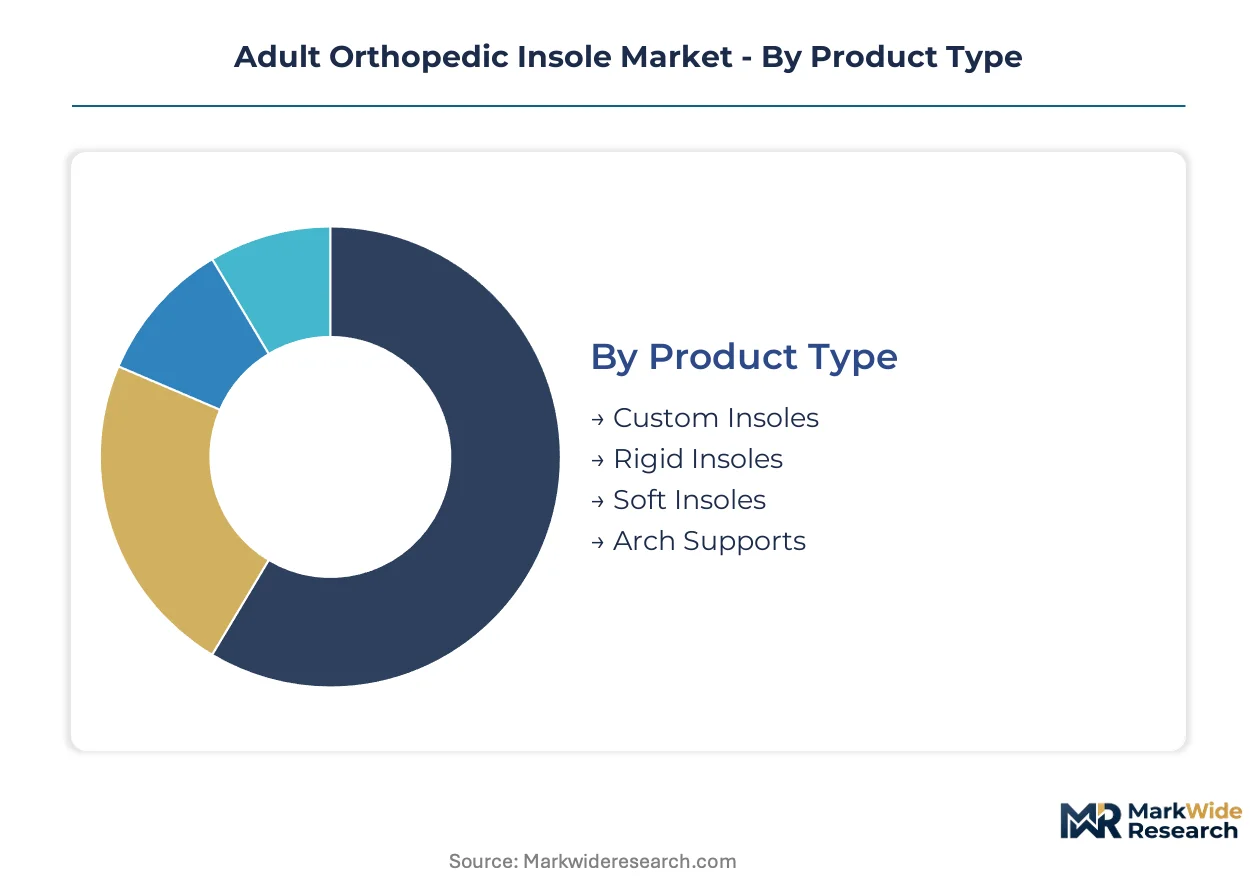
- Custom Insoles:CAD-CAM fabricated devices built from patient-specific plantar pressure maps and biomechanical gait analysis. Demand concentrates in Germany, where statutory health insurance reimbursement mandates podiatrist-directed workflows and elevates certified suppliers above retail competitors.
- Soft Insoles:Multi-layer viscoelastic foam constructions designed for everyday pressure redistribution and comfort enhancement. Athletes and retail consumers in the United States drive volume through running specialty channels, though price compression from over-the-counter alternatives constrains margin expansion.
- Rigid Insoles:Thermoplastic or carbon fiber shell devices engineered for motion control and structural correction.
- Arch Supports:Prefabricated semi-rigid inserts targeting generic foot arch elevation without full customization.
The dominant share belongs to Custom Insoles, while Soft Insoles is closing the gap fastest.
Material:
Volume leadership sits with cost-efficient inputs, though clinical-grade materials command superior unit economics in reimbursable channels.
- Foam:Ethylene-vinyl acetate and polyurethane formulations dominate production scale, with durometer-tunable grades enabling single-device solutions that previously required layered fabrication. Petrochemical feedstock volatility transmits directly to input cost structures.
- Gel:Viscoelastic polymer systems offering shear reduction and thermal stability critical for diabetic neuropathic foot care. Thermoplastic variants are gaining preference in EU MDR-regulated clinical procurement where biocompatibility documentation requirements favor established gel compounders with ISO 10993 testing histories.
- Thermoplastic:Heat-moldable resins enabling in-clinic customization without full CAD-CAM infrastructure.
- Leather:Traditional natural material retained in premium heritage positioning and specific dermatological sensitivity applications.
Foam retains volume leadership, though Gel is expanding most quickly in clinical segments.
End User:
Patient population targeting determines regulatory classification, distribution channel, and replacement cycle economics.
- Diabetic Patients:Neuropathic foot care requiring pressure-redistributing insoles with Medicare-reimbursable replacement intervals. Direct-to-consumer subscription models in the United States are automating quarterly delivery at reimbursable frequencies, capturing adherence data while bypassing traditional footwear retail.
- Athletes:Performance-oriented consumers seeking biomechanical optimization through pressure-mapping analysis. Running specialty retailers in Australia and the Netherlands are installing gait analysis platforms that bridge athletic performance and early pathology detection.
- Seniors:Aging demographics with elevated orthopedic comorbidity rates, particularly responsive to Japanese METI silver economy procurement subsidies.
- General Population:Undifferentiated mass-market consumers purchasing through pharmacy and big-box retail channels.
Diabetic Patients commands the dominant revenue pool, while Seniors is gaining share fastest on demographic tailwinds.
Application:
Use-case positioning separates discretionary retail purchases from medically necessary devices with insurance coverage.
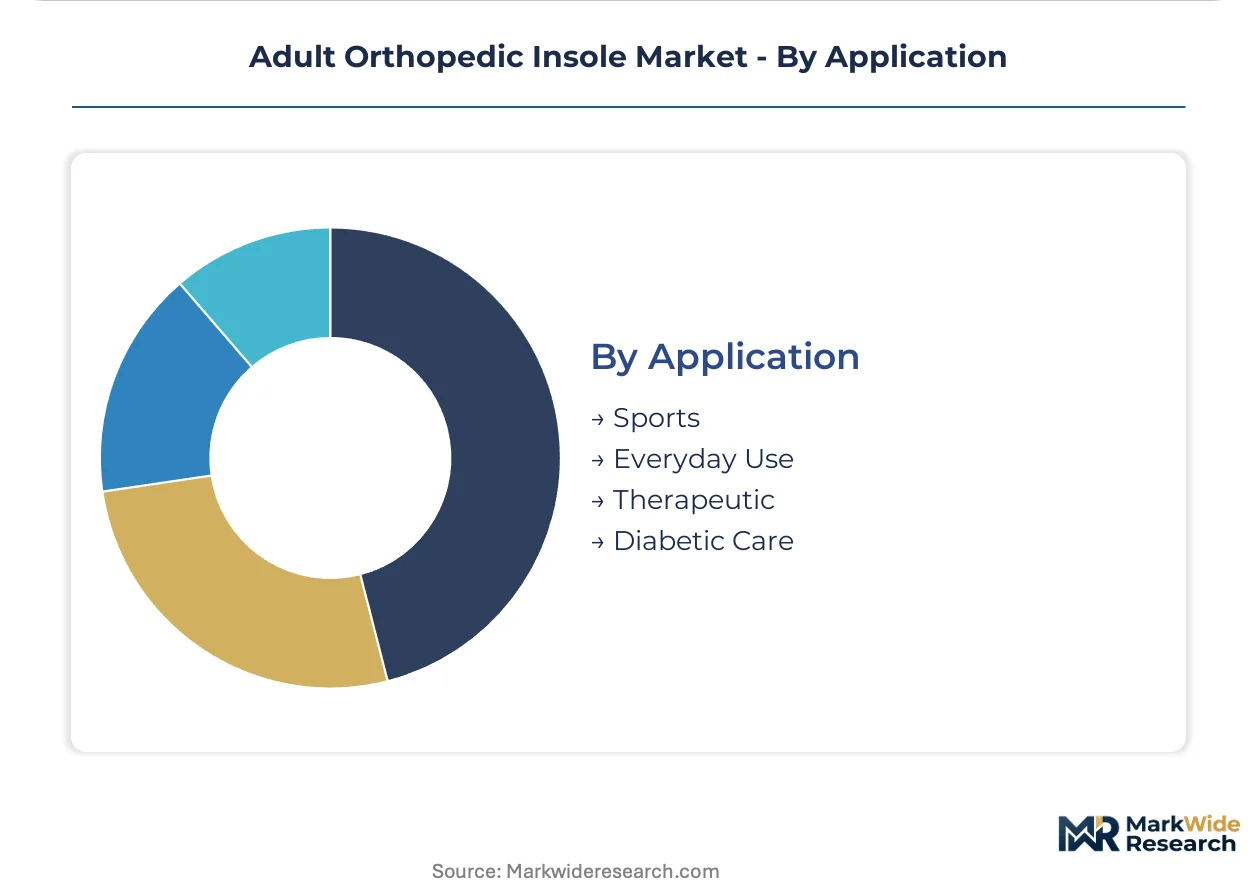
- Therapeutic:Clinically prescribed devices for diagnosed musculoskeletal conditions, requiring FDA Class I registration or EU MDR technical documentation. ISO 13485 certification functions as a mandatory market access threshold for suppliers seeking entry into European and North American clinical procurement.
- Diabetic Care:Specialized pressure-redistribution systems for neuropathic foot ulcer prevention. US FDA quality system registration and German sickness fund reimbursement coding create dual compliance requirements for manufacturers serving transatlantic markets.
- Sports:Performance enhancement and injury prevention targeting athletic demographics without clinical prescription requirements.
- Everyday Use:Comfort-oriented general wellness positioning without therapeutic claims or regulatory oversight.
Therapeutic holds the dominant position, while Diabetic Care is climbing the fastest on prevalence expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetic patient concentrations and statutory reimbursement frameworks are concentrating orthopedic insole procurement in Germany and the United States, while aging demographics in Japan and Australia are accelerating assistive device adoption through targeted government programs.
Germany
Statutory health insurance reimbursement through sickness fund associations mandates podiatrist certification for prescribed insoles, compressing price points while elevating ISO 13485 certification to mandatory status. The EU MDR 2017/745 recast demands clinical evidence portfolios exceeding prior MEDDEV guidance. Manufacturing clusters concentrate in North Rhine-Westphalia and Bavaria, where orthopedic specialists maintain direct supplier relationships with certified fabricators.
United States
Medicare-reimbursable replacement intervals for diabetic neuropathic foot care are automating quarterly delivery through direct-to-consumer subscription models. The FDA classifies therapeutic insoles as Class I medical devices requiring quality system registration for clinical efficacy claims. Boston and Minneapolis-St. Paul host dense networks of podiatry clinics integrating pressure-mapping platforms with CAD-CAM fabrication workflows.
Japan
METI silver economy procurement frameworks subsidize assistive device adoption among septuagenarian populations with elevated orthopedic comorbidity rates. National longevity technology incentives reduce out-of-pocket costs for pressure-redistributing insoles. Industrial activity clusters in the Kanto region around Tokyo and the Kansai region around Osaka, where medical device distributors maintain established relationships with orthopedic specialists.
Australia
TGA regulatory pathways align with ISO 13485 certification requirements for clinical-grade insole procurement through podiatry networks. Remote and rural patient access barriers are driving smartphone photogrammetry adoption for custom prescription capture. Melbourne and Sydney podiatry clinics are deploying benchtop selective laser sintering units for same-day custom fabrication, compressing patient wait times from weeks to hours.
Netherlands
Dutch statutory health insurance frameworks reimburse prescribed orthopedic insoles contingent upon podiatrist-directed workflows similar to German structures. Running specialty retailers in Amsterdam and Rotterdam are installing pressure-mapping platforms that bridge athletic performance optimization with early pathology detection. Digital fabrication adoption is accelerating among independent podiatry practices seeking to eliminate freight costs from distributed supply chains.
Adult Orthopedic Insole Market Competitive Landscape
Player mix skews toward European-engineered medical device specialists and North American consumer-accessible brands with clinical channel penetration. The market exhibits tiered structure with premium custom fabricators, mid-tier soft insole manufacturers, and mass-market gel product suppliers competing across distinct reimbursement and retail channels. Strategic archetypes include ISO 13485-certified clinical suppliers, direct-to-consumer subscription operators, and athletic-retail hybrid platforms. Dominant competitive moves center on CAD-CAM technology licensing partnerships and backward integration into captive 3D scanning software development.
Within the clinical-certified tier, Bauerfeind and Ottobock exemplify German-engineered manufacturing scale with established orthopedic specialist relationships. Superfeet occupies a position bridging athletic performance and clinical biomechanics through pressure-mapping R&D infrastructure. Aetrex Worldwide represents the technology-forward archetype with 3D scanning capabilities spanning retail accessibility and clinical-grade customization workflows.
| Leading Market Players |
|---|
| Dr. Scholl's |
| Superfeet |
| Aetrex Worldwide |
| PowerStep |
| Bauerfeind |
| Ottobock |
| Implus |
| Hanger Clinic |
| Sidas |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with German sickness fund associations lock in supply access for ISO 13485-certified fabricators while anchoring price visibility across statutory reimbursement cycles. These contractual structures concentrate procurement power among North Rhine-Westphalia and Bavaria manufacturing clusters, compressing margin flexibility for mid-tier competitors lacking direct orthopedic specialist relationships.
Pricing Analysis
Cost-plus contracts indexed to ethylene and vinyl acetate monomer benchmarks govern EVA foam input purchasing for mid-tier manufacturers. Three-tier pricing structure across premium custom, standard soft, and economy gel tiers separates podiatrist-certified reimbursement channels from mass-market retail. Pricing pressure stems from German statutory reimbursement compression, while diabetic patients through Medicare-subscription models prove least price-sensitive due to automated quarterly replacement coverage.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific petrochemical feedstock corridors face intermittent port congestion at Rotterdam and Hamburg, elevating working capital requirements for just-in-time foam compounders. Manufacturing concentrates in Germany, China, and the United States, drawing from ethylene-vinyl acetate resin, thermoplastic polyurethane pellets, and viscoelastic gel polymer feedstocks. Single-source vulnerability sits with specialized CAD-CAM software licensors, while distribution runs through podiatry clinic networks, running specialty retail, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to aging demographic expansion across OECD member states, where diabetes prevalence and orthopedic comorbidity rates drive replacement demand irrespective of discretionary spending fluctuations.
For Market Incumbents: Shield margin pools in German clinical channels through backward integration into captive 3D scanning software development, countering remote photogrammetry disruptors. Fortify ISO 13485 certification moats against EU MDR documentation demands that threaten smaller competitors with compliance failure.
For New Entrants and Emerging Players: Rural patient access gaps in Australian and Dutch exurban catchments offer white-space penetration where podiatrist network density collapses. Smartphone photogrammetry subscription services targeting diabetic patients with Medicare-reimbursable automation represent the most penetrable entry vector.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical-certified fabricators with established German sickness fund relationships and benchtop SLS manufacturing infrastructure. Watch Japanese METI silver economy subsidy expansion as the inflection signal for assistive device procurement acceleration across septuagenarian demographics.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks German statutory reimbursement channels and EU MDR market access. |
| Remote 3D Scanning Platform Development | Collapses geographic barriers for rural diabetic patient capture. |
| Benchtop SLS Manufacturing Deployment | Enables same-day custom fabrication, eliminating freight costs and wait times. |
| Direct-to-Consumer Subscription Launch | Automates Medicare-reimbursable replacement cycles while capturing adherence data. |
| Reimbursement Strategy Optimization | Aligns product coding with German sickness fund and US Medicare coverage pathways. |
Research Methodology
Cross-validation between podiatrist practice administrators and biomedical engineering directors anchors the qualitative findings on CAD-CAM workflow adoption. Primary interviews with orthopedic specialists, GPO contracts managers, and running specialty retail buyers combined with FDA 510(k) filings, German sickness fund reimbursement databases, and CMS Medicare claims data enable bottom-up and top-down triangulation.
Sensitivity analysis across material cost volatility scenarios and reimbursement policy shifts frames the analytical approach over the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user population, and application use-case, with CAGRs derived from patient demographic expansion rates and replacement cycle economics.
Forecasts assume regulatory continuity in FDA Class I device pathways and German statutory health insurance frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Smart Orthopedic Implants Market