
 Global Elbow Replacement Market | 2026-2036
Global Elbow Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elbow Replacement Market Foresight
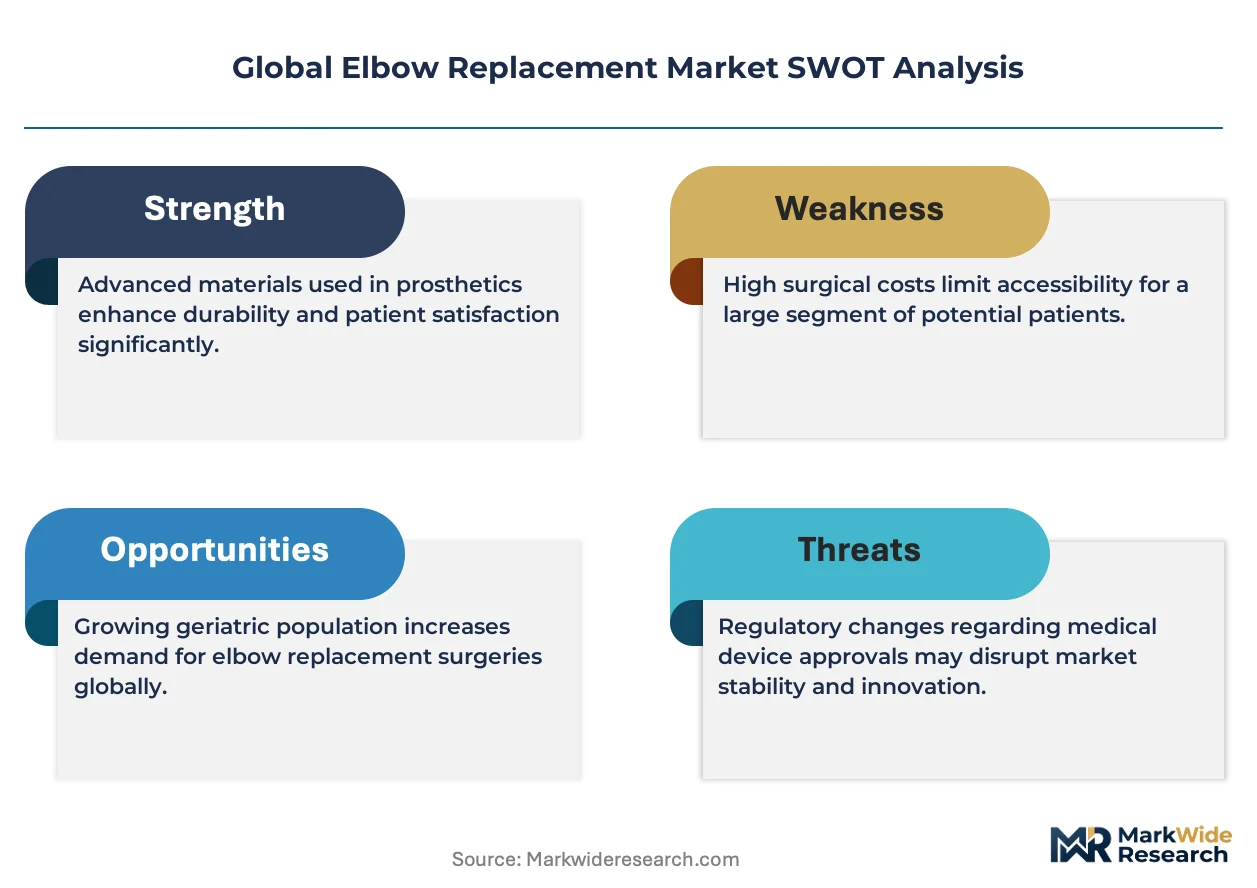
EU MDR is decoupling small orthopedic manufacturers from the European market by imposing clinical evidence requirements that favor well-capitalized incumbents. Zimmer Biomet leverages its notified body relationships to sustain CE mark continuity across its elbow portfolio. Stryker anchors its position through integrated surgical navigation systems that pair with implant placement. Smith & Nephew differentiates via its specialized upper extremity sales force that occupies the academic medical center channel.
Elbow replacement denotes the surgical implantation of artificial components to restore function and relieve pain in a damaged elbow joint, typically employing cobalt-chrome alloy humeral and ulnar components with ultra high molecular weight polyethylene bushings articulating through a hinge or unlinked mechanism. The procedure addresses end-stage joint destruction from trauma, inflammatory disease, or degenerative conditions where conservative management has failed. Linked prosthesis designs dominate revision cases where ligamentous instability precludes unlinked options, while cermet coatings represent the fastest-growing technology segment as surgeons seek enhanced fixation longevity in younger, more active patients. Porous coatings retain the largest installed base but face margin compression from commoditization.
FDA 510(k) clearances shape product development cycles for US market entry, while EMA's MDR transition extends timelines for European commercialization. Japan's PMDA imposes distinct clinical trial requirements that filter which multinational firms compete in its reimbursement-listed device catalog. Stakeholders must monitor how Japan's aging demographics and Germany's Diagnosis-Related Group reimbursement adjustments reshape volume allocation between primary and revision procedures.
Market Dynamics
The elbow replacement market pivots on a fundamental tension: EU MDR clinical evidence requirements are consolidating manufacturer power among well-capitalized incumbents while simultaneously compressing timelines for US market entry through streamlined FDA 510(k) pathways. This regulatory divergence is reshaping competitive positioning across geographies.
Growth Catalysts
- Germany's DRG reimbursement recalibration:The country's diagnosis-related group adjustments for arthroplasty procedures are expanding hospital program capacity for rheumatoid arthritis patients requiring joint reconstruction.
- Cermet coating technology:Surgeons in younger patient cohorts are demanding enhanced fixation longevity that porous-coated alternatives cannot reliably deliver, accelerating material substitution in primary implant selection.
- Japan's PMDA reimbursement-listed device catalog:The regulator's structured clinical trial requirements filter multinational competition, creating protected volume pools for qualified entrants in prefectures with concentrated osteoarthritis prevalence.
Market Restraints
- Cobalt-chrome alloy supply concentration:Primary smelting capacity for implant-grade alloys clusters in a limited supplier base, exposing manufacturers to input cost volatility and qualification timeline risk.
- EU MDR notified body bottleneck:The European Medical Device Regulation's extended clinical evidence requirements have decoupled small orthopedic manufacturers from CE mark continuity, favoring incumbents with established notified body relationships.
- Revision surgery complexity ceiling:Linked prosthesis designs required for ligamentous instability cases face technical limitations in bone stock preservation that constrain re-revision options.
Strategic Opportunities
- India's underpenetrated arthroplasty infrastructure:The country's emerging tertiary hospital networks present white space for upper extremity specialization programs currently concentrated in Western markets.
- Integrated surgical navigation convergence:Pairing implant placement with real-time navigation systems creates differentiation beyond commodity hardware, absorbing software and imaging technology into procedural workflows.
- Japan's aging prefecture demand rotation:Osteoarthritis prevalence in rural prefectures is driving revision surgery volumes faster than primary procedure growth, reallocating service line investment toward complex case management.
Industry Challenges
- Upper extremity fellowship pipeline constraints:Academic medical centers face scarcity of specialized surgeons trained in elbow arthroplasty techniques, limiting procedure volume expansion regardless of implant availability.
- EMA MDR transition timeline compression:Manufacturers must reconfigure quality management systems and clinical documentation simultaneously across portfolios, straining regulatory affairs capacity.
- Legacy unlinked implant integration friction:Hospitals maintaining mixed device inventories encounter sterilization protocol conflicts and instrument tray incompatibility that complicate operating room scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elbow Replacement Market |
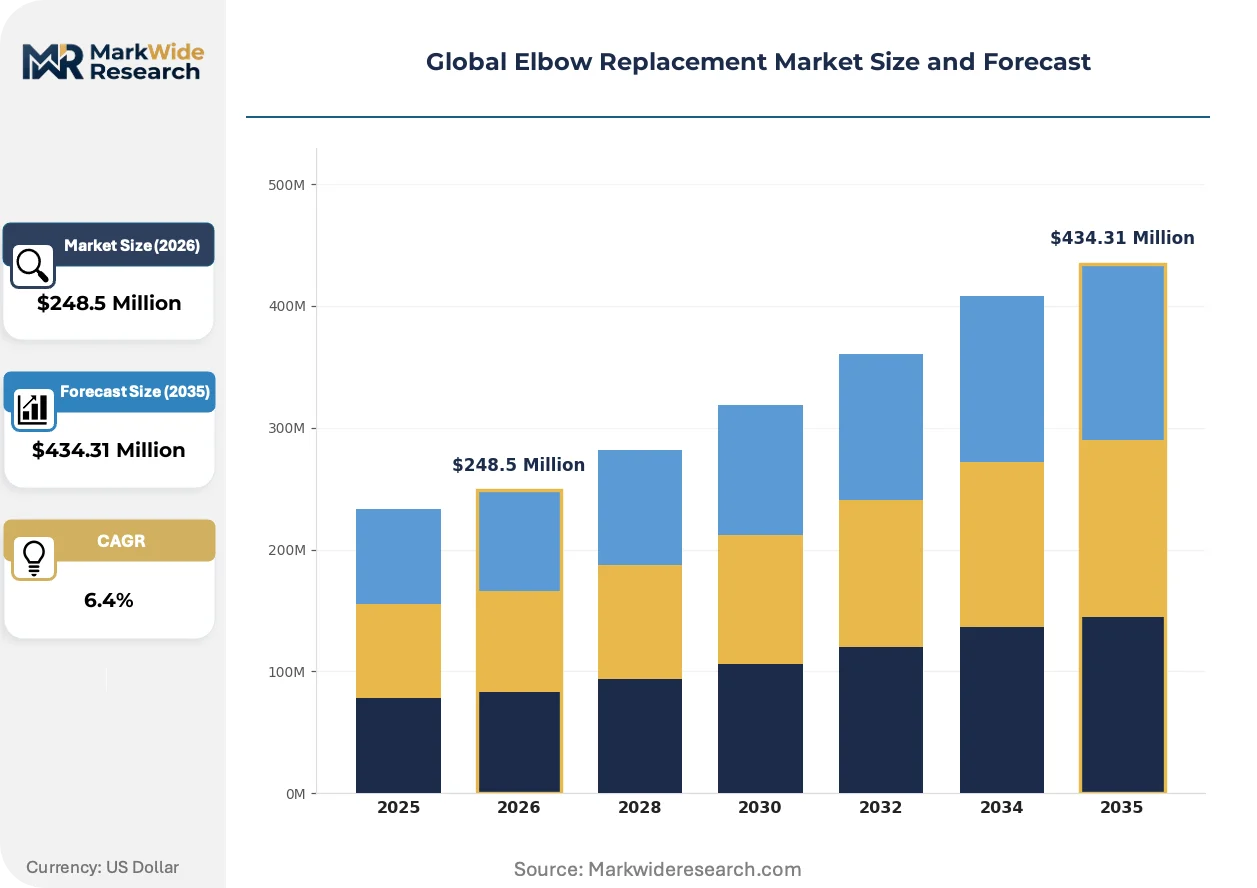
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $434.31 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unlinked Prosthesis, Linked Prosthesis, Semi-constrained Prosthesis, Resurfacing Elbow Implant Technology: Cermet Coatings, Hydroxyapatite Coatings, Titanium Alloy, Ultra High Molecular Weight Polyethylene, Porous Coatings Application: Osteoarthritis, Rheumatoid Arthritis, Post-Traumatic Arthritis, Elbow Fractures, Avascular Necrosis End User: Orthopedic Clinics, Specialized Surgical Centers, Ambulatory Surgery Centers, Rehabilitation Facilities |
| Companies Covered | Zimmer Biomet, Stryker, Smith & Nephew, Johnson & Johnson, Acumed, Arthrex, DJO Global, Wright Medical Group, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elbow Replacement Market Shifts & Advancements
Material science advances and regulatory pathway divergence are compressing traditional competitive moats while enabling new entrants to capture volume through specialized channel positioning. Three forces dominate this transformation.
Cermet coatings for elbow implant fixation are absorbing market attention from conventional porous titanium surfaces. Academic medical centers with high revision caseloads are adopting these materials fastest, prioritizing longevity metrics in younger patient populations. The technology is absorbing premium pricing power from commodity-coated alternatives as surgeons correlate surface engineering with reduced aseptic loosening rates.
REACH substance restrictions and EU MDR clinical evidence mandates are converging to extend European commercialization timelines. Manufacturers must now document biocompatibility across full supply chains while satisfying notified body expectations for implant survival data. Small and mid-cap firms without existing CE mark continuity are responding by deprioritizing EU market entry in favor of FDA 510(k) pathways and Asia-Pacific registrations.
Academic medical center procurement committees are consolidating vendor relationships around comprehensive upper extremity portfolios rather than single-product negotiations. The traditional distributor-led sales model faces displacement from direct manufacturer clinical specialist teams embedded in teaching hospitals. Germany and Japan exhibit this pattern most visibly, where hospital group purchasing aligns with surgeon training program affiliations.
Global Elbow Replacement Market Segmentation
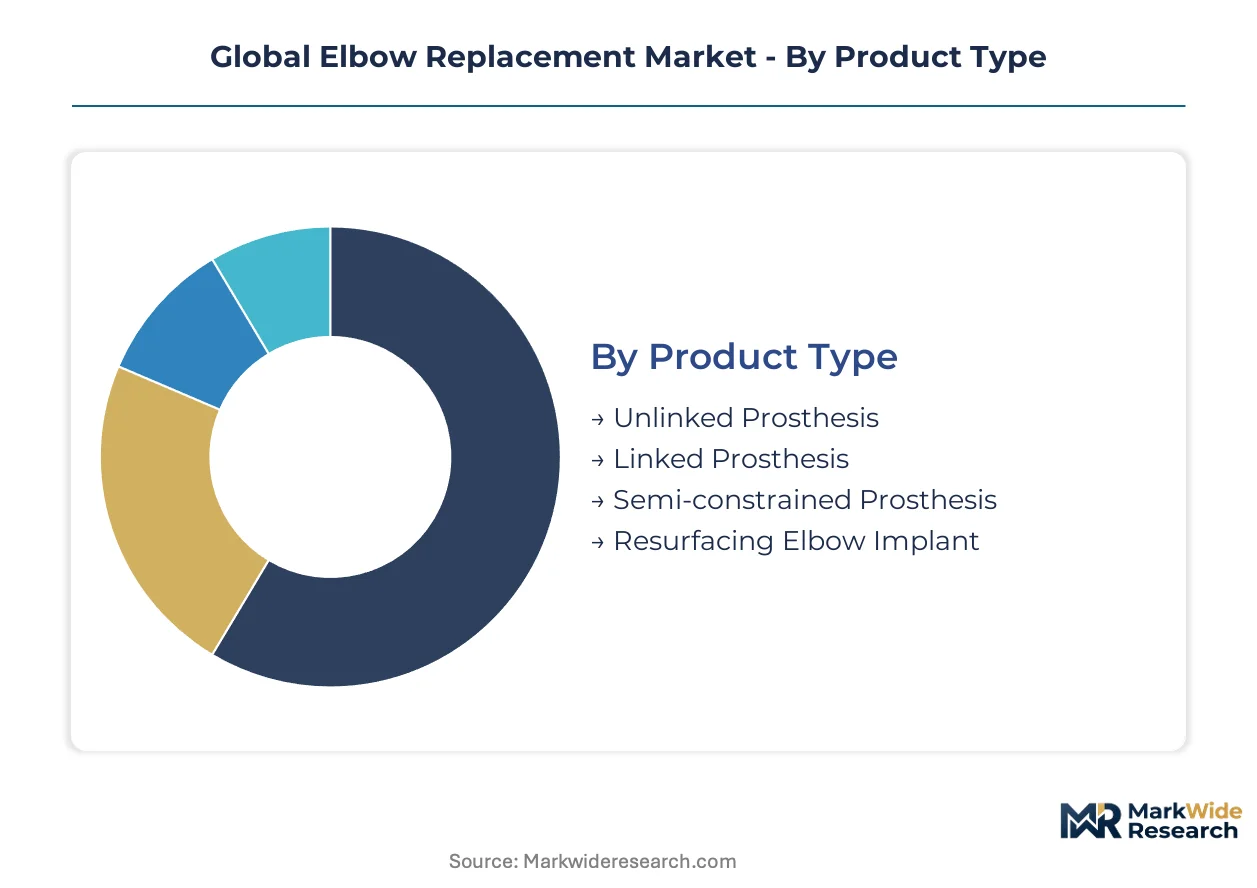
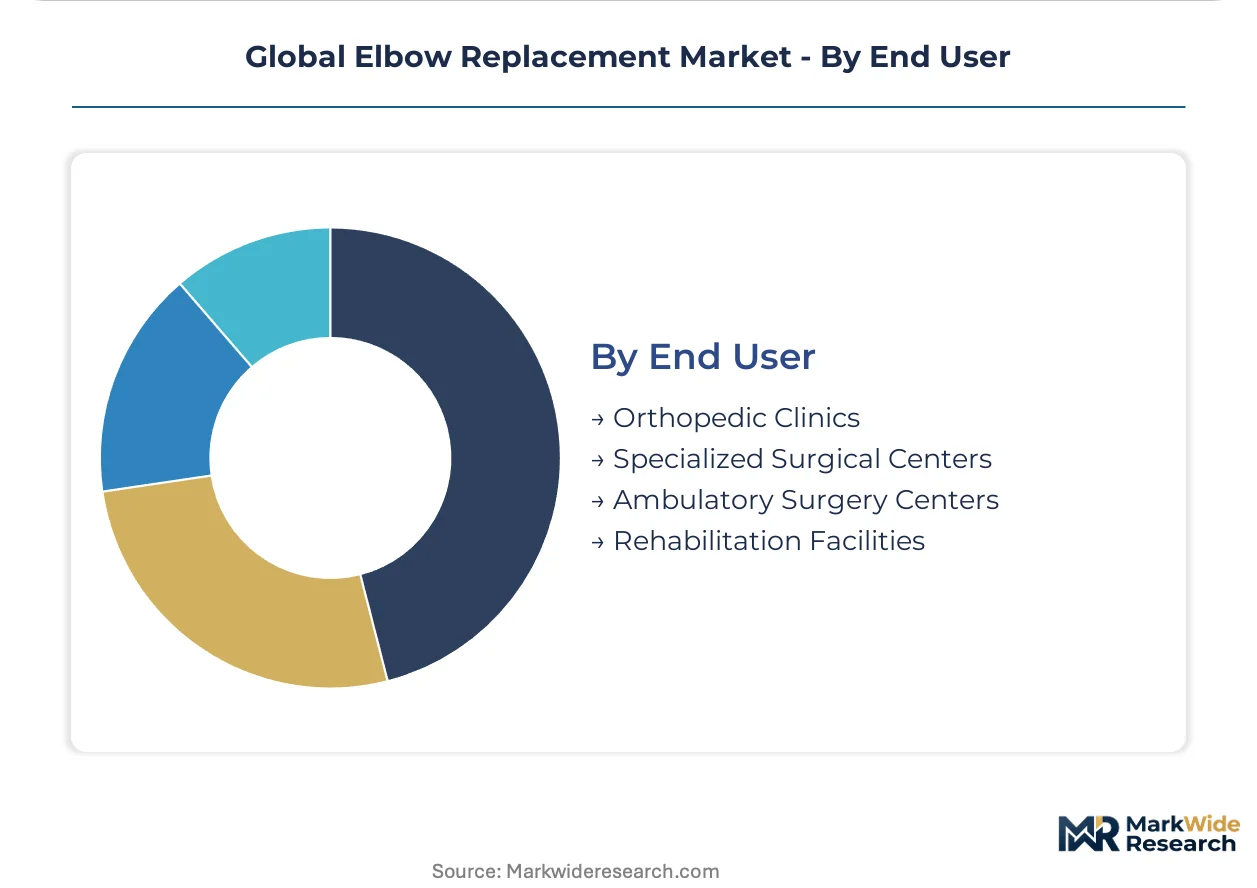
Elbow replacement segmentation reveals distinct procurement patterns across implant designs, surface technologies, and care settings. Manufacturers align R&D investment with procedure complexity tiers while distribution channels fragment between hospital systems and outpatient facilities.
Product Type:
Surgeon training background and case complexity drive selection between constraint mechanisms.
- Linked Prosthesis:Hinge mechanisms connect humeral and ulnar components through a fixed axis, delivering intrinsic stability for revision cases with ligamentous deficiency. Demand clusters in Germany's academic medical centers where rheumatoid arthritis patients present with bone loss and soft-tissue compromise.
- Unlinked Prosthesis:Separate components rely on native ligamentous integrity for articulation, preserving bone stock and enabling greater range of motion. Japanese prefectures with aging osteoarthritis populations favor this design for primary procedures where joint preservation matters.
- Semi-constrained Prosthesis:Intermediate stability through snap-fit or loosely linked designs bridges primary and revision applications.
- Resurfacing Elbow Implant:Capitellar and trochlear resurfacing preserves native bone in younger trauma patients with localized cartilage defects.
Linked prosthesis leads volumes today; unlinked designs are gaining share fastest in primary case expansion.
Technology:
Surface engineering differentiation determines fixation longevity and pricing power across patient age cohorts.
- Cermet Coatings:Ceramic-metal composites bond to cobalt-chrome substrates through plasma spraying, yielding superior osseointegration kinetics. Younger active patients in US metropolitan markets drive adoption as surgeons prioritize implant survival metrics over upfront cost.
- Porous Coatings:Sintered titanium beads create three-dimensional pore structures for biological fixation. This technology retains the largest installed base but faces margin compression from commoditization in standard primary cases.
- Hydroxyapatite Coatings:Calcium phosphate layers accelerate bone apposition through biomimetic chemistry.
- Titanium Alloy:Ti-6Al-4V substrates dominate structural components requiring strength-to-weight optimization.
- Ultra High Molecular Weight Polyethylene:Cross-linked UHMWPE bushings articulate against metallic surfaces in bearing couples.
Porous coatings anchor current revenue; cermet variants show steepest expansion trajectory among surface technologies.
Application:
Indication-specific reimbursement and patient demographics reshape volume allocation between primary and revision pathways.
- Rheumatoid Arthritis:Systemic inflammatory destruction produces bilateral symmetric joint involvement requiring staged reconstruction. Germany's DRG recalibration for arthroplasty has expanded hospital program capacity specifically for this patient pool.
- Osteoarthritis:Degenerative cartilage loss drives the largest absolute procedure volumes, concentrated in Japan's rural prefectures where aging demographics concentrate disease prevalence.
- Post-Traumatic Arthritis:Prior fracture malunion or intra-articular injury accelerates secondary joint degeneration.
- Elbow Fractures:Acute comminuted distal humerus or proximal ulna injuries in elderly patients convert to arthroplasty when internal fixation fails.
- Avascular Necrosis:Steroid-induced or traumatic osteonecrosis of the capitellum produces focal collapse requiring resurfacing or replacement.
Osteoarthritis generates highest absolute procedures; rheumatoid arthritis cases are climbing fastest on expanded access programs.
End User:
Site-of-service economics and surgeon concentration determine channel profitability and instrument investment requirements.
- Orthopedic Clinics:Physician-owned facilities capture high-margin primary cases with streamlined scheduling and dedicated implant consignment. These settings concentrate in US suburban markets with favorable outpatient procedure reimbursement.
- Specialized Surgical Centers:Hospital-affiliated units with dedicated upper extremity teams manage complex revision caseloads and fellowship training rotations. Japan and Germany exhibit highest penetration of this model.
- Ambulatory Surgery Centers:Freestanding facilities compete on cost efficiency for straightforward primary arthroplasty.
- Rehabilitation Facilities:Post-acute settings coordinate prosthetic fitting and functional recovery protocols.
Orthopedic clinics dominate primary case economics; specialized surgical centers capture premium revision margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic fellowship programs in Germany, Japan, and the United States anchor the global elbow replacement talent base, concentrating specialized surgical expertise in academic medical centers that drive procedure volume and implant innovation.
United States
FDA 510(k) clearance pathways compress product development cycles for incremental implant designs, accelerating market entry timelines relative to European alternatives. The agency's streamlined review absorbs preclinical data packages that European regulators now require in expanded clinical trials. Metropolitan hospital systems in the Northeast and Midwest concentrate revision caseloads where fellowship-trained surgeons manage complex ligamentous instability.
Germany
Diagnosis-related group reimbursement recalibration expands hospital program capacity specifically for rheumatoid arthritis patients requiring joint reconstruction. EU MDR notified body relationships determine CE mark continuity, favoring incumbent manufacturers with established regulatory infrastructure. The Rhine-Ruhr and Bavarian hospital networks anchor arthroplasty volume expansion through integrated upper extremity service lines.
Japan
PMDA reimbursement-listed device catalog requirements filter multinational competition, creating protected volume pools for qualified entrants. Aging demographics in rural prefectures concentrate osteoarthritis prevalence, driving revision surgery volumes faster than primary procedure growth. The Kansai region's academic medical centers specialize in unlinked prosthesis selection for joint preservation in elderly cohorts.
United Kingdom
NICE technology appraisal pathways determine implant reimbursement eligibility within the National Health Service procurement framework. Post-Brexit regulatory divergence from EU MDR timelines creates parallel compliance obligations for manufacturers maintaining dual market access. London and Manchester teaching hospitals coordinate specialized upper extremity fellowship rotations that concentrate surgical expertise.
Australia
TGA conformity assessment procedures align with EU MDR evidence standards while maintaining distinct procedural requirements for prosthesis inclusion on the Australian Register of Therapeutic Goods. Private hospital networks in New South Wales and Victoria capture premium primary arthroplasty volumes through dedicated orthopedic service lines. The country's aging population and sports trauma burden generate revision caseloads concentrated in metropolitan surgical centers.
Global Elbow Replacement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven portfolios absorb commodity volume while specialized entrants capture premium revision margins. The manufacturer base consolidates around three archetypes: integrated orthopedic conglomerates with comprehensive joint replacement portfolios, upper extremity specialists with concentrated sales force deployment, and navigation-technology hybrids pairing hardware with surgical software. Competitive positioning hardens through notified body relationship depth in Europe and integrated surgical system bundling in the United States.
Within the diversified conglomerate tier, Zimmer Biomet and Stryker exemplify scale-driven positioning that spans multiple joint reconstruction categories. Smith & Nephew occupies a specialist position through dedicated upper extremity commercial infrastructure. Johnson & Johnson's market presence anchors diversified medical device portfolio breadth. These manufacturers represent contrasting strategic postures: comprehensive joint replacement coverage versus focused anatomical specialization versus diversified healthcare conglomerate structure.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Smith & Nephew |
| Johnson & Johnson |
| Acumed |
| Arthrex |
| DJO Global |
| Wright Medical Group |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Captive smelting arrangements for implant-grade cobalt-chrome alloys anchor both supply security and premium pricing power for incumbent manufacturers. This backward integration into raw material qualification insulates established players from input volatility while enabling sustained margin capture in cermet-coated implant tiers.
Pricing Analysis
Bundled implant-plus-instrumentation packages dominate academic medical center procurement, while unbundled component sales persist in outpatient orthopedic clinics. Three-tier pricing structure across premium cermet-coated, standard porous-coated, and economy legacy designs reflects certification grade and surgeon training program affiliation. Pricing pressure stems from GPO consolidation in US hospital systems and DRG compression in Germany. Outpatient clinics exhibit highest price sensitivity; academic centers prioritize longevity metrics over upfront cost.
Supply Chain Analysis
Dual-sourcing requirements for cobalt-chrome alloy feedstock mandate multi-supplier qualification across German, Japanese, and US smelters. Raw material dependencies center on cobalt ore from the DRC, chromium from South Africa, and titanium sponge from Japan. Single-source vulnerability concentrates in implant-grade alloy qualification timelines. Distribution runs through manufacturer-direct clinical specialist teams for academic centers and distributor networks for community hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by surgeon demand rotation toward cermet-coated implants with enhanced fixation longevity in younger patient cohorts.
For Market Incumbents: Deploy notified body relationship depth as the primary lever. Deepen CE mark continuity investments ahead of EU MDR transition deadlines to exclude capital-constrained challengers. Anchor defensive positioning through integrated surgical navigation bundling that absorbs software capability into hardware procurement decisions. Threat substitution from navigation-technology hybrids demands preemptive platform integration. For New Entrants and Emerging Players: Digital channel routes through telesurgical training platforms offer lowest-friction entry. India's emerging tertiary hospital networks present the most penetrable white space for upper extremity specialization programs. Target unlinked prosthesis segments in Japanese prefectures where aging demographics concentrate primary procedure demand. Go-to-market angle: embedded clinical specialist teams bypassing traditional distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for upper extremity pure-plays because EU MDR compliance costs are decoupling small manufacturers from CE mark continuity. Five-to-ten-year viability hinges on reimbursement-listed device catalog positioning in Japan and Germany. Acquisition target archetype: focused elbow specialists with established PMDA or BfArM relationships. Signal to watch: revision surgery volume acceleration in rural Japanese prefectures as inflection indicator for service line investment reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements favor incumbent notified body relationships over challenger timelines. |
| Hospital System Partnership | Academic medical center procurement consolidation rewards embedded clinical specialist teams with exclusive vendor status. |
| Software Companion Development | Integrated surgical navigation systems differentiate implant placement beyond commodity hardware specifications. |
| Reimbursement Strategy | PMDA reimbursement-listed device catalog qualification filters multinational competition in Japan's protected volume pools. |
| Backward Integration | Captive cobalt-chrome alloy qualification insulates margin capture from raw material supply volatility. |
Research Methodology
Direct dialogue with elbow arthroplasty surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) clearances, EMA MDR transition guidance, PMDA reimbursement catalogs, and hospital procurement databases. Bottom-up and top-down triangulation reconciled implant shipment data with procedure volume estimates across the analysis window.
Bottom-up modeling aggregated surgeon-reported case volumes, implant utilization rates, and ASP trajectories by product tier and geography. Top-down verification cross-checked against national arthroplasty registry data, DRG reimbursement filings, and medical device trade flows. Segmentation dimensions spanned constraint mechanism, surface technology, indication type, and care setting. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and demographic disease prevalence projections.
Regulatory timeline slippage, cobalt supply disruption, and fellowship pipeline constraints are the dominant revision risks. Deviation in EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Global Shoulder Replacement Market