
 Orthopedic Joint Reconstruction Market | 2026-2036
Orthopedic Joint Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Joint Reconstruction Market Analysis
Implant servicing and revision component revenue is rewriting profit pool distribution across the orthopedic value chain. Zimmer Biomet leverages its comprehensive revision portfolio and biologics platform to capture recurring surgical demand. Stryker anchors its position through robotics-assisted integration, linking MAKO surgical systems to implant pull-through. Johnson & Johnson Services, Inc. competes via DePuy Synthes's global manufacturing scale and cementless hip innovation pipelines.
Orthopedic joint reconstruction encompasses the surgical replacement of damaged articular surfaces with prosthetic implants, typically fabricated from cobalt-chrome alloys, ultra-high molecular weight polyethylene bearings, and titanium plasma-sprayed stems engineered to restore biomechanical function and alleviate pain in weight-bearing joints. Knee implants dominate procedure volumes globally, while robotics-assisted technology commands premium positioning and fastest expansion as hospitals justify capital expenditure through improved alignment accuracy and reduced revision risk. Cementless fixation gains share in younger, active patient cohorts seeking bone-ingrowth longevity, though cemented constructs retain cost advantages in aging populations with compromised bone quality.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations compel manufacturers to generate robust clinical follow-up data, elevating barriers for new entrants while favoring incumbents with established post-market surveillance infrastructure. ISO 5834 standards for polyethylene wear properties and ASTM F2077 testing protocols for hip stem fatigue resistance further constrain material selection and design freedom. Stakeholders must monitor reimbursement compression dynamics alongside ambulatory site-of-service expansion to calibrate capital deployment between inpatient capacity and outpatient surgical infrastructure.
Market Dynamics
Robotics-assisted surgical platforms are compressing revision risk premiums and redistributing implant demand toward systems-integrated suppliers, forcing capital allocation tradeoffs between hardware infrastructure and consumable pull-through.
Growth Catalysts
- Cementless Fixation Technology:Titanium plasma-sprayed stems with porous coatings enable bone-ingrowth longevity in patients under sixty-five, expanding addressable surgical candidacy beyond traditional age thresholds.
- Ambulatory Surgery Center Expansion:CMS reimbursement parity for outpatient total joint arthroplasty accelerates site-of-service migration from inpatient hospitals to freestanding surgical facilities.
- EU MDR Clinical Evidence Requirements:Stricter post-market surveillance obligations for implant longevity claims favor manufacturers with established registry infrastructure and long-term follow-up datasets.
Market Restraints
- Cobalt-Chrome Alloy Supply Concentration:Primary smelting capacity for medical-grade cobalt concentrates in Central African mining regions and Chinese refining operations creates raw material vulnerability.
- Polyethylene Oxidation Degradation:Gamma-sterilized UHMWPE bearings exhibit oxidative embrittlement in vivo, limiting implant lifespan in high-activity patient cohorts despite cross-linked alternatives.
- FDA 510(k) Predicate Device Pathway:Substantial equivalence requirements for new implant designs constrain geometric innovation and extend regulatory timelines for novel bearing surface configurations.
Strategic Opportunities
- Same-Day Discharge Protocols:Multimodal anesthesia and rapid-recovery pathways enable outpatient total knee arthroplasty in ambulatory surgery centers, capturing reimbursement differentials versus inpatient settings.
- Biologics-Implant Convergence:Osteobiologic adjuvants paired with revision components accelerate bone defect healing, creating premium pricing tiers for complex reconstruction cases.
- Patient-Specific Instrumentation:Preoperative CT-based cutting guides reduce operative time and alignment outliers, differentiating capital equipment vendors in bundled payment environments.
Industry Challenges
- Robotics-Assisted Surgical Training:Steep learning curves for MAKO and ROSA systems require proctored case volumes that strain surgeon bandwidth and delay productivity ramp.
- EU MDR Technical Documentation Remediation:Legacy implant portfolios face costly clinical data gaps under MDR Annex XIV requirements, forcing portfolio rationalization or expensive post-hoc studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Joint Reconstruction Market |
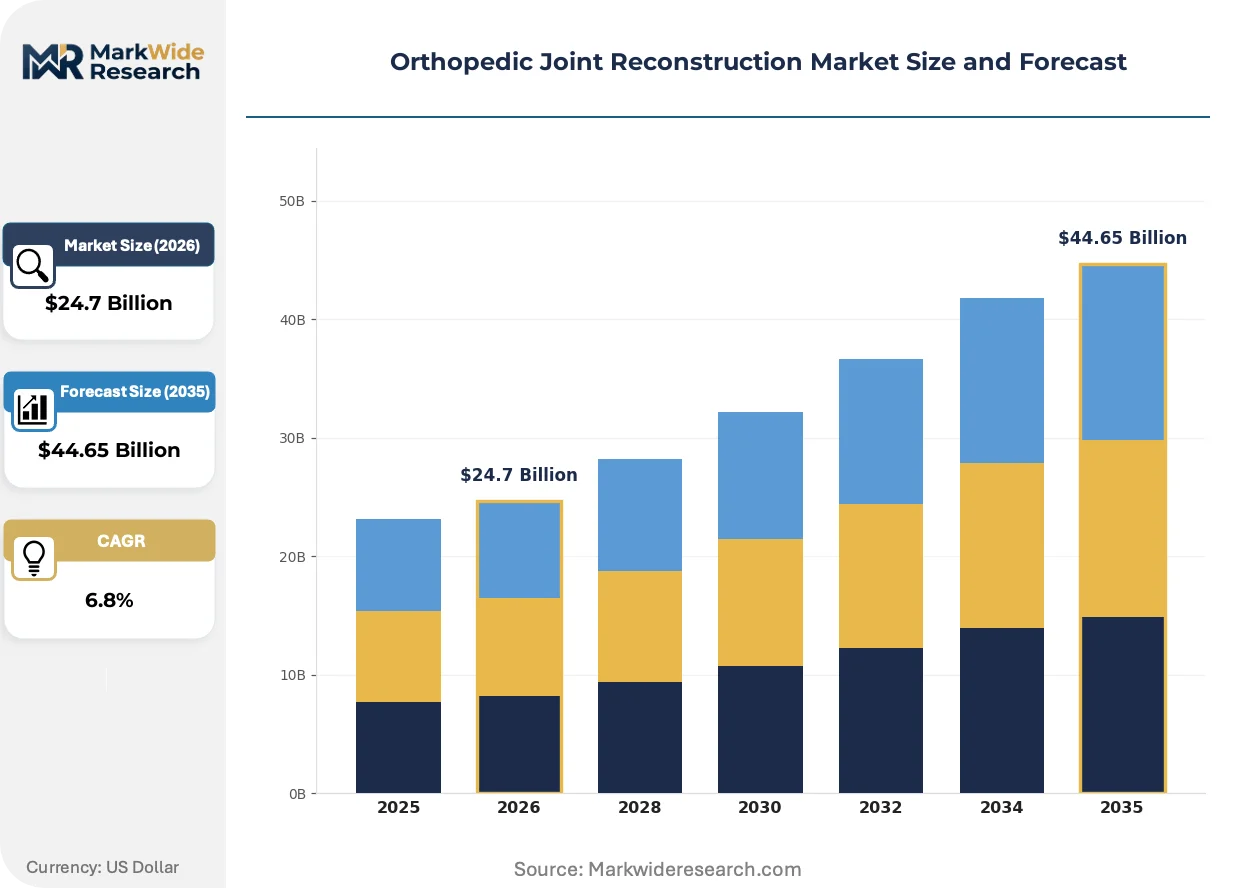
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Implants, Hip Implants, Shoulder Implants, Ankle Implants End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgery Centers Technology: Cemented, Cementless, Hybrid, Robotics-Assisted Material: Metal Alloys, Polyethylene, Ceramic, Biologics |
| Companies Covered | Zimmer Biomet, Stryker, Johnson & Johnson Services, Inc., Smith & Nephew, Medtronic, B. Braun Melsungen AG, Enovis, MicroPort Scientific Corporation, Arthrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Joint Reconstruction Market Emerging Trajectories
Digital surgical ecosystems are collapsing the distinction between preoperative planning, intraoperative execution, and postoperative monitoring, creating integrated data loops that redefine implant value propositions.
Smart implants with embedded sensors for load and temperature monitoring are hybridizing passive mechanical devices with real-time biomechanical feedback systems. Academic medical centers in Germany and the United States are piloting these instrumented tibial trays for postoperative gait analysis. The technology is hybridizing implant hardware with remote patient monitoring revenue streams, compressing traditional device-only business models.
FDA's evolving Software as a Medical Device guidance intersects with EU MDR Annex VIII classification rules to impose dual validation requirements on surgical planning algorithms. Manufacturers must demonstrate clinical equivalence across both jurisdictions for machine learning-enabled alignment prediction tools. Knee implant vendors with pre-cleared digital surgery platforms are responding by accelerating 510(k) submissions for AI-assisted resection planning modules.
Hospital purchasing committees are consolidating implant contracts around single-vendor robotics ecosystems, displacing traditional multi-source procurement for knees and hips. Health systems in the United States are demanding exclusive supply agreements that bundle capital equipment, disposable instruments, and implant inventory. This concentration is most visible in the Southeast, where regional hospital networks are standardizing on one robotic platform to simplify staff training and instrument sterilization workflows.
Orthopedic Joint Reconstruction Market Segmentation
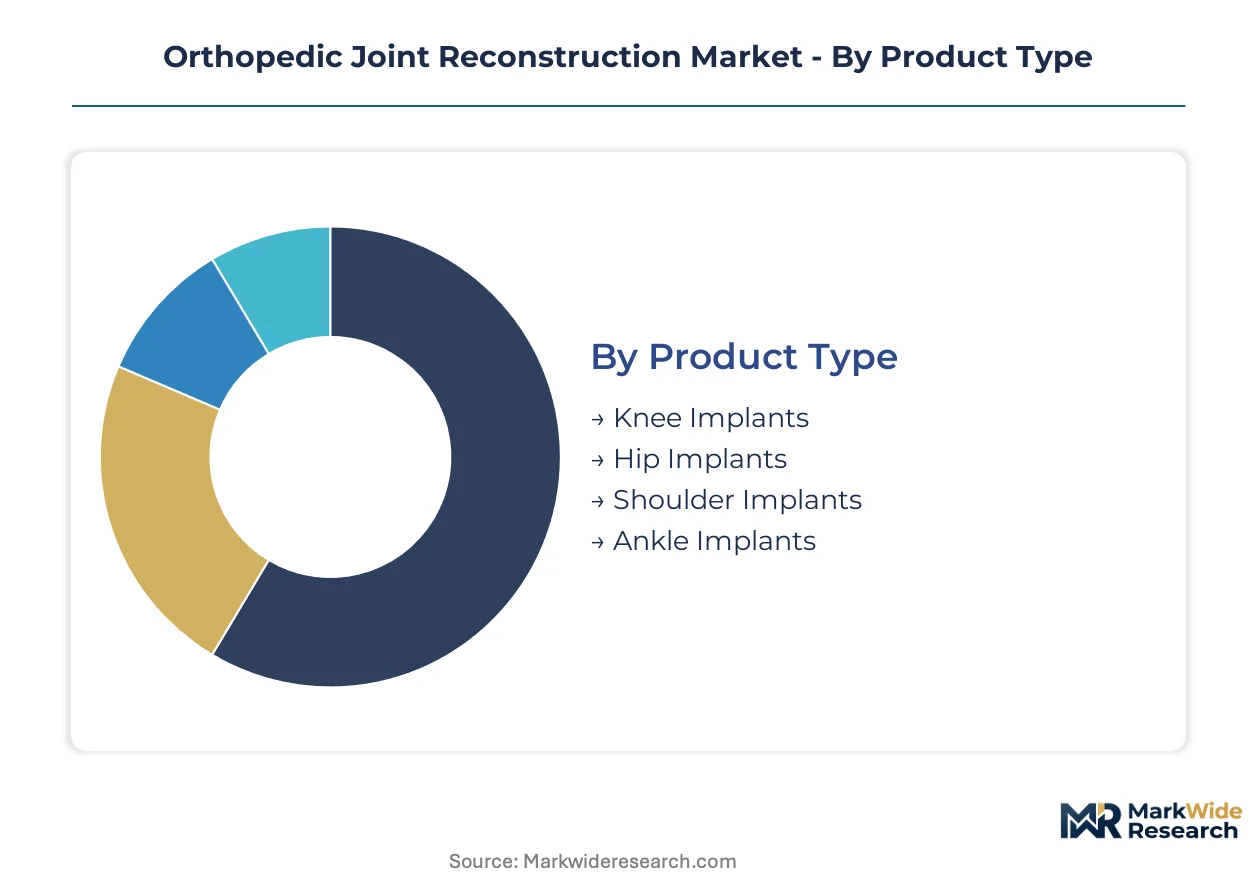
Orthopedic joint reconstruction segmentation reveals distinct clinical and commercial fault lines. Product portfolios, site-of-service economics, fixation philosophies, and material specifications each command separate pricing architectures and regulatory pathways.
Product Type:
Use-case spectrum spans primary arthroplasty for degenerative osteoarthritis through complex revision reconstruction following implant failure.
- Knee Implants:Femoral components, tibial trays, and patellar resurfacing systems address tricompartmental degeneration. Demand concentrates in United States metropolitan hospital networks where bundled payment programs reward standardized implant selection and rapid discharge protocols.
- Hip Implants:Acetabular cups, femoral stems, and bearing couples restore weight-bearing function in femoral head collapse. European markets favor ceramic-on-ceramic configurations for younger patients seeking wear resistance, while United States volume tilts toward metal-on-polyethylene for cost-sensitive Medicare populations.
- Shoulder Implants:Anatomic and reverse total shoulder systems target rotator cuff deficiency and glenohumeral arthritis.
- Ankle Implants:Three-component designs replace tibiotalar articulation in post-traumatic arthritis and rheumatoid destruction.
The dominant share belongs to Knee Implants, while Hip Implants is closing the gap fastest through cementless fixation expansion in active patient cohorts.
End User:
Customer economics stratify across inpatient capacity investments and outpatient infrastructure deployment.
- Hospitals:Academic medical centers and community hospitals maintain high-volume arthroplasty service lines with dedicated joint replacement centers. United States health systems in Florida and Texas are consolidating implant contracts around single-vendor robotics platforms to standardize surgeon training and sterilization workflows.
- Ambulatory Surgery Centers:Freestanding surgical facilities capture CMS reimbursement parity for outpatient total joint procedures. Southeast United States regional networks are migrating knee and hip volumes to ASC settings, capturing facility fee differentials versus inpatient stays.
- Orthopedic Clinics:Physician-owned specialty practices perform diagnostic workup and postoperative monitoring.
- Rehabilitation Centers:Skilled nursing and inpatient rehabilitation facilities manage extended recovery for complex cases.
Hospitals retain the dominant share, though Ambulatory Surgery Centers are expanding most quickly as payor site-of-service incentives intensify.
Technology:
Fixation philosophy and surgical assistance capabilities define implant selection criteria and capital equipment requirements.
- Cementless:Porous-coated titanium stems and acetabular shells enable biological osseointegration. Younger, active patient cohorts in Germany and Australia drive demand for bone-ingrowth longevity, expanding surgical candidacy below traditional age thresholds.
- Robotics-Assisted:Computer-navigated resection and implant positioning systems link hardware infrastructure to implant pull-through. United States hospitals justify MAKO and ROSA capital expenditures through alignment accuracy claims and reduced revision risk positioning.
- Cemented:Polymethylmethacrylate fixation provides immediate stability in osteoporotic bone.
- Hybrid:Combinations of cemented and cementless techniques address specific anatomical challenges.
Cemented technology holds the dominant share, while Robotics-Assisted is gaining share fastest through hospital purchasing committee consolidation around integrated ecosystems.
Material:
Biocompatibility specifications and wear properties govern regulatory clearance pathways and implant longevity claims.
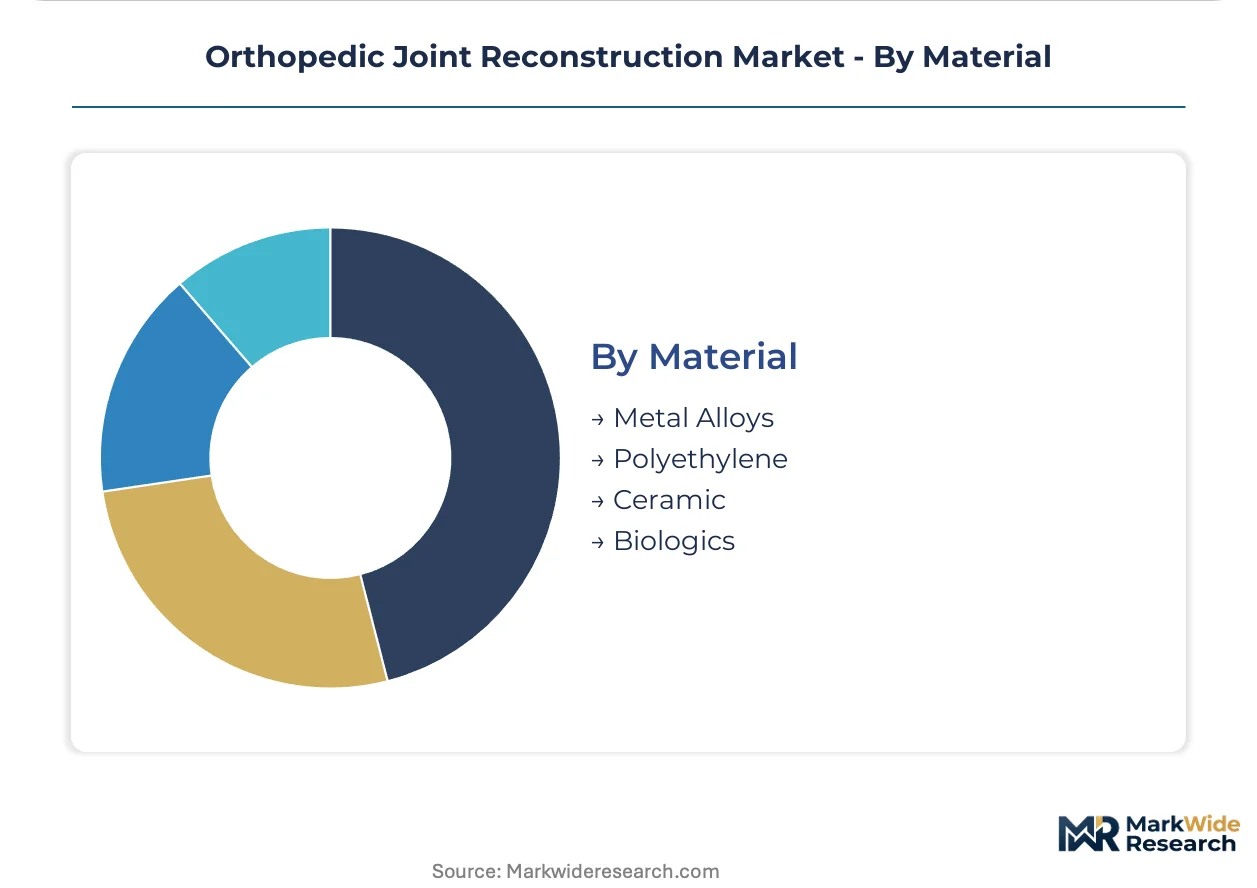
- Metal Alloys:Cobalt-chrome and titanium formulations provide structural support and articulating surfaces. Raw material vulnerability concentrates in Central African mining regions and Chinese refining operations, constraining supply security for medical-grade cobalt concentrates.
- Polyethylene:Ultra-high molecular weight bearings accommodate articulating motion with controlled wear. Cross-linked UHMWPE variants address oxidative embrittlement concerns in gamma-sterilized legacy formulations, though high-activity patient cohorts still exhibit bearing surface degradation.
- Ceramic:Alumina and zirconia composites offer wear resistance for younger patients.
- Biologics:Osteobiologic adjuvants accelerate bone defect healing in revision scenarios.
Metal Alloys command the dominant share, while Biologics is climbing the fastest through convergence with revision component premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade cobalt refining concentrates in Chinese processing facilities and Central African mining regions, creating geographic vulnerability for implant alloy supply chains. United States metropolitan hospital networks and German academic medical centers anchor procedure volume. Regulatory divergence between FDA 510(k) pathways and EU MDR clinical evidence requirements shapes regional competitive positioning.
United States
Commercial reimbursement parity for outpatient total joint arthroplasty accelerates ASC migration in Florida and Texas health systems. FDA 510(k) substantial equivalence requirements constrain geometric innovation timelines for novel bearing surfaces. Southeast regional networks standardize on single-vendor robotics platforms to consolidate surgeon training and sterilization workflows.
Germany
Ceramic-on-ceramic hip configurations dominate younger patient cohorts seeking wear resistance longevity. EU MDR Annex XIV clinical evidence obligations favor manufacturers with established post-market surveillance infrastructure. Academic medical centers in Bavaria pilot smart implant sensor systems for postoperative gait analysis and remote monitoring.
Japan
Aging demographics drive knee arthroplasty volumes in Kanto and Kansai metropolitan corridors. PMDA regulatory timelines for novel cementless fixation technologies extend market entry for porous-coated titanium innovations. Osaka-based surgical networks emphasize rapid-recovery pathways and same-day discharge protocols for cost containment.
Australia
Younger active patient populations in New South Wales and Victoria expand demand for bone-ingrowth longevity solutions. TGA conformity assessment requirements align with ISO 5834 polyethylene wear property standards. Sydney orthopedic clusters lead adoption of patient-specific instrumentation derived from CT-based preoperative planning.
Switzerland
Swissmedic oversight of high-risk implant classifications elevates clinical data requirements for revision component portfolios. Precision manufacturing capabilities in the Lake Geneva region supply plasma-sprayed titanium coatings to European OEMs. Zurich academic hospitals integrate robotics-assisted platforms with bundled payment structures for alignment accuracy justification.
Orthopedic Joint Reconstruction Market Vendor Landscape
Integrated systems vendors and specialized implant manufacturers split the market along capital equipment versus consumable pull-through strategies. Tier-one consolidates around robotics-implant ecosystems and comprehensive revision portfolios. Tier-two competes through biologics convergence and patient-specific instrumentation. Dominant competitive moves include ASC-focused distribution partnerships and MDR-driven portfolio rationalization.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker exemplify systems-integration archetypes linking surgical robotics to implant demand. Johnson & Johnson Services, Inc. occupies a position emphasizing global manufacturing scale and cementless hip innovation pipelines. These three anchors represent distinct strategic postures: comprehensive revision servicing, robotics-assisted alignment platforms, and multinational production infrastructure.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew |
| Medtronic |
| B. Braun Melsungen AG |
| Enovis |
| MicroPort Scientific Corporation |
| Arthrex |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific maritime freight corridors from Shanghai to Long Beach transmit cobalt concentrate cost volatility directly into implant pricing tiers, amplifying margin compression for manufacturers lacking captive raw material positions while enabling premium differentiation for suppliers with vertically secured alloy supply.
Pricing Analysis
Revision component servicing and extended warranty contracts generate lifetime value multiples exceeding primary implant sales. Three-tier pricing structure across premium, standard, and economy levels segments by bearing surface technology and robotic system compatibility, with academic medical centers showing lowest price sensitivity and ASC procurement committees driving hardest volume negotiations. Pricing pressure stems from CMS bundled payment compression and GPO contract consolidation, forcing manufacturers to absorb logistics cost inflation in exchange for exclusive supply agreements.
Supply Chain Analysis
Contract manufacturing for porous titanium coatings concentrates in Swiss precision foundries and German plasma-spray facilities, with secondary capacity in Japanese medical device subcontractors. Raw material sourcing draws from Central African mining regions for cobalt concentrates, Chinese refining operations for medical-grade alloys, and Texan polyethylene resin production for UHMWPE bearings. Single-source vulnerability concentrates in Chinese cobalt processing, where environmental compliance disruptions threaten alloy availability. Distribution runs through hospital system consignment inventory and ASC direct-to-site logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic joint reconstruction operates as a defensive-moat market where regulatory entrenchment through FDA 510(k) predicate pathways and EU MDR clinical evidence requirements erect decade-long barriers against new implant geometries.
For Market Incumbents: Pre-empt robotics-assisted platform standardization by locking Southeast health systems into exclusive MAKO or ROSA supply agreements before competitor capital deployment cycles complete. Cementless fixation R&D pipelines and biologics-implant convergence capabilities represent priority investment levers against emerging sensor-enabled smart implant substitutes. MDR-driven portfolio rationalization creates acquisition opportunities for distressed revision component lines lacking post-market surveillance datasets. For New Entrants and Emerging Players: Ambulatory surgery center distribution partnerships in Texas and Florida represent the most penetrable entry point, bypassing hospital purchasing committee consolidation through direct ASC contracting and rapid-recovery pathway co-development. Patient-specific instrumentation derived from low-dose CT preoperative planning offers a capital-light go-to-market angle that sidesteps robotics hardware infrastructure requirements and appeals to cost-conscious ASC operators seeking alignment accuracy without seven-figure capital commitments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates exiting orthopedic divisions under EU MDR remediation cost pressure, particularly European OEMs facing Annex XIV clinical data gaps in legacy hip and knee portfolios. Long-term viability frames around robotics-implant ecosystem integration and ASC-focused distribution density rather than standalone implant manufacturing scale. Watch FDA 510(k) clearance timelines for AI-assisted surgical planning modules as an inflection signal for digital surgery platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Platform Standardization | Hospital purchasing committees in the Southeast United States are consolidating implant contracts around single-vendor MAKO or ROSA ecosystems to simplify staff training workflows. |
| EU MDR Technical Documentation Remediation | Legacy implant portfolios face costly clinical data gaps under Annex XIV requirements, forcing portfolio rationalization or expensive post-hoc studies. |
| Ambulatory Surgery Center Distribution Partnerships | Freestanding surgical facilities in Florida and Texas capture CMS reimbursement parity for outpatient total joint procedures, creating channel expansion opportunities. |
| Cementless Fixation R&D Pipeline Investment | Porous-coated titanium stems enable bone-ingrowth longevity in patients under sixty-five, expanding addressable surgical candidacy beyond traditional age thresholds. |
| Biologics-Implant Convergence Development | Osteobiologic adjuvants paired with revision components accelerate bone defect healing, creating premium pricing tiers for complex reconstruction cases. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and hospital procurement contract registries preceded structured interviews with orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and ASC operations executives. Secondary validation drew from CMS Medicare claims data, ISO 5834 polyethylene wear property standards, and ASTM F2077 hip stem fatigue testing protocols. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates.
Assumptions held fixed include CMS reimbursement parity for outpatient total joint arthroplasty and EU MDR Annex XIV clinical evidence requirements across the analysis window; variables tested included ASC migration velocity and robotics-assisted adoption curves. Segmentation dimensions spanned product type, site-of-service economics, fixation philosophy, and material specification, with CAGRs derived from regression analysis of historical procedure volumes against demographic projections and payor policy shifts. Forecast inputs incorporated PMDA regulatory timeline assumptions for Japanese market entry and TGA conformity assessment patterns for Australian adoption.
Practitioners should monitor FDA Software as a Medical Device guidance evolution and EU MDR notified body capacity constraints for early signals of digital surgery platform clearance delays or implant portfolio rationalization waves. Forecasts reflect these assumptions alongside modeled scenarios for cobalt supply disruption and ASC reimbursement compression. Quarterly review of hospital system robotics capital expenditure announcements and GPO contract consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Global Orthopedic Splints Market