
 Orthopedic Wire Pin Driver Market | 2026-2036
Orthopedic Wire Pin Driver Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Wire Pin Driver Market Insights
ISO 13485 certification is rotating as the primary gatekeeper for orthopedic power tool manufacturers seeking CE marking and FDA registration. Stryker leverages its vertically integrated manufacturing footprint across North America and Europe to sustain premium positioning. Zimmer Biomet anchors its portfolio through deep relationships with hospital purchasing consortiums. NSK competes in Asia-Pacific through specialized compact drive systems for extremity surgery.
An orthopedic wire pin driver is a powered surgical instrument delivering rotational torque to insert Kirschner wires, Steinmann pins, and similar fixation hardware into bone, typically operating at speeds between 800 and 2,500 RPM with adjustable torque clutch mechanisms to prevent thermal necrosis. Its primary purpose is to enable precise, repeatable fixation in trauma and reconstructive procedures while reducing surgeon fatigue and operative time. The product type dimension shows drive devices capturing the dominant margin pool due to electromechanical complexity and replacement part revenue, while surgical pins represent a high-volume consumable stream with thinner unit economics. Application-level demand tilts toward fracture fixation as trauma case volumes expand, though sports medicine represents the fastest-growing surgical indication as arthroscopic techniques advance.
FDA 510(k) premarket notification and EU MDR technical documentation requirements impose substantial compliance costs that favor incumbents with dedicated regulatory affairs teams. The EU F-Gas Regulation and RoHS substance restrictions additionally constrain motor and battery chemistry choices for cordless pin driver platforms. Stakeholders must monitor how FDA's evolving software-as-a-medical-device guidance applies to smart pin drivers with torque-sensing feedback algorithms.
Market Dynamics
Powered surgical instrument manufacturers face mounting pressure from EU MDR recertification timelines and FDA software guidance evolution, compressing product development cycles while expanding compliance overhead.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter clinical evidence requirements for Class IIa surgical instruments accelerate hospital replacement cycles as older devices lose CE marking validity.
- Trauma center expansion in China:Provincial health commissions prioritize orthopedic emergency infrastructure, creating concentrated demand clusters for powered fixation systems.
- Battery chemistry advances:Lithium-sulfur cell density improvements enable cordless pin drivers with sustained torque output matching tethered alternatives.
Market Restraints
- Neodymium supply concentration:Rare earth magnet processing dominates Chinese refining corridors, exposing motor assembly costs to export quota volatility.
- EU F-Gas Regulation motor cooling constraints:Restricted refrigerant options limit thermal management designs for high-RPM surgical handpieces.
- Manual instrument substitution:Battery-powered alternatives face price resistance from cost-conscious ambulatory surgery centers maintaining pneumatic tool fleets.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives for Class C surgical equipment attract contract manufacturing investment from multinational power tool suppliers.
- Torque-sensing algorithm integration:Convergence of strain gauge miniaturization and edge computing enables real-time bone density adaptation during pin insertion.
- Direct-to-hospital distribution:Bypassing traditional implant distributor networks allows device manufacturers to capture service contract margins previously ceded to intermediaries.
Industry Challenges
- ISO 13485 auditor shortage:Certification body capacity constraints extend quality management system audit queues by eight to fourteen months.
- Legacy sterilization protocol incompatibility:Newer polymer housing materials degrade under steam autoclave cycles still standard across German hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Wire Pin Driver Market |
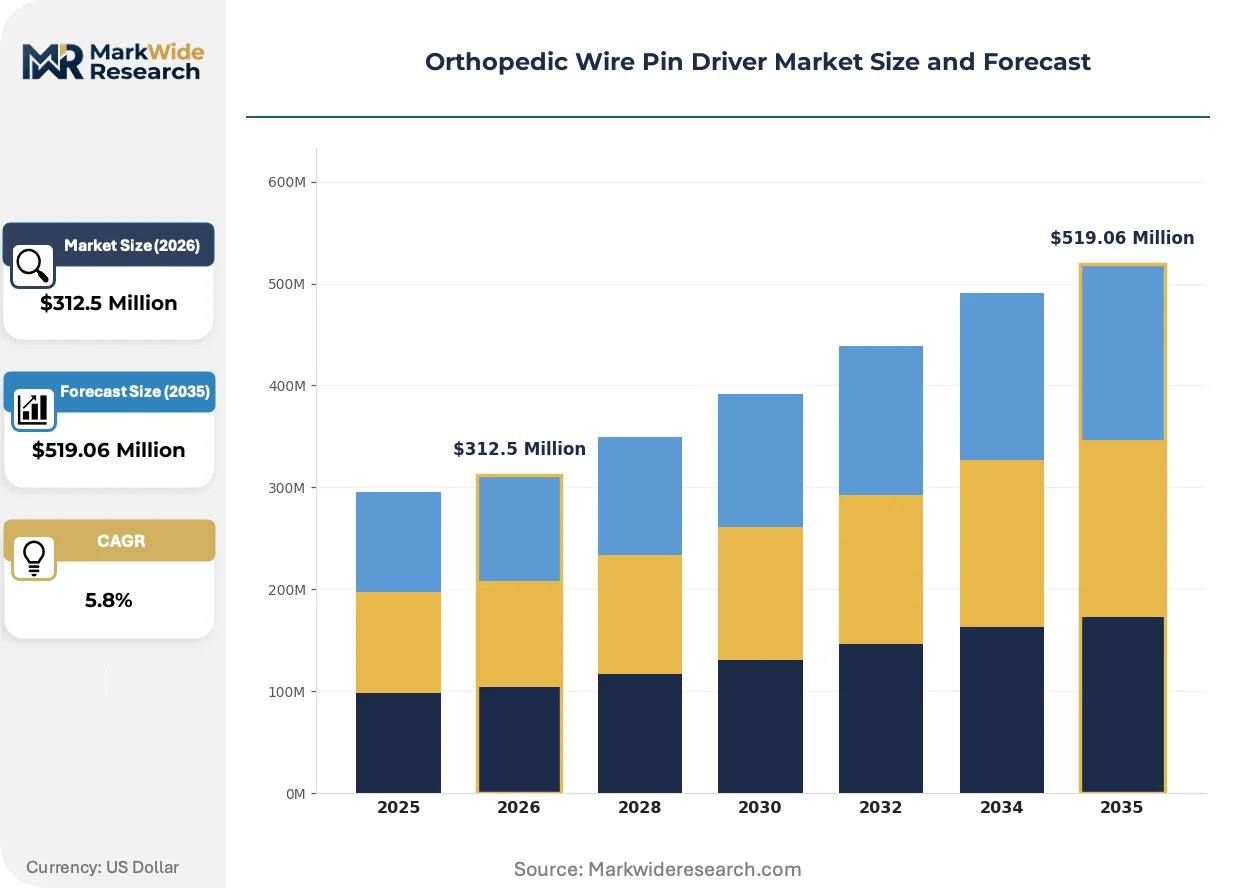
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Pins, Drive Devices, Drills, Accessories Application: Fracture Fixation, Joint Surgery, Bone Stabilization, Sports Medicine End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesale |
| Companies Covered | Stryker, NSK, ConMed, ACF Medical, Healmeds, PUSM, Wuhu Ruijin, Norer, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Wire Pin Driver Market Trends and Innovations
Smart instrument architectures and revised regulatory frameworks are redrawing competitive boundaries between established orthopedic power tool suppliers and emerging electromechanical specialists.
Brushless DC motor platforms with integrated torque feedback loops are fragmenting the traditional distinction between premium surgical-grade and industrial-grade power tools. Tier-one trauma centers in the United States and Germany now specify closed-loop control systems previously reserved for neurosurgical applications. This capability migration is compressing margin structures for mid-tier device categories as performance expectations converge upward.
EU MDR Article 117 device-drug combination rules now capture pin drivers delivering antibiotic-coated fixation hardware, triggering additional notified body consultation requirements. Surgical instrument divisions must restructure regulatory submission workflows previously siloed from pharmaceutical compliance teams. Trauma product portfolios face the steepest timeline extensions as legacy technical files require clinical literature reviews for biocompatibility substantiation.
Hospital purchasing consortiums in the United States are consolidating orthopedic power tool contracts into single-source agreements spanning multiple surgical disciplines. Independent ambulatory surgery centers lose negotiating leverage as integrated delivery networks centralize procurement authority. This concentration is most pronounced in Texas and Florida health systems where orthopedic specialty consolidation has outpaced national benchmarks.
Orthopedic Wire Pin Driver Market Segmentation
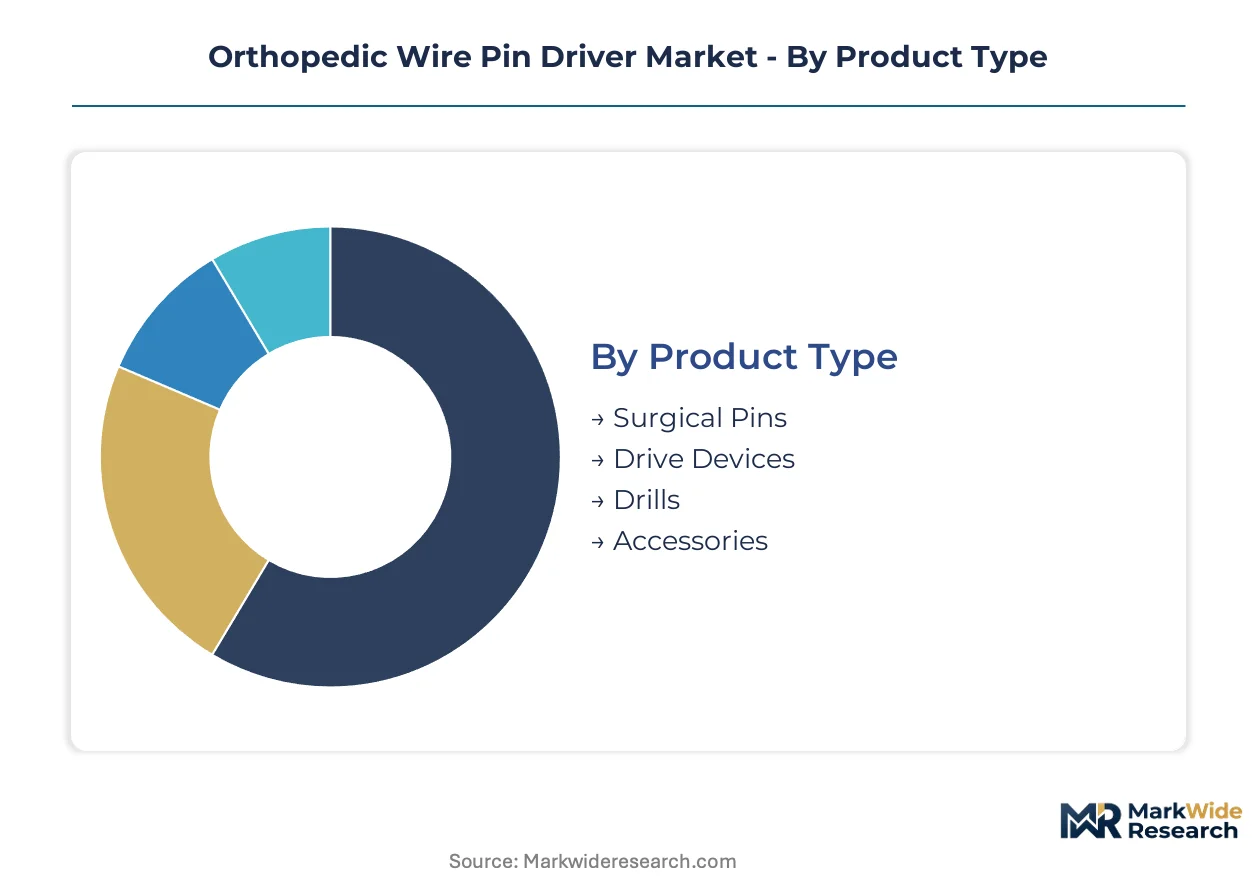
Orthopedic wire pin driver segmentation reveals divergent margin structures across hardware and consumables, with electromechanical complexity determining pricing power. Procurement patterns vary sharply between capital-intensive trauma centers and high-volume ambulatory settings.
Product Type:
Margin pools concentrate in reusable drive systems where torque-clutch engineering and motor miniaturization sustain premium positioning, while consumable pins compete on volume scale.
- Drive Devices:Electromechanical handpieces delivering 800-2,500 RPM with adjustable torque clutches dominate capital equipment budgets. United States trauma centers prioritize closed-loop feedback systems for thermal necrosis prevention, driving replacement cycles as battery chemistry advances.
- Surgical Pins:Kirschner wires and Steinmann pins constitute high-volume consumables with thinner unit economics. Chinese provincial hospitals anchor demand as trauma infrastructure expands, though sterilization protocol standardization constrains material selection.
- Drills:General-purpose rotary instruments for bone preparation serve lower-acuity procedures. German hospital networks maintain pneumatic tool fleets for cost containment.
- Accessories:Sterilization trays, battery packs, and torque-limiting attachments complete system ecosystems. Aftermarket revenue stabilizes manufacturer cash flows.
Drive devices hold installed capacity. Surgical pins are rotating up the share rankings.
Application:
Procedure complexity and reimbursement rates determine equipment specification tiers across surgical indications.
- Fracture Fixation:Trauma procedures requiring precise pin placement for bone alignment constitute the foundational demand base. United States Level I trauma centers specify premium cordless systems for emergency department throughput.
- Sports Medicine:Arthroscopic techniques for ligament reconstruction and joint preservation are expanding most quickly. German outpatient clinics drive adoption of compact extremity-focused drivers.
- Joint Surgery:Total and partial arthroplasty procedures leverage pin drivers for provisional fixation. Academic medical centers concentrate demand for navigation-compatible instruments.
- Bone Stabilization:Prophylactic and corrective osteotomy applications serve pediatric and deformity correction practices. Reimbursement variability limits equipment upgrade frequency.
Fracture fixation maintains procedure volume leadership. Sports medicine claims the steepest expansion trajectory.
End User:
Capital allocation authority and sterilization infrastructure capacity shape purchasing behavior across care settings.
- Hospitals:Integrated delivery networks centralize procurement for high-volume orthopedic service lines. Texas and Florida health systems lead specialty consolidation.
- Orthopedic Clinics:Dedicated musculoskeletal practices prioritize instrument durability for same-day surgery throughput. Ambulatory surgical facility licensing drives equipment standardization.
- Surgical Centers:Freestanding facilities balance capital constraints against case volume growth. Leasing arrangements predominate for powered instrument fleets.
- Rehabilitation Facilities:Post-acute settings utilize pin drivers for hardware removal and adjustment procedures. Lower utilization rates sustain manual instrument preference.
Hospitals command capital budgets. Orthopedic clinics are rotating up the share rankings.
Distribution Channel:
Channel economics reflect service intensity requirements and regulatory documentation burdens.
- Direct Sales:Manufacturer field organizations serve tier-one trauma centers with technical training and service contract bundling. United States purchasing consortiums consolidate contract authority.
- Medical Distributors:Specialized orthopedic supply intermediaries maintain sterile field representation and inventory consignment. German hospital networks rely on regional distributors for MDR compliance support.
- Online Retail:E-procurement platforms gain traction for accessory and consumable replenishment. Chinese hospital group purchasing organizations pilot digital sourcing.
- Wholesale:Broad-line medical supply aggregators serve cost-sensitive secondary markets. Price transparency pressures margin structures.
Direct sales hold installed relationships. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Level I trauma centers in the United States, Germany, and China concentrate procurement authority for powered surgical instruments. Hospital purchasing consortiums in Texas and Florida drive contract consolidation. Provincial health commissions in China accelerate infrastructure deployment.
United States
Integrated delivery networks in Texas and Florida centralize orthopedic power tool procurement across multi-hospital systems. FDA 510(k) premarket notification timelines favor established manufacturers with dedicated regulatory affairs teams. Level I trauma centers in Houston and Miami specify closed-loop torque feedback systems for emergency department throughput.
Germany
Academic medical centers in Berlin and Munich prioritize navigation-compatible instruments for complex arthroplasty procedures. EU MDR technical documentation requirements extend recertification timelines for Class IIa surgical instruments. The Baden-Württemberg industrial corridor hosts precision motor manufacturers supplying surgical handpiece assemblies.
China
Provincial health commissions prioritize trauma center expansion in Sichuan and Guangdong provinces. NMPA registration pathways for powered surgical instruments streamline market entry for domestic manufacturers. The Yangtze River Delta cluster concentrates battery cell production for cordless surgical platforms.
Japan
Metropolitan hospitals in Tokyo and Osaka adopt compact extremity-focused drivers for outpatient arthroscopic procedures. PMDA consultation requirements for software-enabled surgical instruments extend development cycles. The Nagoya industrial zone supplies brushless DC motor components to regional device assemblers.
India
Corporate hospital chains in Maharashtra and Karnataka upgrade surgical suites for orthopedic trauma capacity. CDSCO medical device rules and PLI scheme incentives attract contract manufacturing investment from multinational suppliers. The Delhi-NCR corridor concentrates distributor networks serving North Indian hospital procurement.
Orthopedic Wire Pin Driver Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with integrated power tool divisions. Market structure concentrates around three to five established suppliers with decade-long hospital relationships. Strategic archetypes span full-line trauma platforms, specialized extremity systems, and contract manufacturing specialists. Competitive moves center on M&A for regulatory asset acquisition and direct-to-hospital distribution bypassing traditional implant intermediaries.
Among diversified orthopedic suppliers, Stryker, Zimmer Biomet, and ConMed occupy positions spanning premium-tier trauma centers and mid-market ambulatory settings. Stryker represents the vertically integrated archetype with captive manufacturing across North American and European corridors. Zimmer Biomet anchors consortium-level contracting authority through integrated delivery network relationships. ConMed exemplifies the acquisition-driven expansion model, consolidating regional specialists into broader surgical instrument portfolios.
| Leading Market Players |
|---|
| Stryker |
| NSK |
| ConMed |
| ACF Medical |
| Healmeds |
| PUSM |
| Wuhu Ruijin |
| Norer |
| Zimmer Biomet |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification gates both supplier qualification and price differentiation in orthopedic power tools, with audit queue delays extending eight to fourteen months and concentrating procurement leverage among incumbents who can absorb compliance overhead while mid-tier competitors face margin compression from expedited certification fees.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate motor assembly sourcing, with neodymium magnet pricing tethered to Chinese export quota volatility. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop feedback systems from basic cordless units and refurbished pneumatic fleets. Pricing pressure stems from ambulatory surgery centers maintaining manual instrument substitution for cost containment. German hospital networks exhibit lowest price sensitivity due to EU MDR recertification mandates, while Indian corporate hospital chains negotiate aggressively under PLI scheme incentives.
Supply Chain Analysis
Just-in-time inventory strategies predominate among United States integrated delivery networks, while Chinese provincial hospitals maintain strategic stockpiles of surgical pins to buffer NMPA registration delays. Brushless DC motor components concentrate in Japan's Nagoya industrial zone and Germany's Baden-Württemberg corridor, with battery cell production anchored in China's Yangtze River Delta. Raw material dependencies span neodymium magnets, lithium-sulfur cells, and surgical-grade stainless steel. Single-source vulnerability in rare earth refining exposes motor costs to export quota disruptions. Distribution runs through specialized orthopedic supply intermediaries maintaining sterile field representation and MDR compliance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual instrument substitution threatens cordless pin driver penetration in cost-sensitive settings, forcing powered surgical instrument manufacturers to defend elective procedure volumes through performance differentiation and service bundling.
For Market Incumbents: Consolidate regulatory affairs capacity to compress EU MDR recertification timelines and capture hospital replacement cycles as legacy devices lose CE marking validity. Deepen backward integration into precision motor manufacturing to insulate margins from neodymium supply volatility. Anchor consortium-level contracting authority through integrated delivery network relationships in Texas and Florida health systems. For New Entrants and Emerging Players: Aftermarket service gaps in torque-limiting attachment calibration and battery pack refurbishment present white-space targets where incumbents under-serve. India's PLI scheme for Class C surgical equipment offers the most penetrable geography for contract manufacturing investment. Pursue direct-to-hospital distribution bypassing traditional implant distributor networks to capture service contract margins. For Investors and Strategic Acquirers: EU MDR Article 117 device-drug combination rules reshape the acquisition landscape by triggering additional notified body consultation requirements for antibiotic-coated fixation hardware delivery systems. Long-term viability favors targets with dedicated pharmaceutical compliance teams and restructured regulatory submission workflows. Watch for ISO 13485 auditor capacity expansion as the signal indicating accelerated certification timelines and compressed competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | CE marking validity cliffs for Class IIa surgical instruments concentrate replacement demand among prepared incumbents. |
| Torque-Sensing Algorithm Development | Strain gauge miniaturization convergence with edge computing enables real-time bone density adaptation during pin insertion. |
| Direct-to-Hospital Distribution Buildout | Bypassing implant distributor networks captures service contract margins previously ceded to sterile field intermediaries. |
| Lithium-Sulfur Battery Integration | Cell density improvements enable cordless platforms with sustained torque output matching tethered alternatives. |
| India PLI Scheme Manufacturing Entry | Production-linked incentives for Class C equipment attract contract manufacturing from multinational power tool suppliers. |
Research Methodology
A spread of perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, NMPA registration filings, hospital procurement contract records, and trade customs data for surgical instrument imports. Bottom-up installed base estimates and top-down trauma procedure volume projections were triangulated to anchor market sizing.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the projection horizon. CAGRs were derived from procedure volume elasticity to trauma center infrastructure deployment, battery chemistry substitution curves, and regulatory recertification cycle timing. Industry-specific forecast inputs include provincial health commission capital expenditure plans in China and integrated delivery network specialty consolidation patterns in the United States.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR implementation timelines, and NMPA registration procedures; material policy shifts would require re-modeling. Revision becomes warranted when rare earth export quota volatility or auditor capacity constraints cross thresholds that alter certification queue dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Hip Orthosis Market