
 Orthopedic Extremity Market | 2026-2036
Orthopedic Extremity Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Extremity Market Analytics
Modular implant systems with interchangeable bearing surfaces and stem options is realigning hospital procurement toward configurable kits rather than single-SKU purchases. Stryker Corporation leverages its proprietary Triathlon knee platform to anchor high-volume extremity reconstruction contracts with integrated delivery networks. Zimmer Biomet Holdings competes through differentiated shoulder arthroplasty portfolios that occupy the revision and reverse-construction segments. Arthrex specializes in suture anchor and soft-tissue fixation technologies that sustain premium positioning in sports medicine extremity applications.
Orthopedic extremity devices encompass implants, fixation hardware, prosthetic replacements, and orthotic supports engineered from cobalt-chrome alloys, titanium porous structures, and ultra-high molecular weight polyethylene for load-bearing articulation in shoulder, elbow, wrist, hip, knee, ankle, and foot joints. These systems restore mechanical alignment and enable ambulation following trauma, degenerative joint failure, or congenital deformity. The implant and fixation device segments dominate revenue due to recurring revision cycles and instrument tray economics, while biologics-enabled bone grafting represents the fastest-expanding technology category as surgeons integrate cellular scaffolds into complex fracture management. Sports injury applications command disproportionate margin pools because athletic patient demographics justify premium bearing surfaces and accelerated rehabilitation protocols.
FDA 510(k) premarket notification requirements govern device safety and substantial equivalence for U.S. market access, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance for CE-marked extremity products. Japan's PMDA enforces QMS inspections and clinical data standards that shape entry timelines for foreign manufacturers. Stakeholders must monitor evolving biocompatibility testing protocols and decentralized trial frameworks that will determine which product configurations achieve accelerated regulatory pathways.
Market Dynamics
The Orthopedic Extremity Market is reconfiguring around patient-specific manufacturing workflows that compress implant delivery from months to weeks, forcing traditional inventory-heavy distribution models toward digital-to-physical supply chains anchored by point-of-care 3D printing capabilities.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined premarket notification for 3D-printed implants accelerates product-to-market timelines for patient-specific extremity hardware, reducing regulatory friction for additive manufacturing platforms.
- Ambulatory Surgical Center Expansion:Dedicated orthopedic outpatient networks in the United States, Germany, and China are shifting procedure volumes away from inpatient settings, creating concentrated demand nodes for extremity reconstruction systems.
- Porous Titanium Structures:Osseointegration-optimized additive manufacturing lattices enable biological fixation without cement, expanding indications to younger, active patient demographics previously excluded from arthroplasty.
Market Restraints
- Cobalt-Chrome Alloy Supply Concentration:Foundry capacity for medical-grade casting alloys clusters in German and Austrian suppliers, exposing implant manufacturers to input volatility from energy-intensive smelter operations.
- EU Medical Device Regulation Transition:MDR's expanded clinical evidence requirements and notified body bottlenecks extend CE-marking timelines for extremity implant portfolios, freezing product launches in European markets.
- Revision Surgery Burden:Polyethylene bearing surface wear and aseptic loosening generate predictable long-term liability costs that compress margins on primary arthroplasty systems despite high initial ASPs.
Strategic Opportunities
- Biologics-Enabled Bone Grafting:Cellular scaffold integration into complex fracture management represents the fastest-expanding technology category as surgeons combine mechanical fixation with osteoinductive matrices.
- Sports Medicine Premium Positioning:Athletic patient demographics in North American and Australian markets justify accelerated rehabilitation protocols and ceramic-on-ceramic bearing surfaces that command sustained margin premiums.
- Japan PMDA Streamlined Entry:QMS inspection harmonization initiatives for foreign manufacturers with existing FDA clearance create regulatory arbitrage opportunities for extremity implant portfolios.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Point-of-care 3D printing deployment requires specialized biomedical engineers capable of DICOM-to-implant workflow management, a skillset concentrated in academic medical centers.
- Instrument Tray Capital Intensity:Modular implant systems demand hospital capital allocation to configurable sterilization and storage infrastructure that strains ambulatory surgical center balance sheets.
- Post-Market Surveillance Data Integration:MDR-mandated implant registries and FDA's evolving real-world evidence frameworks require manufacturers to restructure quality management systems around longitudinal patient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Extremity Market |
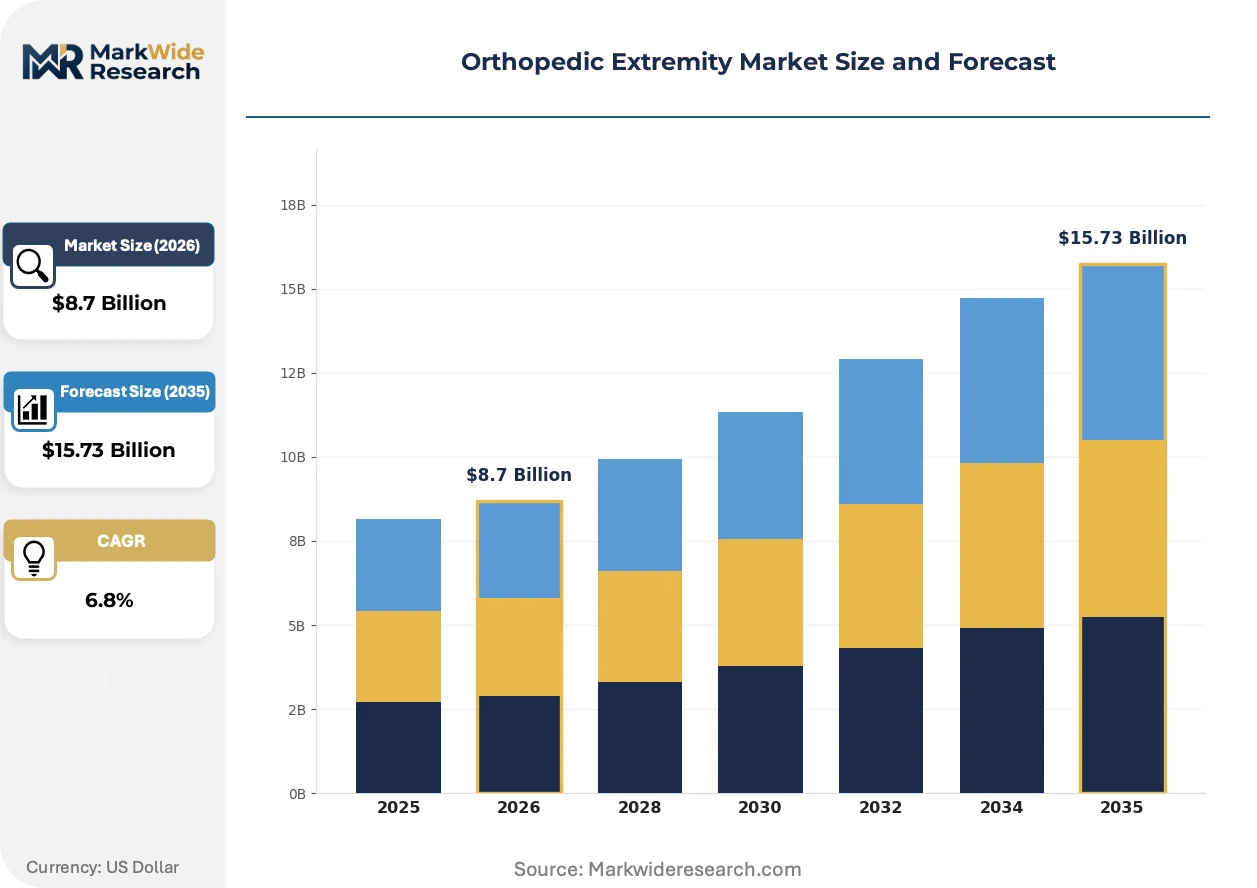
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Fixation Devices, Prosthetics, Orthotics End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Technology: Bone Grafting, Arthroscopy, Preoperative Planning, Biologics Application: Fractures, Sports Injuries, Degenerative Conditions, Trauma |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, DePuy Synthes, Smith & Nephew, Arthrex, Medtronic, Globus Medical, Enovis Corporation, Acumed LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Extremity Market Evolving Landscape
Digital manufacturing workflows are collapsing traditional boundaries between imaging, design, and implant production, enabling same-day surgical planning that redefines extremity reconstruction economics.
Patient-specific 3D-printed titanium lattice implants is absorbing the functional load of conventional machined stems in complex revision arthroplasty. Academic medical centers and high-volume orthopedic networks are adopting these platforms at accelerating cadence as surgeon training programs integrate additive manufacturing literacy. This technology is absorbing the revision case volume that previously required extensive intraoperative customization, compressing operative time and instrument sterilization costs.
Japan's PMDA has tightened QMS inspection protocols for foreign-manufactured extremity implants, requiring on-site audits that extend entry timelines by six to twelve months. Domestic distributors are absorbing compliance costs by establishing captive technical documentation teams in Tokyo. European and North American manufacturers with existing FDA 510(k) portfolios are most affected, responding through joint venture structures with Japanese orthopedic device specialists.
Hospital procurement committees are consolidating extremity implant purchasing through integrated delivery network contracts that bundle primary and revision systems across multiple joint categories. Independent ambulatory surgical centers are responding through group purchasing organizations that aggregate volume for configurable modular kits. This behavioral shift is most visible in United States metropolitan markets where health system consolidation has concentrated buying power among three to five dominant networks per region.
Orthopedic Extremity Market Segmentation
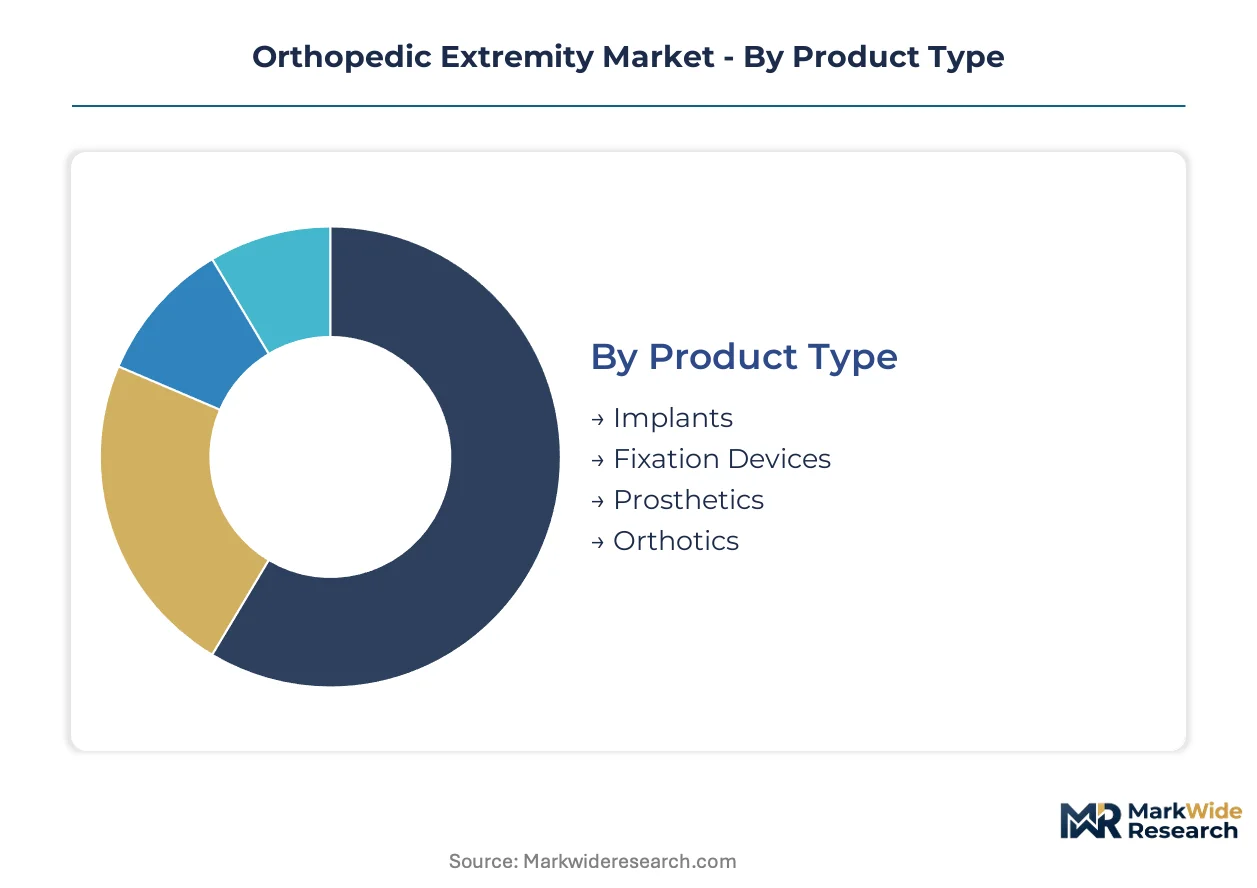
Orthopedic extremity device segmentation reveals divergent margin structures and replacement-cycle economics across hardware categories. Procurement committees weigh revision-surgery predictability against upfront capital allocation when configuring multi-joint implant portfolios.
Product Type:
Upgrade cycles vary dramatically across hardware categories, with cementless fixation driving shorter effective lifecycles in younger patient cohorts.
- Implants:Cobalt-chrome and titanium porous structures form the revenue core for shoulder, hip, and knee arthroplasty. United States integrated delivery networks concentrate procurement for modular systems with interchangeable bearing surfaces, compressing vendor margins through volume aggregation.
- Fixation Devices:Plates, screws, and intramedullary nails manufactured from medical-grade stainless steel and titanium alloys stabilize complex fractures. German trauma centers generate concentrated demand for anatomically contoured locking plate systems that reduce secondary revision rates.
- Prosthetics:Silicone and advanced polymer limb replacements serve amputation rehabilitation with customized socket interfaces.
- Orthotics:Rigid and semi-rigid external support devices manage non-operative joint stabilization and post-surgical immobilization.
Volume placements concentrate in Implants; the faster expansion belongs to Fixation Devices as trauma case volumes rise in emerging outpatient networks.
End User:
Capital intensity and sterilization infrastructure requirements sort customers into distinct procurement tiers with divergent contract structures.
- Hospitals:Academic medical centers and tertiary care facilities maintain comprehensive arthroplasty programs with dedicated implant libraries and revision surgery capabilities. China's tier-one cities are building dedicated orthopedic wings that anchor regional referral networks for complex reconstruction cases.
- Clinics:Ambulatory surgical centers in United States metropolitan markets are capturing primary arthroplasty volume through streamlined patient pathways and same-day discharge protocols.
- Rehabilitation Centers:Post-acute facilities manage prosthetic fitting and orthotic customization for functional recovery programs.
- Home Care:Remote monitoring and mobile orthotic services extend care continuity for rural and mobility-limited patient populations.
Procedure economics favor Clinics for standard primary cases; the steepest expansion trajectory runs through Rehabilitation Centers as bundled payment models lengthen post-acute accountability.
Technology:
Surgeon workflow integration and training-curve duration determine technology adoption velocity across operative settings.
- Bone Grafting:Autograft, allograft, and synthetic matrices address segmental bone loss in complex trauma and tumor resection. Australian sports medicine networks are pioneering cellular scaffold combinations with mechanical fixation for accelerated return-to-play protocols.
- Arthroscopy:Minimally invasive joint visualization and instrumentation enables diagnostic and therapeutic procedures with reduced soft-tissue disruption.
- Preoperative Planning:CT-based templating and 3D-printed surgical guides compress operative time and implant sizing errors.
- Biologics:Growth factor and cell-based therapies represent the frontier of biological fixation enhancement, though reimbursement uncertainty constrains routine deployment.
Established utilization centers on Arthroscopy; Biologics is climbing the fastest as Japan's PMDA streamlines regenerative medicine approval pathways.
Application:
Patient demographics and activity-level expectations create divergent pricing tolerance across injury and disease categories.
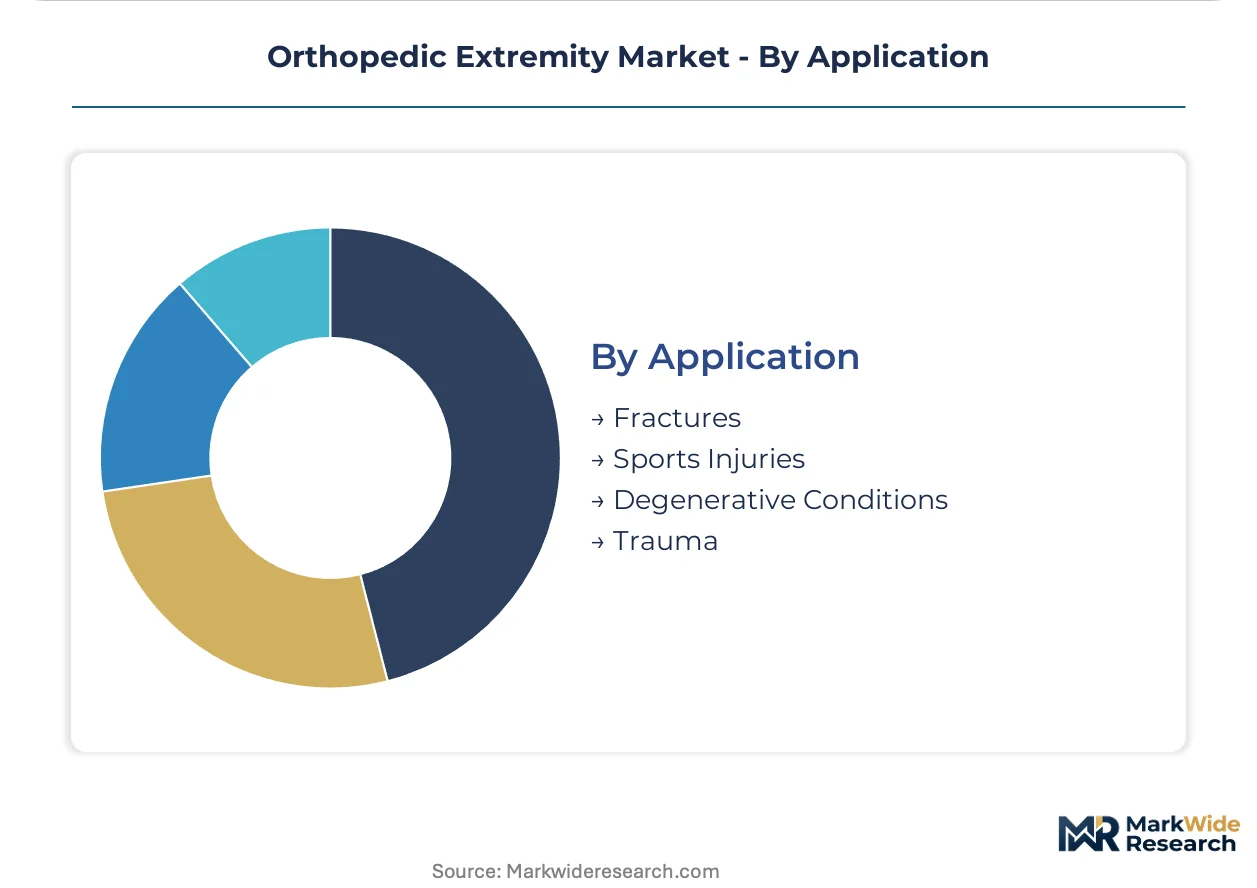
- Sports Injuries:Ligament reconstruction and cartilage repair in athletic populations justify premium bearing surfaces and accelerated rehabilitation investments. North American professional and collegiate sports networks sustain disproportionate margin pools for suture anchor and soft-tissue fixation technologies.
- Fractures:Trauma fixation hardware addresses acute skeletal disruption from falls, collisions, and occupational incidents.
- Degenerative Conditions:Osteoarthritis and rheumatoid arthritis drive elective arthroplasty volume in aging populations with predictable implant wear profiles.
- Trauma:High-energy injury patterns require emergent stabilization with provisional and definitive fixation strategies.
Case volume aggregates in Degenerative Conditions; Sports Injuries is gaining share fastest as youth athletic participation and injury awareness expand in middle-income markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic extremity device production clusters in German and Austrian foundries for cobalt-chrome alloys, while consumption concentrates in the United States, Germany, and China as these nations expand dedicated outpatient surgical networks.
United States
Integrated delivery networks in metropolitan markets aggregate procurement power for modular implant systems, compressing vendor margins through volume-based contracting. FDA 510(k) pathway modernization accelerates clearance timelines for 3D-printed patient-specific hardware. The Cleveland Clinic and Mayo Clinic anchor high-volume extremity reconstruction referral networks that drive technology adoption.
Germany
Trauma centers generate concentrated demand for anatomically contoured locking plate systems that reduce secondary revision rates. EU Medical Device Regulation transition extends CE-marking timelines, freezing some product launches while domestic manufacturers adapt quality management systems. The Stuttgart and Dresden industrial corridors host precision foundry operations for medical-grade casting alloys.
China
Tier-one cities are building dedicated orthopedic wings that anchor regional referral networks for complex reconstruction cases. NMPA regulatory harmonization initiatives streamline market entry for foreign manufacturers with existing FDA clearance. Shanghai and Beijing medical centers pioneer point-of-care 3D printing deployment for patient-specific implant production.
Japan
PMDA QMS inspection protocols for foreign-manufactured implants extend entry timelines by six to twelve months, favoring domestic distributors with captive technical documentation teams. METI initiatives promote regenerative medicine approval pathway streamlining for biologics-enabled bone grafting. The Tokyo-Osaka corridor concentrates orthopedic device distribution infrastructure.
Australia
TGA oversight shapes entry requirements for extremity implant portfolios, with sports medicine networks pioneering cellular scaffold combinations for accelerated return-to-play protocols. Professional and collegiate athletic systems sustain premium pricing tolerance for ceramic-on-ceramic bearing surfaces. Sydney and Melbourne academic medical centers drive arthroscopy technology adoption.
Orthopedic Extremity Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with integrated instrument tray economics and modular platform strategies. Hospital procurement consolidation favors vendors offering configurable kits across multiple joint categories rather than single-SKU suppliers. Three archetypes dominate: full-line reconstructive platforms, sports medicine specialists, and trauma fixation innovators. M&A activity targets additive manufacturing capabilities and biologics portfolios, while strategic partnerships anchor distribution in ambulatory surgical center networks.
Among diversified orthopedic platforms, Stryker Corporation and Zimmer Biomet Holdings exemplify the full-line reconstructive archetype with modular knee and shoulder systems. Arthrex occupies a specialist position in suture anchor and soft-tissue fixation technologies for sports medicine applications. These three anchors represent contrasting competitive vectors: scale-driven platform breadth versus focused premium positioning in high-margin athletic patient segments.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| DePuy Synthes |
| Smith & Nephew |
| Arthrex |
| Medtronic |
| Globus Medical |
| Enovis Corporation |
| Acumed LLC |
| Others |
Value Network & Pricing Analysis
Cobalt-chrome alloy ingot costs cascade through German and Austrian foundry operations into tiered implant pricing, with energy-intensive smelter economics separating premium porous titanium structures from standard cemented stem configurations in hospital procurement negotiations.
Pricing Analysis
Margin tightening in primary arthroplasty systems reflects polyethylene bearing surface commoditization and integrated delivery network volume aggregation. Three-tier pricing structure across premium, standard, and economy levels stratifies by osseointegration performance and surgeon training requirements. Cost compression accelerates in standard tiers as ambulatory surgical centers consolidate purchasing through group buying organizations. Academic medical centers exhibit lowest price sensitivity due to revision surgery capture and teaching mission subsidies.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume extremity implant demand from integrated delivery networks, while specialty distributors serve independent ambulatory surgical centers with configurable instrument tray logistics. German and Austrian foundries supply medical-grade cobalt-chrome casting alloys; Chinese titanium sponge refineries feed additive manufacturing powder production. Distribution runs through regional orthopedic device specialists with captive sterilization infrastructure. Single-source vulnerability concentrates in porous titanium lattice printing capacity anchored in academic medical center point-of-care deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for medical-grade cobalt-chrome alloys prop implant pricing power, with energy cost volatility in German and Austrian smelter operations sustaining margin premiums for manufacturers with captive alloy supply arrangements.
For Market Incumbents: Anchor procurement committee relationships through bundled primary-revision system contracts across shoulder, hip, and knee categories. Deepen backward integration into cobalt-chrome foundry operations to offset German and Austrian supplier energy cost volatility. Defend against additive manufacturing point-of-care entrants by locking instrument tray economics into long-term ambulatory surgical center agreements. For New Entrants and Emerging Players: Patient-specific 3D-printed titanium lattice platforms offer entry wedge into complex revision arthroplasty cases underserved by modular stem systems. Target United States metropolitan ambulatory surgical centers with DICOM-to-implant workflow partnerships that compress operative time. Pursue FDA 510(k) pathway modernization for streamlined premarket notification to accelerate first commercial placements. For Investors and Strategic Acquirers: PMDA QMS inspection harmonization announcements for FDA-cleared portfolios is the leading indicator that Japanese market entry timelines will compress for foreign manufacturers, unlocking distribution value in the Tokyo-Osaka corridor. Position for five-to-ten year holding periods around biologics-enabled bone grafting capabilities. Monitor additive manufacturing technician certification program expansion as inflection signal for point-of-care deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Modernization | Accelerates premarket clearance for 3D-printed patient-specific implants, compressing product-to-market timelines. |
| Point-of-Care 3D Printing Deployment | Enables same-day surgical planning and patient-specific titanium lattice production at academic medical centers. |
| Biologics-Enabled Bone Grafting | Integrates cellular scaffolds with mechanical fixation for complex fracture management in sports medicine networks. |
| Ambulatory Surgical Center Partnership | Captures primary arthroplasty volume shift through streamlined patient pathways and same-day discharge protocols. |
| PMDA QMS Harmonization | Streamlines Japanese market entry for FDA-cleared manufacturers through reduced inspection timelines. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR notified body conformity assessments, and hospital procurement database extracts, complemented by interviews with orthopedic surgeons, biomedical engineers, GPO contracts managers, and additive manufacturing specialists. Secondary sources included CMS Medicare utilization data, Japanese PMDA QMS inspection records, and German foundry industry reports. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Historical implant placement trends cross-referenced against surgeon panel input on technology adoption velocity shaped the projection framework. Segmentation modeling covered product type, end user facility tier, technology category, and application across geographic markets. CAGRs derived from procedure volume elasticity to aging demographics and sports injury incidence patterns. Forecast inputs incorporated ambulatory surgical center expansion trajectories and regulatory pathway modernization timelines without year-specific anchoring.
Several conditions sit outside the modeled scope, including unannounced MDR notified body capacity constraints, cobalt-chrome alloy supply disruptions from energy market volatility, and breakthrough biologics reimbursement determinations. Forecasts reflect documented assumptions on surgeon training curve duration and point-of-care 3D printing technician availability. Periodic stress-testing of base assumptions against PMDA inspection protocol changes and integrated delivery network consolidation announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market