
 3D Orthopedic Scanning System Market | 2026-2036
3D Orthopedic Scanning System Market Size, Share, and Industry Trends Forecast 2026-2036
3D Orthopedic Scanning System Market Intelligence
Buyer concentration among hospital networks and orthopedic clinic chains is recalibrating procurement standards for 3D scanning platforms. GE Healthcare leverages its installed base of diagnostic imaging to cross-sell orthopedic scanning modules into integrated surgical planning suites. Materialise anchors its position through software-hardware bundling that locks in prosthetic design workflows. Stryker Corporation competes by extending its joint replacement ecosystem into pre-operative anatomical capture.
A 3D orthopedic scanning system is an optical or laser-based device that captures sub-millimeter surface geometry of bone structures and surrounding soft tissue for digital reconstruction. These systems typically operate at resolutions between 0.1 mm and 0.5 mm, generating point clouds that feed into CAD environments for patient-specific implant fabrication or prosthetic socket design. Handheld scanner deployments dominate orthopedic clinics due to flexibility across examination rooms, while structured light technology captures the largest revenue share given its speed-to-accuracy ratio for full-limb acquisition. Prosthetics design applications are expanding fastest as rehabilitation centers adopt socket-digitization protocols to reduce fitting iterations.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development cycles and market access timelines for device manufacturers. ISO 13485 quality management certification has become a baseline procurement filter for hospital buyers evaluating scanner vendors. Stakeholders must monitor how CMS reimbursement coding for digitized surgical planning evolves, as coverage decisions will determine whether clinic-level adoption accelerates or stalls outside cash-pay cosmetic and sports-medicine segments.
Market Dynamics
Hospital procurement consolidation is compressing vendor evaluation cycles and forcing scanner manufacturers to bundle software licenses with hardware contracts to secure multi-year agreements. Orthopedic clinic chains now demand ISO 13485 certification as a non-negotiable entry ticket, filtering out smaller optical component suppliers.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for optical scanning devices with predicate device claims are accelerating product introductions into US hospital networks. Device manufacturers leverage substantial equivalence arguments to compress regulatory review periods.
- Prosthetics digitization protocols:Rehabilitation centers in Germany and Japan are mandating socket-scanning workflows to reduce fitting iterations and improve patient throughput. These protocols create pull-through demand for handheld structured light systems.
- Laser triangulation advances:Sub-millimeter accuracy improvements in blue-laser scanning modules are displacing contact-based measurement in pre-surgical planning suites. Orthopedic surgeons now specify optical capture for complex revision cases.
Market Restraints
- CMOS sensor supply concentration:Taiwanese and South Korean semiconductor foundries dominate high-resolution image sensor fabrication, creating single-source vulnerability for scanner OEMs. Geopolitical friction threatens component availability.
- EU MDR technical documentation burdens:Expanded clinical evidence requirements for Class IIa optical devices extend conformity assessment timelines by 12-18 months. Notified body capacity constraints compound delays.
- Contact-based CMM substitution:Coordinate measuring machines retain preference in high-tolerance orthopedic implant manufacturing where absolute dimensional traceability is mandatory. Optical systems face displacement risk in metrology-grade applications.
Strategic Opportunities
- Pediatric orthopedic digitization:Underpenetrated children's hospitals in India and Brazil lack dedicated scanning protocols for growing-limb prosthetics. Early-mover vendors can establish de facto standards before public procurement frameworks crystallize.
- AI-integrated point cloud processing:Machine learning algorithms converging with optical capture are automating anatomical landmark detection and reducing CAD preprocessing labor. Software-hardware bundling locks in recurring revenue streams.
- Japan METI productivity subsidy programs:Government incentives for surgical workflow digitization cover 30-50% of scanner acquisition costs for accredited medical institutions. Qualified vendors gain price advantage in public tenders.
Industry Challenges
- Biomedical optics engineering talent scarcity:Specialized skill sets combining laser physics, medical device regulation, and clinical workflow design concentrate in Boston and Stuttgart clusters. Recruitment competition with autonomous vehicle LiDAR programs drives compensation inflation.
- Legacy PACS integration complexity:Hospital IT departments resist optical scan data formats that bypass established DICOM infrastructure. Scanner vendors must develop proprietary bridges or cede procurement decisions to radiology department veto.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Orthopedic Scanning System Market |
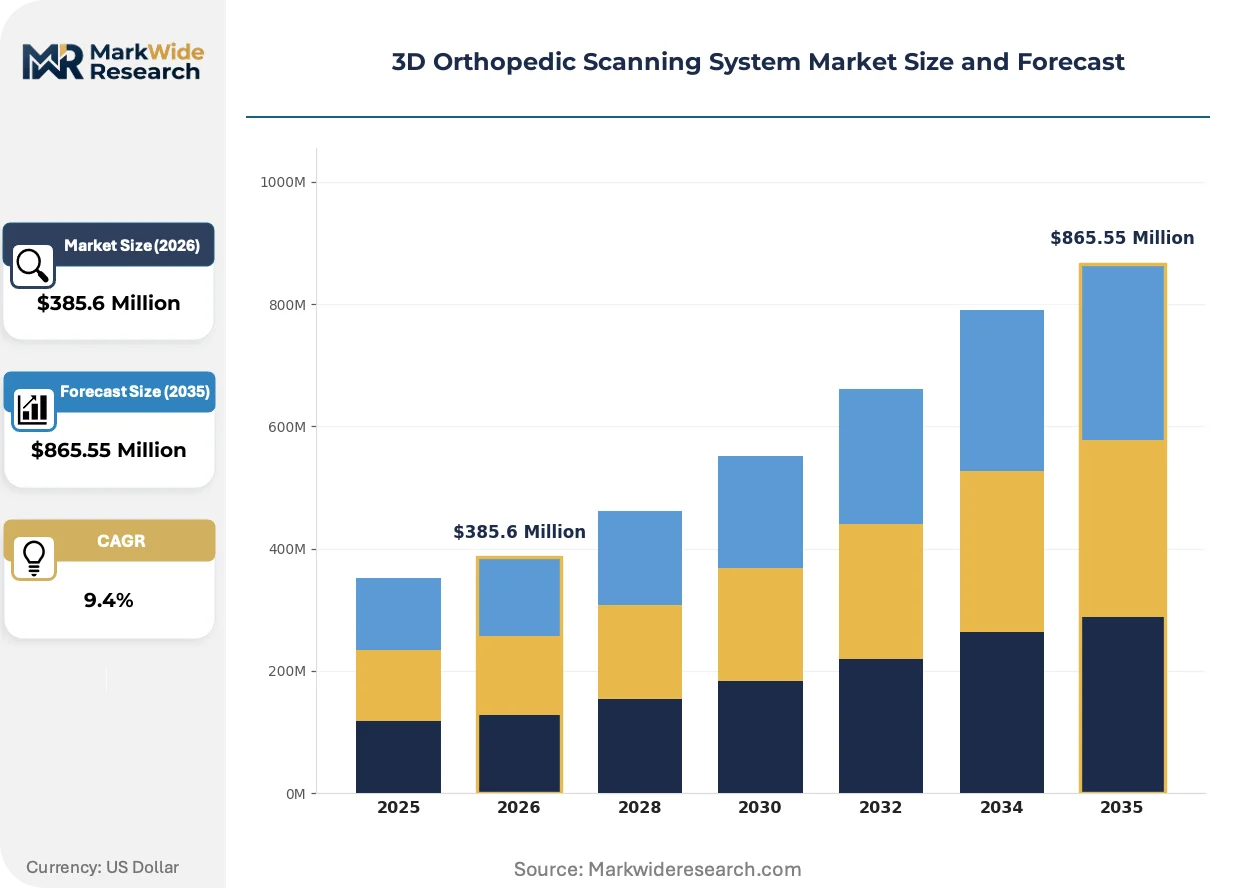
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanner, Fixed Scanner, Portable Scanner, Desktop Scanner Technology: Laser Scanning, Structured Light, Photogrammetry, Time-of-Flight Application: Orthopedic Implants, Prosthetics Design, Injury Assessment, Rehabilitation Planning End User: Orthopedic Clinics, Rehabilitation Centers, Diagnostic Labs, Research Institutions |
| Companies Covered | GE Healthcare, Medtronic, Materialise, Elinvision, Artec Europe, Stryker Corporation, 3D Systems, FARO Technologies, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Orthopedic Scanning System Market Strategic Shifts & Innovations
Real-time surface reconstruction algorithms are collapsing the gap between patient examination and implant design, compressing pre-surgical planning timelines from weeks to days. Three convergent developments are reshaping competitive positioning.
Structured light scanning is automating full-limb geometry capture in orthopedic clinics, eliminating technician-dependent measurement variability. German rehabilitation centers deploy these systems across examination rooms with minimal calibration downtime. The technology is automating socket design workflows that previously required three to four manual fitting appointments.
EU MDR post-market surveillance obligations are mandating systematic clinical follow-up data collection for optical scanning devices. Manufacturers must establish vigilance systems tracking device performance across implant lifecycle. High-volume joint replacement centers face the steepest compliance cost increases as they manage scanner fleets across multiple surgical sites.
Hospital procurement departments are consolidating vendor relationships into integrated surgical planning contracts that bundle imaging, scanning, and implant supply. Orthopedic clinic chains in the United States now issue single-source RFPs spanning diagnostic capture through prosthetic delivery. This behavior concentrates purchasing power among three to five national health systems that can mandate interoperability standards.
3D Orthopedic Scanning System Market Segmentation
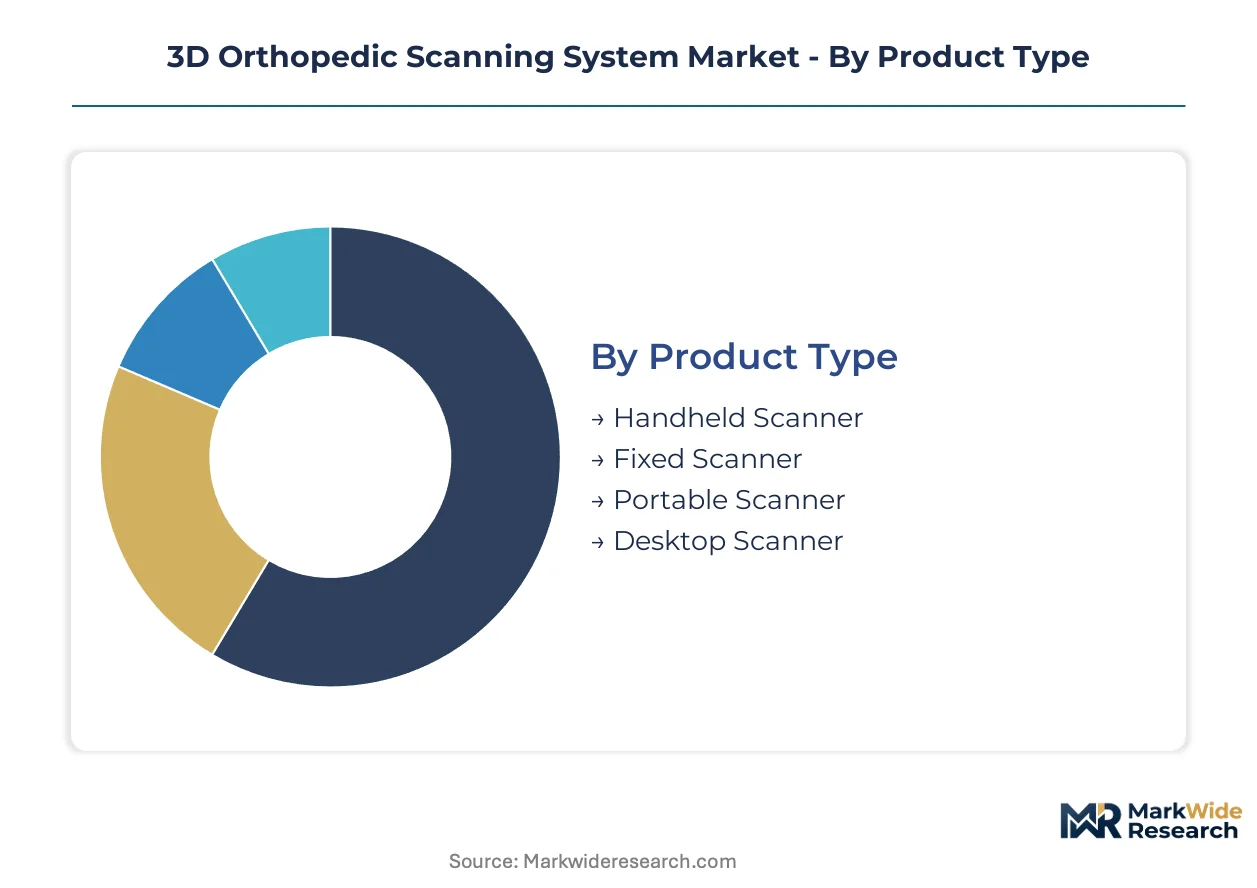
Segmentation in the 3D orthopedic scanning system market reveals distinct procurement patterns across hardware form factors, optical technologies, and clinical workflows. Hospital buyers prioritize upgrade compatibility and replacement-cycle synchronization when evaluating scanner investments across these dimensions.
Product Type:
Replacement cycles vary sharply across product categories, with clinic infrastructure constraints and mobility requirements dictating refresh timing.
- Handheld Scanner:Compact optical units weighing under 2 kilograms enable point-of-care capture across multiple examination rooms. German rehabilitation centers and Japanese orthopedic clinics deploy these for socket-digitization protocols that compress patient fitting schedules. Procurement concentrates in ambulatory settings where room-to-room flexibility outweighs absolute precision benchmarks.
- Fixed Scanner:Stationary gantry systems mounted on calibrated frames deliver sub-0.1-millimeter accuracy for complex revision surgeries. United States hospital networks install these in dedicated pre-surgical planning suites where throughput justifies capital allocation. The upgrade cycle extends to 7-10 years given structural installation requirements and software integration depth.
- Portable Scanner:Battery-powered units with wheeled transport support outreach programs and satellite clinic deployments.
- Desktop Scanner:Compact benchtop systems serve research institutions and small orthopedic practices with limited floor space.
Volume placements concentrate in Handheld Scanner configurations; the faster expansion belongs to Portable Scanner systems as outreach networks proliferate.
Technology:
Cost tiers separate optical capture methods, with precision requirements and software licensing bundling creating distinct budget brackets for hospital procurement committees.
- Laser Scanning:Blue-laser triangulation modules achieve 0.05-millimeter accuracy through structured light projection and CMOS sensor arrays. United States academic medical centers specify these for revision joint replacement cases where bone defect mapping demands metrology-grade fidelity. Component costs from Taiwanese foundries concentrate supply risk in premium-tier deployments.
- Structured Light:Pattern projection systems capture full-limb geometry in under 10 seconds with 0.1-0.3-millimeter precision. German rehabilitation centers standardize on these platforms for prosthetic socket workflows that eliminate manual measurement variability. The technology dominates mid-tier procurement budgets through favorable speed-to-accuracy economics.
- Photogrammetry:Multi-camera passive systems reconstruct surface geometry from calibrated image sets without active projection.
- Time-of-Flight:Modulated light pulse measurement enables rapid depth mapping for initial screening applications.
Procurement volumes cluster in Structured Light platforms; steepest expansion trajectory attaches to Laser Scanning as revision surgery volumes climb in aging populations.
Application:
Customer type and reimbursement pathways segment demand, with implant manufacturers and rehabilitation providers operating on divergent procurement timelines.
- Orthopedic Implants:Pre-surgical anatomical capture for patient-specific joint replacement components requires ISO 13485-traceable measurement chains. United States hospital networks integrate these workflows with FDA-cleared surgical planning software to secure CMS reimbursement coverage. The application commands premium pricing through regulatory documentation burdens.
- Prosthetics Design:Socket digitization for lower-limb prostheses reduces fitting iterations from four appointments to two. Japanese rehabilitation centers leverage METI productivity subsidies covering 30-50 percent of scanner acquisition costs. Demand concentrates in government-funded disability services where throughput metrics drive capital allocation.
- Injury Assessment:Trauma documentation and deformity quantification support medicolegal and treatment planning workflows.
- Rehabilitation Planning:Progress monitoring for orthopedic recovery protocols enables objective outcome measurement.
Revenue concentration sits with Orthopedic Implants; Prosthetics Design gains share fastest as digitization mandates spread through European and Asian rehabilitation networks.
End User:
Facility scale and patient volume determine scanner fleet sizing, with procurement authority centralizing differently across institutional types.
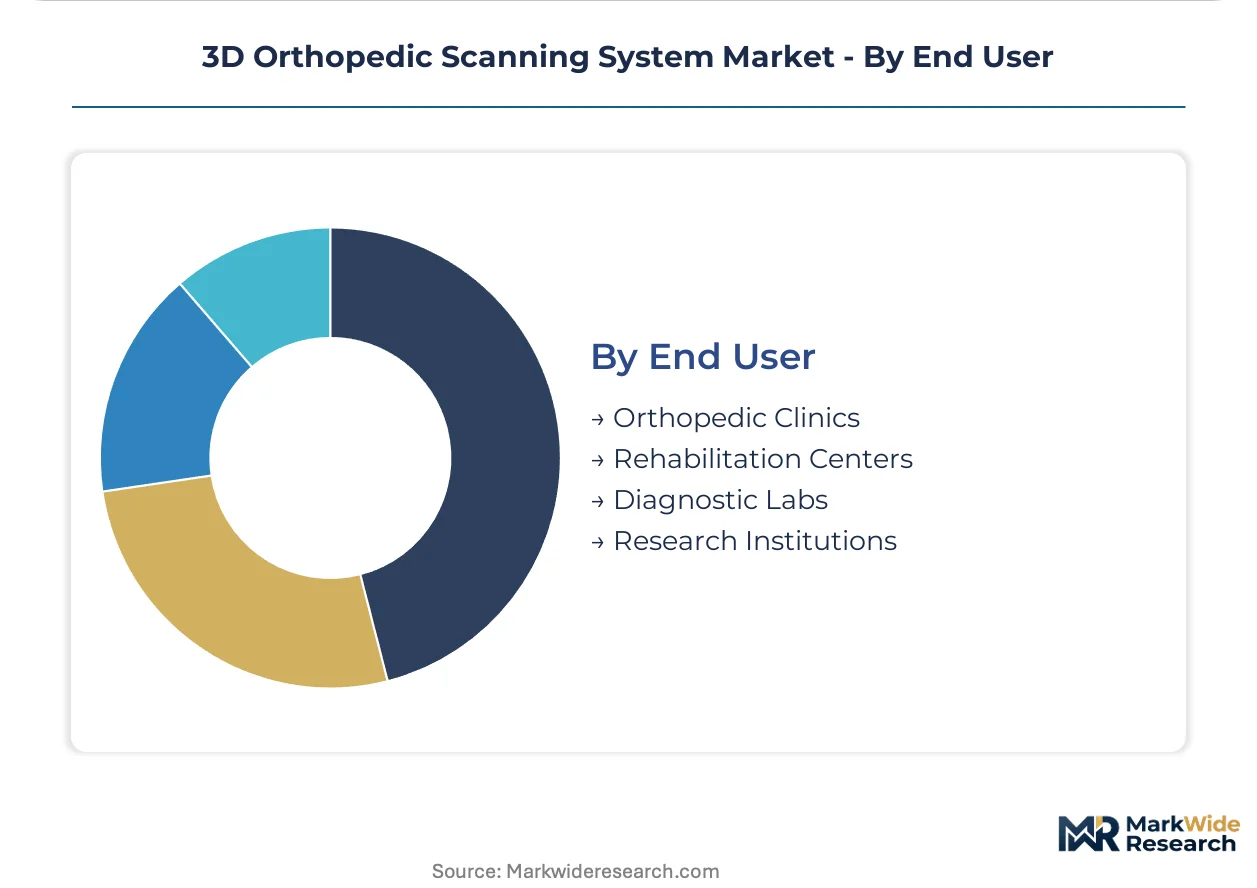
- Orthopedic Clinics:Private practice groups and specialty clinic chains deploy 1-3 handheld units per location for examination-room flexibility. United States-based Arthritis and Joint Replacement Centers specify structured light systems bundled with implant vendor software licenses. Replacement cycles accelerate to 4-5 years as optical sensor resolution improves.
- Rehabilitation Centers:Prosthetics and orthotics facilities mandate socket-scanning protocols to standardize fitting quality across technician skill levels. German statutory health insurance reimbursement frameworks cover digitization costs, creating pull-through demand for mid-tier hardware. Volume procurement concentrates in national disability service networks.
- Diagnostic Labs:Independent imaging centers add optical scanning to differentiate from hospital radiology departments.
- Research Institutions:Academic medical centers and biomechanics laboratories evaluate emerging capture technologies for clinical translation.
Scanner shipments concentrate in Orthopedic Clinics; Rehabilitation Centers show the steepest volume climb as European and Asian health systems mandate digitization protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement budgets concentrate in the United States, Germany, and Japan, where digitized pre-surgical workflows command premium capital allocation. Orthopedic clinic chains in these markets are standardizing structured light and laser scanning platforms for implant customization and prosthetic socket design.
United States
FDA 510(k) clearance pathways for optical scanning devices with predicate device claims compress regulatory review timelines for manufacturers. Academic medical centers in Boston and New York specify blue-laser triangulation modules for revision joint replacement cases demanding metrology-grade fidelity. Hospital networks consolidate vendor relationships into integrated surgical planning contracts spanning diagnostic capture through prosthetic delivery.
Germany
Rehabilitation centers mandate socket-scanning protocols under statutory health insurance reimbursement frameworks that cover digitization costs. EU MDR technical documentation obligations for Class IIa optical devices extend conformity assessment timelines, filtering smaller suppliers from procurement pools. The Stuttgart cluster anchors biomedical optics engineering talent combining laser physics with medical device regulation expertise.
Japan
METI productivity subsidy programs cover 30-50 percent of scanner acquisition costs for accredited medical institutions, creating price advantages for qualified vendors in public tenders. Rehabilitation centers in Osaka and Tokyo deploy handheld structured light systems for prosthetic socket workflows that compress patient fitting schedules. Aging population demographics drive revision surgery volumes and associated pre-surgical anatomical capture demand.
United Kingdom
NHS procurement frameworks for orthopedic digitization equipment prioritize ISO 13485-certified vendors with established clinical evidence portfolios. London teaching hospitals integrate optical scanning into surgical planning suites alongside FDA-cleared software for CMS-equivalent reimbursement pathways. The Oxford-Cambridge corridor concentrates research institutions evaluating emerging capture technologies for clinical translation.
South Korea
MFDS regulatory pathways for optical medical devices align with international standards, facilitating market access for scanner OEMs with established EU or US clearances. Seoul-based hospital networks invest in fixed gantry systems for dedicated pre-surgical planning suites where throughput justifies capital allocation. Domestic CMOS sensor fabrication capabilities from foundries in Suwon reduce component supply vulnerability for local scanner assemblers.
3D Orthopedic Scanning System Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-hardware bundling and AI-integrated point cloud processing as differentiation vectors. The market structure consolidates around three to five national health systems in the United States and integrated clinic chains in Germany that mandate interoperability standards through single-source RFPs. Diagnostic imaging incumbents and surgical implant manufacturers represent dominant strategic archetypes, each leveraging installed base relationships to cross-sell orthopedic scanning modules. Competitive moves concentrate on strategic partnerships for PACS integration bridges and geographic expansion into underpenetrated pediatric orthopedic markets in India and Brazil.
Within the diagnostic imaging tier, GE Healthcare and Siemens Healthineers exemplify archetypes leveraging cross-selling infrastructure into surgical planning suites. Among surgical implant specialists, Stryker Corporation and Medtronic occupy positions extending joint replacement ecosystems into pre-operative anatomical capture. Materialise represents the software-hardware bundling archetype, anchoring prosthetic design workflows through locked-in CAD environments. 3D Systems and FARO Technologies sit within the precision metrology tier, serving high-tolerance applications where absolute dimensional traceability commands premium positioning.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic |
| Materialise |
| Elinvision |
| Artec Europe |
| Stryker Corporation |
| 3D Systems |
| FARO Technologies |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap optical component specialists in Germany and Japan anchor supply-side discipline through multi-generational capital allocation that resists short-term margin compression. Their patient financing models sustain ISO 13485-certified production lines while pricing power concentrates among scanner OEMs with captive software ecosystems.
Pricing Analysis
High-volume handheld scanner placements compete on procurement contract scale while fixed gantry systems command margin premiums through metrology-grade precision claims. Pricing stratifies across FDA-cleared premium tiers, ISO 13485-certified standard tiers, and uncertified economy tiers for research applications. Cost compression in mid-tier structured light modules intensifies as Taiwanese CMOS sensor foundries consolidate supply. Rehabilitation centers in Germany exhibit highest price sensitivity due to statutory reimbursement caps, while United States academic medical centers prioritize accuracy benchmarks over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Boston, and Osaka coordinate hub-and-spoke patterns for scanner hardware and replacement optical components. Manufacturing concentrates in Germany for precision gantry assemblies, Taiwan for CMOS sensor fabrication, and South Korea for laser diode modules. Scanner OEMs draw from specialized biomedical optics foundries with limited alternative sourcing for blue-laser triangulation engines. Single-source vulnerability in Taiwanese semiconductor fabrication threatens component availability during geopolitical friction. Distribution runs through orthopedic implant vendor direct sales forces and specialized medical device distributors with ISO 13485 warehousing certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation obligations for Class IIa optical devices construct a cost-of-compliance moat that filters smaller competitors and entrenches incumbent positions through extended conformity assessment timelines.
For Market Incumbents: Deepen software-hardware bundling to lock prosthetic design workflows into recurring revenue streams. Expand backward integration into CMOS sensor supply partnerships to mitigate Taiwanese foundry concentration risk. Invest in AI-integrated point cloud processing capabilities before emerging entrants achieve clinical validation. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass entrenched implant vendor relationships in underpenetrated Brazilian and Indian pediatric orthopedic markets. Target children's hospitals lacking dedicated scanning protocols for growing-limb prosthetics. Pursue METI subsidy qualification in Japan to gain price advantage in public tenders. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric scanner specialists with established FDA 510(k) clearances in the United States and EU MDR technical files in progress. Long-term viability hinges on reimbursement strategy execution as CMS coverage decisions determine clinic-level adoption acceleration. Monitor FDA predicate device claim rejections as inflection indicators for regulatory pathway congestion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited substantial equivalence claims compress review timelines for predicate-based optical scanning submissions. |
| EU MDR Technical Documentation | Class IIa device conformity assessments extend timelines and filter smaller suppliers from procurement pools. |
| Hospital System Partnership | Integrated surgical planning contracts bundle imaging, scanning, and implant supply across three to five national networks. |
| Software Companion Development | AI-integrated point cloud processing automates anatomical landmark detection and reduces CAD preprocessing labor. |
| Reimbursement Strategy | CMS coding for digitized surgical planning determines whether clinic adoption accelerates beyond cash-pay segments. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings on scanner adoption patterns. Primary interviews with biomedical engineers, hospital purchasing committees, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body records, and METI subsidy program disclosures. Bottom-up shipment estimates triangulate against top-down capital expenditure surveys across United States, German, and Japanese health systems.
Comparable-period anchoring to historical replacement cycles for diagnostic imaging equipment calibrated the projection horizon across the analysis window. Segmentation modeling spans hardware form factor, optical technology tier, clinical application, and end-user facility type. CAGRs derive from installed base growth rates correlated with revision surgery volume projections and prosthetics digitization mandate diffusion curves. Forecast inputs incorporate CMOS sensor supply constraints and notified body capacity bottlenecks.
The model holds under stable regulatory clearance timelines and reimbursement coverage expansion; deviation in FDA predicate device claim rejections or EU MDR notified body backlogs would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Orthopaedic Cushions Market