
 Medical Traction Devices Market | 2026-2036
Medical Traction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Traction Devices Market Outlook
A shift from single-source component supply to multi-source procurement is repositioning how manufacturers secure electromechanical assemblies for traction platforms. DJO LLC leverages its rehabilitation equipment heritage to sustain broad hospital channel access across North America. Zimmer Biomet anchors its position through orthopedic system integration, while Dynatronics competes on specialized physical therapy distribution.
Medical traction devices apply controlled distractive force to the spine or skeletal structures through motorized, hydraulic, or manual mechanisms, typically delivering 20-150 pounds of pull force with adjustable angle and duration parameters to relieve nerve compression or stabilize fractures. Electrical traction devices command premium placement in hospital settings due to programmable precision and patient monitoring integration, whereas manual traction equipment retains cost-sensitive demand in home care settings where caregiver supervision substitutes for automation. Spinal disorder applications generate the deepest margin pools as chronic disc pathology drives recurring clinical visits, while sports injury traction sits at the fastest-growing edge as athletic medicine programs professionalize recovery protocols.
FDA 510(k) premarket notification requirements and ISO 13485 medical device quality management systems govern product commercialization in the United States and European markets respectively, with both frameworks elevating barrier costs for new entrants seeking clinical validation. Japan's PMDA enforces equivalent stringent review timelines that shape regional launch sequencing for manufacturers. Stakeholders must monitor evolving MDR clinical evidence requirements in Europe and the trajectory of CMS reimbursement coding for traction therapy as these forces determine viable market access pathways.
Market Dynamics
Electrical traction systems are displacing manual and hydraulic alternatives across hospital rehabilitation departments as orthopedic clinics pursue programmable precision and EMR-integrated patient monitoring workflows.
Growth Catalysts
- FDA 510(k) Pre-market Notification:The streamlined clearance pathway accelerates time-to-revenue for electromechanical traction platforms targeting post-surgical rehabilitation protocols in United States hospital systems.
- ISO 13485 Quality Management Systems:Certification mandates across European markets elevate barrier costs for marginal competitors, consolidating shelf access for validated manufacturers in Germany and France.
- Aging Demographics in Japan:METI-supported geriatric care infrastructure investments drive sustained procurement of non-invasive spinal decompression equipment in Tokyo and Osaka metropolitan clinical networks.
Market Restraints
- Electromechanical Component Supply Concentration:Precision motor and sensor sourcing concentrates among East Asian contract manufacturers, exposing OEMs to logistics volatility and tariff exposure.
- Reimbursement Coding Uncertainty:CMS traction therapy coding revisions in the United States create revenue recognition delays for capital equipment deployed in outpatient settings.
- Manual Traction Cost Floor:Home-care caregiver-supervised alternatives cap pricing elasticity for automated systems in price-sensitive patient segments.
Strategic Opportunities
- Sports Medicine Program Expansion:Athletic recovery professionalization at university and professional team facilities in Germany creates demand for portable traction units with rapid setup protocols.
- Japan PMDA Harmonization Initiatives:Streamlined review timelines for devices with prior FDA clearance reduce duplicate clinical validation costs for manufacturers entering Japanese distribution.
- Telehealth-Integrated Remote Monitoring:Convergence of traction device telemetry with cloud-based physical therapy platforms enables subscription revenue models beyond equipment sale margins.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Electromechanical system design expertise for medical device applications concentrates among a narrow pool of specialists in Boston and Stuttgart metropolitan clusters.
- Legacy System Integration Complexity:Hospital IT departments face middleware development burdens when connecting new traction platforms to entrenched EMR architectures from dominant health record vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Traction Devices Market |
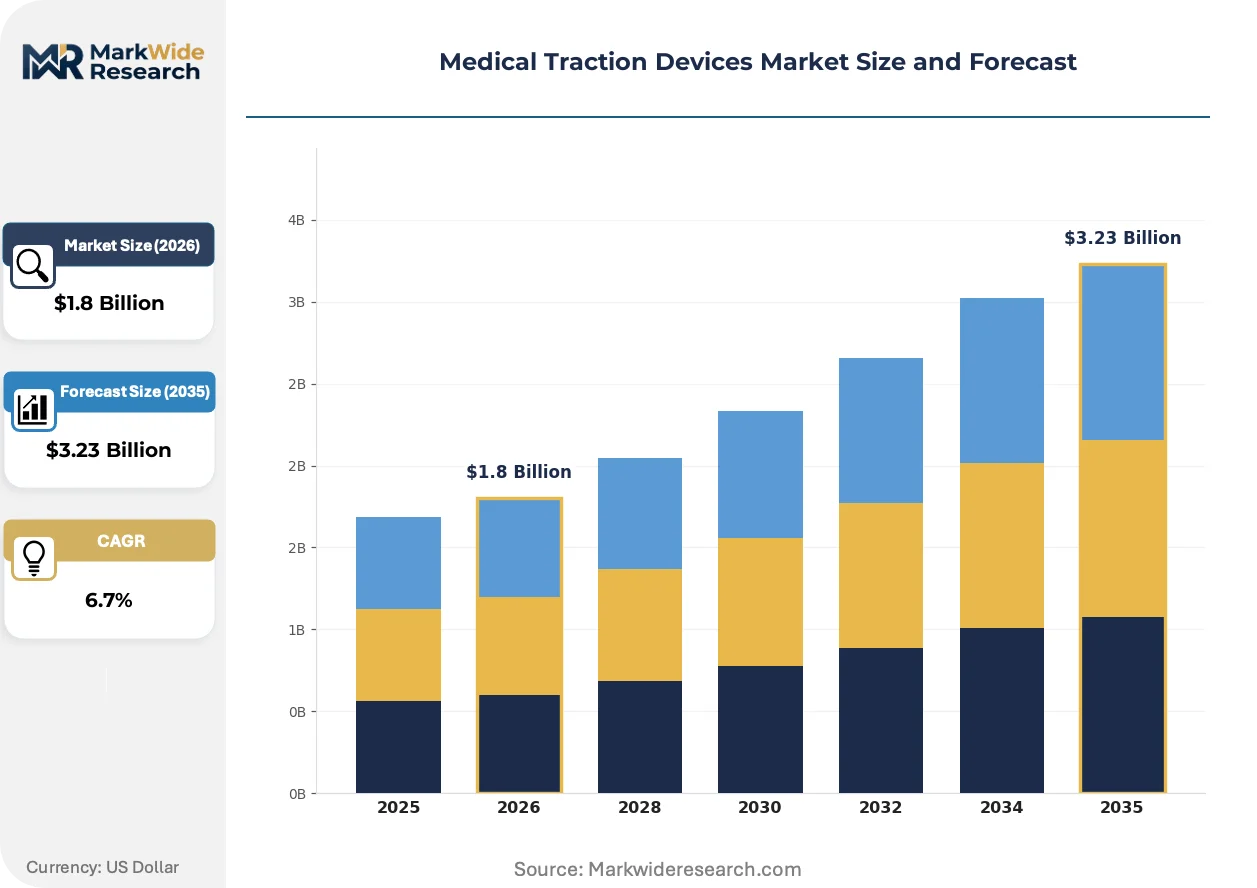
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Traction Devices, Electrical Traction Devices, Suspension Traction Systems, Skin Traction Equipment End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Settings Application: Spinal Disorders, Fracture Management, Post-Surgical Rehabilitation, Sports Injuries Technology: Electronic Traction Systems, Hydraulic Systems, Pneumatic Devices, Manual Mechanisms |
| Companies Covered | CERT Health Sciences, Zimmer Biomet, DJO LLC, ISI, PMT Corporation, BTL, Dynatronics, Orthofix, Vax-D Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Traction Devices Market Strategic Shifts
Programmable automation and connected health architectures are redefining competitive differentiation in traction device manufacturing, compressing margins for purely mechanical alternatives while opening service-layer revenue streams.
Variable-angle motorized traction platforms with real-time force feedback sensors are expanding into hospital-based rehabilitation departments as orthopedic surgeons demand precise distraction parameters for post-laminectomy protocols. Academic medical centers in the United States and university hospitals in Germany are standardizing these configurations for spinal decompression workflows. The technology is expanding into previously manual-dominated segments by substituting automation for specialized physical therapist labor.
Europe's Medical Device Regulation (MDR) clinical evidence requirements are intensifying post-market surveillance obligations for traction device manufacturers seeking CE marking renewal. The framework mandates periodic safety and performance reporting that elevates ongoing regulatory compliance costs above legacy Medical Device Directive levels. Spinal disorder application segments face the steepest documentation burdens due to direct patient contact and sustained force application risks.
Hospital procurement committees are consolidating vendor relationships around full-service rehabilitation equipment portfolios rather than standalone traction unit acquisitions. Integrated sourcing agreements with DJO LLC and Zimmer Biomet are displacing single-product distributors in North American health system purchasing. This concentration is most visible in United States integrated delivery networks where standardization across multiple facilities drives volume-based contracting leverage.
Medical Traction Devices Market Segmentation
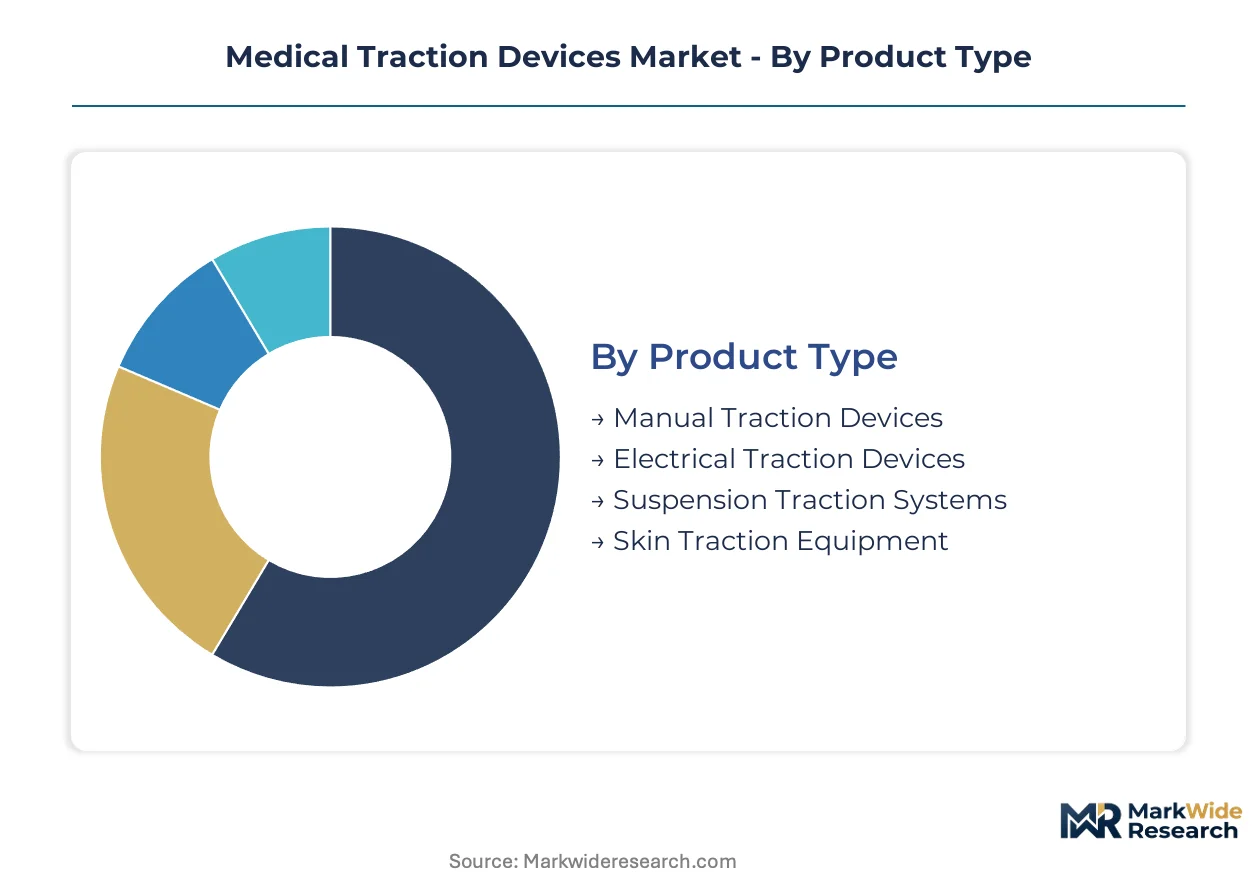
Traction device procurement patterns diverge sharply across care settings, with capital-intensive hospitals favoring programmable systems while home care segments prioritize cost containment over automation. Understanding these segment boundaries enables manufacturers to align R&D investment with margin profiles and replacement cycle timing.
Product Type:
Replacement cycles accelerate as orthopedic clinics retire hydraulic platforms for electronic alternatives with EMR integration capabilities.
- Electrical Traction Devices:Motorized platforms deliver 20-150 pounds of programmable pull force with real-time feedback sensors. Demand concentrates in United States academic medical centers where post-laminectomy rehabilitation protocols require precise distraction parameters and automated documentation.
- Manual Traction Devices:Caregiver-operated systems rely on pulley configurations and weight stacks without electromechanical components. These retain cost-sensitive demand in United States home care segments where Medicare reimbursement constraints cap equipment budgets and family supervision substitutes for automation.
- Suspension Traction Systems:Overhead-mounted frameworks for long-term immobilization in German trauma wards.
- Skin Traction Equipment:Adhesive-based systems for pediatric fracture management in Japanese geriatric care networks.
Electrical Traction Devices sits at the top of the volume ranking, with Suspension Traction Systems climbing the fastest as European trauma centers modernize infrastructure.
End User:
Customer procurement authority determines pricing elasticity, with integrated delivery networks extracting volume discounts unavailable to independent clinics.
- Hospitals:Inpatient rehabilitation departments command capital equipment budgets exceeding outpatient facilities. United States health systems in Texas and California standardize on full-service vendor contracts that bundle traction platforms with continuous passive motion devices and patient monitoring integration.
- Orthopedic Clinics:Specialized practices prioritize rapid-setup portable units for high-throughput spinal decompression workflows. German outpatient surgical centers in Bavaria and North Rhine-Westphalia drive demand for compact electromechanical systems that fit within leased clinical space constraints.
- Rehabilitation Centers:Physical therapy-focused facilities in Japan's Osaka metropolitan area favor multi-modality equipment configurations.
- Home Care Settings:United States Medicare Part B reimbursement limitations restrict automated system adoption to manual alternatives supervised by family caregivers.
Hospitals capture the dominant revenue share, though Orthopedic Clinics expand most quickly as ambulatory surgical center construction accelerates across Germany and the United States.
Application:
Clinical outcome documentation requirements intensify for segments involving sustained patient contact and force application risks.
- Spinal Disorders:Chronic disc pathology and nerve compression cases generate recurring clinical visits with documented decompression protocols. United States pain management clinics in Florida and Arizona deploy variable-angle motorized platforms for non-surgical intervention before surgical referral.
- Sports Injuries:Athletic medicine programs at German Bundesliga training facilities and United States university athletic departments professionalize recovery protocols. Portable traction units with rapid setup capabilities serve sideline and locker room deployment scenarios where treatment windows compress competitive return timelines.
- Fracture Management:Japanese trauma centers in Tokyo apply skin and skeletal traction for pre-operative stabilization.
- Post-Surgical Rehabilitation:United States hospital outpatient departments coordinate traction therapy with physical therapy billing codes.
Spinal Disorders anchors segment revenue, while Sports Injuries gains share fastest as professional athletic investment in recovery infrastructure expands across German and United States markets.
Technology:
Component sourcing concentration in East Asian contract manufacturers shapes technology migration timelines and tariff exposure profiles.
- Electronic Traction Systems:Microprocessor-controlled platforms integrate force sensors, programmable angle adjustment, and telemetry output for EMR documentation. United States hospital procurement committees prioritize these configurations for orthopedic service line accreditation requirements.
- Manual Mechanisms:Pulley, weight stack, and crank systems without electrical components dominate price-sensitive segments. Japanese home care distributors bundle these with training protocols for family caregiver administration in rural prefectures outside metropolitan clinical networks.
- Hydraulic Systems:Fluid-pressure platforms retain installed base in older German rehabilitation hospitals with extended depreciation schedules.
- Pneumatic Devices:Compressed-air alternatives serve specific traction applications in French physical therapy clinics.
Electronic Traction Systems leads technology deployment, with Pneumatic Devices expanding most quickly as French clinics seek alternatives to hydraulic maintenance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement networks anchor demand concentration for programmable traction platforms, with academic medical centers in Texas and California driving standardization of EMR-integrated rehabilitation workflows.
United States
FDA 510(k) clearance pathways accelerate commercialization timelines for electromechanical traction systems targeting post-surgical rehabilitation. Integrated delivery networks in Texas and California extract volume discounts through bundled vendor contracts spanning multiple facilities. Hospital procurement committees prioritize full-service rehabilitation equipment portfolios over standalone traction acquisitions.
Germany
Ambulatory surgical center construction across Bavaria and North Rhine-Westphalia expands demand for compact electromechanical systems fitting leased clinical constraints. MDR clinical evidence requirements intensify post-market surveillance obligations above legacy Medical Device Directive levels. University hospitals in Heidelberg and Munich standardize variable-angle motorized configurations for spinal decompression protocols.
Japan
METI-supported geriatric care infrastructure investments sustain procurement of non-invasive spinal decompression equipment in Tokyo and Osaka metropolitan networks. PMDA review timelines shape regional launch sequencing for manufacturers entering Japanese distribution. Trauma centers in Tokyo apply skin traction systems for pre-operative stabilization in aging patient populations.
United Kingdom
NHS procurement frameworks consolidate vendor relationships around rehabilitation equipment portfolios with service-layer attachments. MHRA post-Brexit regulatory autonomy maintains alignment with MDR evidence standards while streamlining UK-specific conformity assessments. London teaching hospitals pilot telemetry-integrated traction platforms for cloud-based physical therapy coordination.
France
Physical therapy clinics in Île-de-France and Provence-Alpes-Côte d'Azur seek pneumatic alternatives to hydraulic maintenance requirements. ANSM market surveillance obligations parallel MDR intensification across European markets. Rehabilitation hospitals in Lyon and Marseille modernize infrastructure toward electronic traction migration from legacy hydraulic installed bases.
Medical Traction Devices Market Competitive Environment
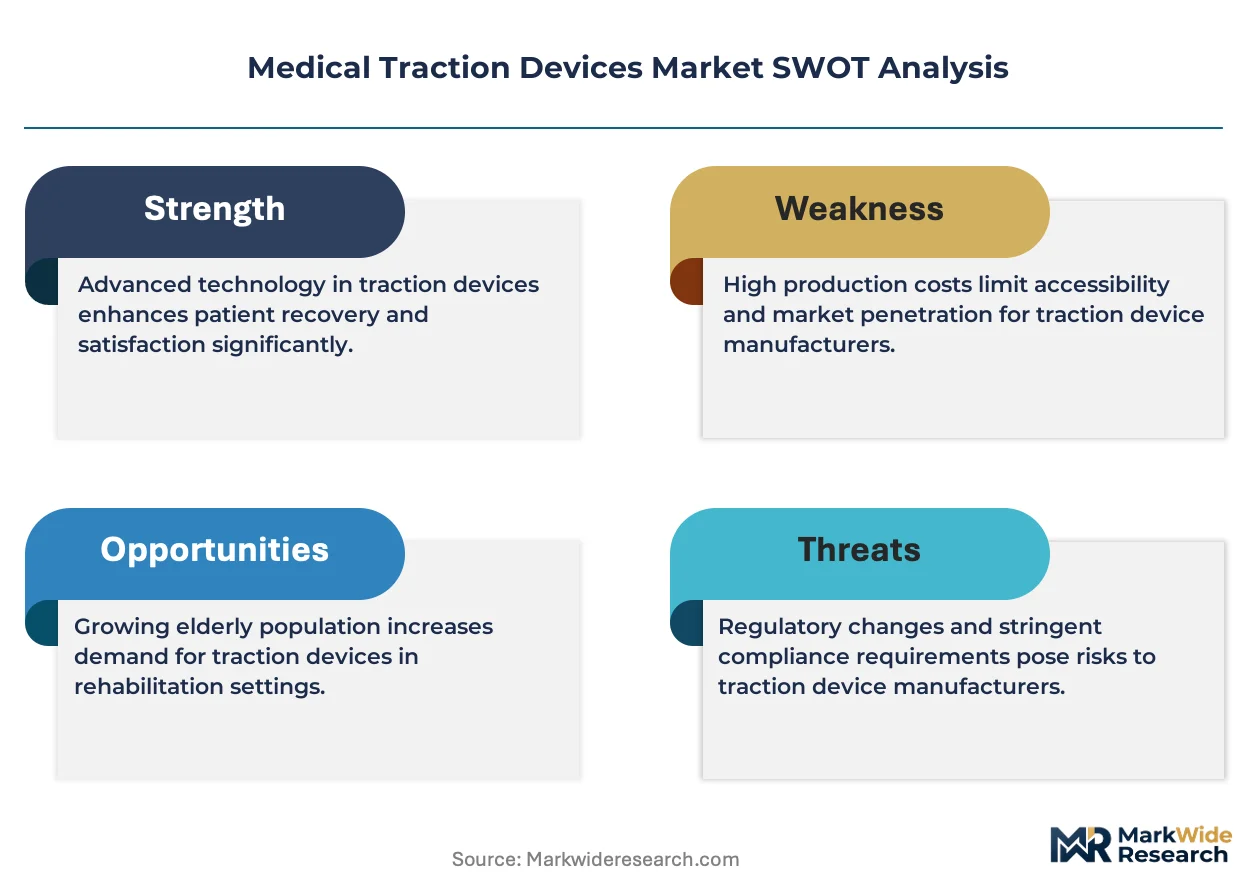
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated service models. The vendor base stratifies across three maturity tiers: diversified orthopedic conglomerates with rehabilitation portfolios, specialized physical therapy equipment fabricators, and component-assembly contract manufacturers. Competitive positioning hinges on FDA clearance velocity, ISO 13485 certification maintenance, and integrated delivery network contract penetration. Dominant competitive moves include portfolio diversification into full-service rehabilitation platforms and strategic partnerships with East Asian electromechanical component suppliers.
Within the diversified orthopedic tier, Zimmer Biomet and DJO LLC exemplify scale-driven positioning through broad hospital channel access and rehabilitation equipment heritage respectively. Dynatronics occupies a specialist position focused on physical therapy distribution networks. CERT Health Sciences and BTL represent European-origin competitors navigating MDR compliance intensification. ISI, PMT Corporation, Orthofix, and Vax-D Medical Technologies anchor the mid-tier specialist segment where niche application focus substitutes for portfolio breadth.
| Leading Market Players |
|---|
| CERT Health Sciences |
| Zimmer Biomet |
| DJO LLC |
| ISI |
| PMT Corporation |
| BTL |
| Dynatronics |
| Orthofix |
| Vax-D Medical Technologies |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum commodity indices from the London Metal Exchange cascade through electromechanical component fabrication into three-tier pricing structures across premium, standard, and economy levels for traction device OEMs. Precision motor housings and sensor enclosures absorb base metal volatility, compressing margins for mid-tier manufacturers while validated suppliers pass through certification-grade premiums to hospital procurement committees.
Pricing Analysis
Input-cost pass-through from East Asian contract manufacturers concentrates pricing power among ISO 13485-certified suppliers serving United States academic medical centers. FDA 510(k) clearance tier and EMR integration capability separate premium configurations from standard electromechanical platforms, while manual traction alternatives anchor economy pricing for Medicare-constrained home care segments. Cost compression in standard-tier motorized systems is intensifying because hospital procurement committees extract volume discounts through integrated delivery network contracts. Orthopedic clinics demonstrate least price sensitivity due to reimbursement code alignment, whereas home care distributors face maximum budget pressure from Medicare Part B equipment caps.
Supply Chain Analysis
Biomedical engineering talent scarcity in Boston and Stuttgart metropolitan clusters constrains electromechanical system design capacity for medical device applications. Precision motor and sensor sourcing concentrates among contract manufacturers in China, South Korea, and Taiwan, drawing from rare earth magnet supply chains and semiconductor foundry output. Single-source vulnerability in torque sensor procurement exposes OEMs to logistics volatility and tariff exposure. Distribution runs through specialized physical therapy equipment distributors in North America and hospital procurement frameworks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA 510(k) clearance velocity and MDR clinical evidence intensification create accelerating barriers to shelf access. The convergence of reimbursement coding revisions with ISO 13485 certification maintenance elevates capital requirements for sustained participation.
For Market Incumbents: Anticipate telehealth-integrated traction platforms disrupting standalone equipment margins by accelerating software companion development and cloud-based physical therapy platform partnerships. Defensive consolidation moves should prioritize backward integration into precision sensor supply chains and captive certification consulting capabilities to accelerate FDA submission timelines for portfolio extensions. Hospital system partnership density in Texas and California integrated delivery networks remains the critical lever for volume retention.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in motorized traction platforms creates white-space opportunity for mid-tier configurations with programmable precision minus full EMR integration. Portable electromechanical units for German sports medicine programs and Japanese geriatric care networks represent the most penetrable segments given ambulatory construction acceleration and METI infrastructure investment. A reimbursement strategy-first go-to-market angle, targeting CMS coding alignment before product launch, differentiates capital-efficient entrants from hardware-focused competitors.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized physical therapy equipment fabricators possessing ISO 13485 certification and established German or Japanese distribution channels. Long-term viability across the analysis window hinges on regulatory navigation capability rather than manufacturing scale alone. Acquisition target archetypes should emphasize firms with cleared FDA 510(k) portfolios and embedded hospital procurement relationships. The signal to watch as inflection indicator is CMS traction therapy coding revision adoption velocity in United States outpatient settings.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance pathways compress time-to-revenue for electromechanical platforms targeting post-surgical rehabilitation protocols. |
| CE Marking Pathway Investment | MDR clinical evidence preparation elevates barrier costs and consolidates shelf access for validated European manufacturers. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and California standardize procurement across multi-facility rehabilitation service lines. |
| Software Companion Development | Telemetry integration with cloud-based physical therapy platforms enables subscription revenue models beyond equipment sale margins. |
| Reimbursement Strategy Alignment | CMS coding optimization determines viable market access pathways for outpatient traction therapy deployment scenarios. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, ISO 13485 certification registries, and hospital procurement databases; plus customs trade data for electromechanical component flows — were reconciled through bottom-up and top-down triangulation. Clinician input on post-laminectomy rehabilitation protocols and physical therapy workflow integration informed demand-side assumptions.
Cross-referencing historical shipment patterns against expert panel input on orthopedic clinic expansion and ambulatory surgical center construction shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and technology tier alongside regional regulatory cluster variations. CAGRs were derived from installed base replacement cycles and penetration rate assumptions for electronic traction migration from manual alternatives.
Caveats apply where CMS reimbursement coding revisions, MDR clinical evidence requirement intensification, or East Asian component supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory clearance velocity and hospital capital equipment budget trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Intramedullary Nails Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Hip Reconstruction Devices Market