
 Osteoporosis Testing Market | 2026-2036
Osteoporosis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Osteoporosis Testing Market Outlook
The capital-intensity divergence between installed-base leaders and point-of-care entrants is bifurcating competitive strategy across the osteoporosis testing landscape. Hologic, Inc. leverages its captive DXA manufacturing footprint to sustain premium positioning in hospital radiology departments. Siemens Healthineers anchors European demand through integrated imaging workflows that bundle bone density with broader musculoskeletal protocols. BeamMed Ltd competes on portable ultrasound systems that target clinic-based screening outside traditional hospital capital budgets.
Osteoporosis testing encompasses quantitative assessment of bone mineral density and microarchitectural integrity through ionizing radiation, acoustic impedance, or biochemical serum markers, with DXA remaining the clinical reference standard at 0.5-1.0% precision error for lumbar spine and femoral neck measurement. The technology dimension shows bone density scanners commanding the majority of installed value while wearable devices represent the fastest-expanding frontier for remote monitoring applications. Diagnostic labs extract superior margins from biochemical marker panels that enable fracture risk stratification beyond static density readings, whereas home care penetration remains constrained by reimbursement complexity and operator training requirements.
The FDA maintains 510(k) premarket notification requirements for bone densitometry systems under radiological health regulations, while the EU Medical Device Regulation imposes stricter clinical evidence standards for DXA and CT-based devices entering European markets. Japan's PMDA and METI coordinate reimbursement pricing with preventive screening guidelines that expand eligible patient populations for bone density assessment. Stakeholders must monitor evolving CMS coverage determinations for trabecular bone score add-on reimbursement and wearable-derived biomarker validation studies that could reshape competitive boundaries between centralized imaging and distributed screening models.
Market Dynamics
Hospital radiology departments are consolidating purchasing power around integrated imaging platforms while ambulatory clinics pursue decentralized screening models, creating divergent capital deployment strategies across the osteoporosis testing value chain.
Growth Catalysts
- Preventive screening mandates:Japan's METI reimbursement policies expand eligible populations for bone density assessment, accelerating preventive care adoption among aging demographics.
- DXA precision improvements:Advances in dual-energy X-ray absorptiometry achieve sub-one-percent measurement error for lumbar spine and femoral neck assessment, reinforcing clinical confidence in diagnostic outcomes.
- Ambulatory clinic expansion:Primary care networks in Germany and France deploy portable ultrasound systems to extend screening access beyond hospital radiology departments.
Market Restraints
- Reimbursement complexity:CMS coverage determinations for trabecular bone score add-ons remain inconsistent across Medicare Administrative Contractors, creating payment uncertainty for advanced diagnostics.
- Supply concentration in detectors:Solid-state detector manufacturing concentrates among Japanese and German component suppliers, exposing device makers to single-source risk.
- Operator training requirements:DXA precision depends on certified technologist positioning protocols that limit deployment in resource-constrained settings.
Strategic Opportunities
- Remote monitoring convergence:Wearable accelerometers paired with smartphone-based fracture risk algorithms enable continuous bone health tracking outside clinical settings.
- Biochemical panel expansion:Diagnostic laboratories in South Korea and Australia commercialize serum marker combinations that stratify fracture risk beyond static density measurements.
- Point-of-care channel development:Pharmacy-based screening kiosks in the United Kingdom leverage retail foot traffic to capture previously unscreened at-risk populations.
Industry Challenges
- Integration complexity:Point-of-care ultrasound devices face interoperability barriers with hospital PACS networks and electronic health record systems.
- Certification timeline compression:EU Medical Device Regulation clinical evidence requirements extend DXA device approval cycles by twelve to eighteen months compared to prior directives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteoporosis Testing Market |
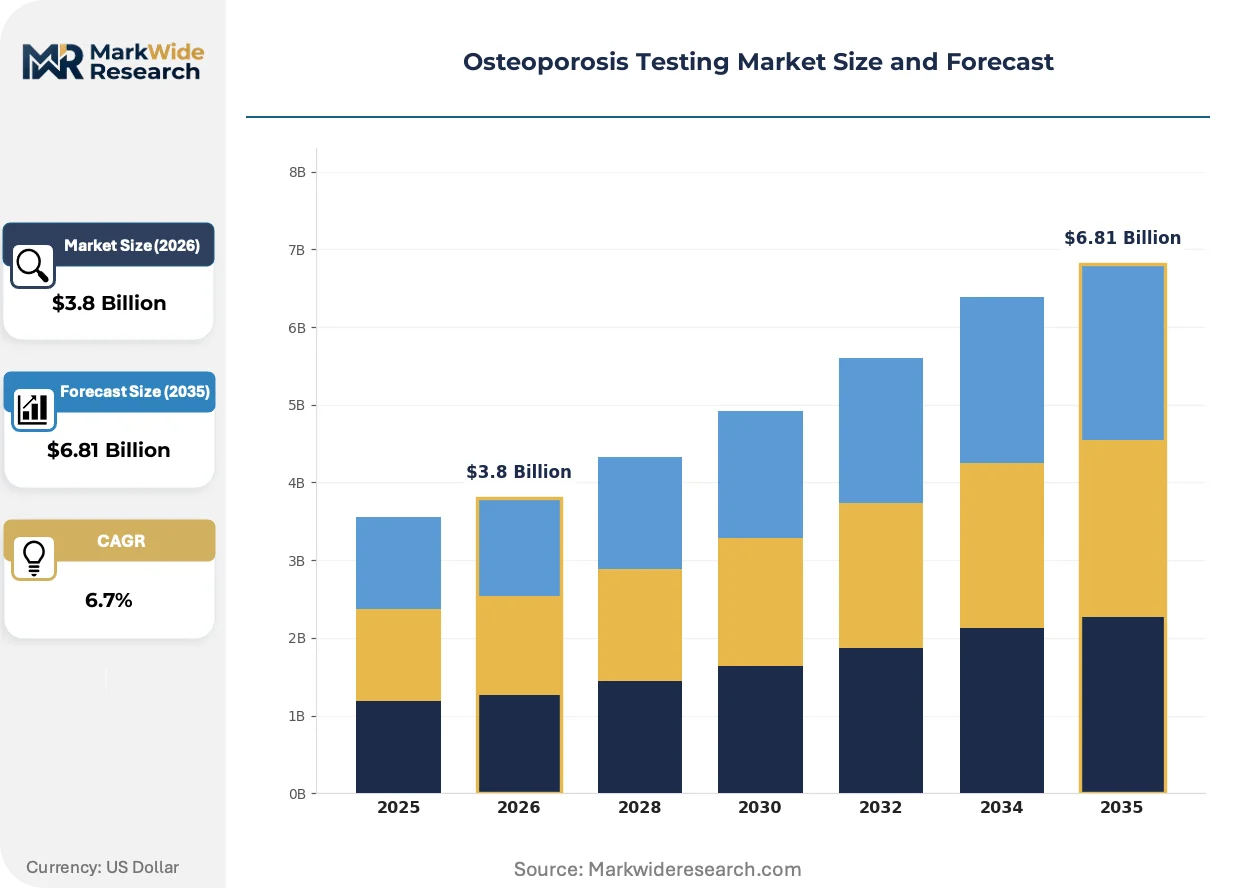
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: DXA, Ultrasound, CT Scan, Biochemical Markers End User: Clinics, Hospitals, Home Care, Diagnostic Labs Application: Screening, Diagnosis, Monitoring, Research Technology: Bone Density Scanners, Imaging Devices, Software Solutions, Wearable Devices |
| Companies Covered | Hologic, Inc., GE Healthcare, Siemens Healthineers, Medtronic, OsteoSys Corp., BeamMed Ltd, Swissray, DMS Imaging, Eurobio Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteoporosis Testing Market Strategic Shifts
Diagnostic workflows are bifurcating between high-throughput hospital systems and distributed screening networks, with technology vendors recalibrating hardware architectures and service models to serve divergent deployment contexts.
Quantitative ultrasound technology is fragmenting the traditional DXA monopoly in osteoporosis screening. Portable systems measuring calcaneal broadband ultrasound attenuation and speed of sound now target primary care clinics and mobile health units. Community health centers in Spain and Italy adopt these devices to triage patients for confirmatory DXA referral, compressing the addressable market for centralized densitometry.
The EU Medical Device Regulation imposes stricter clinical performance documentation for bone densitometry systems entering European markets. Manufacturers must generate prospective validation data rather than relying on predicate device equivalence. Small and mid-sized device developers face disproportionate compliance burdens, advantaging established players with dedicated regulatory affairs infrastructure.
Hospital procurement committees now unbundle after-sales service contracts from hardware acquisitions, pressuring vendors to demonstrate discrete value for maintenance, software updates, and remote technical support. Radiology departments in the Netherlands and Sweden negotiate multi-year service agreements separately from capital purchases, compressing vendor margins on recurring revenue streams.
Osteoporosis Testing Market Segmentation
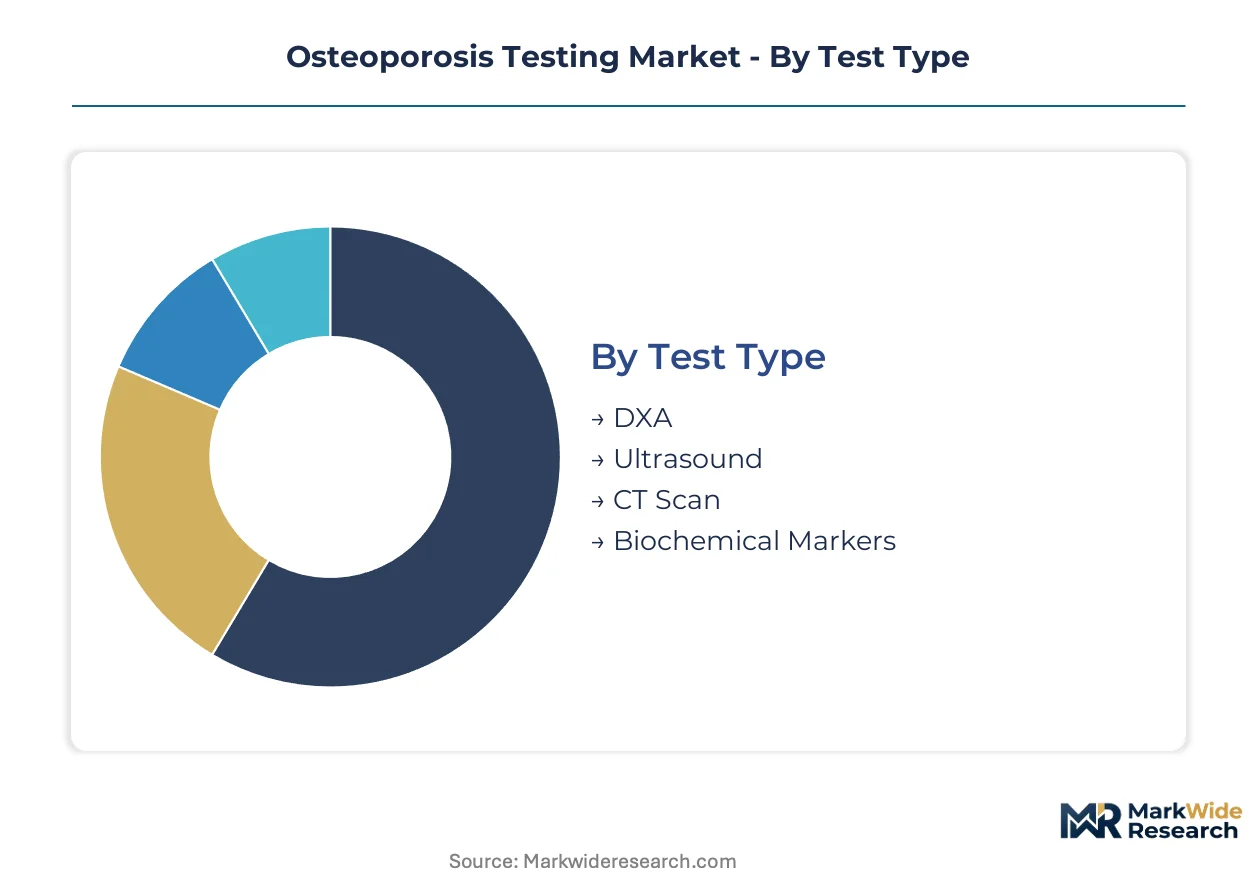
Technology substitution pressures and reimbursement fragmentation create divergent growth trajectories across osteoporosis testing segments. Understanding where portable alternatives displace centralized systems versus where reference-standard methods defend their position enables precise resource allocation for device manufacturers and diagnostic service providers.
Test Type:
Quantitative ultrasound and biochemical alternatives exert the strongest substitution pressure on ionizing-radiation modalities, particularly in primary care and ambulatory settings where capital constraints limit DXA deployment.
- DXA:Dual-energy X-ray absorptiometry delivers the clinical reference standard for lumbar spine and femoral neck bone mineral density quantification with sub-one-percent precision error. Hospital radiology departments in Japan and Germany anchor installed-base demand through integrated imaging workflows and favorable METI reimbursement codes for preventive screening.
- Ultrasound:Portable systems measuring calcaneal broadband ultrasound attenuation and speed of sound enable point-of-care screening without radiation exposure. Primary care networks in Spain and Italy deploy these devices to triage patients for confirmatory DXA referral, compressing addressable volume for centralized densitometry.
- CT Scan:Quantitative computed tomography provides three-dimensional trabecular bone assessment with superior spatial resolution for research applications and complex fracture risk stratification.
- Biochemical Markers:Serum-based panels measuring bone turnover indicators enable dynamic fracture risk assessment beyond static density snapshots, with diagnostic laboratories in South Korea and Australia commercializing expanded test menus.
DXA retains volume leadership; biochemical markers hold the steepest expansion curve.
End User:
Capital deployment patterns bifurcate between consolidated hospital procurement and distributed clinic networks, with reimbursement complexity determining feasible channel economics for each testing modality.
- Clinics:Primary care and specialty clinics drive portable ultrasound adoption through lower capital thresholds and flexible staffing models. Germany's Hausarzt networks and France's cabinet médicaux extend screening access beyond hospital radiology departments.
- Hospitals:Academic medical centers and community hospital systems concentrate DXA purchasing power around integrated imaging platforms with bundled musculoskeletal protocols. Radiology departments in the Netherlands negotiate unbundled service contracts separately from hardware acquisitions.
- Home Care:Wearable accelerometers and smartphone-based fracture risk algorithms target remote monitoring applications, though CMS coverage determinations and operator training requirements constrain penetration.
- Diagnostic Labs:Centralized laboratories extract superior margins from biochemical marker panels through automated high-throughput processing and proprietary risk stratification algorithms.
Hospitals command installed value concentration; clinics gain share fastest through ambulatory expansion.
Application:
Reimbursement incentives and clinical evidence standards create tiered margin structures across the care continuum, from population-wide screening to specialized research protocols.
- Screening:Preventive bone health assessment targets asymptomatic at-risk populations, with Japan's METI policies expanding eligible demographics through favorable reimbursement pricing.
- Diagnosis:Confirmatory testing following fragility fracture or clinical suspicion demands reference-standard DXA precision for treatment initiation decisions.
- Monitoring:Serial assessment tracks bone density response to pharmacologic intervention, requiring consistent measurement protocols and longitudinal data management.
- Research:Clinical trials and epidemiological studies employ advanced imaging biomarkers and biochemical panels to validate novel therapeutic mechanisms.
Diagnosis captures revenue concentration; screening climbs the fastest on preventive policy tailwinds.
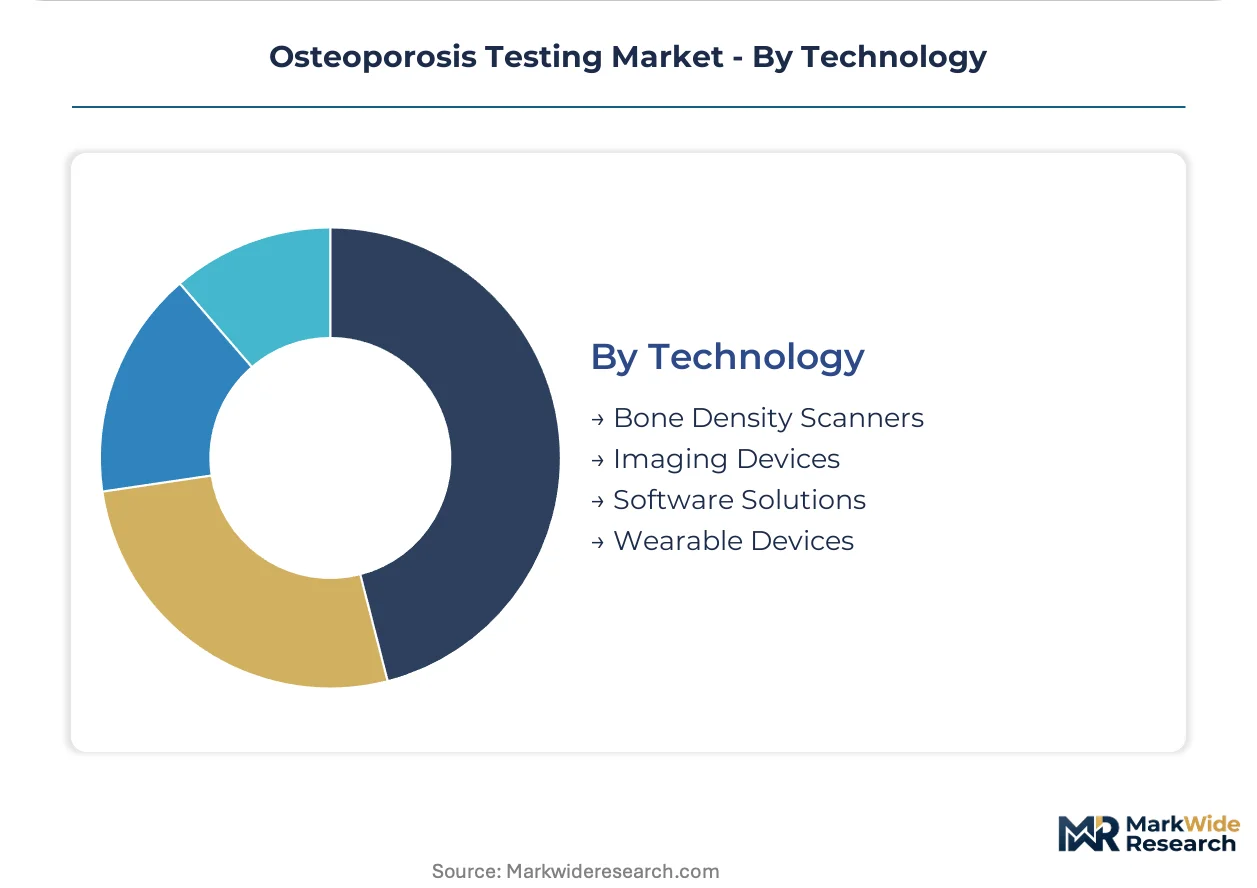
Technology:
Hardware-software integration intensity and data connectivity requirements differentiate competitive positioning across device architectures serving centralized versus distributed deployment contexts.
- Bone Density Scanners:DXA and quantitative CT systems anchor hospital radiology department capital budgets with high unit values and extended depreciation schedules.
- Imaging Devices:Portable ultrasound and peripheral densitometry systems target clinic-based screening with lower price points and reduced facility infrastructure demands.
- Software Solutions:Image analysis platforms, fracture risk algorithms, and electronic health record integration modules extract recurring revenue through subscription and per-test licensing models.
- Wearable Devices:Accelerometer-based monitors and smartphone-connected sensors enable continuous bone health tracking outside clinical settings, though validation studies and regulatory clearance timelines limit near-term commercialization.
Bone density scanners defend installed value leadership; wearables trace the steepest trajectory pending reimbursement validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's preventive screening corridors while reimbursement fragmentation compresses margins across Southern European ambulatory networks. Hospital procurement committees in Germany and the Netherlands negotiate unbundled service contracts that separate hardware from recurring revenue streams. Regulatory divergence between FDA 510(k) pathways and EU MDR clinical evidence requirements creates twelve-to-eighteen-month approval asymmetries that reshape competitive entry sequencing.
United States
Hospital radiology departments anchor DXA installed-base demand through integrated imaging platforms bundled with broader musculoskeletal protocols. FDA maintains 510(k) premarket notification requirements for bone densitometry systems under radiological health regulations, accelerating commercialization timelines relative to European counterparts. Academic medical centers in Boston and the Mayo Clinic corridor concentrate research applications employing advanced trabecular bone score algorithms.
Japan
METI reimbursement policies expand eligible populations for preventive bone density assessment among aging demographics, creating the world's most favorable screening economics. PMDA coordinates with METI to align device approval timelines with reimbursement pricing determinations. Tokyo and Osaka metropolitan areas concentrate hospital radiology department purchasing power around integrated DXA platforms.
Germany
Hausarzt primary care networks deploy portable ultrasound systems to extend screening access beyond hospital radiology departments, fragmenting traditional DXA volume concentration. EU Medical Device Regulation imposes stricter clinical evidence standards that extend device approval cycles compared to prior directives. Bavaria and North Rhine-Westphalia anchor diagnostic imaging manufacturing clusters serving Central European demand.
South Korea
Diagnostic laboratories commercialize serum marker combinations that stratify fracture risk beyond static density measurements, capturing superior margins through automated high-throughput processing. MFDS regulates in vitro diagnostic devices under consolidated medical device frameworks. Seoul Capital Area concentrates laboratory infrastructure and hospital procurement committee decision-making for advanced biochemical panels.
Australia
Diagnostic laboratories leverage geographic isolation to develop proprietary fracture risk stratification algorithms for biochemical marker panels. TGA maintains alignment with EU MDR standards while streamlining approval pathways for devices with prior European clearance. Sydney and Melbourne anchor hospital radiology department consolidation and primary care network expansion for ambulatory screening models.
Osteoporosis Testing Market Competitive Environment
Concentration sits with diversified imaging conglomerates that leverage integrated platform portfolios to capture hospital radiology department procurement. The vendor base separates into three strategic tiers: installed-base leaders with captive manufacturing footprints, point-of-care entrants targeting ambulatory price sensitivity, and diagnostic laboratory specialists extracting margins from biochemical automation. Competitive dynamics center on M&A activity consolidating detector supply chains and strategic partnerships bridging hardware-software integration for electronic health record connectivity.
Within the installed-base leader tier, Hologic, Inc. and Siemens Healthineers occupy positions that exemplify divergent geographic anchoring strategies. Hologic represents North American-centric manufacturing scale applied to premium hospital radiology positioning. Siemens Healthineers anchors European demand through workflow integration bundling bone density with broader musculoskeletal imaging protocols. BeamMed Ltd sits within the point-of-care entrant archetype, exemplifying Israeli-based specialization in portable ultrasound systems targeting clinic-based screening outside traditional hospital capital budgets.
| Leading Market Players |
|---|
| Hologic, Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Medtronic |
| OsteoSys Corp. |
| BeamMed Ltd |
| Swissray |
| DMS Imaging |
| Eurobio Scientific |
| Others |
Value Chain & Pricing Dynamics
DXA manufacturing scale economies in the United States and Germany anchor price floors for hospital radiology systems while compressing margins for portable ultrasound entrants competing outside traditional capital budgets. Component concentration in solid-state detectors concentrates bargaining power among Japanese and German suppliers, forcing device makers to absorb cost volatility or pass through to ambulatory clinic buyers with thinner pricing tolerance.
Pricing Analysis
The customization-premium spread separates configured-to-order DXA platforms with integrated PACS connectivity from standard portable ultrasound units. Hospital radiology departments in Japan and Germany absorb premium pricing for workflow-integrated systems bundling bone density with musculoskeletal protocols. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service unbundling. Cost compression in the portable segment is intensifying as primary care networks in Spain and Italy demand lower capital thresholds. Ambulatory clinics exhibit highest price sensitivity; academic medical centers demonstrate lowest.
Supply Chain Analysis
Inventory lead times for solid-state detectors extend twelve to eighteen months under EU Medical Device Regulation documentation requirements. Manufacturing concentrates in Japan, Germany, and the United States for precision imaging components. Raw material dependencies include rare-earth phosphors for scintillation detectors, high-purity silicon for solid-state arrays, and specialized alloys for precision positioning systems. Single-source vulnerability in detector supply exposes device makers to geographic concentration risk. Distribution runs through hospital procurement committees for DXA systems and medical device distributors for portable ultrasound.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Osteoporosis testing sits in early-cycle expansion as preventive screening mandates in Japan and ambulatory clinic deployment in Germany accelerate penetration beyond hospital radiology departments.
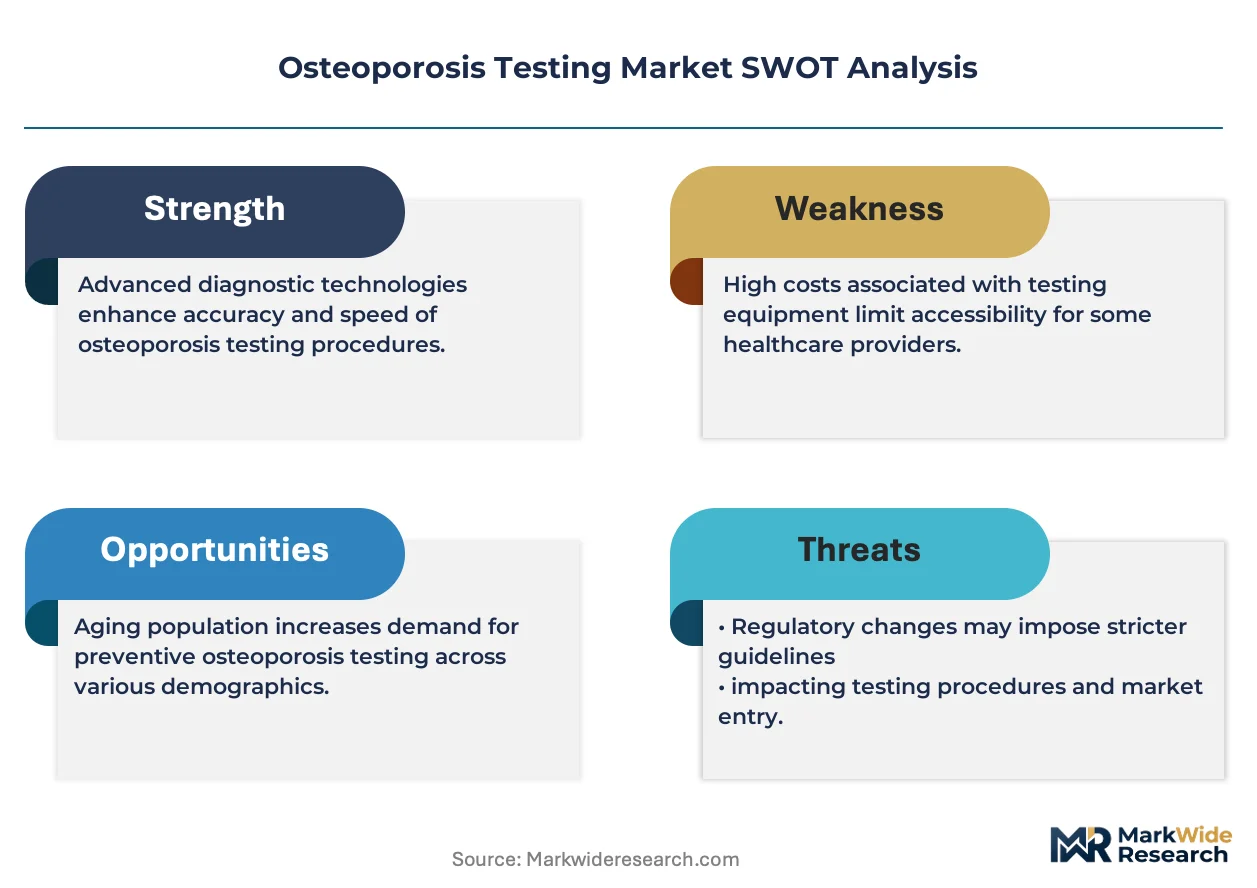
For Market Incumbents: Shield installed-base revenue by deepening captive manufacturing of solid-state detectors and securing multi-year service contracts with hospital procurement committees in the Netherlands and Sweden. Quantitative ultrasound substitution in primary care networks threatens volume concentration; vertical integration into detector production reduces single-source exposure. For New Entrants and Emerging Players: Software companion gaps for electronic health record integration and remote monitoring data management present white-space opportunities. Pharmacy-based screening kiosks in the United Kingdom and wearable accelerometer validation studies offer the most penetrable entry points. A direct-to-clinic sales model bypassing hospital capital committees accelerates initial traction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic laboratory specialists commercializing biochemical marker panels with automated processing infrastructure. Long-term viability favors platforms spanning hardware-software-service integration rather than single-modality device plays. Watch FDA 510(k) clearance timelines for wearable-derived biomarkers as inflection signal for distributed screening model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated imaging workflows with Hologic and Siemens Healthineers anchor DXA volume concentration in Japan and Germany. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend approval cycles for DXA entrants, advantaging established regulatory affairs infrastructure. |
| Software Companion Development | Fracture risk algorithms and PACS integration modules extract recurring revenue through subscription licensing. |
| Reimbursement Strategy | CMS coverage determinations for trabecular bone score add-ons and wearable biomarker validation reshape competitive boundaries. |
| Point-of-Care Channel Development | Pharmacy-based kiosks in the United Kingdom and mobile health units in Spain capture unscreened at-risk populations. |
Study Parameters
The analysis maps DXA systems, portable ultrasound, biochemical markers, and wearable devices, each validated through hospital purchasing committees, primary care clinic administrators, biomedical engineers, and diagnostic laboratory directors. Primary interviews with these stakeholders combined secondary sources including FDA 510(k) filings, PMDA approval databases, METI reimbursement schedules, and CMS coverage determinations. Bottom-up unit economics and top-down epidemiological penetration models triangulate market sizing.
Consistency checks against hospital procurement database trends and GPO contract volumes validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include test type, end user archetype, application purpose, and technology platform. CAGRs derive from installed base replacement cycles, ambulatory expansion rates, and reimbursement policy trajectory. Industry-specific inputs incorporate DXA precision error improvements and biochemical panel automation adoption curves.
Material uncertainties — regulatory clearance delays, reimbursement policy reversals, and supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about preventive screening mandate continuity and wearable validation study outcomes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market