
 Brazil Spinal Surgery Devices Market | 2026-2036
Brazil Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Spinal Surgery Devices Market Outlook
Private hospital networks is reorganizing purchasing authority away from public procurement channels in Brazil's spinal surgery devices sector. Medtronic PLC leverages its broad implant portfolio to sustain deep relationships with major teaching hospitals in São Paulo and Rio de Janeiro. Stryker Corporation anchors its position through specialized surgical navigation systems for complex spinal procedures. Globus Medical Inc. differentiates via advanced expandable cage technologies that address degenerative conditions prevalent in Brazil's aging population.
Brazil spinal surgery devices encompass implantable systems, fixation hardware, bone graft substitutes, and precision instruments designed to stabilize vertebral columns, restore disc height, and decompress neural elements, typically manufactured from titanium alloys, PEEK polymers, or bioresorbable composites with strict fatigue resistance and biocompatibility parameters. Fusion surgery procedures dominate procedural volume due to established reimbursement pathways and surgeon familiarity, while endoscopic surgery represents the fastest-growing segment as minimally invasive training programs expand in Brazilian medical residency curricula. Metal-based implants currently occupy the largest material share, though biodegradable material adoption is accelerating among academic centers pursuing value-based outcomes.
ANVISA governs medical device registration and post-market surveillance, while the Brazilian Ministry of Health establishes reimbursement ceilings through the SUS system and complementary private insurance frameworks. ANVISA's alignment with Mercosur harmonization protocols and emerging equivalence agreements with FDA and Health Canada is streamlining market access for multinational manufacturers. Stakeholders must monitor how Brazil's pending medical device pricing transparency regulations reshape competitive bidding dynamics between domestic distributors and direct multinational sales operations.
Market Dynamics
Private hospital consolidation across southeastern Brazil is concentrating purchasing power into centralized procurement committees, fundamentally altering how spinal implant manufacturers negotiate contracts and allocate sales resources.
Growth Catalysts
- ANVISA's Mercosur Harmonization:Brazil's medical device regulator has aligned registration pathways with regional standards, compressing clearance timelines for implantable spinal systems from multinational suppliers.
- Minimally Invasive Training Expansion:Brazilian medical residency programs are incorporating endoscopic spinal techniques, expanding the addressable surgeon base for advanced procedural volumes.
- Aging Demographics in São Paulo State:Degenerative spinal conditions are driving procedural demand among patients over sixty-five, with metropolitan surgical corridors absorbing the majority of fusion and decompression cases.
Market Restraints
- Titanium Alloy Input Volatility:Raw material price fluctuations for implant-grade metals compress margin stability for domestic distributors lacking long-term supply contracts.
- SUS Reimbursement Ceilings:Brazil's public health system imposes rigid payment caps on spinal fusion procedures, constraining premium product adoption in public hospital networks.
- PEEK Polymer Sourcing Concentration:Limited domestic production of high-performance polymers forces reliance on imported feedstock, exposing manufacturers to currency and logistics risk.
Strategic Opportunities
- Bioresorbable Composite Adoption:Academic medical centers in Rio de Janeiro are piloting biodegradable spinal implants, creating early-mover positioning for value-based outcome demonstration.
- Minas Gerais Network Expansion:Private hospital chains are building orthopedic surgery capabilities in secondary cities, opening new territorial markets beyond saturated São Paulo corridors.
- Private Insurance Preauthorization Reform:Complementary health plan regulators are streamlining prior authorization for minimally invasive procedures, accelerating patient access timelines.
Industry Challenges
- Surgeon Training Pipeline Constraints:Fellowship programs in complex spinal surgery produce insufficient annual graduates to match procedural volume growth, creating talent scarcity for advanced techniques.
- ANVISA Post-Market Surveillance Compliance:Mandatory adverse event reporting and implant registry participation impose administrative burden on distributors with limited regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Spinal Surgery Devices Market |
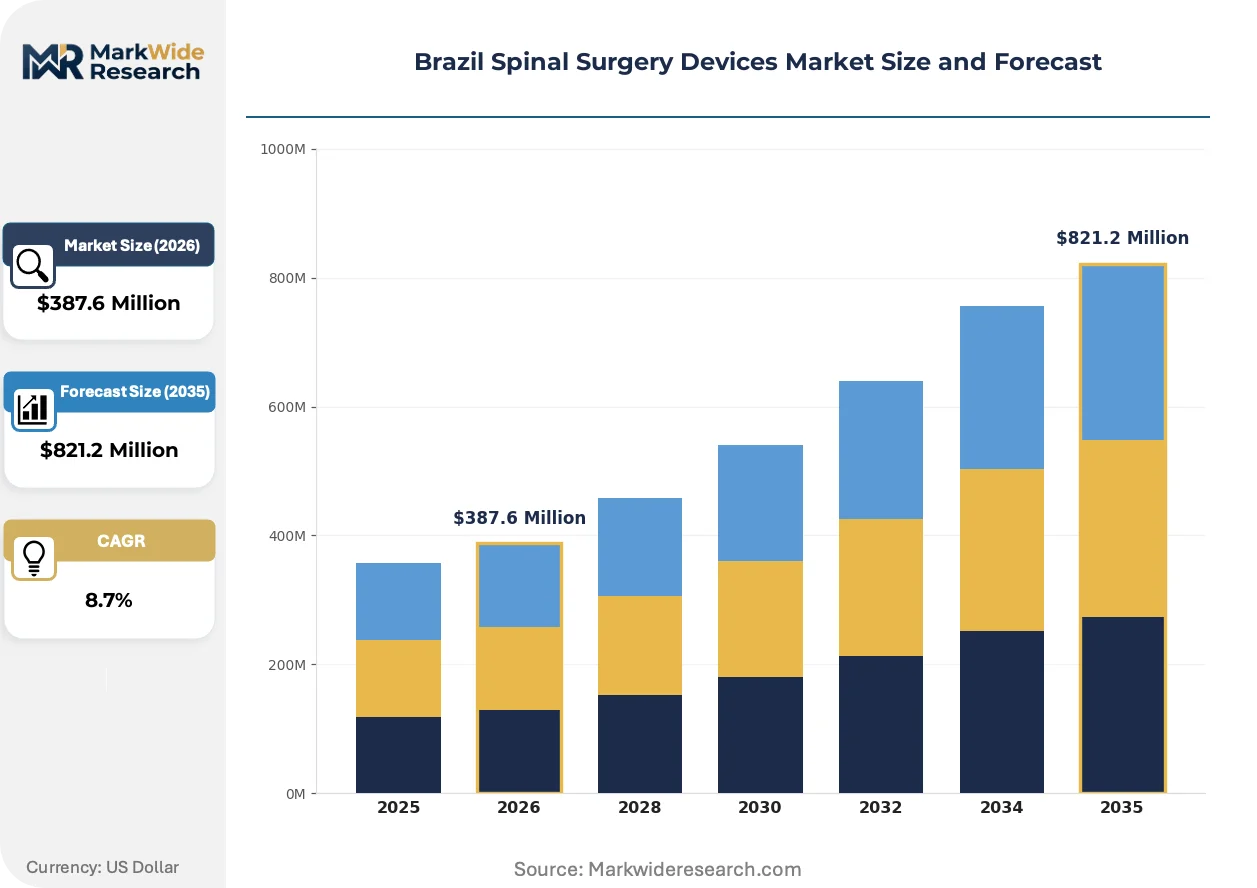
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Bone Grafts, Implants, Surgical Instruments, Fixation Devices Procedure Type: Fusion Surgery, Discectomy, Laminectomy, Endoscopic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Material: Metal, Polymer, Composite, Biodegradable Material |
| Companies Covered | Medtronic PLC, Stryker Corporation, Globus Medical Inc., Zimmer Biomet Holdings, Inc., Johnson & Johnson, Baumer, GMReis, Biomecanica Group, ZimVie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Spinal Surgery Devices Market Strategic Shifts
Technological substitution and regulatory alignment are compressing product lifecycles while reshaping competitive positioning among implant manufacturers serving Brazilian surgical networks.
Expandable cage systems with integrated fixation features are supplanting traditional static interbody devices in degenerative disc procedures. São Paulo's major teaching hospitals are adopting these platforms at accelerated pace, driven by reduced operative time and improved restoration of foraminal height. The shift is compressing demand for conventional titanium standalone cages and forcing distributors to reconfigure inventory toward adaptive geometry portfolios.
ANVISA's equivalence agreements with FDA and Health Canada are streamlining registration pathways for multinational manufacturers with existing major-market clearances. Domestic distributors face intensified competition from direct sales operations as regulatory friction diminishes. Academic centers with research mandates are prioritizing suppliers with established international surveillance data, tilting procurement toward firms with mature post-market study infrastructure.
Hospital purchasing committees are consolidating vendor relationships through single-source contracts for implant categories, displacing fragmented multi-supplier arrangements. Private networks in Rio de Janeiro and Belo Horizonte are leading this consolidation, bundling spinal fixation with navigation system leases. The concentration is visible most acutely in metropolitan corridors where procurement standardization reduces supply chain complexity and strengthens volume-based pricing leverage.
Brazil Spinal Surgery Devices Market Segmentation
Segmentation in Brazil's spinal surgery devices market reveals how procurement committees allocate budgets across implant categories and procedural approaches. Understanding these divisions exposes where multinational manufacturers compete against domestic distributors for contract volume.
Device Type:
Margin pools concentrate in implantable systems where ANVISA registration barriers protect pricing power for established suppliers.
- Implants:Titanium and PEEK interbody cages, artificial discs, and expandable vertebral replacement systems anchor revenue concentration. São Paulo's major teaching hospitals drive demand for integrated fixation platforms that reduce operative time in complex deformity cases. Premium positioning depends on fatigue resistance certification and long-term biocompatibility data.
- Fixation Devices:Pedicle screw systems, rods, hooks, and cross-connectors manufactured from implant-grade alloys provide mechanical stability during fusion healing. Minas Gerais private hospital networks are expanding instrumentation inventories as orthopedic surgery capabilities migrate beyond metropolitan corridors.
- Bone Grafts:Allograft, demineralized bone matrix, and synthetic ceramic substitutes fill interbody spaces to promote arthrodesis.
- Surgical Instruments:Specialized retractors, drills, taps, and insertion tools designed for spinal access and implant placement.
Implants hold installed capacity. Fixation devices are rotating up the share rankings.
Procedure Type:
Volume distribution tracks surgeon training availability and SUS reimbursement pathway maturity across Brazilian states.
- Fusion Surgery:Posterior lumbar interbody fusion, anterior cervical discectomy and fusion, and transforaminal approaches constitute the procedural backbone. Established reimbursement codes through Brazil's public health system sustain predictable case volumes in public hospital networks despite rigid payment ceilings.
- Endoscopic Surgery:Minimally invasive decompression and discectomy via tubular retractors or full endoscopic systems is climbing the fastest as Brazilian residency programs incorporate advanced technique training. Rio de Janeiro academic centers are piloting these platforms for outpatient spinal care.
- Discectomy:Removal of herniated disc material to relieve neural compression, performed open or microsurgically.
- Laminectomy:Decompressive removal of posterior vertebral elements to address spinal stenosis symptoms.
Fusion surgery holds installed capacity. Endoscopic surgery is rotating up the share rankings.
End User:
Customer concentration determines contract negotiation leverage and service level requirements for implant suppliers.
- Hospitals:Public SUS facilities and private networks across southeastern Brazil absorb the majority of spinal procedural volume. Centralized procurement committees in consolidated hospital systems are displacing fragmented purchasing arrangements and bundling implant categories under single-source contracts.
- Ambulatory Surgical Centers:Same-day spinal decompression and limited fusion procedures are expanding most quickly as private insurance preauthorization reforms accelerate patient access timelines in São Paulo state.
- Specialty Clinics:Orthopedic and neurosurgical practices performing diagnostic workup and minor interventions.
- Research Institutions:Academic medical centers conducting clinical trials and post-market surveillance studies for ANVISA compliance.
Hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
Material:
Supply chain configuration shapes cost structures and inventory risk for distributors serving Brazilian surgical networks.
- Metal:Titanium alloys and cobalt-chromium formulations dominate load-bearing applications requiring fatigue resistance and radiolucent imaging compatibility. Raw material price volatility for implant-grade metals compresses margin stability for distributors lacking long-term supply contracts.
- Biodegradable Material:Polylactic acid and polyglycolic acid composites for temporary fixation and fusion scaffolds are expanding most quickly. Rio de Janeiro academic centers are piloting these platforms for value-based outcome demonstration in degenerative disc procedures.
- Polymer:PEEK and other high-performance thermoplastics for radiolucent interbody cages.
- Composite:Reinforced polymer matrices combining mechanical properties with imaging advantages.
Metal holds installed capacity. Biodegradable material is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private hospital procurement committees concentrate purchasing authority across southeastern Brazil's metropolitan surgical corridors. Public SUS facilities maintain volume in degenerative spinal procedures despite reimbursement ceilings. State-level health infrastructure investments determine regional access disparities.
São Paulo
São Paulo state's aging demographics drive procedural demand for lumbar fusion and cervical decompression among patients over sixty-five. ANVISA's streamlined registration pathways accelerate product clearance for implantable systems targeting metropolitan teaching hospitals. The São Paulo metropolitan corridor absorbs the majority of complex deformity cases through consolidated private hospital networks.
Minas Gerais
Minas Gerais exhibits expanding orthopedic surgery capabilities as private hospital chains build secondary city infrastructure beyond saturated southeastern markets. Brazil's Ministry of Health maintains SUS reimbursement frameworks that constrain premium product adoption in public facilities. Belo Horizonte anchors regional procedural volume while tertiary cities absorb spillover demand from São Paulo referral networks.
Rio de Janeiro
Rio de Janeiro academic medical centers pilot bioresorbable spinal implants and endoscopic techniques for value-based outcome demonstration. ANVISA post-market surveillance requirements mandate adverse event reporting and implant registry participation from distributors serving research institutions. The metropolitan surgical corridor concentrates minimally invasive training programs expanding the addressable surgeon base.
Rio Grande do Sul
Rio Grande do Sul maintains established spinal surgery infrastructure through integrated public-private hospital networks serving southern Brazil. State-level complementary health insurance frameworks influence preauthorization timelines for fusion and decompression procedures. Porto Alegre anchors regional demand while distribution networks extend into neighboring Mercosur markets.
Paraná
Paraná's central geographic position positions Curitiba as a logistics hub for spinal implant distribution throughout southern Brazil. Currency exposure affects PEEK polymer sourcing costs for distributors relying on imported high-performance polymer feedstock. The state's hospital networks balance SUS volume with private insurance case expansion.
Brazil Spinal Surgery Devices Market Competitive Environment
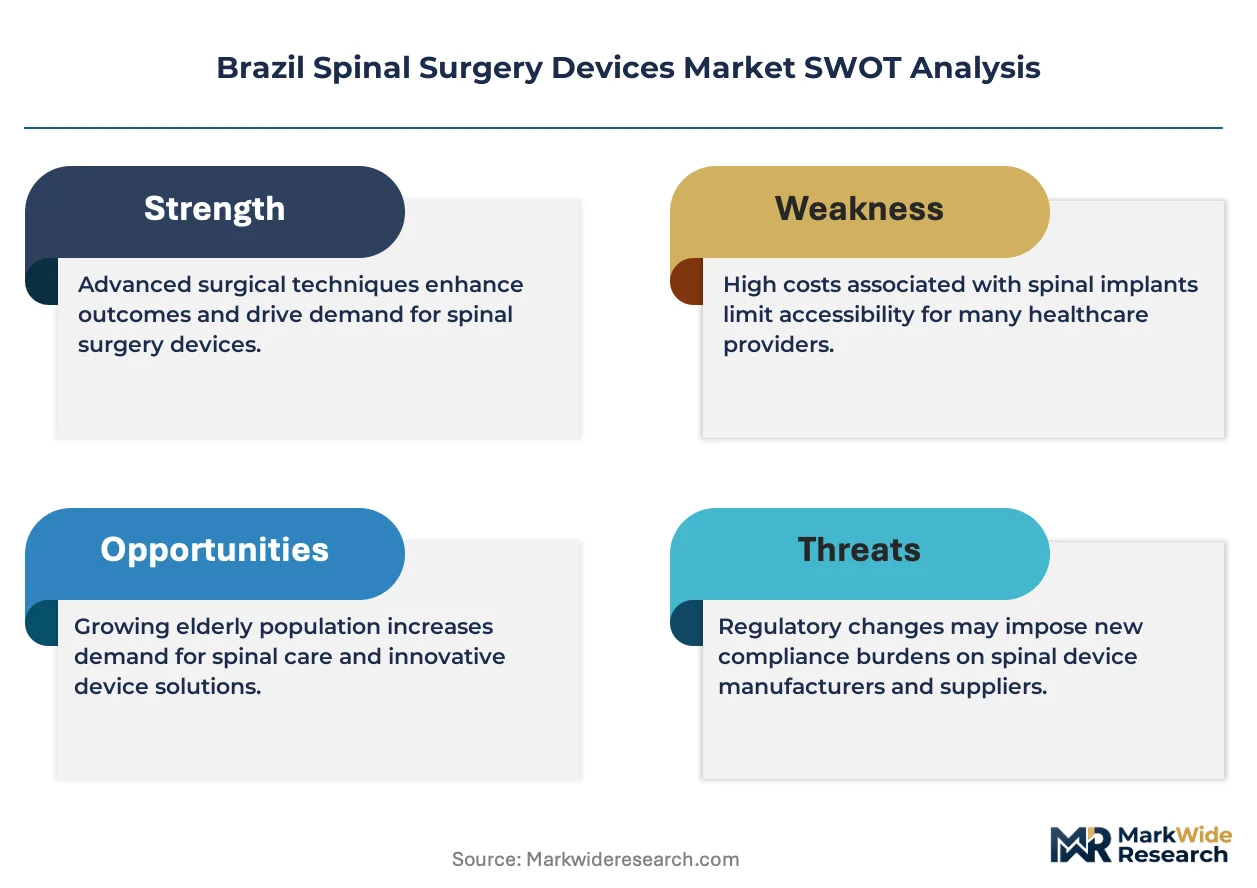
Player mix skews toward multinational implant manufacturers with established ANVISA registration portfolios and deep teaching hospital relationships. Market structure concentrates around firms possessing fatigue resistance certification and long-term biocompatibility data required for premium positioning. Two strategic archetypes dominate: diversified orthopedic conglomerates with broad spinal portfolios, and specialized spine-focused innovators with advanced expandable cage technologies. Competitive moves center on single-source contract bundling with navigation system leases, and direct sales expansion displacing domestic distributor relationships.
Among multinational suppliers, Medtronic PLC, Stryker Corporation, and Globus Medical Inc. exemplify contrasting positioning archetypes. Medtronic occupies a position representing diversified orthopedic scale with broad implant portfolios sustaining deep relationships across major Brazilian teaching hospitals. Stryker anchors its presence through specialized surgical navigation systems for complex spinal procedures, exemplifying the technology-integrated tier. Globus Medical sits within the innovation-focused segment, representing advanced expandable cage technologies addressing degenerative conditions prevalent in Brazil's aging population.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Globus Medical Inc. |
| Zimmer Biomet Holdings, Inc. |
| Johnson & Johnson |
| Baumer |
| GMReis |
| Biomecanica Group |
| ZimVie |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between São Paulo private hospital networks and implant-grade titanium suppliers lock in both raw material access and price visibility across multi-year procurement cycles. These contract structures insulate major distributors from currency-driven input volatility while compressing margin flexibility for smaller domestic players lacking comparable supply commitments.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange titanium pricing anchor implant procurement between Brazilian distributors and multinational manufacturers. Premium-mid-economy pricing differentiation separates fatigue-resistant certified systems from standard-grade alternatives, with ANVISA registration tier serving as the primary quality signal. Pricing pressure stems from SUS reimbursement ceilings constraining public hospital premium adoption, while private insurance networks demonstrate lowest price sensitivity due to preauthorization flexibility.
Supply Chain Analysis
PEEK polymer feedstock concentration in Germany, Switzerland, and the United States creates chokepoint exposure for Brazilian interbody cage manufacturers. Domestic production draws from imported titanium alloys, precision-machined instrumentation, and bioresorbable composite precursors. Single-source vulnerability runs through European polymer suppliers, with distribution anchored in Curitiba-based logistics hubs serving southeastern surgical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's spinal surgery devices market sits in cyclical recovery as ANVISA's regulatory harmonization accelerates product clearance timelines and reopens capital deployment from multinational manufacturers.
For Market Incumbents: Fortify ANVISA registration portfolios through equivalence pathway expansion with FDA and Health Canada, while deepening captive supply arrangements for implant-grade titanium to offset raw material volatility. Threat substitution from bioresorbable platforms in Rio de Janeiro academic centers demands accelerated clinical data generation to defend premium positioning. For New Entrants and Emerging Players: Differentiate on endoscopic navigation compatibility and expandable cage geometries targeting Minas Gerais secondary city expansion. The most penetrable white space sits in ambulatory surgical center supply chains underserved by incumbent direct sales forces, with GPO partnership routes offering fastest hospital access. For Investors and Strategic Acquirers: Specialized spine-focused innovators with established ANVISA clearances and expandable cage patent positions represent the highest-conviction acquisition archetype. Long-term viability over the coming decade hinges on navigation system integration capabilities and value-based outcome demonstration infrastructure. The signal to watch is private insurance preauthorization reform velocity as inflection indicator for outpatient procedural volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Equivalence Pathway Expansion | Compresses registration timelines for multinational manufacturers with FDA clearances. |
| Hospital System Partnership | Secures single-source contract bundling with São Paulo private network procurement committees. |
| Bioresorbable Implant Clinical Trial | Generates outcome data for Rio de Janeiro academic center value-based adoption. |
| Navigation System Integration | Aligns implant portfolios with Stryker-led surgical technology adoption curves. |
| Reimbursement Strategy | Positions premium systems for private insurance preauthorization pathway expansion. |
Study Parameters
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ANVISA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ANVISA registration databases, SUS reimbursement code listings, hospital procurement records, and Mercosur harmonization protocol documents. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data across device type, procedure approach, and end-user facility categories.
Sensitivity analysis around titanium price index volatility and currency fluctuation scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, procedure approach, end-user facility tier, material composition, and geographic corridor. CAGRs were derived from installed base dynamics and replacement cycle analysis, with surgeon training pipeline constraints and ANVISA clearance velocity serving as key forecast inputs.
Forecasts assume regulatory continuity in ANVISA's Mercosur harmonization and FDA equivalence agreements; material policy shifts would require re-modeling. Currency exposure, raw material supply disruption, and SUS reimbursement ceiling adjustments represent specific risk factors that could revise trajectory. Practitioners should keep alternative scenarios live as private insurance preauthorization reform and bioresorbable platform adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market