
 Vehicle Scanner Market | 2026-2036
Vehicle Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Scanner Market Intelligence
A shift from captive system development to third-party procurement of specialized modules is decoupling vehicle scanner integration from core infrastructure management. Leidos Holdings, Inc. leverages its extensive government contracts for market penetration. Rapiscan Systems specializes in high-throughput screening solutions for ports and borders. Nuctech Company Limited positions itself globally with a broad portfolio of imaging technologies for diverse security environments.
A vehicle scanner is an automated system designed for the non-intrusive inspection of cars, trucks, and cargo containers. These systems utilize technologies like 3D Imaging and sensor fusion to generate detailed scans for identifying contraband, explosives, or structural anomalies. Within product types, Lidar-Based scanners are gaining share for autonomous fleet management applications. For end users, government agencies continue to be the largest procurer, driven by law enforcement and border control mandates.
Market access and product design are shaped by stringent security and safety standards. In the United States, equipment must often comply with specifications set by the Department of Homeland Security, while in Europe, CE marking and adherence to directives on radiation safety are mandatory. Future competitive advantage will depend on the ability to embed AI-powered analytics for real-time decision-making without compromising on data privacy regulations like GDPR.
Market Dynamics
The central force shaping the vehicle scanner market is the integration of machine learning into imaging systems. This shift transforms scanners from simple detection tools into predictive analytics platforms, automating threat identification and reducing reliance on human operators for primary screening.
Growth Catalysts
- Heightened Security Mandates:Government requirements, such as specifications from the U.S. Department of Homeland Security for border crossings and federal facilities, compel the procurement of advanced non-intrusive inspection systems to counter contraband and threats.
- Critical Infrastructure Protection:Demand from operators of ports, airports, and energy plants for high-throughput screening solutions is increasing to secure supply chains and prevent unauthorized access or sabotage without disrupting commercial flow.
- Autonomous Fleet Management:The adoption of Lidar-Based scanners for structural integrity checks and undercarriage inspection is expanding within commercial logistics and autonomous vehicle fleets, opening a new application vertical beyond traditional security.
Market Restraints
- High Capital Investment:The significant upfront cost associated with acquiring and installing high-resolution 3D imaging and sensor fusion systems presents a substantial barrier for smaller organizations or municipalities with limited security budgets.
- System Integration Complexity:Integrating new scanner hardware and its proprietary software with existing, often decades-old, command-and-control platforms and security information management systems poses significant technical and operational challenges.
- Radiation Safety Compliance:Adherence to stringent standards for ionizing radiation, including CE marking directives in Europe, constrains product design and requires lengthy, costly certification processes, particularly for systems used in public spaces.
Strategic Opportunities
- Expansion in Emerging Economies:Infrastructure development projects across Southeast Asia and the Middle East create significant opportunities for deploying vehicle scanners at new ports, border checkpoints, and commercial hubs that lack modern inspection capabilities.
- Commercial Loss Prevention:A growing application is in the commercial logistics sector for verifying cargo manifests, detecting theft, and identifying undocumented goods, shifting the value proposition from pure security to operational efficiency.
- AI-Powered Predictive Analytics:The convergence of machine learning with advanced imaging allows for the development of systems that can predict potential threats based on anomaly detection patterns, moving beyond simple contraband identification.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of data scientists and AI engineers capable of developing, training, and maintaining the sophisticated algorithms required for automated threat detection hinders innovation and deployment at scale.
- Data Privacy and Governance:Managing and securing the vast amounts of sensitive data generated by scanners, including images of vehicle occupants, requires robust frameworks to comply with regulations like GDPR without compromising security effectiveness.
- Lack of Interoperability Standards:The absence of universal standards for data formats and communication protocols between scanners from different manufacturers complicates the creation of unified, multi-vendor security networks for large-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Scanner Market |
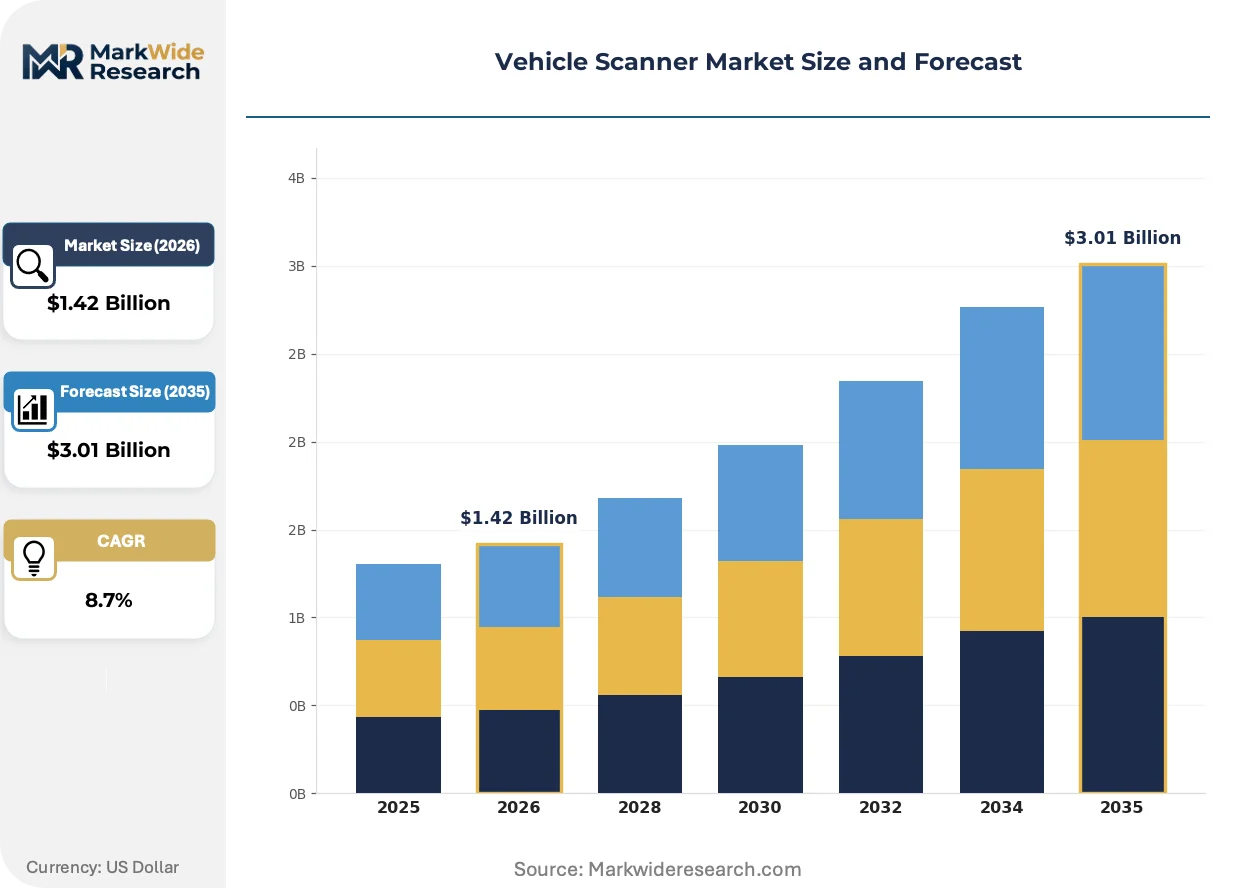
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar-Based, Lidar-Based, Infrared, Ultrasonic, Optical Camera Technology: 3D Imaging, Sensor Fusion, Machine Learning, Signal Processing, Edge Computing Application: Traffic Monitoring, Law Enforcement, Fleet Management, Parking Management, Toll Collection End User: Government Agencies, Private Security Firms, Logistic Operators, Vehicle OEMs, Infrastructure Providers |
| Companies Covered | Leidos Holdings, Inc., Rapiscan Systems, Gatekeeper Security Inc., Omnitec Group, Nuctech Company Limited, SCANLAB GmbH, SecureOne International BV, UVeye, Smith's Detection Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Scanner Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric detection to software-driven intelligence. This transition prioritizes automated analytics, real-time data fusion, and system modularity, enabling more adaptive and predictive security postures at critical checkpoints.
Advanced 3D Imaging, often combined with sensor fusion techniques, generates detailed, rotatable models of vehicles and their contents. Border security agencies and operators of high-security facilities are adopting this technology for its ability to provide superior context over flat images. This multi-modal data capture capability is overtaking traditional 2D X-ray systems by dramatically improving the detection accuracy of cleverly concealed contraband and improvised explosive devices.
The European Union's AI Act introduces a risk-based framework that classifies certain security and surveillance technologies as high-risk. This legislation mandates rigorous testing, data governance, and human oversight for AI systems used in law enforcement and critical infrastructure protection. Scanner manufacturers targeting European markets are now compelled to redesign their machine learning models for greater transparency and auditability, impacting development cycles and compliance costs.
A clear transition toward modular system architecture is altering procurement patterns. End users are increasingly sourcing specialized components like imaging arrays, conveyor systems, and analytical software from different best-in-class vendors rather than buying a single turnkey solution. This unbundling is most evident in large-scale port and border modernization projects in the United States and China, affording greater flexibility and simplifying future technology upgrades.
Vehicle Scanner Market Segmentation
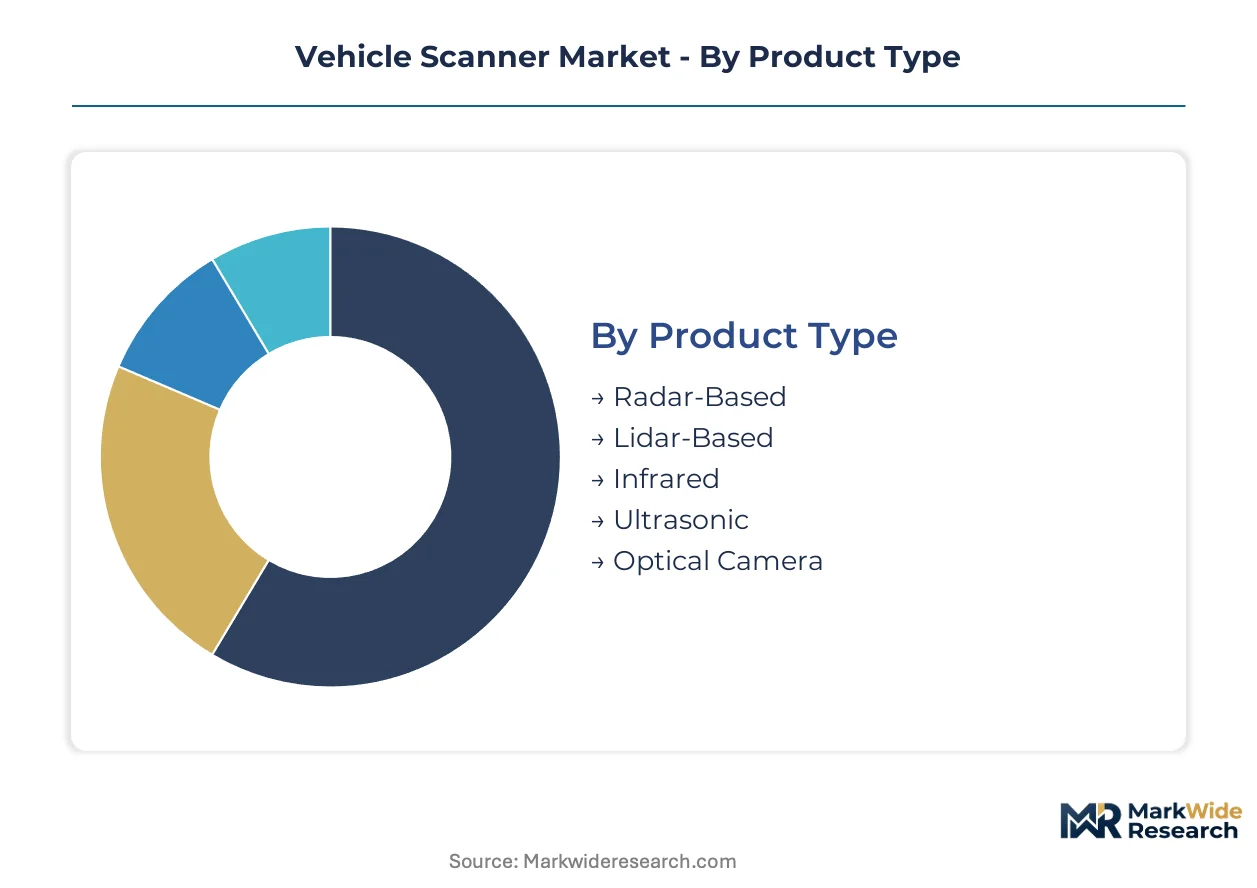
The vehicle scanner market segmentation highlights the diverse technological approaches and end-user applications driving demand and innovation within the industry. Understanding these distinct segments provides clarity on where investment and technological advancements are concentrating across the security landscape.
Product Type:
The choice of vehicle scanner product type often depends on the specific inspection requirements and environmental conditions at a security checkpoint.
- Lidar-Based:These scanners utilize pulsed laser light to measure distances and create highly accurate 3D representations of vehicle undercarriages and profiles. Demand is expanding for autonomous fleet management applications, where they perform structural integrity checks and enhance navigational safety.
- Radar-Based:Radar systems employ radio waves to detect objects and measure their speed and distance, effectively penetrating adverse weather conditions for vehicle tracking. Their integration is crucial for traffic monitoring applications in regions like Germany, ensuring continuous data collection despite fog or heavy rain.
- Infrared:Infrared scanners detect heat signatures, primarily used for identifying concealed persons or overheating components within vehicles.
- Ultrasonic:Ultrasonic technology uses sound waves for proximity sensing and basic object detection, common in parking management systems.
- Optical Camera:High-resolution optical cameras capture visual images for license plate recognition and general vehicle surveillance in law enforcement.
Volume sits with Radar-Based systems; growth tilts toward Lidar-Based scanners.
Technology:
The underlying technology determines the depth of inspection and the level of automation achievable across diverse vehicle scanning applications.
- Machine Learning:This technology enables automated threat detection by training algorithms on vast datasets of scanned images, significantly reducing reliance on human operators for primary screening. Its adoption is critical for enhancing border security operations in the United States, streamlining the identification of contraband.
- 3D Imaging:Advanced 3D imaging systems generate detailed, rotatable models of vehicles and their contents, providing superior contextual information compared to traditional 2D methods. High-security facilities in Europe are increasingly deploying 3D imaging for more accurate detection of cleverly concealed explosives.
- Sensor Fusion:Sensor fusion combines data from multiple sensor types to create a more comprehensive and reliable picture of inspected vehicles.
- Signal Processing:Signal processing techniques enhance raw data from sensors, improving image clarity and detection accuracy for various anomalies.
- Edge Computing:Edge computing processes data locally at the scanner, reducing latency and bandwidth requirements for real-time threat analysis.
More mature technologies like Signal Processing offer foundational capabilities, while Machine Learning is experiencing the steepest expansion trajectory.
Application:
Different end-user segments prioritize specific applications based on their operational needs and security objectives.
- Law Enforcement:This application involves using vehicle scanners at border crossings, checkpoints, and critical infrastructure to detect contraband, weapons, and explosives. Government agencies in Canada leverage these systems to enforce customs regulations and counter illicit trafficking.
- Fleet Management:Scanners in fleet management assess vehicle structural integrity, conduct undercarriage inspections, and verify cargo manifests for commercial logistics operations. Commercial logistics providers in China are integrating these solutions to enhance operational efficiency and prevent cargo theft.
- Traffic Monitoring:Vehicle scanners contribute to traffic flow analysis and incident detection on highways and urban roads in major cities.
- Parking Management:These systems automate vehicle entry and exit, monitor occupancy, and enhance security in large parking facilities.
- Toll Collection:Scanners facilitate automated vehicle identification and classification for efficient electronic toll collection systems on national highways.
Core value for Law Enforcement remains security, while Fleet Management applications are increasingly valued for operational efficiency gains.
End User:
The scale of deployment and budgetary considerations significantly influence the type and sophistication of vehicle scanning solutions adopted by different end-user groups.
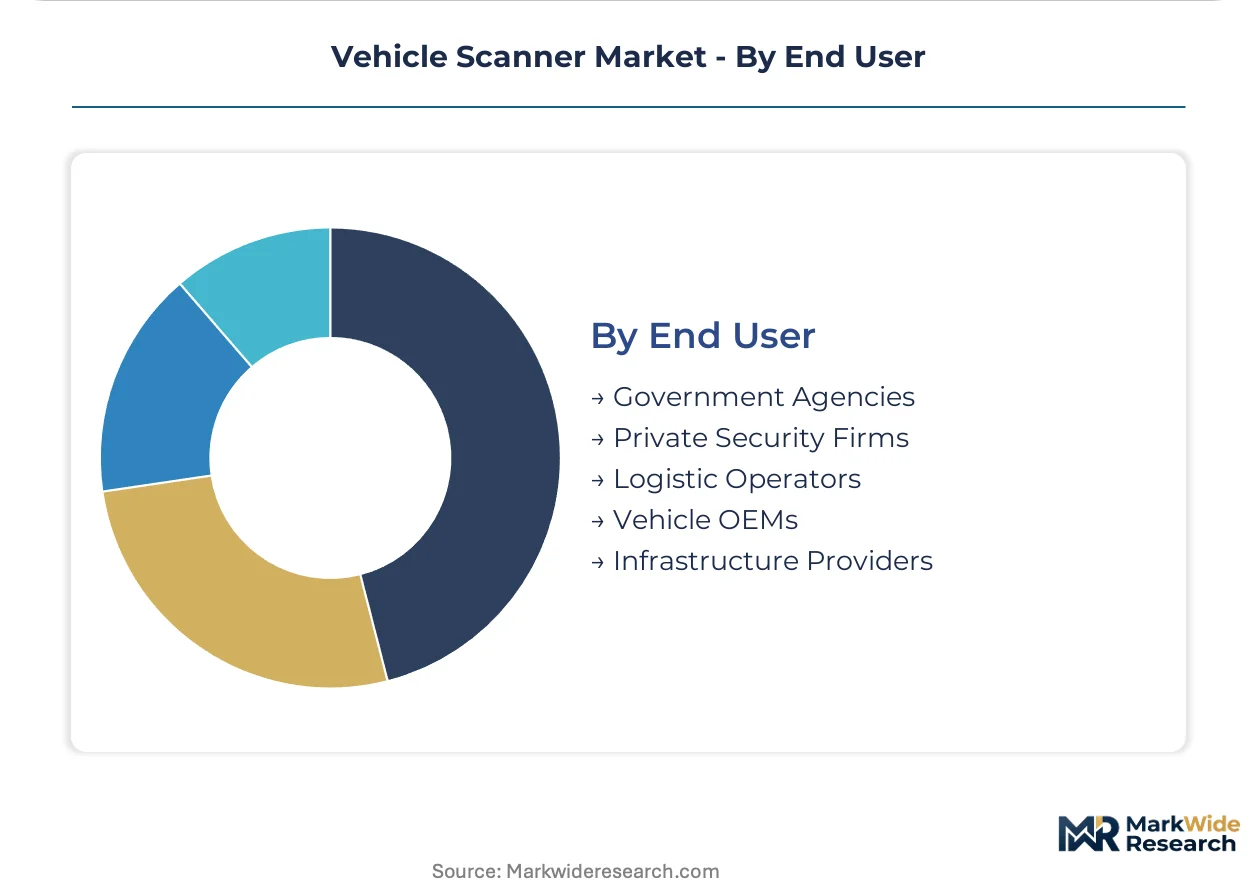
- Government Agencies:This segment represents the largest procurer of vehicle scanners, driven by mandates for border control, customs inspections, and protection of federal facilities. The U.S. Department of Homeland Security consistently invests in advanced non-intrusive inspection systems for national security.
- Logistic Operators:Commercial logistics companies utilize scanners for cargo verification, loss prevention, and ensuring compliance with shipping regulations across their supply chains. Major freight forwarders in Germany implement these technologies to streamline warehouse operations and reduce pilferage.
- Private Security Firms:These firms deploy scanners for access control and perimeter security at corporate campuses, events, and private facilities.
- Vehicle OEMs:Original Equipment Manufacturers integrate scanning technologies for quality control during production and for autonomous driving features.
- Infrastructure Providers:Operators of ports, airports, and energy plants use scanners to secure critical access points and prevent unauthorized entry.
Government Agencies lead in strategic procurement, while Logistic Operators are increasingly influencing product development through their demand for integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for advanced vehicle scanning technologies, driven by national security priorities and significant infrastructure investments. Regional security mandates and technological advancements shape the procurement patterns for non-intrusive inspection systems across key global markets. Diverse regulatory frameworks and economic development trajectories influence the adoption rates and technological sophistication of vehicle scanners in each geography.
United States
Heightened security mandates from the U.S. Department of Homeland Security compel the procurement of advanced non-intrusive inspection systems at border crossings and federal facilities. The Transportation Security Administration (TSA) also drives demand for screening solutions at critical transportation hubs. Major technology clusters in California and Texas continue to innovate in sensor fusion and AI-powered analytics for vehicle inspection.
China
Large-scale infrastructure projects across China, including new ports and border checkpoints, fuel demand for high-throughput vehicle scanners. Commercial logistics providers integrate these solutions to enhance operational efficiency and prevent cargo theft, supported by government initiatives for smart city development. The Yangtze River Delta region, with its extensive port infrastructure, represents a significant market for advanced screening technologies.
Germany
Traffic monitoring applications for Radar-Based systems are expanding in Germany, ensuring continuous data collection despite adverse weather conditions. Adherence to CE marking directives and stringent radiation safety standards shapes product design and market access for manufacturers. Bavaria, a hub for automotive engineering, increasingly adopts Lidar-Based scanners for autonomous fleet management applications.
Canada
Government agencies in Canada leverage vehicle scanners for law enforcement, enforcing customs regulations, and countering illicit trafficking at border entries. Public Safety Canada mandates the use of advanced inspection technologies to enhance national security and economic integrity. The Greater Toronto Area, a major logistics hub, sees growing deployment of scanners for cargo verification and loss prevention.
United Arab Emirates
Infrastructure development projects across the United Arab Emirates, particularly in new ports and commercial hubs, create significant opportunities for deploying modern vehicle scanners. The Dubai Customs Authority invests in advanced imaging systems to secure trade flows and detect contraband. Dubai and Abu Dhabi, as global logistics gateways, prioritize high-security screening solutions for critical access points.
Vehicle Scanner Market Key Industry Players
Strategic partnerships dominate the current landscape, allowing companies to combine specialized modules and extend their market reach. The vehicle scanner market exhibits a tiered structure, with large defense contractors alongside specialized technology providers and regional integrators. Geographic expansion and technology licensing represent key competitive moves as firms seek to penetrate new markets and enhance their product portfolios.
Within the large government contractor tier, Leidos Holdings, Inc. leverages its extensive government contracts for market penetration in the United States and globally. Rapiscan Systems exemplifies a specialist in high-throughput screening solutions, targeting ports and borders with advanced non-intrusive inspection systems. Nuctech Company Limited, a prominent Chinese entity, positions itself globally with a broad portfolio of imaging technologies for diverse security environments, reflecting a strategy of comprehensive product offerings.
| Leading Market Players |
|---|
| Leidos Holdings, Inc. |
| Rapiscan Systems |
| Gatekeeper Security Inc. |
| Omnitec Group |
| Nuctech Company Limited |
| SCANLAB GmbH |
| SecureOne International BV |
| UVeye |
| Smith's Detection Group Ltd. |
| Others |
Cost & Logistics Intelligence
The integration of AI-powered analytics into vehicle scanners is reshaping cost economics by emphasizing software development over raw hardware. This shift simultaneously concentrates supply in specialized module providers rather than full-system integrators.
Pricing Analysis
Warranty and service bundles significantly influence the total cost of ownership for vehicle scanners, often unbundled for modular components. Project-based pricing dominates for large-scale deployments, with customization level and after-sales service quality driving price differentiation. Pricing softness reflects heightened competition from new entrants offering specialized modules. Smaller municipalities and commercial logistics providers exhibit higher price sensitivity compared to national government agencies.
Supply Chain Analysis
Single-source vulnerability sits with specialized sensor and imaging component manufacturers, primarily concentrated in China and Germany. The vehicle scanner supply chain draws from advanced Lidar sensors, high-resolution 3D imaging processors, and proprietary AI algorithms. Intellectual property theft represents a significant structural risk, particularly for software-driven innovations. Distribution runs through direct sales channels for government agencies, while system integrators serve private security firms and logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle scanner market is characterized by a vertical-integration race, as companies seek to control the full technology stack from sensor manufacturing to AI-powered analytics. This strategy aims to secure intellectual property and enhance solution differentiation.
For Market Incumbents: Extend existing government contracts by offering comprehensive, modular upgrade paths for legacy systems. Incumbents must also deepen R&D investment in AI-powered analytics to counter emerging threats from specialized software providers. The threat of new entrants with advanced machine learning capabilities necessitates continuous innovation. Enhancing certification investment for new radiation safety standards provides a critical lever for market access.
For New Entrants and Emerging Players: Begin with specialized AI-powered analytics modules that integrate seamlessly into existing hardware platforms. Target the commercial logistics sector in China, which values operational efficiency gains from cargo verification. Focus on developing solutions that address specific data privacy concerns, offering a transparent and auditable go-to-market angle. This approach allows new players to penetrate the market without the high capital investment of full-system development.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized software firms developing AI-powered analytics for anomaly detection. Over the next 5-10 years, the market favors companies that can demonstrate robust data governance frameworks compliant with regulations like GDPR. Acquisition targets include agile startups with proven machine learning algorithms and sensor fusion expertise. The signal to watch is the widespread adoption of interoperability standards, which would consolidate fragmented technology offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Predictive Analytics | This initiative enables automated threat detection, significantly reducing reliance on human operators for primary screening tasks. |
| Develop Modular System Architectures | Modular designs allow end users to source best-in-class components, simplifying upgrades and offering greater integration flexibility. |
| Secure Radiation Safety Certifications | Adherence to stringent standards like CE marking is mandatory for market access, particularly for systems used in public spaces. |
| Expand into Southeast Asian Markets | Infrastructure development across Southeast Asia creates significant opportunities for deploying vehicle scanners at new ports. |
| Form Partnerships for Sensor Fusion | Combining data from multiple sensor types creates a comprehensive picture, improving detection accuracy for complex anomalies. |
Research Approach
Government security reports, customs trade data, and technology patent databases formed the secondary backbone for this analysis. Primary interviews with law enforcement officials, logistics operators, security systems integrators, and AI engineers provided granular insights. This approach ensured comprehensive data validation through both bottom-up and top-down triangulation. Market sizing and segmentation were cross-referenced against multiple data points.
Historical trendline analysis established foundational growth patterns for the vehicle scanner market across the modeling period. The analytical framework modeled segmentation by product type, technology, application, end user, and regional security mandates. Compound Annual Growth Rates were derived from a multi-factor regression model incorporating technological advancements. Government spending on border security and critical infrastructure projects served as key forecast inputs.
Underlying measurement precision varies by segment; government procurement and critical infrastructure applications carry tighter precision. Forecasts reflect assumptions on regulatory changes and technological adoption rates. Geopolitical shifts or new data privacy regulations could alter market trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automated Guided Cart Market