
 Advanced Driver Assistance Systems Testing Equipment Market | 2026-2036
Advanced Driver Assistance Systems Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Driver Assistance Systems Testing Equipment Market Analysis
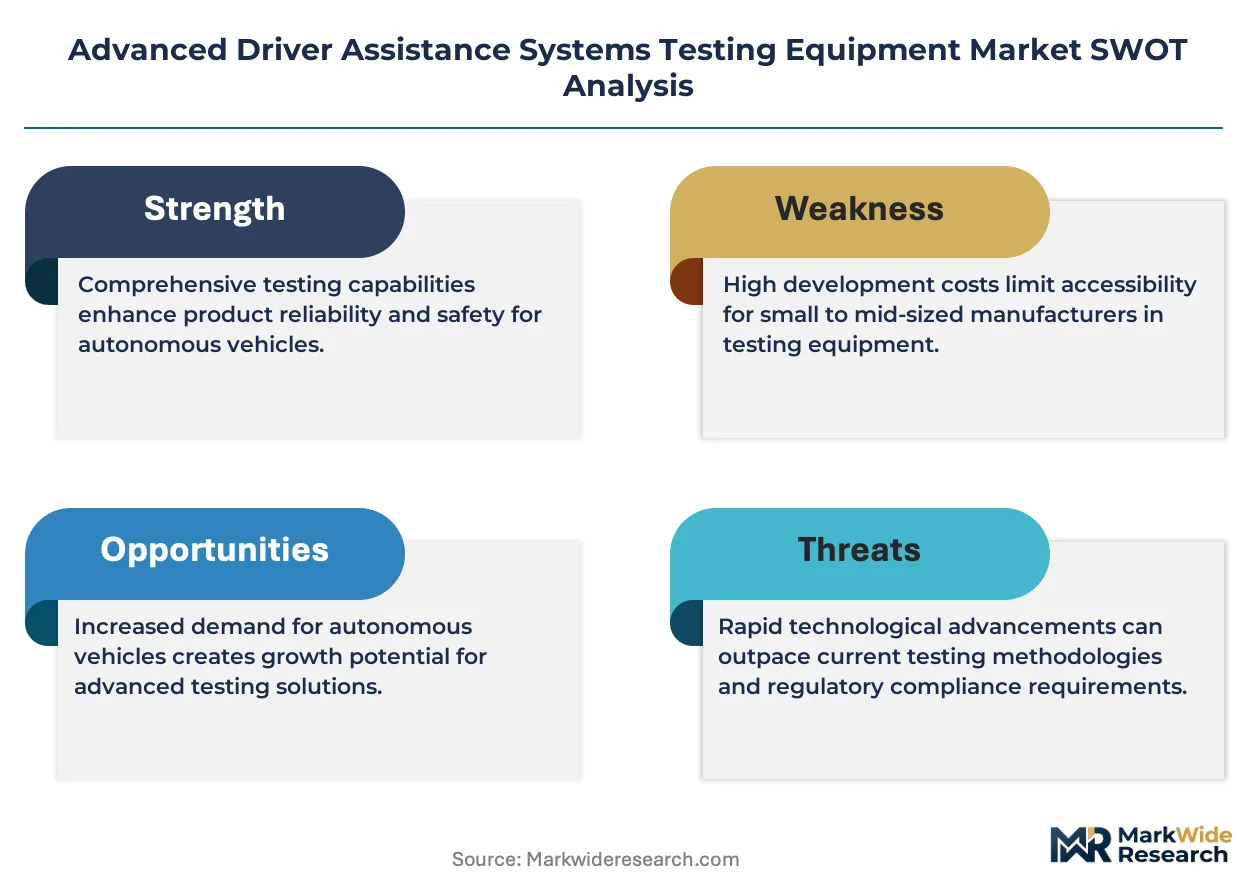
The gap between premium multi-sensor validation rigs and entry-level single-function test benches is realigning procurement patterns across the supply base. TKH Group NV leverages its integrated vision and radar test platforms to anchor high-end contracts with European automakers. National Instruments Corporation competes through modular PXI-based architectures that sustain flexibility across evolving ADAS protocols. AVL LIST GmbH dominates full-vehicle proving ground installations, occupying a position where end-to-end test traceability commands pricing power.
Advanced Driver Assistance Systems testing equipment comprises calibrated hardware-in-the-loop rigs, sensor target simulators, and scenario-generation software used to validate perception, planning, and actuation functions under reproducible conditions. These systems subject cameras, lidar, and radar units to synthetic weather, lighting, and obstacle configurations that would be unsafe or uneconomical to replicate on public roads. Lidar sensor test rigs currently lead capital expenditure among product categories, while software tools for scenario-based validation represent the fastest-expanding margin pool as virtual testing displaces physical prototype mileage. Machine learning validation frameworks are displacing rule-based test scripts, concentrating R&D investment among end users with autonomous vehicle programs.
NHTSA's Federal Motor Vehicle Safety Standards and Euro NCAP's progressive rating protocols are mandating wider sensor coverage, directly expanding the addressable base for radar and camera test systems. China's MIIT publishes GB standards for intelligent connected vehicles that require domestic certification, creating parallel demand for localized test equipment configurations. Stakeholders must monitor how regulatory divergence between NHTSA, ECE, and GB frameworks fragments test protocol harmonization and multiplies validation workload for global platform programs.
Market Dynamics
Sensor fusion validation is compressing test cycles as automakers consolidate radar, camera, and lidar verification into unified hardware-in-the-loop rigs rather than discrete single-sensor benches. This consolidation is redistributing capital expenditure toward integrated platform vendors and away from point-solution providers.
Growth Catalysts
- Euro NCAP 2026 protocols:Mandates for vulnerable road user detection and junction assist are expanding the addressable base for pedestrian target simulators and scenario-generation software across European test laboratories.
- Hardware-in-the-loop consolidation:Automakers are converging sensor validation onto unified rigs that reduce physical prototype mileage, pulling demand toward multi-domain test platforms capable of synchronous camera-radar-lidar stimulation.
- China's MIIT GB standards:Domestic certification requirements for intelligent connected vehicles are creating parallel demand for localized test equipment configurations that accommodate GB/T protocol variations.
Market Restraints
- High-purity signal generation components:Specialized RF components for radar target simulation face supply concentration among German and Japanese component vendors, creating input cost volatility and extended lead times.
- Regulatory fragmentation:Divergence between NHTSA Federal Motor Vehicle Safety Standards, ECE regulations, and China's GB frameworks multiplies validation workload for global platform programs without harmonized test protocols.
- Virtual substitution threshold:Software-based sensor simulation is capturing validation tasks below SAE Level 3, compressing addressable demand for physical test rigs in entry-level ADAS segments.
Strategic Opportunities
- India's proving ground deficit:The country's sparse automotive test infrastructure creates white space for mobile sensor validation units and portable hardware-in-the-loop systems serving domestic OEMs and component suppliers.
- Software scenario libraries:Subscription-based access to pre-validated test scenarios is emerging as a recurring revenue channel, displacing perpetual-license models among Tier-2 suppliers with limited scenario-development resources.
- AI Act compliance preparation:European automotive AI validation requirements are creating demand for machine learning test frameworks that document training data provenance and algorithmic decision boundaries.
Industry Challenges
- Embedded systems cybersecurity certification:UN R155 and ISO/SAE 21434 mandates are extending validation timelines as test equipment vendors must demonstrate secure software development lifecycle documentation alongside functional performance.
- Multi-physics simulation expertise:Scarce talent pools capable of integrating electromagnetic, optical, and mechanical simulation domains are constraining R&D velocity for integrated test platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Driver Assistance Systems Testing Equipment Market |
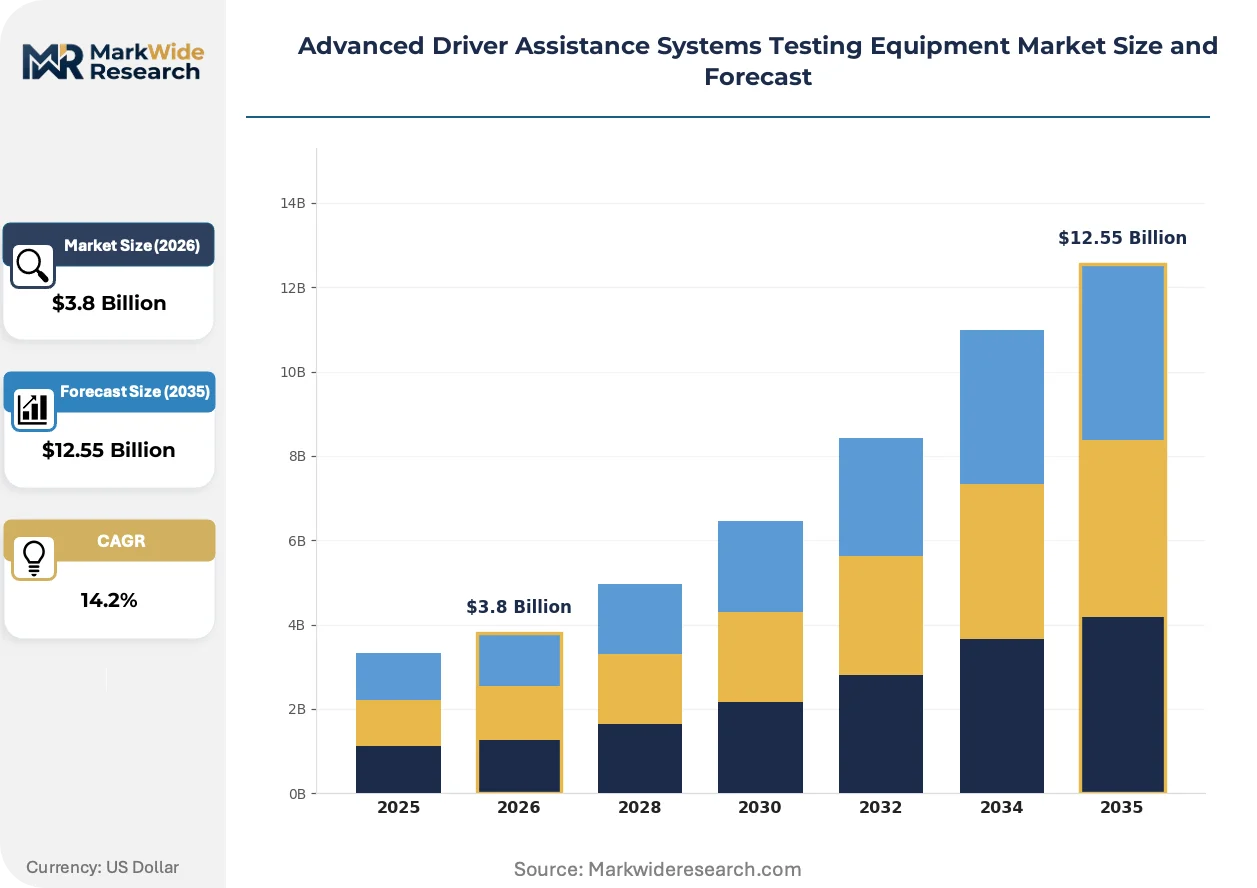
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, Lidar Sensors, Cameras, Software Tools Application: Autonomous Vehicles, Collision Avoidance, Lane Departure Warning, Adaptive Cruise Control End User: Automakers, Testing Labs, Research Institutions, Tier-1 Suppliers Technology: Machine Learning, Computer Vision, Sensor Fusion, Data Analytics |
| Companies Covered | TKH Group NV, FEV Group GmbH, National Instruments Corporation, AVL LIST GmbH, AB Dynamics plc, Racelogic Limited, Konrad GmbH, Oxford Technical Solutions Ltd, Averna Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Driver Assistance Systems Testing Equipment Market Emerging Trajectories
Digital twin architectures are collapsing the boundary between virtual sensor simulation and physical test execution, enabling continuous validation pipelines that feed real-world test results back into synthetic scenario libraries. This convergence is restructuring how OEMs allocate capital across physical and virtual test assets.
Photorealistic rendering engines are integrating with hardware-in-the-loop rigs to stimulate camera-based ADAS with synthetic imagery that matches physical test track fidelity. Tier-1 suppliers are deploying these fused virtual-physical platforms to compress validation schedules for new vehicle programs. The technology is integrating previously separate software and hardware test budgets into unified capital planning frameworks.
NHTSA's advancing Federal Motor Vehicle Safety Standards for automatic emergency braking are mandating wider operational design domain coverage, including low-light and adverse weather performance. This regulatory expansion is forcing test equipment vendors to invest in dynamic lighting rigs and precipitation simulation chambers. The United States market is responding with expanded proving ground capacity and upgraded environmental test cell installations.
Validation-as-a-service models are displacing capital-intensive equipment purchases among mid-tier component suppliers with intermittent test requirements. Specialized test houses in Germany and Michigan are capturing this demand by offering time-shared access to sensor target simulators and scenario libraries. The automotive electronics sector is driving this shift, with suppliers prioritizing operational expenditure flexibility over fixed asset ownership.
Advanced Driver Assistance Systems Testing Equipment Market Segmentation
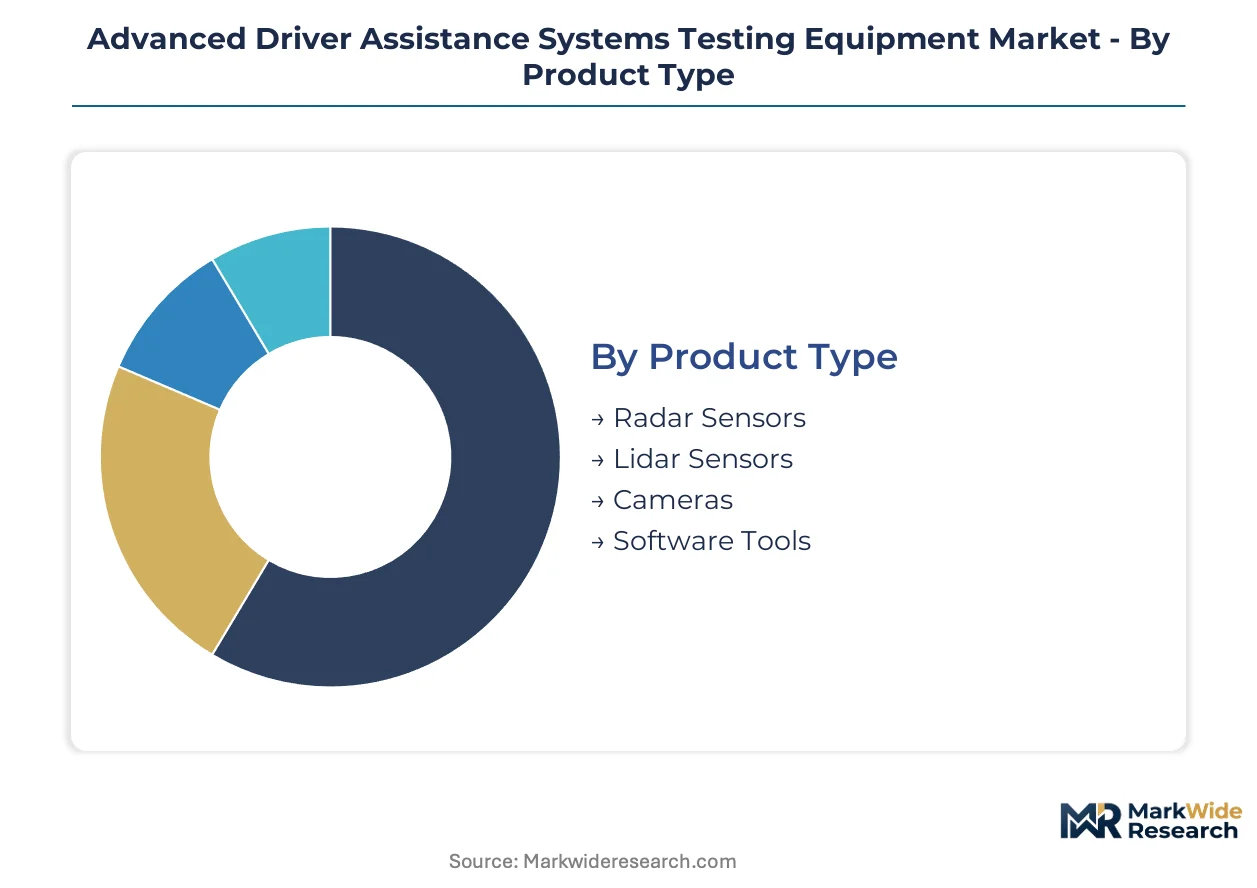
ADAS testing equipment segments reflect divergent capital deployment strategies across the validation value chain. Procurement patterns split between integrated platform buyers seeking end-to-end traceability and point-solution purchasers optimizing for single-function test coverage.
Product Type:
Buyers differentiate by sensor modality complexity and the degree of environmental simulation required for regulatory certification.
- Lidar Sensors:Test rigs for solid-state and mechanical lidar units incorporate calibrated reflectivity targets and range accuracy validation under synthetic fog and precipitation. German proving grounds and Michigan test facilities are expanding lidar-specific environmental chambers to meet NHTSA expanded operational design domain requirements.
- Software Tools:Scenario-generation platforms and machine learning validation frameworks enable virtual mileage accumulation before physical prototype deployment. China's MIIT GB certification requirements are accelerating localized software procurement for domestic intelligent connected vehicle programs.
- Radar Sensors:RF target simulators with Doppler signature generation for adaptive cruise and blind-spot monitoring validation.
- Cameras:Photorealistic rendering engines and dynamic lighting rigs for image sensor characterization under variable illumination.
Lidar test systems lead volumes today; software tools are gaining share fastest.
Application:
Validation intensity scales with functional safety integrity levels and the severity of failure modes under assessment.
- Autonomous Vehicles:End-to-end validation pipelines spanning perception, planning, and actuation demand unified hardware-in-the-loop rigs with synchronous multi-sensor stimulation. SAE Level 4 programs in California and Arizona are consolidating previously discrete test benches into integrated validation platforms.
- Collision Avoidance:Automatic emergency braking test protocols require pedestrian and cyclist target simulators with precise trajectory control. Euro NCAP 2026 vulnerable road user mandates are expanding procurement of soft pedestrian dummies and propulsion systems in European test laboratories.
- Lane Departure Warning:Camera-based lane marking detection validation under worn road surface and adverse weather conditions.
- Adaptive Cruise Control:Radar target simulation for following distance calibration across speed and traffic density variations.
Collision avoidance leads volumes today; autonomous vehicle applications are expanding most quickly.
End User:
Budget authority and test frequency determine whether stakeholders favor capital equipment ownership or validation-as-a-service consumption.
- Tier-1 Suppliers:Continental, Bosch, and Denso validation divisions require continuous throughput for sensor fusion module verification, driving investment in multi-domain test platforms. These suppliers are consolidating single-sensor benches into unified rigs to compress program timelines for European and North American OEM customers.
- Automakers:In-house proving ground operations at Volkswagen, Ford, and BYD prioritize end-to-end traceability for homologation documentation.
- Testing Labs:Independent facilities including DEKRA and TÜV SÜD offer time-shared access to certified test scenarios.
- Research Institutions:University-affiliated mobility centers with intermittent validation needs favor portable hardware-in-the-loop units.
Tier-1 suppliers lead volumes today; testing labs are climbing the fastest.
Technology:
R&D investment concentrates where algorithmic validation complexity outpaces rule-based test script coverage.
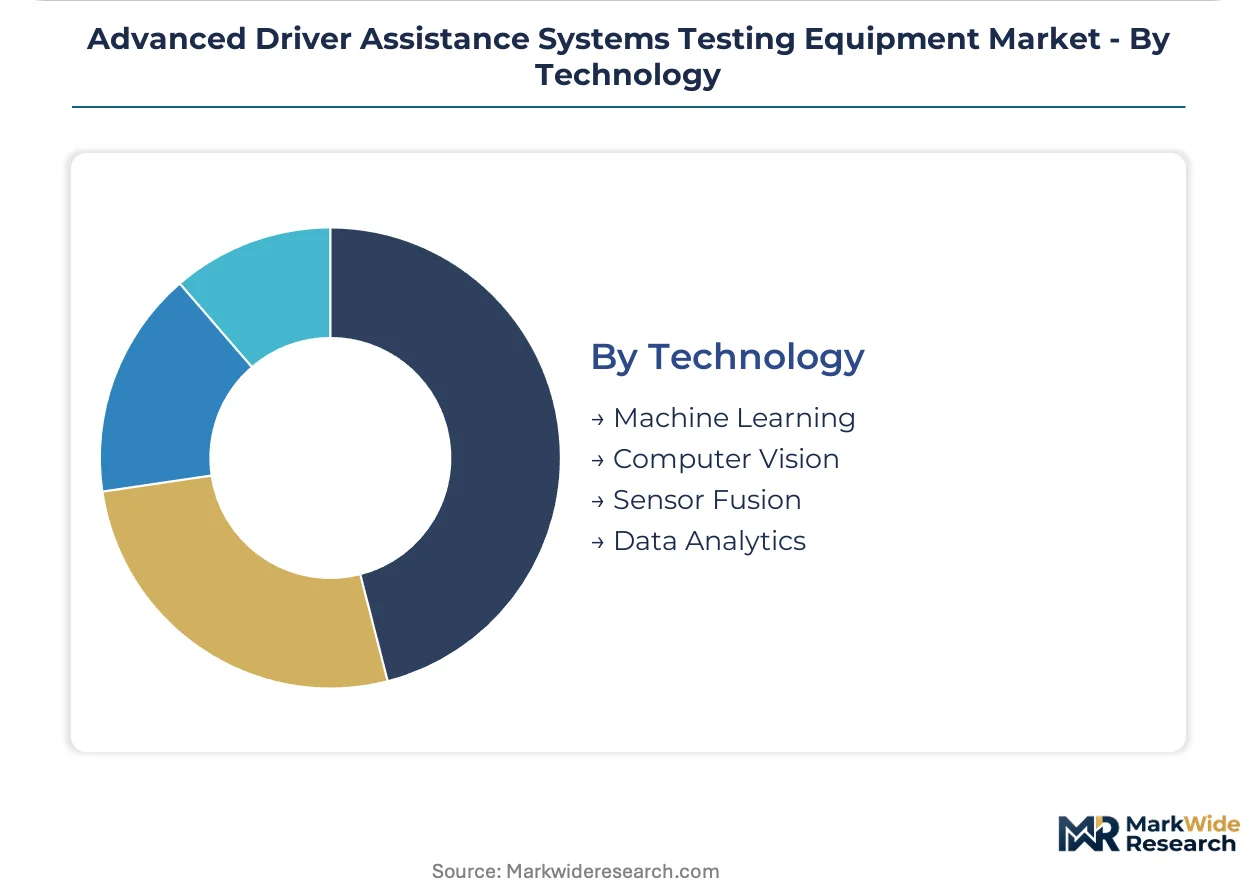
- Sensor Fusion:Multi-domain synchronization of camera, radar, and lidar inputs demands electromagnetic-optical-mechanical co-simulation expertise. TKH Group and National Instruments are capturing this demand through integrated platform architectures that unify previously separate hardware test budgets.
- Machine Learning:Training data provenance documentation and algorithmic decision boundary testing are emerging requirements under EU AI Act preparatory guidelines. European automotive AI validation frameworks are creating specialized demand for ML test tooling among German and French OEMs.
- Computer Vision:Image recognition validation for traffic sign and lane marking detection under variable illumination.
- Data Analytics:Test result aggregation and regression detection across large-scale scenario libraries.
Sensor fusion leads volumes today; machine learning is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in multi-physics simulation and RF signal processing anchor regional demand, concentrating procurement authority in automotive clusters with dense proving ground infrastructure.
Germany
KBA homologation requirements and Euro NCAP protocol development drive test equipment procurement across Bavarian and Baden-Württemberg automotive corridors. The EU AI Act preparatory guidelines are accelerating investment in machine learning validation frameworks among Stuttgart-based Tier-1 suppliers. Ingolstadt and Wolfsburg proving grounds are expanding lidar environmental chambers to meet expanded operational design domain testing mandates.
United States
NHTSA Federal Motor Vehicle Safety Standards for automatic emergency braking are forcing wider sensor coverage validation across Michigan and Arizona test facilities. The Inflation Reduction Act's domestic content provisions are pulling semiconductor test equipment manufacturing toward Southeast automotive corridors. Ann Arbor and Detroit laboratories are upgrading precipitation simulation chambers to address low-light and adverse weather performance requirements.
China
MIIT GB standards for intelligent connected vehicles are creating parallel certification demand for localized test configurations in Yangtze River Delta manufacturing zones. The country's dual carbon goals are accelerating virtual testing adoption to reduce physical prototype mileage in Shanghai and Shenzhen development centers. Beijing-Tianjin-Hebei corridor laboratories are expanding sensor fusion validation capacity for domestic OEM platform programs.
Japan
METI industrial standards for autonomous driving systems are consolidating radar and camera verification onto unified hardware-in-the-loop rigs among Nagoya-based suppliers. JIS certification requirements for automotive electronics are sustaining demand for high-purity RF signal generation components. Kanto region test houses are capturing validation-as-a-service demand from mid-tier component manufacturers with intermittent test requirements.
South Korea
MFDS alignment with international automotive safety standards is expanding pedestrian target simulator procurement across Seoul Capital Area testing laboratories. The country's national semiconductor strategy is concentrating sensor test equipment R&D in Gyeonggi-do research complexes. Busan-Ulsan automotive clusters are investing in portable hardware-in-the-loop systems to serve intermittent validation needs among emerging Tier-2 suppliers.
Advanced Driver Assistance Systems Testing Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the validation equipment spectrum. The vendor base separates between integrated platform architects sustaining multi-domain synchronization and point-solution specialists optimizing for single-sensor test coverage. Three archetypes dominate: German proving ground system integrators, modular instrumentation houses, and scenario-software pure-plays. Consolidation pressure is accelerating through strategic partnerships between hardware rig manufacturers and photorealistic rendering engine developers, while geographic expansion into China's MIIT certification market represents the dominant competitive move.
Within the integrated platform tier, TKH Group NV and National Instruments Corporation exemplify multi-domain test architecture providers. AVL LIST GmbH occupies a position among full-vehicle proving ground installation specialists where end-to-end traceability commands pricing power. These three entities represent the concentration of procurement authority among European and North American automakers consolidating previously discrete sensor benches into unified validation rigs.
| Leading Market Players |
|---|
| TKH Group NV |
| FEV Group GmbH |
| National Instruments Corporation |
| AVL LIST GmbH |
| AB Dynamics plc |
| Racelogic Limited |
| Konrad GmbH |
| Oxford Technical Solutions Ltd |
| Averna Technologies Inc |
| Others |
Supply Flow & Price Mechanics
Euro NCAP 2026 vulnerable road user mandates gate qualified supply for pedestrian target simulators and premium-tier pricing access for integrated hardware-in-the-loop rigs, compressing procurement options for laboratories without pre-certified environmental chamber configurations.
Pricing Analysis
Bundled validation-as-a-service offerings separate from unbundled perpetual-license software sales across the ADAS testing equipment landscape. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service intensity. Pricing pressure stems from virtual substitution thresholds below SAE Level 3, compressing margins for entry-level single-sensor benches. Tier-2 component suppliers exhibit highest price sensitivity, while OEM proving ground operations absorb premium tier costs for end-to-end traceability.
Supply Chain Analysis
Domestic content provisions in the United States Inflation Reduction Act and China's MIIT localization mandates are reshaping sourcing patterns for RF signal generation components and sensor target simulators. High-purity radar components concentrate in Germany and Japan, while photorealistic rendering engines draw from United States and United Kingdom software houses. Single-source vulnerability around specialized electromagnetic-optical-mechanical co-simulation expertise constrains integrated platform vendor expansion. Distribution runs through Tier-1 supplier procurement divisions and independent testing laboratory procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ADAS testing equipment margins expand through virtual testing displacement of physical prototype mileage, concentrating premium-tier demand among sensor fusion platform vendors while compressing addressable volume for point-solution providers.
For Market Incumbents: Anticipate regulatory fragmentation between NHTSA, ECE, and GB frameworks by investing in modular test architectures that accommodate protocol variations without hardware replacement. Vertical integration into scenario-generation software capabilities defends against pure-play algorithmic validation entrants. Certification investment for EU AI Act preparatory guidelines secures pricing power among Stuttgart-based Tier-1 suppliers. For New Entrants and Emerging Players: Begin with India's proving ground deficit as the most penetrable geography, deploying portable hardware-in-the-loop units for domestic OEMs with intermittent validation needs. Subscription-based scenario library access captures recurring revenue from Tier-2 suppliers lacking scenario-development resources. Channel partnership with established testing houses in Michigan and Germany accelerates credibility building without capital-intensive facility construction. For Investors and Strategic Acquirers: Roll-up economics work for scenario-software pure-plays because fragmented intellectual property ownership across European and North American developers creates consolidation value. Long-term viability centers on machine learning validation frameworks as SAE Level 4 programs displace rule-based test scripts. Watch NHTSA operational design domain expansion announcements as inflection indicators for environmental simulation chamber demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies previously discrete camera-radar-lidar test budgets for European OEM consolidation programs. |
| Scenario Library Subscription Model | Captures recurring revenue from Tier-2 suppliers with limited scenario-development resources. |
| Geographic Expansion into China | Addresses MIIT GB certification requirements for domestic intelligent connected vehicle programs. |
| Machine Learning Validation Framework Development | Documents training data provenance for EU AI Act preparatory guidelines among German OEMs. |
| Validation-as-a-Service Infrastructure | Offers time-shared sensor target simulator access to mid-tier component manufacturers in Michigan. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, testing laboratory technical directors, and aftermarket service heads with secondary validation against SEC filings, vehicle production databases, IHS Markit registration data, and Euro NCAP protocol documentation. Bottom-up equipment shipment estimates and top-down validation budget allocations were triangulated for segment sizing.
Comparable historical periods anchored the projection horizon across sensor modality, application intensity, end-user budget authority, and technology maturity dimensions. CAGRs were derived from regression analysis of capital expenditure patterns against regulatory mandate timelines. Modeled inputs included proving ground capacity expansion announcements, MIIT GB standard publication schedules, and NHTSA Federal Motor Vehicle Safety Standards advancement trajectories.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on semiconductor test equipment, unforeseen regulatory harmonization between NHTSA and ECE frameworks, and breakthrough advances in photorealistic rendering that collapse virtual-physical testing boundaries faster than projected. Forecasts reflect documented assumptions about OEM platform program cadence and Tier-1 supplier consolidation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive Driving Simulators Market