
 Electric Vehicle Test Bench Market | 2026-2036
Electric Vehicle Test Bench Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Test Bench Market Insights
800-volt architecture migration is rewriting powertrain validation protocols across the EV test bench landscape. AVL List GmbH leverages its Graz engineering heritage to dominate high-voltage dynamometer systems for European OEMs. HORIBA Ltd. anchors its position through deep integration of emissions and drivetrain testing under unified software platforms. Chroma ATE Inc. competes aggressively on battery cycler density and Taiwan-based manufacturing scale.
An electric vehicle test bench comprises integrated mechanical loading systems, electrical power analyzers, thermal chambers, and control software designed to simulate real-world driving cycles under laboratory conditions. These systems typically handle voltage ranges up to 1,000 V DC and power levels exceeding 300 kW for commercial vehicle applications, enabling repeatable validation of motor efficiency, battery degradation, and thermal boundaries. Hardware segments command the dominant revenue share due to capital-intensive dynamometer and battery cycler installations, while software layers are capturing margin pools through subscription-based test automation and predictive analytics. Powertrain testing technology leads volume adoption as OEMs internalize e-axle validation, whereas battery testing exhibits the steepest growth trajectory driven by cell chemistry diversification and solid-state prototyping cycles.
Europe's ECE R100 and REACH frameworks mandate granular thermal runaway documentation, compelling test bench vendors to embed multi-point temperature telemetry and gas detection arrays. China's NMPA enforces GB/T cycling protocols that extend test duration requirements, directly expanding installed base utilization rates. The US EPA and NHTSA coordinate on heavy-duty EV duty-cycle standardization, opening new application territory beyond passenger car norms. Stakeholders must weigh in-house validation buildout against specialized third-party lab partnerships as cell-to-pack architectures shorten development timelines.
Market Dynamics
800-volt platform proliferation is compressing validation timelines and forcing test bench architectures to handle higher thermal and electrical stress densities than legacy 400-volt systems permitted.
Growth Catalysts
- China's NMPA battery certification:GB/T cycling protocol extensions force OEMs to expand test capacity, directly lifting installed base utilization rates for cyclers and thermal chambers.
- Solid-state cell prototyping:Next-generation chemistry formats demand novel pressure, temperature, and formation test regimes that obsolete existing equipment.
- In-house validation buildout:Stuttgart and Munich engineering corridors concentrate OEM facility investments, reducing third-party lab dependency.
Market Restraints
- Copper and rare-earth magnet cost volatility:Dynamometer motor assemblies face input price swings that compress hardware margins.
- High-voltage safety certification backlog:ECE R100 compliance documentation delays equipment commissioning at European installations.
- Silicon carbide inverter substitution:Power electronics miniaturization threatens discrete power analyzer attachment rates.
Strategic Opportunities
- India's PLI scheme for automotive:Localized cell manufacturing mandates create greenfield test bench demand from domestic OEMs and suppliers.
- Heavy-duty commercial vehicle electrification:US EPA and NHTSA duty-cycle standardization opens power levels above 300 kW previously unaddressed by passenger-car optimized systems.
- Software-defined test automation:Subscription-based predictive analytics layers capture recurring revenue from hardware-installed bases.
Industry Challenges
- High-voltage systems engineering talent scarcity:Test bench vendors compete with OEMs and Tier-1 suppliers for engineers qualified in 1,000 V DC safety design.
- Cell-to-pack architecture integration complexity:Shortened development timelines compress the window for parallel module and pack-level validation.
- Multi-standard harmonization delays:Divergent US, European, and Chinese thermal runaway documentation formats inflate firmware development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Test Bench Market |
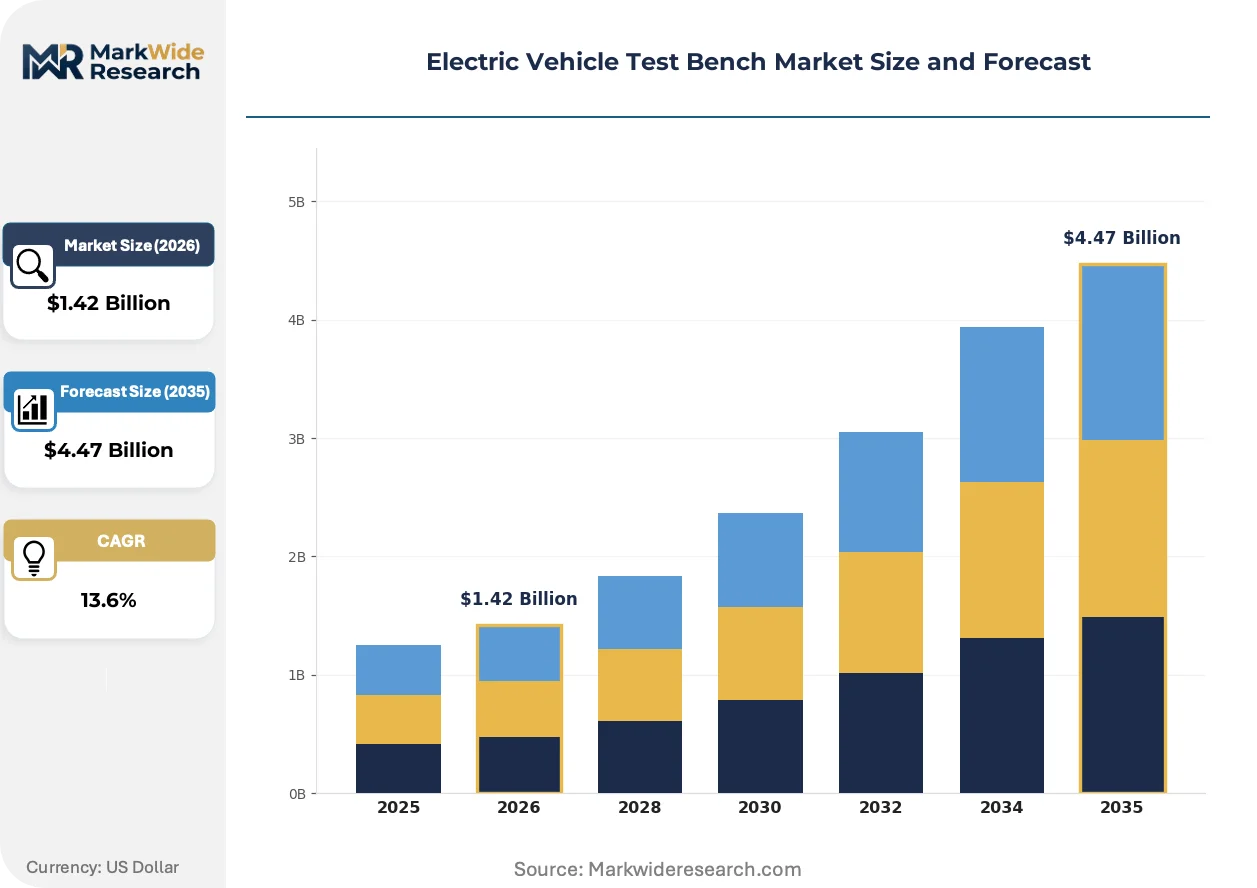
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Hybrid, Accessories End User: OEMs, Tier-1 Suppliers, Research Institutions, Aftermarket Providers Technology: Battery Testing, Powertrain Testing, Component Testing, Thermal Management Application: Prototype Development, Quality Assurance, Performance Testing, Compliance Verification |
| Companies Covered | AVL List GmbH, HORIBA Ltd., FEV, Chroma ATE Inc., ThyssenKrupp, Simpro, National Instruments Corporation, TUV Rheinland, Jiangsu Liance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Test Bench Market Trends and Innovations
Test bench architectures are converging around unified software platforms that collapse the traditional separation between powertrain, battery, and emissions validation workflows into single-environment execution.
Modular power electronics is collapsing the distinction between battery cycler and dynamometer power stages, enabling OEMs to reconfigure test cells for alternating motor and pack validation without hardware swaps. European engineering centers in Graz and Stuttgart are adopting these flexible architectures fastest, compressing capital deployment cycles from twelve to six months.
Europe's F-Gas Regulation and REACH frameworks now mandate granular refrigerant tracking and thermal runaway gas detection arrays embedded within test chamber designs. Equipment vendors serving German OEMs must integrate multi-point telemetry that documents cell venting signatures under abuse testing, adding sensor density requirements that reshape chamber mechanical specifications.
Buyers are consolidating procurement authority from distributed engineering groups into centralized validation centers that negotiate enterprise-wide test automation licenses. This concentration favors vendors with unified software platforms over point-solution hardware specialists, with the shift most visible across multi-brand automotive groups headquartered in Germany and Japan.
Electric Vehicle Test Bench Market Segmentation
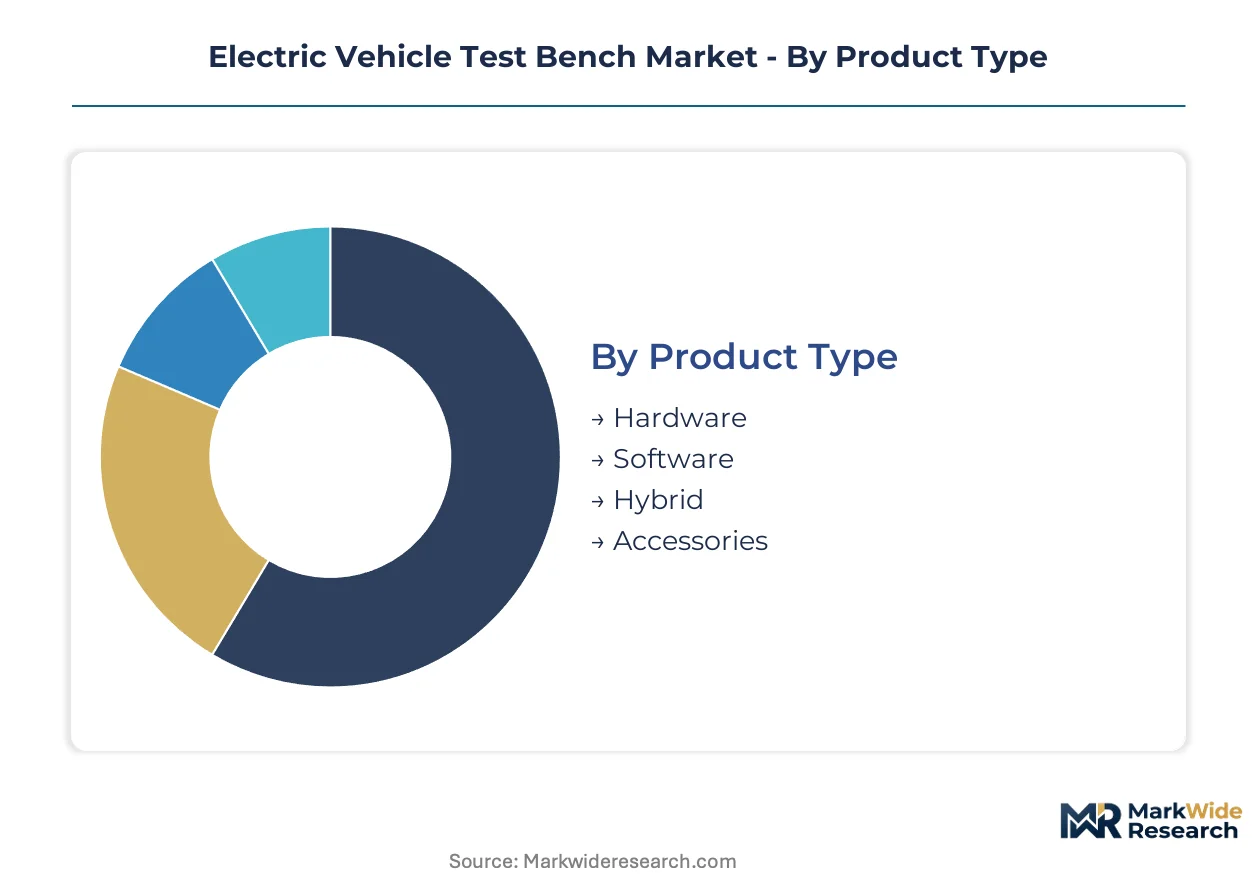
Test bench procurement patterns diverge sharply between capital-intensive hardware installations and recurring software licenses. Segment boundaries are blurring as modular architectures enable single platforms to span battery, powertrain, and thermal validation workflows.
Product Type:
Mature hardware installations dominate capital allocation while software layers capture expanding margin pools through subscription models.
- Hardware:Dynamometer assemblies, battery cyclers, and thermal chambers constitute the capital core, with voltage ratings now standardizing at 1,000 V DC to accommodate 800-volt platform proliferation. German OEMs in Stuttgart and Munich are driving replacement cycles as legacy 400-volt equipment reaches obsolescence.
- Software:Test automation platforms and predictive analytics layers extract recurring revenue from installed hardware bases through enterprise licensing. AVL List GmbH and HORIBA Ltd. are consolidating procurement authority by unifying powertrain, battery, and emissions workflows under single-environment execution.
- Hybrid:Bundled hardware-software contracts reduce commissioning friction for greenfield validation centers.
- Accessories:Sensor arrays, cabling harnesses, and calibration tools complete test cell configurations.
Hardware handles the majority of throughput; software is the fastest mover on share.
End User:
Customer concentration tilts toward entities with captive validation volume and multi-year development pipelines.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz are expanding in-house capacity across Germany's engineering corridor to reduce third-party dependency and protect intellectual property around cell-to-pack architectures.
- Tier-1 Suppliers:Bosch and Continental leverage test benches to validate e-axle and inverter designs before OEM integration, with facilities concentrated around Stuttgart.
- Research Institutions:Fraunhofer institutes and technical universities access subsidized equipment for solid-state prototyping and thermal runaway characterization.
- Aftermarket Providers:Independent labs serve regional OEMs lacking capital for full in-house buildout, particularly in India's emerging EV manufacturing clusters.
OEMs command the largest equipment budgets; Tier-1 suppliers are expanding capacity most aggressively.
Technology:
Technology selection tracks the voltage and thermal stress densities of target vehicle platforms.
- Battery Testing:Cyclers and formation chambers handle cell chemistry validation, pressure testing, and GB/T protocol compliance for China's NMPA certification. Solid-state prototyping is forcing equipment upgrades as existing chambers lack the pressure telemetry and thermal precision that next-generation formats demand.
- Powertrain Testing:E-axle dynamometers simulate real-world driving cycles under laboratory conditions, with European ECE R100 compliance documentation adding commissioning delays due to high-voltage safety certification backlogs.
- Component Testing:Discrete validation of inverters, motors, and DC-DC converters supports modular procurement strategies.
- Thermal Management:Chambers with multi-point temperature telemetry and gas detection arrays satisfy Europe's REACH and F-Gas Regulation mandates for thermal runaway documentation.
Powertrain testing leads installed base volume; battery testing shows the steepest expansion trajectory.
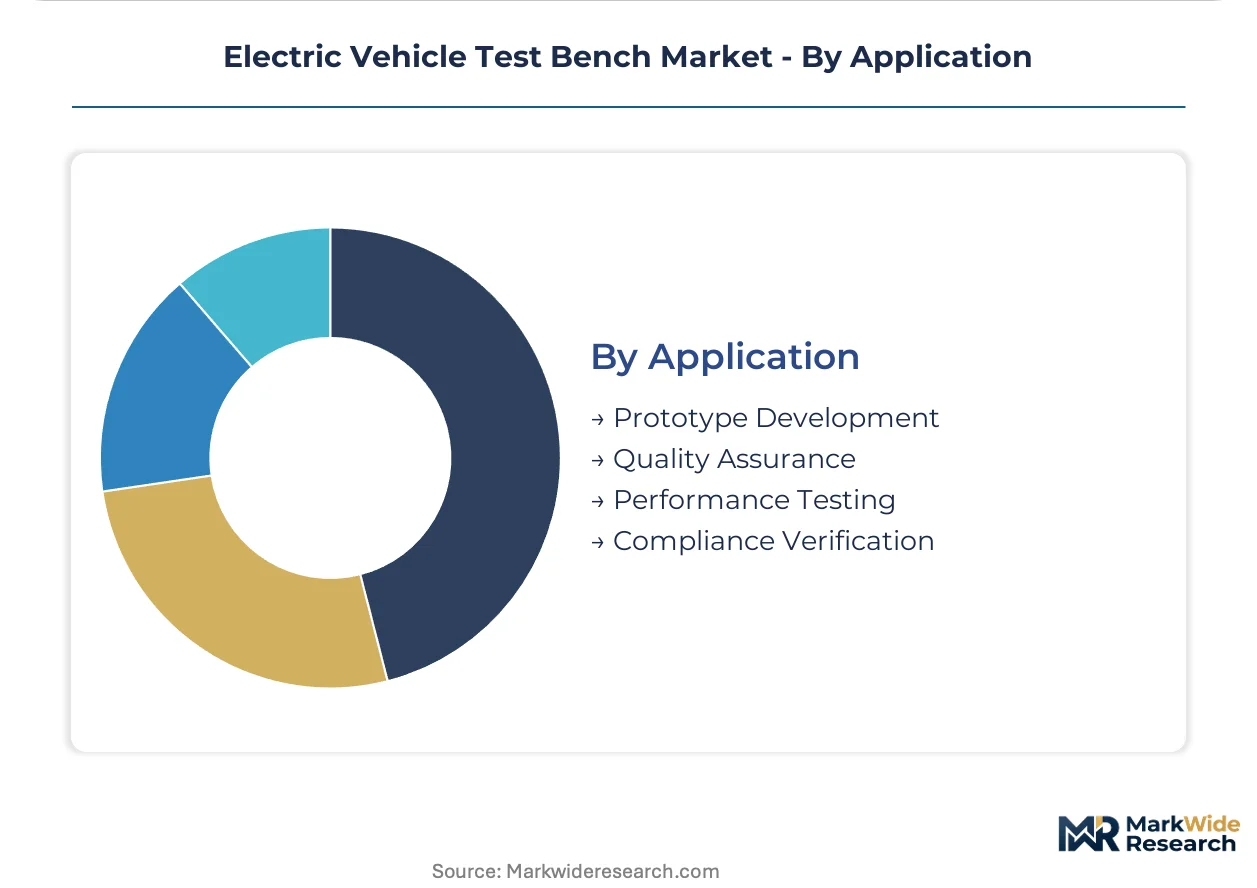
Application:
Application priority shifts with product lifecycle stage and regulatory exposure.
- Prototype Development:Early-stage validation of 800-volt architectures and solid-state cell formats requires flexible test cell reconfiguration capabilities.
- Quality Assurance:Production-line testing ensures motor efficiency and battery degradation remain within specification across manufacturing variance.
- Performance Testing:Dynamometer-based efficiency mapping and thermal boundary validation support marketing claims and warranty pricing.
- Compliance Verification:GB/T cycling protocol extensions in China and ECE R100 thermal runaway documentation in Europe extend test duration requirements and expand utilization rates.
Compliance verification absorbs the most incremental capacity; prototype development commands the highest equipment specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German test bench exports flow primarily to Chinese OEMs building in-house validation capacity, while Taiwanese hardware manufacturers supply cyclers to European engineering centers seeking cost-competitive battery formation equipment.
Germany
Stuttgart and Munich engineering corridors concentrate Volkswagen Group, BMW, and Mercedes-Benz facility investments. ECE R100 compliance documentation mandates extend commissioning timelines for high-voltage installations. Baden-Württemberg hosts AVL List GmbH and multiple Tier-1 supplier validation centers.
China
NMPA battery certification drives GB/T cycling protocol demand across domestic OEMs and joint ventures. MIIT production quotas for new energy vehicles expand test capacity requirements. Yangtze River Delta clusters around Shanghai and Ningbo concentrate greenfield validation center construction.
United States
EPA and NHTSA coordination on heavy-duty EV duty-cycle standardization opens power levels above 300 kW. Michigan and California engineering centers expand prototype development capacity. Detroit-area facilities focus on commercial vehicle electrification validation.
Japan
METI subsidies for solid-state battery R&D force equipment upgrades for pressure and thermal precision requirements. Kansai and Chubu regions host Toyota and Honda validation facilities. Nagoya engineering centers specialize in e-axle dynamometer installations.
India
PLI scheme automotive incentives create greenfield demand from domestic OEMs and cell manufacturers. Tamil Nadu and Gujarat manufacturing corridors attract test bench investments. Chennai and Ahmedabad validation centers serve emerging EV production clusters.
Electric Vehicle Test Bench Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. European engineering heritage confers advantage in high-voltage dynamometer specifications. Three archetypes dominate: integrated platform vendors, hardware-specialist fabricators, and software-layer providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate validation center procurement.
Among Austria-based integrated platform vendors, AVL List GmbH occupies a position exemplifying engineering-heritage dominance in European OEM relationships. Japanese precision instrumentation specialists include HORIBA Ltd., which anchors the emissions-drivetrain convergence archetype. Taiwanese hardware fabricators are represented by Chroma ATE Inc., sitting within the manufacturing-scale battery cycler segment.
| Leading Market Players |
|---|
| AVL List GmbH |
| HORIBA Ltd. |
| FEV |
| Chroma ATE Inc. |
| ThyssenKrupp |
| Simpro |
| National Instruments Corporation |
| TUV Rheinland |
| Jiangsu Liance |
| Others |
Pricing and Supply Chain Analysis
Copper and rare-earth magnet cost volatility determines both pricing tier spreads and supply chain shape across the electric vehicle test bench landscape, compressing hardware margins while forcing buyers toward longer-term contracting structures that lock in component availability.
Pricing Analysis
The 800-volt versus 400-volt equipment pricing gap now spans three distinct technology generations, with legacy dynamometer systems trading at standard rates while next-generation 1,000 V DC platforms command premium positioning due to silicon carbide inverter integration and enhanced thermal management specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ECE R100-compliant systems carrying measurable premiums over baseline configurations. Pricing pressure stems from Taiwanese battery cycler manufacturers compressing hardware margins through manufacturing scale. Tier-1 suppliers exhibit highest price sensitivity due to volume procurement mandates, while OEM captive validation centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for European test bench deployments, with Taiwanese hardware fabricators serving as alternative sourcing nodes for battery formation equipment. Manufacturing concentration centers on Germany, Taiwan, and Japan, with dynamometer motor assemblies drawing from Japanese precision engineering and thermal chamber fabrication resting on German mechanical specifications. Copper winding stock, rare-earth permanent magnets, and silicon carbide power modules constitute critical input dependencies. Single-source vulnerability persists around 1,000 V DC safety-rated contactors and specialized high-voltage telemetry sensors. Distribution runs through direct OEM procurement channels for large installations, with regional distributor networks serving aftermarket providers and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle test bench market sits in a cyclical recovery phase driven by 800-volt platform proliferation forcing replacement cycles across European and Asian OEM validation centers.
For Market Incumbents: Insulate installed base revenue through subscription-based test automation software layers that capture recurring licensing from hardware deployments. Deepen backward integration into high-voltage safety component manufacturing to offset copper and magnet cost volatility. Prioritize certification investment for ECE R100 and GB/T compliance documentation capabilities that extend commissioning timelines and reduce competitive substitution risk from emerging hardware fabricators.
For New Entrants and Emerging Players: India's PLI scheme automotive incentives represent the most penetrable entry point for greenfield validation center construction serving domestic OEMs and cell manufacturers lacking established supplier relationships. Heavy-duty commercial vehicle electrification above 300 kW power levels offers white-space territory previously unaddressed by passenger-car optimized incumbents. Pursue partnership-based go-to-market positioning with established European software platform vendors to bypass hardware certification backlogs.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated platform vendors with unified software-hardware execution capabilities over point-solution specialists. Long-term viability across the analysis window hinges on predictive analytics subscription attach rates rather than transactional hardware margins. Acquisition target archetype: modular power electronics specialists enabling test cell reconfiguration without hardware swaps. The signal to watch is solid-state battery prototyping volume triggering equipment upgrade cycles that obsolete legacy thermal chamber installations.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Platform Standardization | 1,000 V DC equipment specifications align with Porsche and Hyundai 800-volt architectures. |
| Battery Supply Agreement | Long-term cycler procurement contracts secure capacity for CATL and BYD formation testing. |
| Software-Defined Test Automation Investment | Unified platforms capture enterprise licensing from Volkswagen Group validation centers. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat facilities serve India's PLI scheme automotive incentives. |
| Charging Infrastructure Partnership | Heavy-duty duty-cycle validation opens 300+ kW power levels for commercial vehicle electrification. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, test bench system integrators, and thermal management specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of publicly traded equipment vendors, and NMPA certification disclosure records. Bottom-up segment sizing triangulated against top-down industry expenditure estimates from automotive engineering consortium disclosures.
Scenario-bracketing framed analytical approach across the projection horizon, with conservative and expansion cases reflecting divergent solid-state battery prototyping timelines and 800-volt platform adoption curves. Segmentation dimensions modeled included vehicle class, propulsion architecture, voltage tier, OEM captive versus third-party validation sourcing, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield capacity announcements. Industry-specific forecast inputs incorporated GB/T protocol extension mandates and ECE R100 thermal runaway documentation requirements.
Macroeconomic conditions sit as an overlay; deviation in copper pricing, rare-earth magnet export restrictions, or automotive capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and cell-to-pack architecture proliferation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market