
 United Arab Emirates Used Car Market | 2026-2036
United Arab Emirates Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Used Car Market Analytics
Buyer concentration among fleet operators and corporate leasing clients is realigning volume toward multi-unit procurement contracts. AW Rostamani Group leverages its franchise network to capture institutional fleet turnover, while Al Futtaim Automall anchors certified pre-owned supply through manufacturer-backed refurbishment programs. Sun City Motors specializes in high-end pre-owned imports, differentiating on inspection depth and warranty terms.
Used cars in the UAE comprise previously registered vehicles traded through dealer channels, private sales, or auction platforms, typically subjected to roadworthiness testing under federal vehicle inspection standards before re-registration. The primary commercial purpose centers on maximizing asset utility across multiple ownership cycles while reducing per-kilometer depreciation exposure for subsequent buyers. SUV and sedan segments dominate transaction flow, with certified pre-owned vehicles commanding margin premiums due to extended warranty coverage and documented service histories. Franchise dealerships occupy the highest trust tier, though online platforms are accelerating price discovery and compressing geographic arbitrage between emirates.
MOHAP oversees consumer protection frameworks affecting warranty disclosures and odometer verification, while the Emirates Authority for Standardization and Metrology sets periodic technical inspection mandates that filter non-compliant units from resale channels. These standards elevate compliance costs for independent dealers but reinforce certified channel credibility. Stakeholders must monitor evolving federal vehicle emissions benchmarks and digital platform licensing requirements as regulatory scope widens beyond physical inspection to encompass online transaction transparency and data privacy obligations.
Market Dynamics
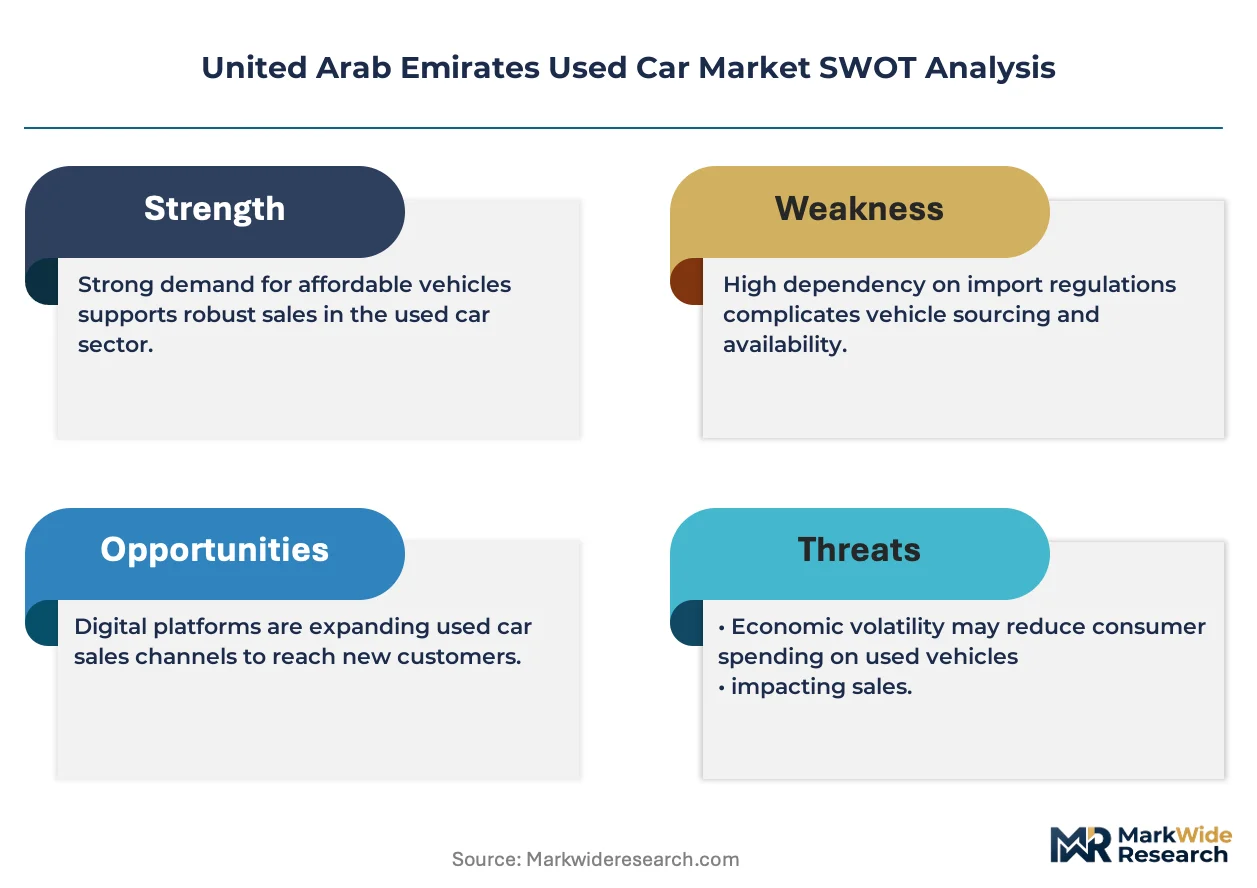
Fleet operators and ride-hailing platforms are consolidating procurement into multi-unit contracts, compressing dealer margins while elevating volume-based negotiation leverage across Dubai and Abu Dhabi.
Growth Catalysts
- Ride-hailing fleet expansion:Platform operators are scaling pre-owned vehicle deployment to optimize total cost of ownership across high-utilization duty cycles.
- Emirates Authority for Standardization and Metrology inspection tightening:Roadworthiness criteria elevation filters substandard inventory, reinforcing certified pre-owned channel credibility.
- Digital auction liquidity:Online platforms are deepening price discovery and compressing inter-emirate arbitrage windows for dealer networks.
Market Restraints
- Import documentation friction:Gulf Cooperation Council customs harmonization gaps delay high-end pre-owned vehicle clearance at Jebel Ali.
- Inspection compliance cost concentration:Independent dealers face margin compression from federal testing mandates without manufacturer refurbishment subsidies.
- Electric vehicle residual uncertainty:Battery degradation assessment standardization lags are damping secondary-market liquidity for hybrid and EV inventory.
Strategic Opportunities
- Sharjah and Northern Emirates penetration:Dealer network density remains below Dubai-Abu Dhabi levels, creating first-mover positioning for certified channel expansion.
- Subscription-to-ownership conversion:Fleet operators are piloting lease-end buyout programs that channel drivers into certified pre-owned purchases.
- MOHAP digital transaction transparency mandates:Evolving consumer protection frameworks will advantage platforms with integrated odometer verification and warranty disclosure systems.
Industry Challenges
- Vehicle history data integration:Fragmented service records across independent garages complicate certified pre-owned documentation standards.
- Skilled inspection technician scarcity:Advanced diagnostic capability for hybrid powertrains outpaces vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Used Car Market |
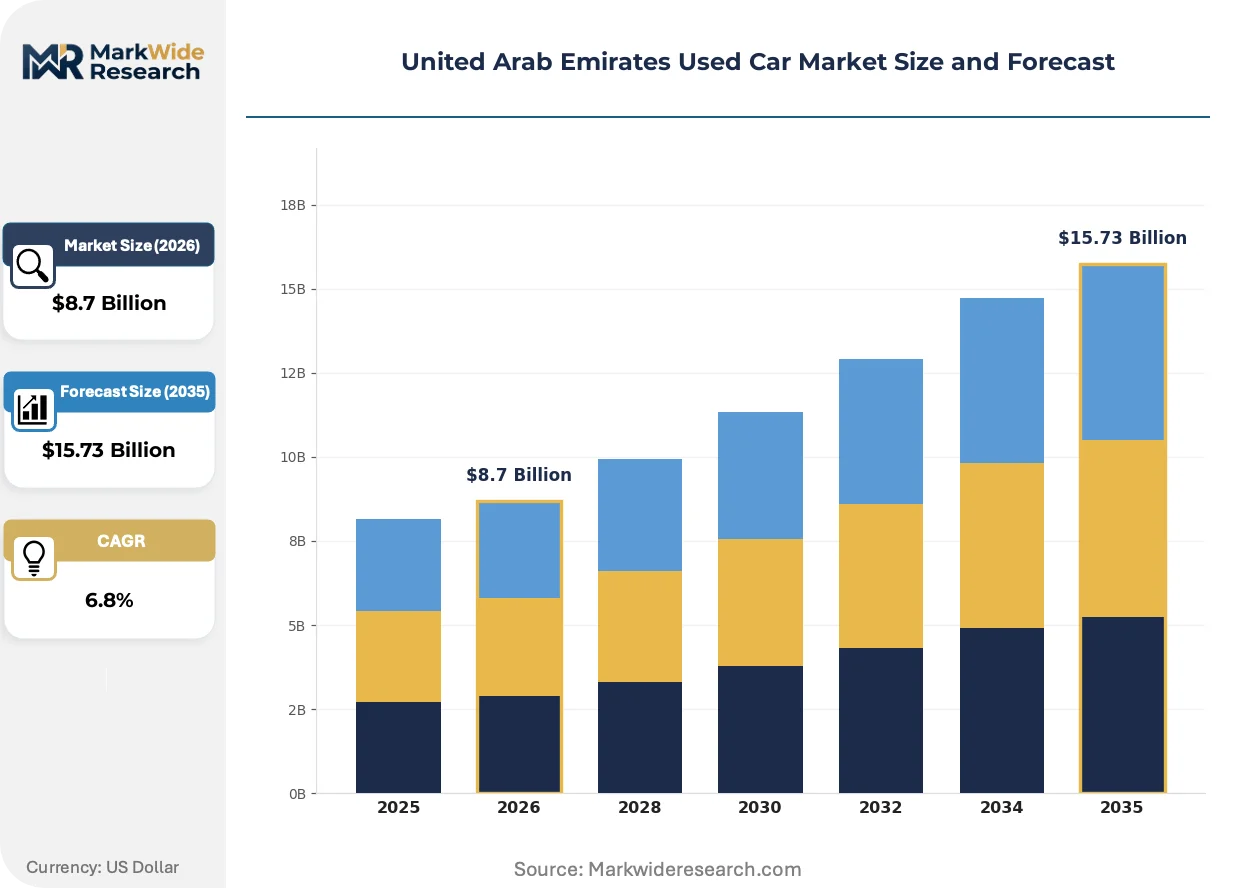
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Condition: Certified Pre-Owned, Non-Certified, As-Is, Refurbished Dealership Type: Franchise, Independent, Online, Auction |
| Companies Covered | CarSwitch, Laith Al Obaidi Motors, Approved Automotive, AW Rostamani Group, Al Tayer Motors, Al Futtaim Automall, Exotic Cars, Al Nabooda Automobiles, Sun City Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Used Car Market Evolving Landscape
Digital infrastructure is reconfiguring how inventory moves from auction to end-buyer, with artificial intelligence and regulatory digitization compressing transaction timelines.
Artificial intelligence valuation engines are automating depreciation curve modeling and real-time pricing adjustments. Fleet disposal managers and franchise dealers are adopting these tools at accelerating rates. The technology is automating price discovery that previously required manual comparable searches and regional dealer network consultation.
MOHAP consumer protection frameworks are expanding into digital platform oversight, mandating odometer verification and warranty disclosure transparency. Independent dealers face compliance cost escalation without manufacturer-backed documentation systems. Dubai-based digital marketplaces are responding by integrating federal inspection data feeds directly into listing interfaces.
Corporate leasing clients are consolidating procurement into multi-year fleet turnover agreements with guaranteed buyback terms. Traditional spot-market dealer transactions are losing share to structured disposal contracts in Abu Dhabi. This concentration is most visible among ride-hailing operators seeking standardized vehicle age profiles across operating territories.
United Arab Emirates Used Car Market Segmentation
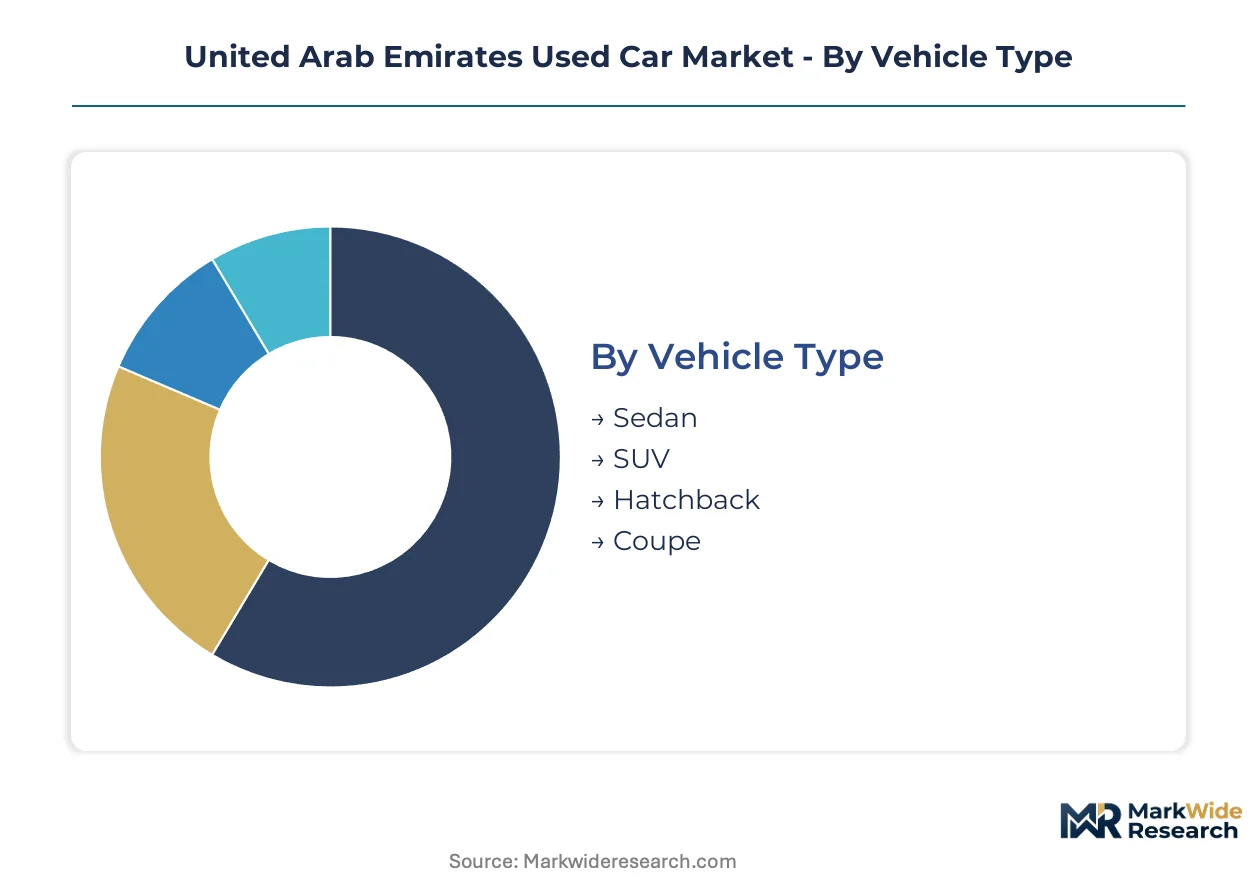
Segmentation in the UAE used car market reveals how procurement patterns diverge across vehicle specifications, certification tiers, and distribution channels. Fleet operators, private buyers, and digital platforms each gravitate toward distinct combinations of these attributes, creating specialized liquidity pools within Dubai and Abu Dhabi.
Vehicle Type:
Customization versus standardization tension runs deepest here, with body style selection directly constraining resale velocity and refurbishment economics.
- Sedan:Three-box configurations dominate corporate fleet procurement due to predictable depreciation curves and established service networks. Demand concentrates among ride-hailing operators in Dubai seeking standardized vehicle age profiles for platform compliance.
- SUV:Higher ground clearance and cabin versatility attract family buyers and executive transport services across Abu Dhabi. The segment commands refurbishment investment from franchise dealers targeting certified pre-owned premiums.
- Hatchback:Compact footprints suit urban density constraints in Sharjah and Northern Emirates municipalities.
- Coupe:Two-door configurations circulate through specialist importers like Sun City Motors with extended warranty differentiation.
Leading the category by volume: SUV. Growing fastest: Sedan.
Fuel Type:
Cost tier stratification separates segments here, with total cost of ownership calculations diverging sharply across duty cycle intensity.
- Petrol:Internal combustion engines with established supply chains dominate auction throughput. Demand concentrates in independent dealer channels across Dubai where inspection compliance costs weigh less heavily on margin structures.
- Diesel:Compression-ignition powertrains retain residual value among commercial fleet operators optimizing for highway fuel economy. The segment faces Emirates Authority for Standardization and Metrology emissions scrutiny tightening resale eligibility.
- Electric:Battery electric vehicles encounter secondary-market liquidity constraints pending degradation assessment standardization.
- Hybrid:Dual-powertrain configurations attract environmentally conscious private buyers in Abu Dhabi with manufacturer warranty transferability.
Dominating transaction flow: Petrol. Expanding most quickly: Hybrid.
Condition:
Application severity divides this category, with utilization intensity determining which certification tier buyers prioritize.
- Certified Pre-Owned:Manufacturer-backed refurbishment with documented service histories and extended warranty coverage. Demand concentrates among corporate leasing clients in Dubai seeking standardized disposal terms and guaranteed buyback structures.
- Non-Certified:Dealer-sold inventory without manufacturer warranty backing trades at discount to certified equivalents. The segment attracts price-sensitive private buyers in Northern Emirates with lower inspection compliance cost exposure.
- As-Is:Unwarranted sales without refurbishment investment circulate through auction platforms and private transactions.
- Refurbished:Independent garage restoration without manufacturer certification occupies mid-tier pricing.
Commanding margin premiums: Certified Pre-Owned. Gaining share fastest: Refurbished.
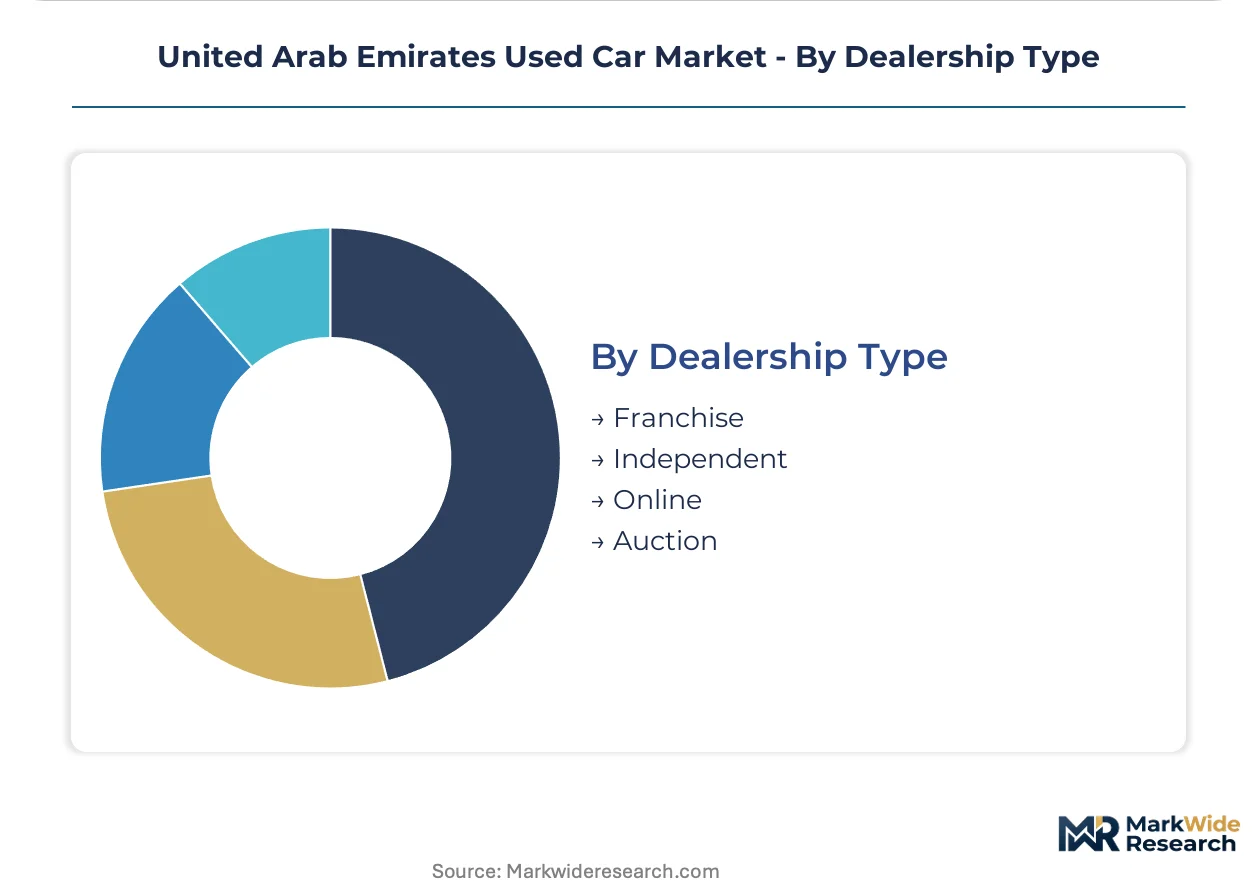
Dealership Type:
Customer type concentration shapes competitive positioning here, with procurement scale determining channel selection.
- Franchise:Manufacturer-affiliated networks like AW Rostamani Group and Al Futtaim Automall anchor certified pre-owned supply through integrated refurbishment programs. Institutional fleet turnover flows disproportionately through these channels in Abu Dhabi.
- Independent:Unaffiliated dealers compete on price discovery without manufacturer subsidy for inspection compliance costs. The segment serves cash buyers in Sharjah with lower documentation requirements.
- Online:Digital marketplaces integrate federal inspection data feeds for odometer verification transparency.
- Auction:Wholesale disposal platforms accelerate price discovery for fleet operators managing multi-unit turnover.
Highest trust tier: Franchise. Deepening liquidity fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement contracts concentrate in Dubai and Abu Dhabi, where ride-hailing platforms and corporate leasing clients drive multi-unit vehicle turnover. Northern Emirates present untapped network density for certified pre-owned expansion.
Dubai
Ride-hailing operators like Careem and Uber scale pre-owned fleet deployment to optimize total cost of ownership across high-utilization duty cycles. MOHAP consumer protection frameworks mandate odometer verification and warranty disclosure transparency for digital platforms. Al Quoz industrial corridor hosts refurbishment clusters where franchise dealers integrate manufacturer-backed programs.
Abu Dhabi
Corporate leasing clients consolidate procurement into multi-year fleet turnover agreements with guaranteed buyback terms. The Emirates Authority for Standardization and Metrology enforces periodic technical inspection mandates that filter non-compliant units from resale channels. Mussafah automotive zone anchors certified pre-owned supply chains serving government and institutional fleets.
Sharjah
Price-sensitive private buyers favor non-certified dealer channels with lower inspection compliance cost exposure. Federal vehicle inspection standards apply uniformly, though enforcement density remains below Dubai-Abu Dhabi levels. Industrial areas near Sharjah International Airport concentrate independent importers specializing in high-volume hatchback transactions.
Northern Emirates
Urban density constraints in Ras Al Khaimah and Fujairah municipalities sustain demand for compact vehicle formats. Emirates Authority for Standardization and Metrology roadworthiness criteria apply, but certified channel penetration lags major metros. Dealer network expansion into these emirates offers first-mover positioning as digital platforms extend coverage.
United Arab Emirates Used Car Market Competitive Landscape
Dubai-based franchise networks anchor the premium tier; Abu Dhabi specialists hold institutional fleet relationships. Market structure splits between manufacturer-affiliated refurbishment programs and independent dealers competing on price discovery. Three archetypes dominate: integrated automotive groups with multi-brand franchise rights, digital-native marketplaces with inspection data integration, and specialist importers focused on luxury pre-owned segments. Competitive moves center on geographic expansion into underserved emirates and technology licensing for AI-powered valuation engines.
Within the integrated automotive group tier, AW Rostamani Group and Al Futtaim Automall exemplify franchise-backed certified pre-owned positioning. Sun City Motors occupies the specialist importer archetype, differentiating on high-end pre-owned sourcing and extended warranty terms. These three entities represent contrasting scale and specialization strategies across the UAE market.
| Leading Market Players |
|---|
| CarSwitch |
| Laith Al Obaidi Motors |
| Approved Automotive |
| AW Rostamani Group |
| Al Tayer Motors |
| Al Futtaim Automall |
| Exotic Cars |
| Al Nabooda Automobiles |
| Sun City Motors |
| Others |
Value Network & Pricing Analysis
Family-owned dealer networks across Dubai and Abu Dhabi anchor inventory sourcing while exerting disciplined margin management through certified pre-owned refurbishment programs. Their concentrated procurement power shapes pricing tiers that separate franchise-backed vehicles from independent dealer inventory.
Pricing Analysis
Volume procurement by fleet operators compresses per-unit margins while elevating total contract values across multi-year agreements. Three-tier pricing structure across certified pre-owned, refurbished independent, and as-is auction tiers separates warranty-backed inventory from undocumented units. Pricing pressure stems from Emirates Authority for Standardization and Metrology inspection compliance costs that independent dealers absorb without manufacturer subsidy. Corporate leasing clients exhibit lowest price sensitivity due to standardized disposal terms, while Sharjah private buyers prioritize upfront cost minimization over certification premiums.
Supply Chain Analysis
Certification gating through federal inspection mandates filters substandard inventory before channel entry, elevating refurbishment cost structures for non-franchise operators. Vehicle sourcing concentrates in Japan, South Korea, and Germany as primary export markets for UAE pre-owned imports. Supply chains draw from auction platforms, lease-end returns, and direct fleet disposals as core inventory inputs. Single-source vulnerability emerges where digital platforms control price discovery algorithms without transparent comparable data. Distribution runs through franchise dealer networks for certified inventory and online marketplaces for price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE used car market sits at a technology-transition inflection where artificial intelligence valuation engines displace manual comparable searches and regional dealer network consultation.
For Market Incumbents: Deepen vertical integration into refurbishment capacity at Al Quoz and Mussafah industrial clusters to capture certified pre-owned premiums. Expand proprietary inspection data feeds ahead of MOHAP digital transparency mandates that will disadvantage non-integrated competitors. Franchise networks must lock in multi-year fleet turnover agreements before ride-hailing operators consolidate procurement further. For New Entrants and Emerging Players: Launch via digital-native marketplaces with integrated odometer verification and federal inspection data feeds to exploit compliance cost gaps facing independent dealers. Target Sharjah and Northern Emirates where certified channel penetration lags Dubai-Abu Dhabi density. White-space exists in subscription-to-ownership conversion programs piloting lease-end buyout structures for fleet drivers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist importers with luxury pre-owned sourcing capabilities and extended warranty infrastructure in Dubai. Long-term viability hinges on positioning for electric vehicle secondary-market liquidity once battery degradation assessment standardization resolves. The signal to watch is Emirates Authority for Standardization and Metrology expansion of emissions criteria that could strand diesel inventory and accelerate hybrid powertrain demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI Valuation Engine Deployment | Automated depreciation modeling compresses price discovery timelines for fleet disposal managers. |
| Certified Pre-Owned Network Expansion | Franchise dealers capture margin premiums through manufacturer-backed refurbishment programs. |
| Digital Platform Integration | Online marketplaces embed federal inspection data to satisfy MOHAP transparency mandates. |
| Geographic Footprint Extension | First-mover positioning in Sharjah and Northern Emirates exploits certified channel gaps. |
| Subscription-to-Ownership Conversion | Fleet operators channel lease-end drivers into structured certified pre-owned purchases. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet procurement managers, franchise dealership operations heads, independent dealer principals, and digital platform executives combined with secondary validation. Secondary sources encompassed Emirates Authority for Standardization and Metrology inspection protocols, MOHAP consumer protection frameworks, customs clearance records at Jebel Ali, and vehicle registration databases. Bottom-up transaction volume estimates triangulated against top-down market sizing.
Granularity-level modeling segmented volume and value across vehicle type, fuel architecture, certification tier, and dealership channel throughout the projection horizon. Propulsion architecture splits between petrol, diesel, hybrid, and electric captured diverging total cost of ownership calculations. Dealership type differentiation modeled franchise, independent, online, and auction channel shares. CAGRs derived from trend extrapolation adjusted for regulatory phase-ins and technology adoption curves. Fleet turnover rates and ride-hailing platform procurement schedules served as demand-side forecast inputs.
Regulatory enforcement variance, electric vehicle residual value volatility, and ride-hailing platform consolidation pace are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding inspection standardization timelines and hybrid powertrain adoption trajectories. A model refresh is warranted upon material change in Emirates Authority for Standardization and Metrology roadworthiness criteria or battery degradation assessment protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Kenya Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Germany Used Car Market