
 Multispace Parking Meter Market | 2026-2036
Multispace Parking Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Multispace Parking Meter Market Foresight
Subscription-based software licensing for parking enforcement and dynamic pricing is broadening the revenue model beyond hardware sales. Flowbird Group leverages its cloud-native platform architecture to anchor recurring service contracts across European city networks. IPS Group sustains technology leadership through in-house production of solar-powered meter assemblies with integrated cellular modems. Hectronic GmbH competes on manufacturing scale, operating dedicated production lines for multi-space kiosks serving German municipal authorities.
A multispace parking meter is a centralized payment and enforcement terminal serving multiple adjacent parking bays, typically incorporating LCD displays, proximity card readers, license plate recognition cameras, and wireless communication modules operating on 4G or LoRaWAN protocols. The device manages time-restricted curb access while transmitting occupancy data to municipal traffic management centers. Smart meters command the dominant share of new procurement budgets as cities phase out mechanical coin mechanisms, while mobile payments represent the fastest-expanding transaction modality, displacing cash acceptance in surface lot installations across municipal and commercial end-user segments.
CE marking under the EU Radio Equipment Directive governs wireless connectivity compliance for European deployments, while FCC Part 15 certification controls electromagnetic emissions for units installed in the United States. The EU Green Deal's embodied carbon requirements for public infrastructure procurement are beginning to shape supplier qualification criteria and material selection decisions. Stakeholders must weigh hardware refresh timelines against evolving interoperability standards for curb data exchange as cities consolidate vendor ecosystems.
Market Dynamics
Contactless payment mandates from municipal transit authorities are compressing hardware refresh cycles and forcing networked meter architectures into legacy curb management infrastructure.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Wireless connectivity compliance standardization accelerates cross-border procurement for European municipal networks.
- Mobile wallet integration:NFC and QR-code payment modalities reduce cash handling costs for city parking authorities.
- Solar-powered meter assemblies:Embedded photovoltaic cells with integrated cellular modems eliminate trenching for electrical infrastructure.
Market Restraints
- Cellular modem supply concentration:Semiconductor fabrication bottlenecks in East Asian foundries constrain production scaling for IoT communication modules.
- License plate recognition camera costs:Optical sensor arrays and edge-computing processors inflate unit manufacturing expenses.
- Mechanical coin mechanism substitution:Cash-accepting legacy meters retain installed base in lower-density municipal jurisdictions.
Strategic Opportunities
- EU Green Deal embodied carbon requirements:Public infrastructure procurement criteria favor low-carbon aluminum enclosures and recycled polymer housings.
- LoRaWAN protocol convergence:Unlicensed spectrum networks merge with 4G cellular backhaul for redundant connectivity in underground installations.
- Dynamic pricing software licensing:Cloud-native enforcement platforms generate recurring revenue beyond one-time hardware sales.
Industry Challenges
- FCC Part 15 certification timelines:Electromagnetic emissions testing for United States deployments extends product launch schedules.
- Interoperability standard fragmentation:Curb data exchange protocols lack unified specifications across municipal vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multispace Parking Meter Market |
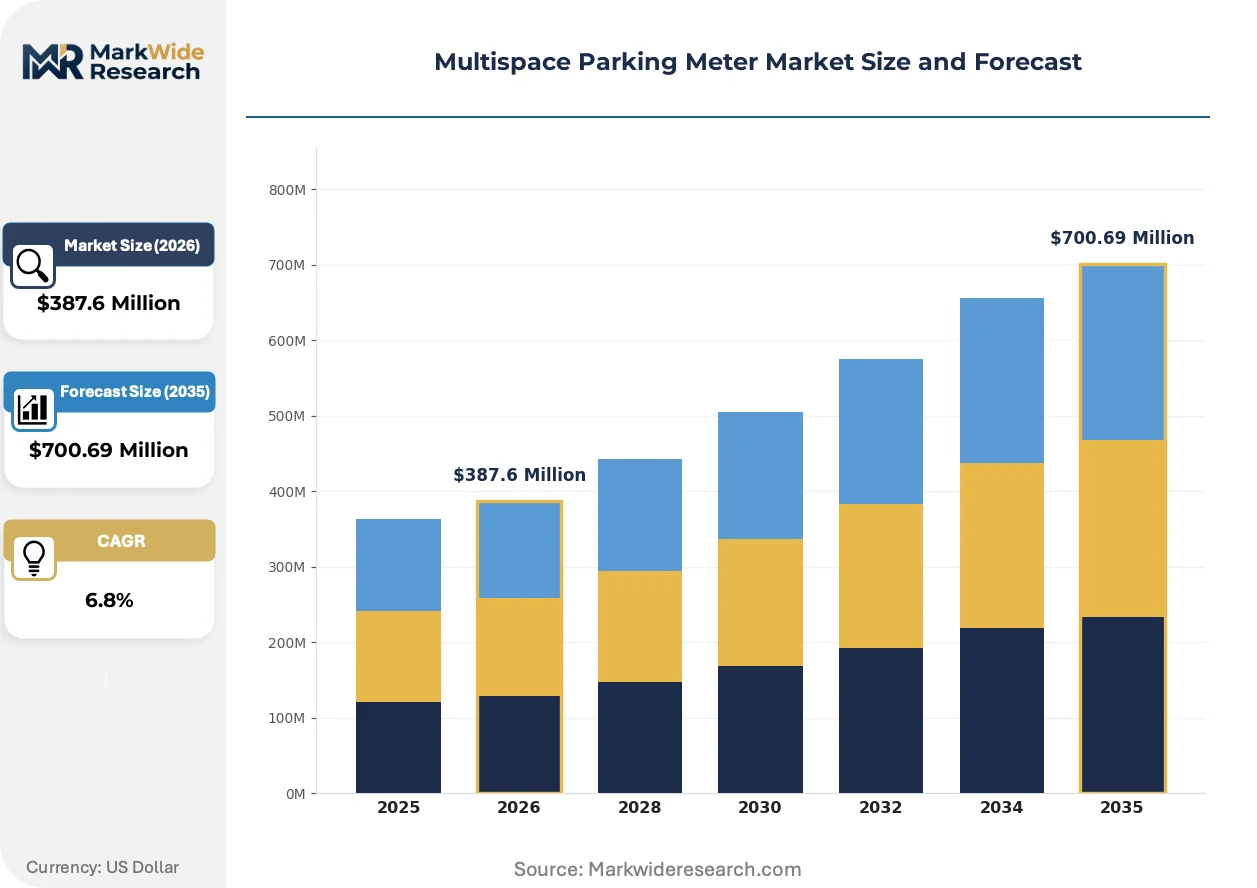
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Traditional Meters, Multi-Space Units, Coin-Operated Machines End User: Municipalities, Private Operators, Commercial Facilities, Residential Areas Installation Type: On-Street, Off-Street, Surface Lots, Structured Parking Payment Method: Mobile Payments, Credit Card, Cash, QR Code |
| Companies Covered | IPS Group, Flowbird Group, Hectronic GmbH, POM Inc., Parking BOXX, J.J. MacKay Canada Limited, Ventek International, IEM SA, METRIC Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multispace Parking Meter Market Shifts & Advancements
Payment modality electrification and embedded connectivity architectures are restructuring how cities procure and operate curb management assets.
License plate recognition cameras with edge-computing capability are electrifying enforcement automation. Municipal parking authorities in Germany and Japan deploy optical sensors for bay-by-bay occupancy verification without physical permits. This compression of manual patrol requirements is electrifying labor cost structures in high-turnover urban zones.
The EU Green Deal's embodied carbon requirements for public infrastructure procurement mandate lifecycle emissions disclosure for aluminum and polymer components. Meter suppliers must document material provenance and manufacturing energy intensity to qualify for German municipal tenders. European deployments face compressed qualification timelines as cities consolidate vendor ecosystems under sustainability criteria.
Subscription-based software licensing is displacing perpetual hardware purchases among North American municipal fleet managers. Cloud-native enforcement platforms with dynamic pricing algorithms replace capital expenditure models with operational spending aligned to citation revenue. This shift concentrates most visibly in United States cities with dedicated smart infrastructure budgets and multi-year service contracts.
Multispace Parking Meter Market Segmentation
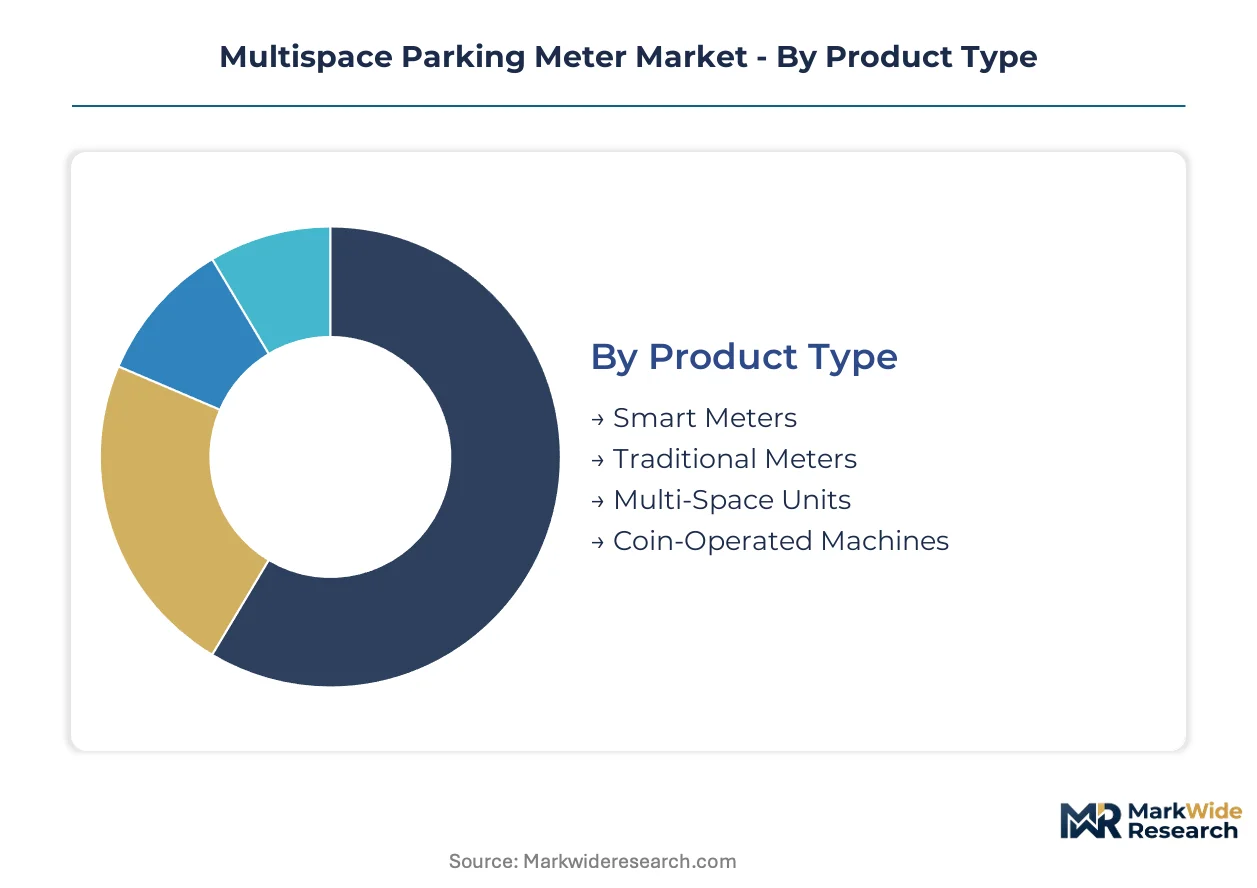
Municipal procurement cycles and payment infrastructure mandates fragment the multispace parking meter market across hardware generations, operator types, and installation environments. Certification requirements under FCC Part 15 and CE marking create divergent compliance burdens that reshape competitive positioning within each segment tier.
Product Type:
CE marking under the EU Radio Equipment Directive and FCC Part 15 certification impose distinct electromagnetic compliance costs across hardware categories, with wireless-enabled units facing extended validation timelines.
- Smart Meters:Networked terminals integrate LCD displays, proximity card readers, and cellular modems operating on 4G or LoRaWAN protocols. German municipal authorities prioritize these units for dynamic pricing enforcement and real-time occupancy data transmission to traffic management centers.
- Traditional Meters:Standalone electromechanical devices with limited connectivity rely on battery power and manual data retrieval. Cash-accepting legacy meters retain installed base in lower-density Japanese prefectures where infrastructure budgets constrain hardware refresh cycles.
- Multi-Space Units:Centralized kiosks serving 4-12 adjacent parking bays with integrated payment processing and enforcement cameras.
- Coin-Operated Machines:Single-bay mechanical meters with coin recognition mechanisms and no wireless communication capability.
Leading the category by volume: Smart Meters. Expanding most quickly: Multi-Space Units.
End User:
Procurement authority and revenue model differentiation segment demand across public sector mandates and commercial operational priorities.
- Municipalities:City parking authorities deploy networked curb management systems under smart city infrastructure budgets. United States transit agencies mandate contactless payment acceptance, compressing refresh cycles for legacy meter replacement programs.
- Private Operators:Commercial parking management companies prioritize dynamic pricing software licensing and cloud-native enforcement platforms. Revenue-share contracts with property owners concentrate procurement in high-turnover urban zones.
- Commercial Facilities:Retail and office complexes install surface lot terminals with license plate recognition for permit enforcement.
- Residential Areas:Homeowner associations and residential districts deploy limited-meter installations with restricted operating hours.
Capturing dominant procurement volume: Municipalities. Gaining share fastest: Private Operators.
Installation Type:
Trenching requirements and power infrastructure availability shape hardware selection across above-ground and subterranean deployment environments.
- On-Street:Curb-adjacent terminals exposed to weather and vandalism require hardened aluminum enclosures. Solar-powered assemblies with embedded photovoltaic cells eliminate electrical infrastructure costs in German and United States urban deployments.
- Off-Street:Surface lots and garage entrances accommodate larger kiosk footprints with integrated signage. Cellular modem supply concentration from East Asian foundries constrains production scaling for these networked installations.
- Surface Lots:Open-air parking areas with high vehicle turnover prioritize rapid transaction processing and license plate capture.
- Structured Parking:Multi-level garages require redundant connectivity through LoRaWAN protocol convergence with 4G cellular backhaul.
Dominating deployment counts: On-Street. Climbing the fastest: Structured Parking.
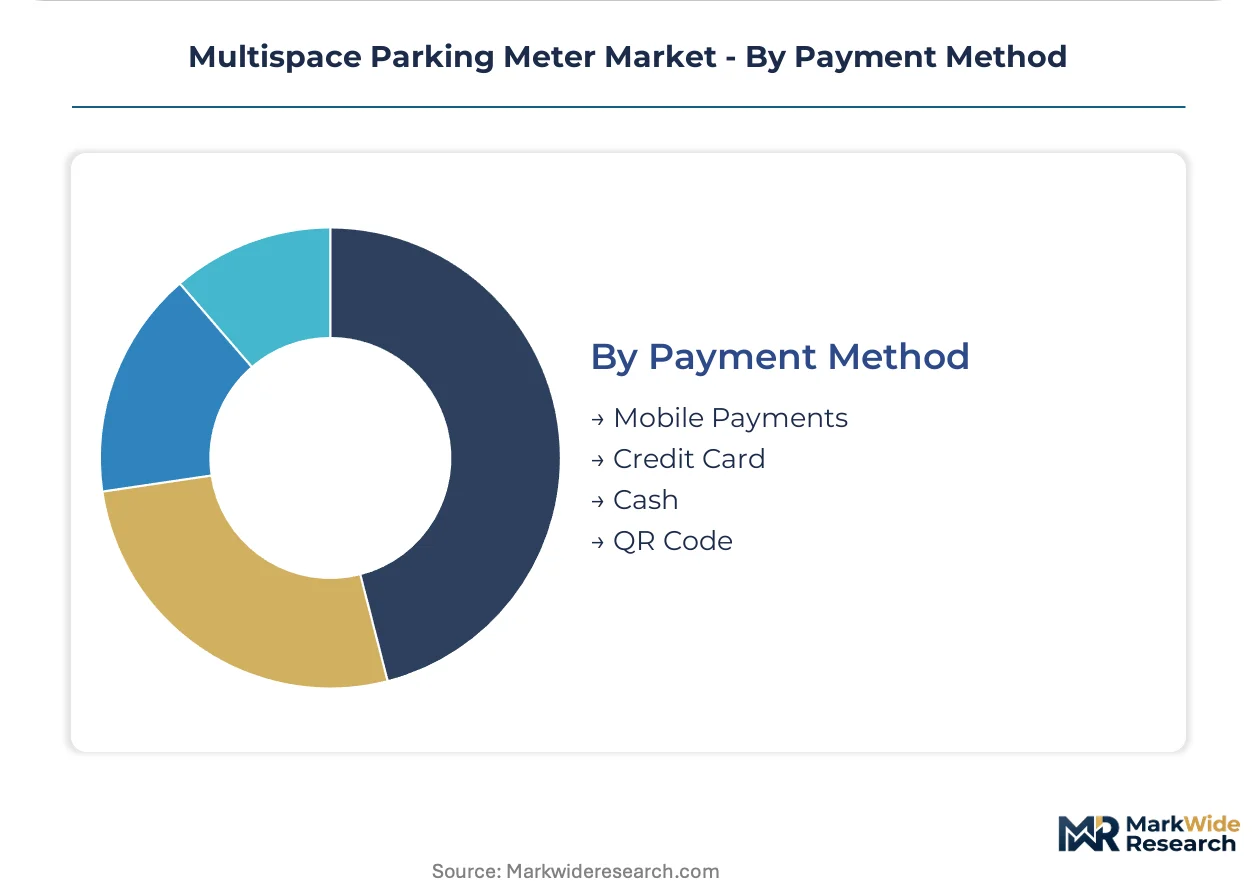
Payment Method:
Transaction modality electrification and cash handling cost reduction drive heterogeneous adoption across municipal and commercial operator segments.
- Mobile Payments:NFC and QR-code modalities integrate with municipal wallet applications and third-party parking apps. United States city transit authorities mandate mobile wallet integration, displacing cash acceptance in surface lot installations.
- Credit Card:EMV chip and contactless card readers dominate commercial facility deployments where visitor parking requires flexible payment options.
- Cash:Coin and bill acceptance mechanisms persist in mechanical legacy meters and jurisdictions with unbanked population concentrations.
- QR Code:Visual payment triggers linked to mobile applications reduce hardware costs compared to NFC-enabled terminals.
Holding dominant transaction share: Mobile Payments. Steepest expansion trajectory: QR Code.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware production clusters in Germany and Japan supply meter assemblies to municipal procurement programs in the United States and Western Europe. Consumption concentrates in urban centers replacing legacy coin mechanisms with networked curb management terminals.
United States
City transit authorities in New York, Chicago, and Los Angeles mandate contactless payment acceptance, compressing refresh cycles for mechanical meter replacement. FCC Part 15 certification governs electromagnetic emissions for cellular-enabled installations. Municipal fleet managers in California and Texas anchor procurement volume under smart city infrastructure budgets.
Germany
Municipal authorities in Berlin, Munich, and Hamburg prioritize solar-powered meter assemblies with integrated LoRaWAN connectivity. CE marking under the EU Radio Equipment Directive standardizes wireless compliance across state procurement networks. The EU Green Deal's embodied carbon requirements shape supplier qualification for aluminum enclosures in Baden-Württemberg manufacturing clusters.
Japan
Prefectural governments in Tokyo, Osaka, and Aichi deploy license plate recognition cameras for bay-by-bay occupancy verification. METI guidelines influence interoperability standards for curb data exchange protocols. Legacy mechanical meters retain installed base in lower-density prefectures where infrastructure budgets constrain hardware refresh timelines.
United Kingdom
Transport for London and municipal authorities in Manchester and Birmingham expand networked curb management deployments. GDPR compliance requirements shape data handling specifications for occupancy transmission systems. Private operators in London's high-turnover zones drive dynamic pricing software licensing adoption.
France
The ANSM and CNIL framework influences data protection requirements for license plate recognition systems in Paris, Lyon, and Marseille. Municipal parking authorities prioritize mobile wallet integration to reduce cash handling costs. CE marking accelerates cross-border procurement from German component suppliers.
Multispace Parking Meter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the meter assembly value chain. Integrated manufacturers operating dedicated production lines for aluminum enclosures and photovoltaic cells face competition from procurement specialists outsourcing fabrication to contract foundries. Three archetypes dominate: vertically integrated hardware producers, cloud-native platform licensors, and regional municipal contractors. Competitive moves concentrate on manufacturing scale expansion and recurring service contract capture.
Within the integrated production tier, IPS Group and Hectronic GmbH exemplify capital-intensive positioning through in-house assembly operations. Flowbird Group occupies the platform-centric archetype, anchoring cloud-native service delivery. These three entities represent the dominant competitive vectors: captive manufacturing control, recurring software revenue, and municipal relationship density.
| Leading Market Players |
|---|
| IPS Group |
| Flowbird Group |
| Hectronic GmbH |
| POM Inc. |
| Parking BOXX |
| J.J. MacKay Canada Limited |
| Ventek International |
| IEM SA |
| METRIC Group Ltd |
| Others |
Supply & Pricing Matrix
Cellular modem miniaturization and solar-embedded assembly methods are compressing unit economics while concentrating procurement leverage among East Asian semiconductor foundries. German municipal authorities now bundle hardware refresh cycles with 10-year service contracts, shifting supplier pricing power toward recurring SaaS tiers.
Pricing Analysis
Margin tightening in mid-tier meter assemblies reflects LoRaWAN module cost volatility and CE marking compliance overhead. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native enforcement platforms from basic networked terminals and legacy coin-operated units. Price differentiation rests on FCC Part 15 certification grade and embedded LPR camera resolution. Municipal fleet managers exhibit highest price sensitivity; private operators with revenue-share contracts tolerate premium hardware costs.
Supply Chain Analysis
EU Green Deal domestic-content mandates for public infrastructure procurement are reshaping aluminum enclosure sourcing toward Baden-Württemberg manufacturing clusters. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China. Meter assemblies draw from photovoltaic cells, cellular modems, and optical sensor arrays. Single-source vulnerability in 4G IoT chipset supply creates procurement risk. Distribution runs through municipal procurement consortiums and commercial parking management integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular modem supply concentration and contactless payment mandates are forcing subscale hardware vendors toward exit or acquisition, consolidating competitive terrain around integrated platform providers.
For Market Incumbents: Deepen captive production of solar-powered meter assemblies to offset East Asian semiconductor dependency. Anchor municipal relationships through 15-year dynamic pricing software licensing contracts. IPS Group and Flowbird Group demonstrate this defensive posture against emerging cloud-native entrants. For New Entrants and Emerging Players: Enter via white-label LPR camera modules for retrofit installations in Japanese prefectures with constrained infrastructure budgets. Target lower-density German municipalities underserved by integrated platform vendors. Pursue revenue-share go-to-market structures with commercial facility operators. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-centric acquisitions by industrial automation conglomerates seeking smart city exposure. Five-to-ten year viability favors cloud-native enforcement platforms with recurring revenue above 60% of total contract value. Monitor LoRaWAN protocol standardization timelines as inflection signal for hardware-software margin reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellular Modem Supply | Mitigates Taiwan foundry concentration risk for German municipal deployments. |
| Cloud-Native Enforcement Platform Launch | Converts California transit authority contracts from CapEx to recurring SaaS revenue. |
| EU Green Deal Certification Program | Qualifies aluminum enclosures for Paris municipal tenders under embodied carbon criteria. |
| LoRaWAN-4G Convergence Partnership | Enables redundant connectivity for Tokyo underground structured parking installations. |
| License Plate Recognition Module Acquisition | Accelerates bay-by-bay occupancy verification for Osaka prefectural authorities. |
Research Methodology
Document review covered municipal procurement databases, FCC Part 15 certification filings, and EU Green Deal technical specifications, complemented by interviews with parking authority fleet managers, smart city infrastructure officers, meter hardware procurement leads, and cloud platform engineering directors. Secondary sources included CE marking compliance registries, German municipal tender announcements, and METI interoperability guidelines. Bottom-up unit deployment estimates triangulated against top-down smart city infrastructure budget allocations.
Segment-level projections across hardware generation, operator type, installation environment, and payment modality fed into analytical framework outputs over the projection horizon. CAGRs derived from municipal replacement cycle timing, contactless payment mandate phase-in schedules, and solar assembly cost curves. Forecast inputs incorporated LoRaWAN network deployment timelines and license plate recognition camera adoption rates by prefecture.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or interoperability standard fragmentation scenarios. Assumptions reflect documented municipal budget commitments and regulatory compliance timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Car Rental Service Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Poland Car Rental Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Refuse Truck Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Bird Carriers Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
India Taxi Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Water Truck Rental Market