
 Vehicle Crash Testing System Market | 2026-2036
Vehicle Crash Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Crash Testing System Market Insights
German engineering consortiums is broadening production capacity for high-fidelity crash test dummies and sensor arrays. HORIBA leverages its instrumentation portfolio to dominate measurement systems for impact dynamics. Humanetics Innovative Solutions anchors the anthropomorphic test device segment through sustained R&D intensity in biofidelic design. Siemens competes across simulation software where its digital twin capabilities extend into pre-physical validation workflows.
Vehicle crash testing systems encompass integrated hardware-software platforms designed to measure occupant injury criteria, structural deformation, and impact energy distribution under controlled collision conditions, typically capturing data at sampling rates exceeding 100 kHz through onboard accelerometers and high-speed imaging. These systems serve the primary industrial purpose of certifying vehicle designs against mandatory safety thresholds before mass production authorization. Dynamic testing commands the largest share of product-type revenue as OEMs prioritize full-vehicle sled and barrier impact validation, while hybrid testing represents the fastest-expanding technology segment where simulation-to-physical correlation reduces prototype iteration cycles. Component testing occupies concentrated margin pools among specialized suppliers serving tier-one seatbelt and airbag manufacturers.
NHTSA's Federal Motor Vehicle Safety Standards, Euro NCAP's evolving assessment protocols, and China's GB 11551 frontal impact requirements collectively mandate repeatable, auditable crash validation that OEMs cannot bypass. The EU AI Act and emerging software-defined vehicle regulations are layering algorithmic accountability onto passive safety systems, expanding testing scope into automated emergency braking validation. Stakeholders must monitor regulatory divergence between jurisdictions where divergent dummy specifications and injury metric thresholds threaten to fragment equipment standardization.
Market Dynamics
Regulatory divergence between NHTSA, Euro NCAP, and China's GB standards is fragmenting equipment specifications, forcing OEMs to maintain parallel validation protocols and driving capital intensity in testing infrastructure.
Growth Catalysts
- Euro NCAP Protocol Evolution:The 2026 pedestrian protection and autonomous emergency braking mandates expand testing scope beyond traditional barrier impacts into active safety system validation.
- Electric Vehicle Structural Redesign:Battery pack integration and reinforced passenger compartments require novel sled configurations and modified barrier geometries that obsolete legacy testing regimes.
- Software-Defined Vehicle Architecture:Over-the-air updates to restraint control modules create recurring validation cycles that sustain equipment utilization rates at OEM facilities.
Market Restraints
- High-Fidelity Sensor Cost Volatility:Piezoelectric accelerometers and strain gauge arrays depend on rare earth supply chains concentrated in China's processing infrastructure.
- Dummy Biofidelity Standardization Lag:Divergent THOR-50M specifications between US and European regulators force duplicate anthropomorphic device procurement.
- Physical Test Substitution Pressure:Finite element simulation suites from Siemens and Dassault Systèmes compress demand for full-scale barrier impacts in early development phases.
Strategic Opportunities
- India's Automotive Safety Mandate Expansion:Bharat NCAP adoption and mandatory ABS requirements for two-wheelers create first-mover positioning for sled and barrier suppliers.
- Active Safety-to-Passive Safety Convergence:Integration of pre-crash sensing with pyrotechnic restraint deployment demands hybrid test rigs combining simulation with physical impact.
- Subscription-Based Validation Services:Tier-one suppliers and emerging OEMs in Southeast Asia prefer equipment-as-a-service models over capital-intensive facility ownership.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Correlation of finite element models with physical test data requires specialists fluent in both LS-DYNA and experimental mechanics.
- Certification Timeline Compression:Euro NCAP's biannual protocol updates compress the window between draft publication and mandatory compliance testing.
- Legacy Data Architecture Integration:Decades of proprietary crash test databases resist migration to cloud-native platforms that enable cross-OEM benchmarking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Crash Testing System Market |
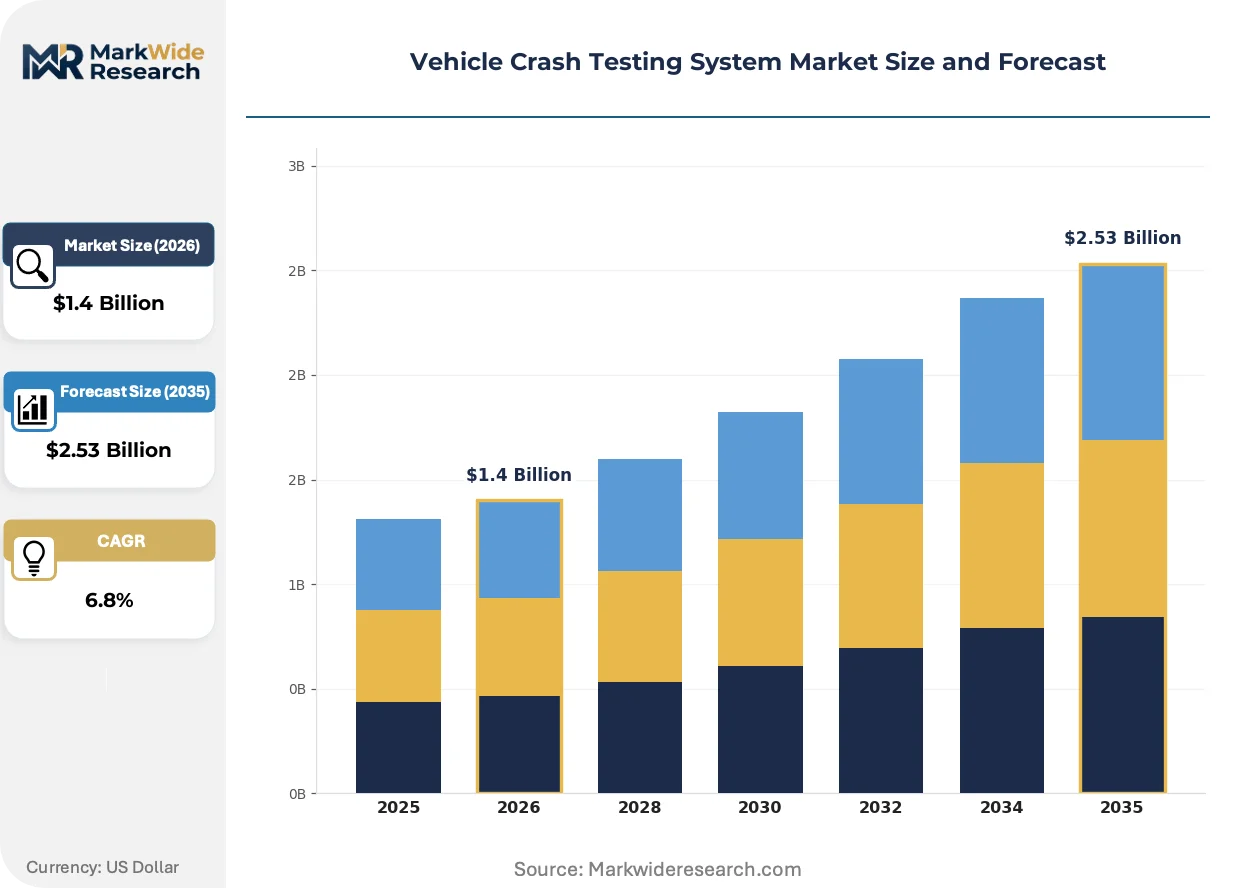
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Testing, Static Testing, Component Testing, Full-Scale Testing Technology: Simulation, Physical Testing, Hybrid Testing, Instrumentation End User: Automobile Manufacturers, Regulatory Authorities, Research Institutions, Safety Assessment Organizations Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Others |
| Companies Covered | 4activeSystems GmbH, Dynamic Research, Humanetics Innovative Solutions, HORIBA, GESAC, TASS International, Cellbond, Siemens, JASTI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Crash Testing System Market Trends and Innovations
Digital twin correlation and active safety integration are displacing siloed physical testing regimes, compressing development cycles while expanding the data volume and analytical sophistication required of validation infrastructure.
Modular sled propulsion architectures are modularizing crash test facility design, allowing OEMs to reconfigure impact angles and velocities without dedicated barrier installations. Tier-one suppliers in Germany and Japan are adopting these systems to serve multiple OEM contracts from shared facilities. This modularity is compressing capital deployment timelines and enabling smaller validation centers to compete with established full-scale installations.
EU AI Act algorithmic accountability requirements are extending crash testing scope into automated emergency braking validation, mandating reproducible documentation of neural network decision boundaries under impact scenarios. OEMs must now demonstrate that perception-to-actuation latency remains within injury threshold windows across diverse pedestrian and cyclist profiles. European facilities are responding by integrating sensor-in-the-loop testing with traditional physical barrier impacts.
Buyer concentration among megaplatform OEMs is consolidating procurement authority into centralized technical centers in Stuttgart, Toyota City, and Detroit, displacing distributed purchasing at individual manufacturing sites. Tier-two equipment suppliers now face direct qualification by these technical centers rather than plant-level engineering teams. This concentration is most visible in Germany, where consortium purchasing agreements cover instrumentation, dummies, and facility infrastructure under unified contract frameworks.
Vehicle Crash Testing System Market Segmentation
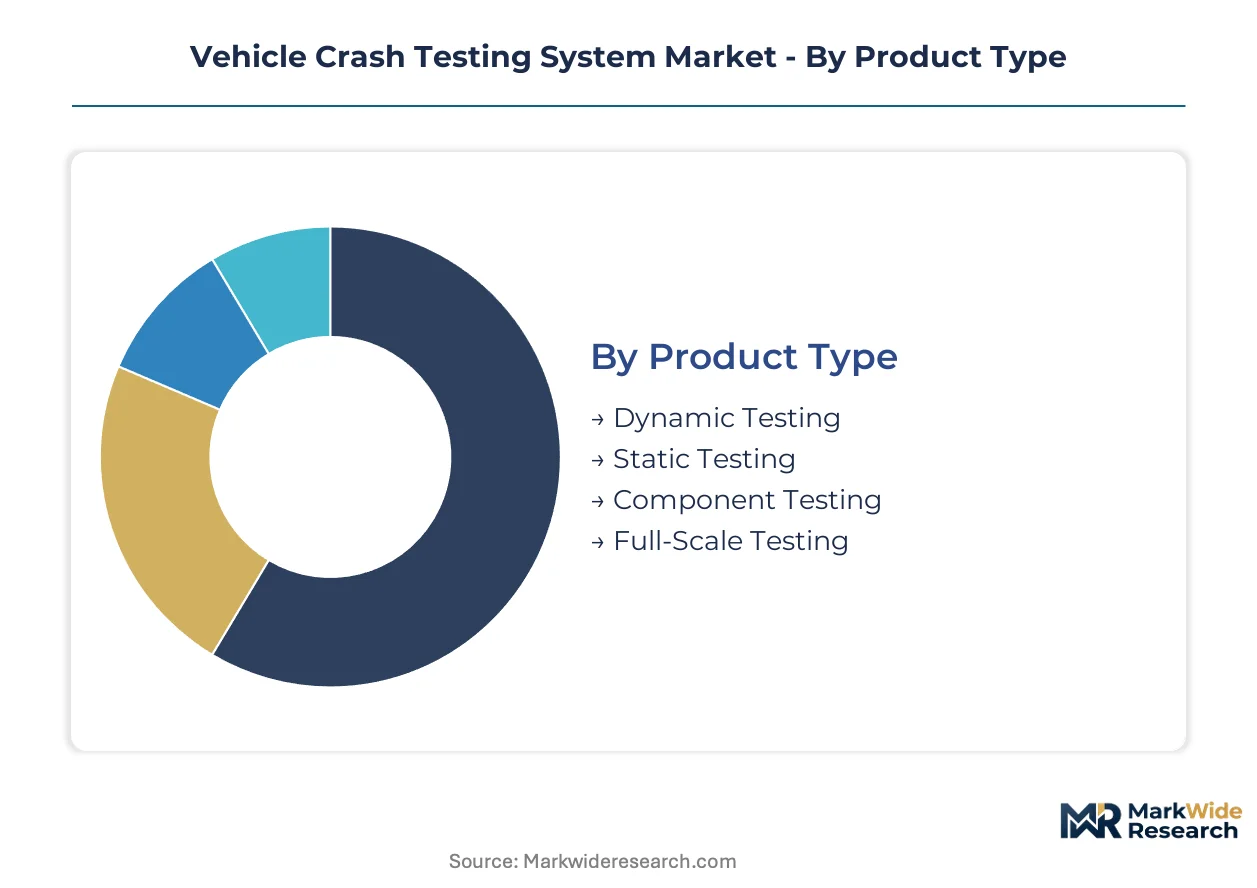
Equipment upgrade cycles in crash testing infrastructure create distinct demand patterns across product categories. OEMs replace sled systems and dummies on 7-10 year intervals while software platforms refresh faster, fragmenting procurement timelines across segments.
Product Type:
Replacement cycles vary sharply by product category, with full-scale barrier installations requiring decade-long capital commitments while component rigs turn over faster.
- Dynamic Testing:Sled-based impact systems measuring occupant kinematics through high-speed propulsion and onboard DAS acquisition. German and Japanese OEMs concentrate procurement here as EV platform redesigns force new sled configurations for battery-protected occupant compartments.
- Static Testing:Quasi-static load applications for seat anchorage and roof crush validation without kinetic energy components. Regulatory authorities in the United States and Germany maintain extensive static facilities for FMVSS and UN-ECE certification protocols.
- Component Testing:Dedicated rigs for airbag modules, seatbelts, and steering column collapse characteristics. Tier-one suppliers like Autoliv and ZF operate captive component labs with faster equipment refresh rates than OEM full-scale centers.
- Full-Scale Testing:Complete vehicle-to-barrier impacts with multi-camera photogrammetry and post-crash deformation mapping. Research institutions in Japan and Germany dominate this capital-intensive segment for protocol development and regulatory correlation studies.
Dynamic Testing sits at the top of the volume ranking, with Component Testing climbing the fastest as tier-one suppliers expand in-house validation capabilities.
Technology:
Technology selection tracks customer sophistication tiers, with premium OEMs layering simulation-to-physical correlation while budget-constrained buyers prioritize standalone physical rigs.
- Simulation:Finite element preprocessing through LS-DYNA and PAM-CRASH solvers for virtual crash prediction. Siemens and Dassault Systèmes serve this segment where pre-physical validation compresses prototype iterations for Euro NCAP timing pressures.
- Physical Testing:Hardware-only validation without computational preprocessing correlation. China's GB standard compliance drives concentrated demand here among domestic OEMs with limited CAE infrastructure.
- Hybrid Testing:Hardware-in-the-loop architectures combining real-time simulation with physical dummy or sled components. This segment gains share fastest as AEB-to-restraint integration mandates sensor-in-the-loop correlation for EU AI Act documentation.
- Instrumentation:Data acquisition systems, accelerometer arrays, and high-speed imaging equipment. HORIBA and Kistler compete across this high-margin attach category with sensor refresh cycles outpacing sled replacement timelines.
Physical Testing commands the largest installed base, though Hybrid Testing expands most quickly through active-passive safety convergence requirements.
End User:
End-user type determines facility scale and equipment specification intensity, with manufacturers operating the most comprehensive installations while authorities focus on audit repeatability.
- Automobile Manufacturers:Toyota, Volkswagen, and Ford operate captive validation centers with multi-sled configurations and in-house dummy fleets. These facilities require continuous instrumentation upgrades to track evolving Euro NCAP and NHTSA protocols.
- Regulatory Authorities:NHTSA's Vehicle Research and Test Center and Germany's KBA maintain reference facilities for standard-setting and OEM audit testing. Their procurement prioritizes measurement traceability and inter-laboratory correlation over throughput.
- Research Institutions:University-affiliated centers and national laboratories conduct fundamental biomechanics and structural mechanics research. Japan's JARI and Germany's DEKRA operate such facilities with hybrid physical-simulation architectures.
- Safety Assessment Organizations:Euro NCAP and IIHS operate consumer-facing rating programs with standardized test protocols. Their equipment specifications directly influence OEM procurement decisions through protocol adoption.
Automobile Manufacturers represent the dominant revenue concentration, with Safety Assessment Organizations gaining procurement influence fastest through protocol harmonization efforts.
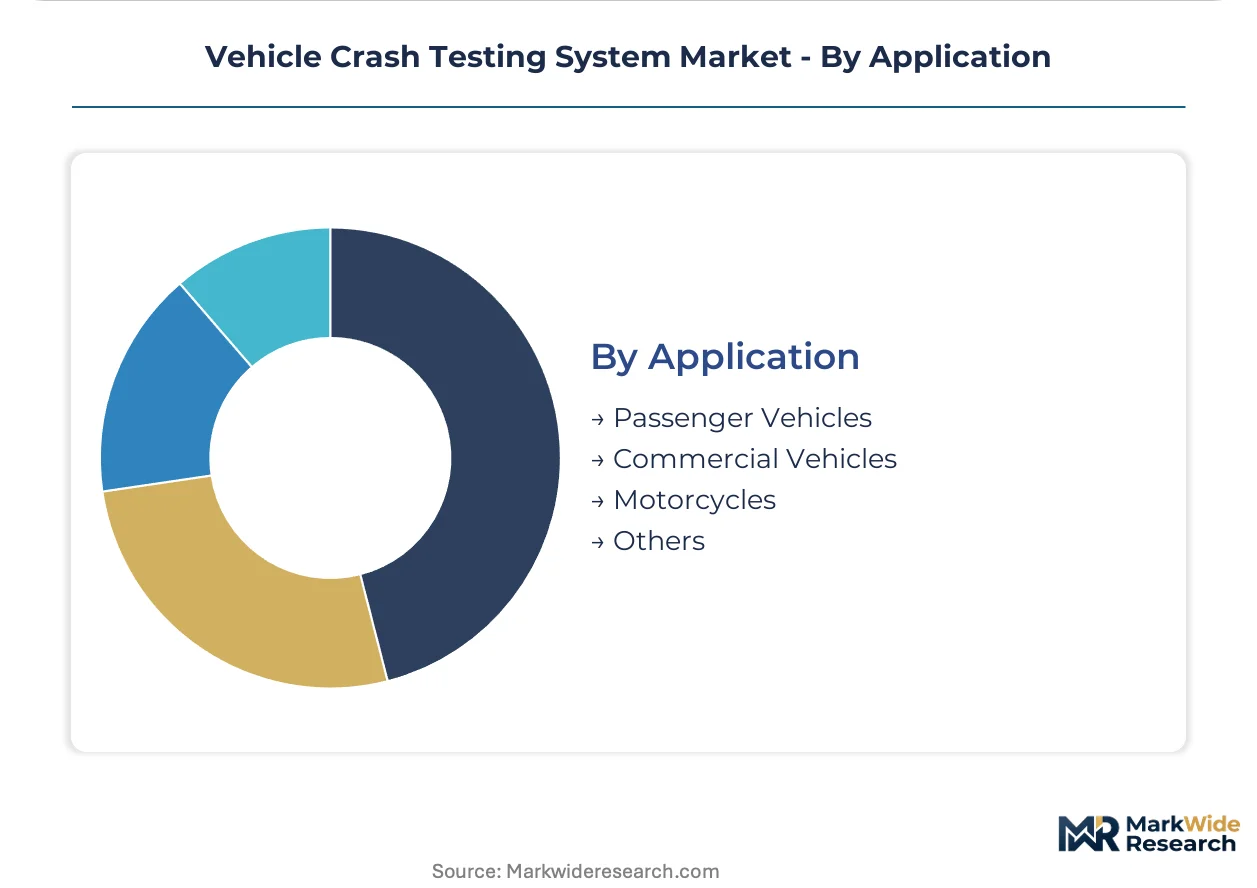
Application:
Application segmentation reflects divergent crash pulse characteristics and dummy specifications, with motorcycle testing requiring specialized equipment that passenger vehicle rigs cannot repurpose.
- Passenger Vehicles:Full-width frontal, offset deformable barrier, and side pole impacts using THOR and Hybrid III dummy families. This segment absorbs the majority of sled and barrier investment as OEMs validate C-NCAP, Euro NCAP, and IIHS rating targets simultaneously.
- Commercial Vehicles:Heavy truck cab integrity and bus rollover validation with specialized high-mass propulsion systems. NHTSA's underride guard regulations and UN R29 cab strength standards drive equipment specifications here.
- Motorcycles:Two-wheeler barrier impacts and helmet testing with distinct anthropomorphic devices and barrier geometries. India's Bharat NCAP motorcycle mandate and European L-category regulations are expanding this historically underserved segment.
- Others:Agricultural equipment, recreational vehicles, and specialty vehicle categories with fragmented regulatory coverage. These applications rely on adapted passenger vehicle rigs with modified pulse characteristics.
Passenger Vehicles retains the dominant equipment allocation, with Motorcycles showing the steepest expansion trajectory through emerging market safety mandate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between NHTSA protocols, Euro NCAP standards, and China's GB requirements creates arbitrage opportunities where testing equipment procurement concentrates in jurisdictions with the most demanding compliance timelines. OEMs migrate validation capacity toward markets where safety mandates tighten fastest, compressing equipment deployment cycles.
United States
NHTSA's Federal Motor Vehicle Safety Standards and IIHS consumer rating programs drive sustained sled and barrier investment by Detroit-based OEMs. The 2026 underride guard regulations and evolving pedestrian protection mandates expand testing scope beyond traditional frontal impacts. Technical centers in Michigan operate multi-sled configurations serving Ford, General Motors, and Stellantis validation programs simultaneously.
Germany
KBA enforcement of UN-ECE regulations and Euro NCAP protocol development creates concentrated demand for high-fidelity anthropomorphic devices and instrumentation arrays. Stuttgart and Wolfsburg anchor OEM captive facilities where Volkswagen, Mercedes-Benz, and BMW coordinate consortium purchasing agreements. The EU AI Act's algorithmic accountability requirements extend testing into automated emergency braking validation.
China
GB 11551 frontal impact mandates and C-NCAP rating adoption propel domestic OEM investment in full-scale barrier installations. MIIT oversight of new energy vehicle structural requirements forces battery-specific sled configurations that obsolete legacy equipment. Shanghai and Beijing host technical centers where BYD, NIO, and Geely operate expanded validation infrastructure.
Japan
METI coordination of JNCAP protocols and domestic OEM export compliance sustains investment in THOR dummy procurement and high-speed data acquisition. Toyota City and Yokohama concentrate captive facilities where Toyota, Honda, and Nissan maintain parallel validation tracks for domestic and export markets. JARI operates reference facilities for regulatory correlation studies.
India
Bharat NCAP adoption and mandatory ABS requirements for two-wheelers create first-mover positioning for equipment suppliers. CDSCO-aligned safety mandates and the PLI scheme for automotive manufacturing accelerate validation infrastructure buildout. Pune and Chennai host emerging technical centers where Mahindra, Tata Motors, and emerging EV specialists expand testing capabilities.
Vehicle Crash Testing System Market Competitive Landscape
German and Japanese producers anchor the premium instrumentation tier; North American specialists hold dominant positions in anthropomorphic test devices. The market structures around three tiers: full-system integrators delivering sled-to-software platforms, component specialists focusing on dummies or sensors, and regional fabricators serving emerging market compliance buildouts. Consolidation pressures concentrate procurement authority into OEM technical centers, forcing direct qualification relationships. Competitive moves center on hybrid testing architecture development and subscription-based equipment service models.
Within the full-system integration tier, HORIBA and Siemens occupy positions exemplifying measurement-to-simulation convergence. Among anthropomorphic device specialists, Humanetics Innovative Solutions anchors biofidelic design advancement. Japanese fabricators including JASTI represent regional equipment supply archetypes serving domestic OEM validation programs. These named entities illustrate competitive positioning without constraining strategic optionality for adjacent participants.
| Leading Market Players |
|---|
| 4activeSystems GmbH |
| Dynamic Research |
| Humanetics Innovative Solutions |
| HORIBA |
| GESAC |
| TASS International |
| Cellbond |
| Siemens |
| JASTI |
| Others |
Pricing and Supply Chain Analysis
Biomechanical engineering talent concentration in Stuttgart and Wolfsburg widens pricing-tier spreads, as German OEM captive facilities absorb premium labor costs while Chinese validation centers exploit cost differentials for standard-grade instrumentation procurement.
Pricing Analysis
Distributor margins on piezoelectric accelerometer arrays and THOR dummy sensor modules compress direct-to-OEM pricing by 12-18 percent for volume buyers. Three-tier pricing structure across premium, standard, and economy levels separates HORIBA measurement systems from regional Japanese fabricators and Chinese component suppliers. Price differentiation hinges on ISO 17025 calibration certification and NHTSA correlation study documentation. Pricing pressure stems from finite element simulation substitution in early development phases, with tier-one seatbelt manufacturers showing highest price sensitivity and German OEM technical centers least sensitive due to consortium purchasing leverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for sled propulsion systems and full-scale barrier installations, while tier-two distributors serve emerging market validation centers in India and Southeast Asia. Component fabrication concentrates in Germany, Japan, and China, with piezoelectric crystal processing anchored in Chinese rare earth infrastructure. Supply chains draw from lithium niobate substrates, high-tensile steel alloys, and biofidelic polymer compounds. Single-source vulnerability in Chinese rare earth processing threatens accelerometer cost stability. Distribution runs through equipment-as-a-service platforms for budget-constrained tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid testing architecture adoption expands margin pools as OEMs trade capital-intensive physical rigs for recurring simulation-to-correlation service contracts, compressing upfront equipment spend while elongating revenue visibility.
For Market Incumbents: Acquire sensor-in-the-loop testing capabilities to counter Dassault Systèmes finite element substitution threat. Integrate backward into cloud-native data architectures that unlock cross-OEM benchmarking subscriptions. Certification investment in EU AI Act algorithmic accountability documentation captures active safety validation spend migrating from passive safety budgets. For New Entrants and Emerging Players: Enter via India's Bharat NCAP infrastructure buildout, where CDSCO-aligned mandates and PLI scheme incentives concentrate demand for motorcycle-specific barrier rigs and two-wheeler dummy procurement. Target component testing segment penetration among Autoliv and ZF captive labs with faster refresh cycles than OEM full-scale centers. Go-to-market through equipment-as-a-service models that displace capital-intensive facility ownership for Southeast Asian tier-one suppliers. For Investors and Strategic Acquirers: Tier-one automotive suppliers are the most active acquirer in this space, consolidating instrumentation specialists to secure captive validation capacity for software-defined vehicle restraint modules. Long-term viability hinges on hybrid testing IP portfolios that bridge physical and simulation domains. Acquisition target archetype: mid-cap dummy manufacturers with THOR-50M biofidelity advancement programs. Signal to watch: Euro NCAP protocol biannual update frequency acceleration as inflection indicator for equipment refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Testing Architecture Development | Sensor-in-the-loop integration captures EU AI Act AEB validation mandates. |
| Subscription-Based Validation Services | Equipment-as-a-service models penetrate Southeast Asian tier-one supplier budgets. |
| THOR Dummy Biofidelity Advancement | THOR-50M specification convergence reduces duplicate procurement for Euro NCAP and NHTSA compliance. |
| Cloud-Native Data Platform Migration | Cross-OEM benchmarking unlocks recurring revenue from decades of proprietary crash test databases. |
| India Market First-Mover Positioning | Bharat NCAP adoption and motorcycle ABS mandates concentrate infrastructure buildout in Pune and Chennai. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and regulatory authority test center directors with secondary validation against NHTSA FMVSS filings, Euro NCAP protocol documentation, UN-ECE regulatory submissions, and vehicle production databases from IHS Markit. Bottom-up segment sizing and top-down macro constraint triangulation anchored market estimates.
Segment-weighting applied product type, technology, end user, and application dimensions across the projection horizon, with vehicle class and propulsion architecture as automotive-specific cross-cuts. CAGRs derived from regression analysis of historical equipment procurement cycles correlated with regulatory mandate implementation timelines. Forecast inputs included OEM R&D capex disclosures and Euro NCAP protocol update schedules.
The model holds under stable regulatory harmonization assumptions; deviation in NHTSA-Euro NCAP dummy specification divergence or Chinese GB standard acceleration would shift equipment procurement timing and geographic concentration. Forecasts reflect documented assumptions regarding EV platform redesign intensity and software-defined vehicle OTA update frequency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Dynamometer Market