
 Automotive Emission Analyzer Market | 2026-2036
Automotive Emission Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Emission Analyzer Market Analysis
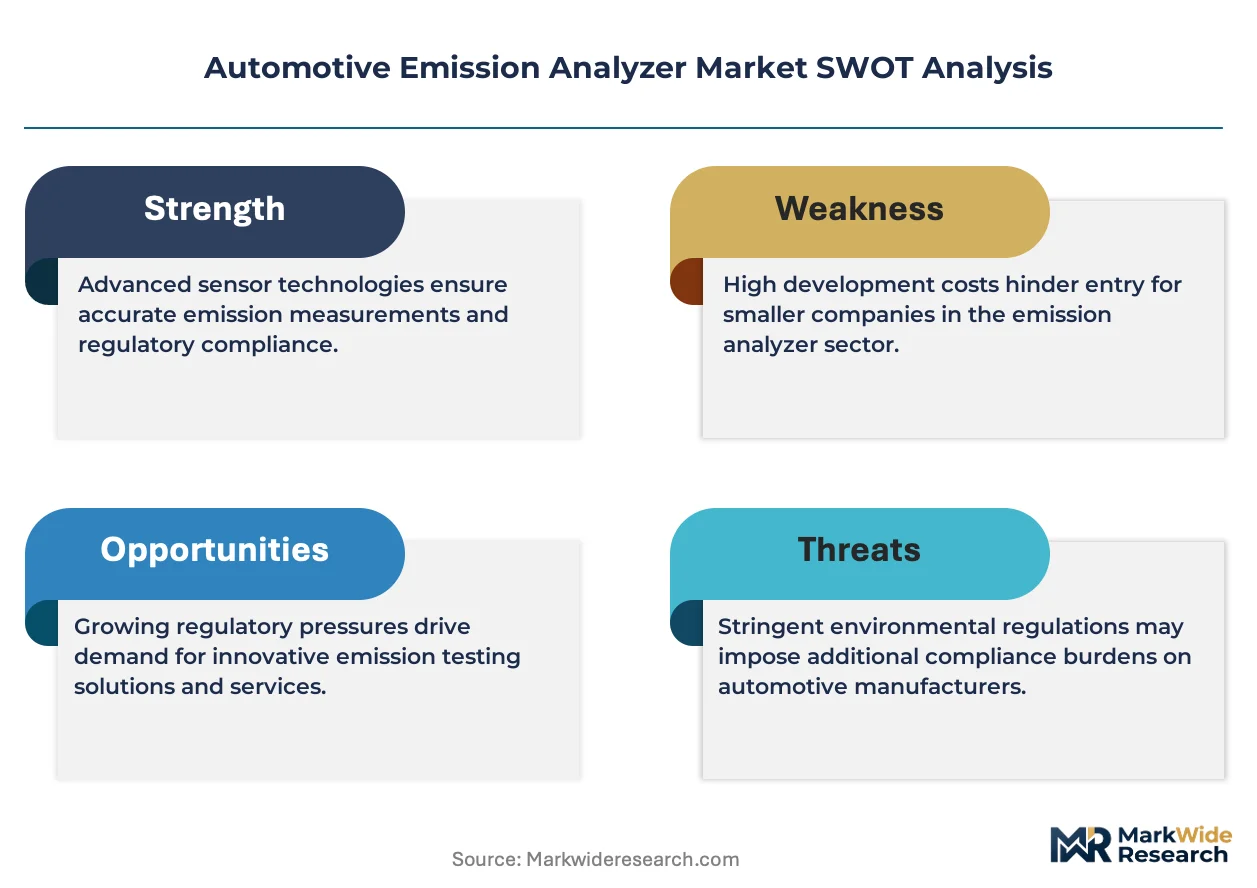
EU Green Deal compliance deadlines for heavy-duty vehicle CO2 reduction is expanding the cost-of-entry calculus for emission testing equipment across European service chains. Horiba Ltd. anchors its position through deep specialization in multi-gas measurement benches for laboratory certification. AVL List GmbH competes via integrated testing software paired with engine dynamometer systems. Siemens Aktiengesellschaft leverages industrial automation expertise to sustain channel control in connected analyzer networks.
An automotive emission analyzer is a precision instrument that quantifies exhaust gas constituents including CO, CO2, HC, NOx, and particulate matter using optical, electrochemical, or gravimetric detection methods at flow rates calibrated to regulatory test cycles. Its primary commercial purpose is verifying powertrain compliance against mandatory emission thresholds before type approval or in-service surveillance. Gas analyzers occupy the largest installed base among technology segments while portable analyzers represent the fastest expansion vector as roadside enforcement agencies deploy mobile screening units. Fixed analyzers dominate laboratory and certification revenue pools whereas mobile analyzers command premium pricing in on-road testing applications where rapid deployment replaces permanent infrastructure.
The US EPA, California Air Resources Board, and China's MEE collectively shape product standards through divergent test protocols that force manufacturers into modular hardware architectures. EPA Tier 4 and Euro VII precursor rules are forcing simultaneous NOx and particulate number measurement capabilities that inflate sensor complexity and service contract values. Stakeholders must monitor regulatory harmonization talks between Brussels and Beijing that could compress SKU variety or splinter certification requirements further.
Market Dynamics
Non-dispersive infrared sensor technology is compressing hardware refresh cycles as laboratories and service stations retire chemiluminescence benches. Fleet operators in Germany are accelerating procurement ahead of EU Green Deal enforcement timelines.
Growth Catalysts
- EU Green Deal heavy-duty CO2 mandates:Fleet operators across Germany, France, and Poland are pre-buying analyzers to lock in compliance capacity before enforcement deadlines tighten.
- China MIIT real-time telemetry mandate:Heavy-duty diesel registrations in eastern manufacturing corridors now require continuous emissions monitoring, forcing analyzer retrofits at inspection stations.
- Portable analyzer adoption:Roadside enforcement agencies in California and Texas are deploying mobile screening units to replace fixed tunnel infrastructure.
Market Restraints
- Sensor cost inflation:Simultaneous NOx and particulate number measurement requirements under EPA Tier 4 precursor rules are doubling sensor stack costs.
- Supply concentration in German optics:Precision infrared source manufacturing clusters in Bavaria create single-point vulnerability for NDIR module supply.
- Regulatory protocol fragmentation:Divergent test cycles between EPA, CARB, and China's MEE force modular hardware architectures that inflate SKU complexity.
Strategic Opportunities
- India's impending BS-VII transition:The country's national automotive regulator is expected to mandate analyzer upgrades at state transport authority test centers within three years.
- Connected analyzer networks:Industrial automation platforms are enabling remote calibration and predictive maintenance contracts that extend customer lifetime value.
- Hydrogen combustion testing:Engine laboratories require new gas benches capable of measuring NH3 and N2O slip from hydrogen-fueled powertrains.
Industry Challenges
- Metrology talent scarcity:Field service engineers with combined optical and electrochemical sensor expertise command premium wages in Stuttgart and Shanghai.
- Certification timeline compression:Euro VII laboratory accreditation requires parallel validation across multiple national type-approval bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Emission Analyzer Market |
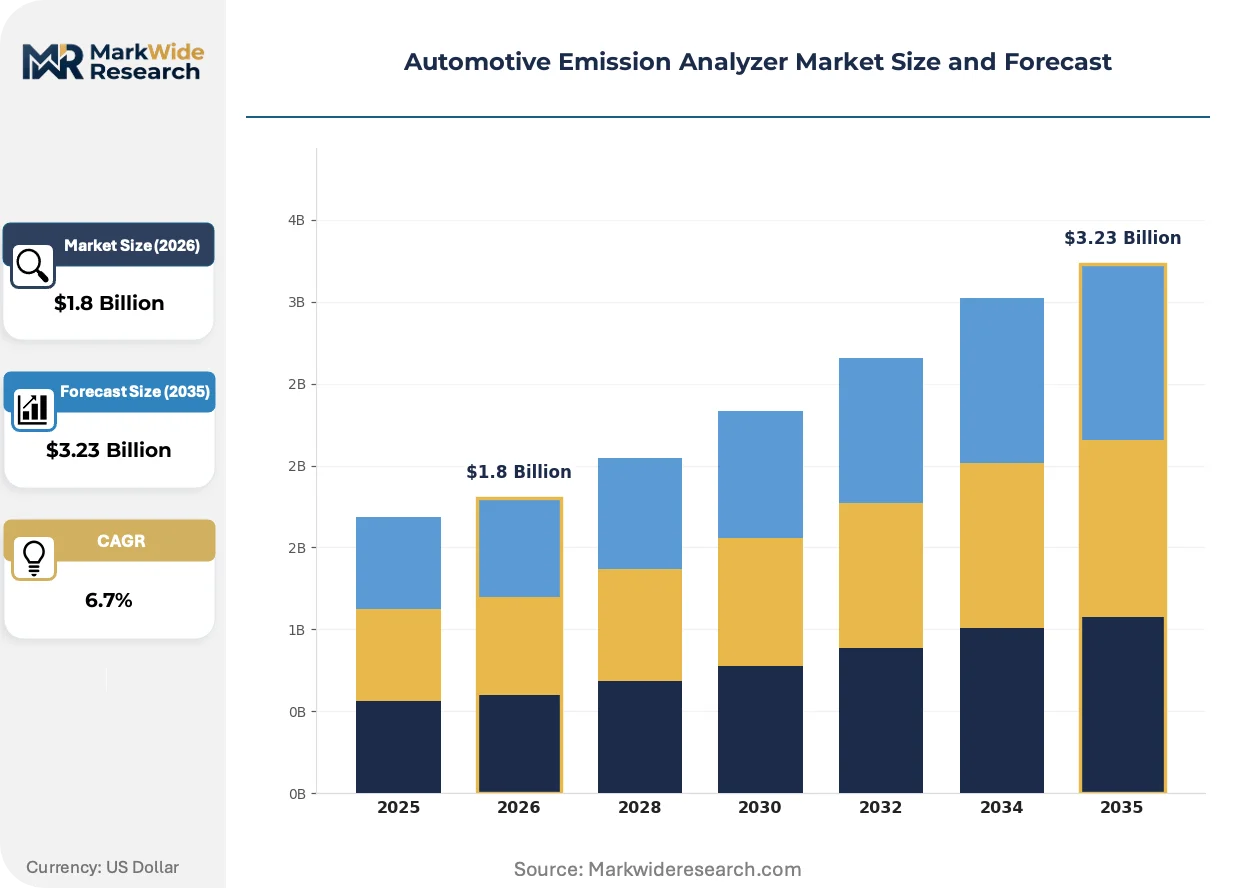
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Analyzers, Noise Measurement, Emission Testing Systems, Portable Analyzers Product Type: Fixed Analyzers, Mobile Analyzers, Hybrid Systems, Analytic Software End User: OEMs, Aftermarket Providers, Government Agencies, Research Institutions Application: On-Road Testing, Laboratory Testing, Compliance Monitoring, Fleet Management |
| Companies Covered | Testo SE & Co. KGaA, Siemens Aktiengesellschaft, Horiba Ltd., Sensors, Inc., Fuji Electric Co. Ltd., AVL List GmbH, Emerson Electric Co., MRU Instruments GmbH, Teledyne Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Emission Analyzer Market Emerging Trajectories
Analyzer hardware is converging with cloud telemetry and predictive maintenance platforms. Regulatory test protocol divergence is forcing modular sensor architectures that complicate manufacturing scale.
Quantum cascade laser spectroscopy is rewriting multi-gas measurement economics in laboratory certification benches. Powertrain test cell operators at German OEM facilities are adopting QCL benches for simultaneous CO, CO2, NO, NO2, and NH3 quantification at sub-ppm resolution. The technology is rewriting cost structures by collapsing multiple single-gas analyzers into one optical path, compressing capital expenditure per test lane by half.
EPA Tier 4 and Euro VII precursor rules are mandating particulate number counting alongside traditional mass measurement. Engine dynamometer suppliers must integrate condensation particle counters into existing gas analyzer benches, extending test cycle duration and calibration complexity. Heavy-duty engine manufacturers in the US Midwest and Rhineland are absorbing these capital costs ahead of type-approval deadlines.
Fleet procurement departments are unbundling analyzer hardware from service contracts. Large commercial vehicle operators in China's Pearl River Delta now source portable units directly while contracting third-party calibration services, bypassing traditional integrated vendors. This pattern is compressing vendor margins in the mobile analyzer segment while expanding aftermarket service addressability.
Automotive Emission Analyzer Market Segmentation
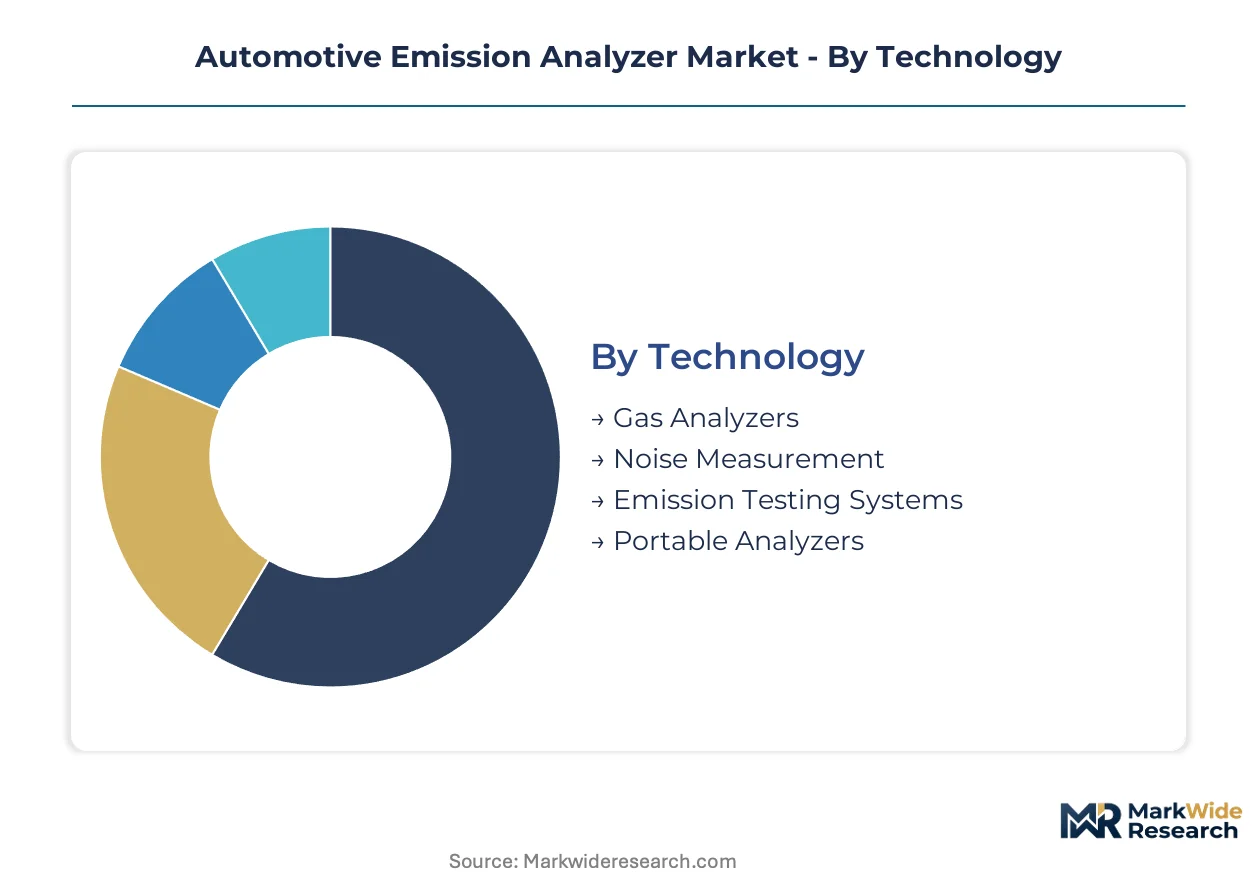
Analyzer procurement patterns diverge sharply across technology platforms and deployment contexts. Regulatory enforcement intensity and capital intensity requirements reshape segment prioritization for vendors and end-users alike.
Technology:
Standardization dominates gas measurement cores while customization proliferates at the sensor periphery.
- Gas Analyzers:Multi-constituent benches employing NDIR, chemiluminescence, and electrochemical cells to quantify CO, CO2, HC, and NOx at regulatory precision. Demand concentrates in German and Chinese certification laboratories where MIIT and EU Green Deal enforcement timelines compress procurement cycles.
- Portable Analyzers:Battery-powered units with wireless telemetry for roadside screening and depot spot-checks. California and Texas enforcement agencies deploy mobile screening units to replace fixed tunnel infrastructure, driving premium pricing for rapid-deployment hardware.
- Noise Measurement:Acoustic sensors integrated with exhaust flow meters for pass-by testing protocols.
- Emission Testing Systems:Integrated dynamometer-gas bench combinations for full vehicle certification.
Most installed capacity flows through Gas Analyzers. Expansion is steepest in Portable Analyzers.
Product Type:
Cost tier stratification separates permanent infrastructure from depreciable field assets.
- Fixed Analyzers:Permanent installations in certification laboratories and inspection stations with climate-controlled environments and hard-piped calibration gas distribution. OEM test cells in Stuttgart and Shanghai anchor demand for multi-lane configurations.
- Mobile Analyzers:Vehicle-mounted or trailer-deployed systems for on-road enforcement and fleet spot-audits. China's Pearl River Delta fleet operators source units directly while unbundling calibration services, compressing vendor margins.
- Hybrid Systems:Modular architectures allowing laboratory-to-roadside reconfiguration.
- Analytic Software:Cloud platforms for remote calibration management and predictive maintenance.
Laboratory and certification revenue pools concentrate in Fixed Analyzers. Mobile Analyzers command premium pricing in on-road testing applications.
End User:
Customer type determines contract structure and service attachment rates.
- OEMs:Powertrain manufacturers operating internal certification facilities with dedicated test lanes. Heavy-duty engine producers in the US Midwest and Rhineland absorb capital costs for Euro VII and EPA Tier 4 precursor compliance.
- Government Agencies:State and federal enforcement bodies procuring for roadside screening and periodic inspection regimes. Procurement prioritizes interoperability with existing enforcement databases.
- Aftermarket Providers:Independent service stations and fleet maintenance depots.
- Research Institutions:University laboratories and national metrology institutes.
OEMs dominate capital expenditure volume. Government Agencies drive standardization through procurement specifications.
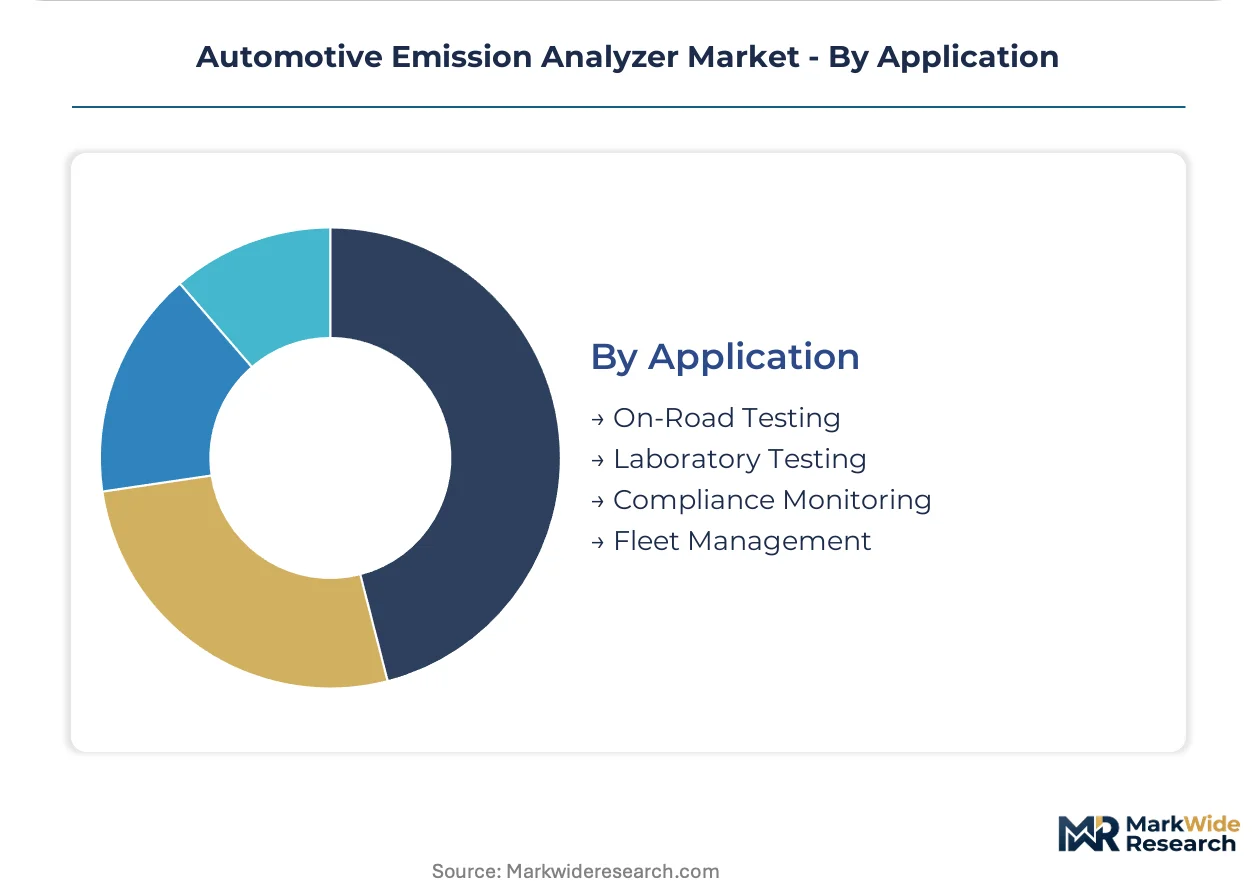
Application:
Volume-maturity tradeoffs separate established laboratory workflows from emerging connected fleet regimes.
- Laboratory Testing:Controlled-environment certification against regulatory test cycles including WLTC and FTP. Quantum cascade laser spectroscopy is collapsing multiple single-gas analyzers into one optical path at German OEM facilities.
- On-Road Testing:Real-world emission measurement using portable emission measurement systems and remote sensing. China's MIIT mandates real-time telemetry for heavy-duty diesel registrations in eastern manufacturing corridors.
- Compliance Monitoring:Continuous surveillance of in-service vehicle populations.
- Fleet Management:Operator-owned monitoring for preventive maintenance and regulatory pre-screening.
Laboratory Testing retains the largest revenue base. On-Road Testing is climbing the fastest as telemetry mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical metrology engineers cluster in Bavaria and Stuttgart anchor European analyzer design capacity. Chinese sensor specialists concentrate in Shenzhen and Suzhou. Indian calibration technicians are scaling in Pune and Chennai ahead of regulatory deadlines.
Germany
Heavy-duty fleet operators in the Rhineland are pre-buying analyzer capacity before EU Green Deal enforcement tightens. The KBA mandates parallel type-approval validation that compresses certification timelines. Stuttgart OEM test cells absorb capital costs for Euro VII precursor compliance while Bavarian optics clusters supply precision infrared sources.
China
MIIT mandates real-time emissions telemetry for heavy-duty diesel registrations across eastern manufacturing corridors. The MEE enforces continuous monitoring protocols that force inspection station retrofits. Shanghai and Suzhou host the densest concentrations of NDIR module assembly operations serving domestic certification laboratories.
United States
EPA Tier 4 precursor rules are doubling sensor stack costs for engine manufacturers in the Midwest. California CARB deploys mobile screening units to replace fixed tunnel infrastructure. Detroit heavy-duty engine producers and Austin enforcement agencies split demand between laboratory certification and roadside deployment hardware.
India
State transport authority test centers anticipate BS-VII analyzer upgrade mandates within three years. The country's national automotive regulator is finalizing protocol specifications that will obsolete existing chemiluminescence benches. Pune and Chennai technical institutes are scaling metrology training programs to address field service engineer scarcity.
Japan
METI funding accelerates hydrogen combustion test bench development for NH3 and N2O measurement. JIS standards revisions require simultaneous particulate number and mass quantification. Nagoya powertrain laboratories and Tokyo certification centers anchor demand for quantum cascade laser spectroscopy platforms.
Automotive Emission Analyzer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base organizes around three strategic archetypes: industrial automation platforms, precision measurement specialists, and integrated testing system providers. Consolidation pressures concentrate in sensor module supply where Bavarian optics clusters create geographic chokepoints. Competitive moves center on backward integration into infrared source manufacturing and technology licensing for quantum cascade laser platforms.
Among German fabricators, AVL List GmbH and MRU Instruments GmbH exemplify the precision measurement specialist archetype with deep roots in engine dynamometer integration. Horiba Ltd. represents the integrated testing system tier, anchoring multi-gas laboratory certification demand. Siemens Aktiengesellschaft occupies the industrial automation platform position, leveraging channel control in connected analyzer networks. These three patterns dominate competitive positioning across European and Asian procurement cycles.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| Siemens Aktiengesellschaft |
| Horiba Ltd. |
| Sensors, Inc. |
| Fuji Electric Co. Ltd. |
| AVL List GmbH |
| Emerson Electric Co. |
| MRU Instruments GmbH |
| Teledyne Technologies Incorporated |
| Others |
Supply Flow & Price Mechanics
Family-owned Bavarian optics specialists anchor precision infrared source manufacturing, translating captive process knowledge into pricing power over NDIR module supply while resisting margin compression from unbundled service demands.
Pricing Analysis
The bundled-vs-unbundled service split is compressing vendor margins in mobile analyzers while expanding aftermarket service addressability. Three-tier pricing structure across laboratory certification, roadside enforcement, and fleet spot-check tiers reflects calibration complexity and telemetry integration depth. Pricing pressure stems from fleet procurement departments in China's Pearl River Delta sourcing portable units directly while contracting third-party calibration services. Aftermarket providers and independent service stations exhibit highest price sensitivity; OEM test cells in Stuttgart and Shanghai show lowest sensitivity due to capital absorption for regulatory pre-compliance.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and recalibration of electrochemical sensor stacks are creating secondary supply channels that compete with new module procurement. Precision infrared source manufacturing concentrates in Germany, China, and Japan, with Bavarian clusters supplying German and Chinese certification laboratories. NDIR optical benches, quantum cascade laser platforms, and electrochemical cell arrays constitute critical component dependencies. Single-source vulnerability in German optics creates geographic chokepoint risk. Distribution runs through OEM direct procurement for laboratory systems and government tender channels for enforcement hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in connected analyzer networks where predictive maintenance contracts extend customer lifetime value, offsetting hardware margin compression from unbundled procurement patterns.
For Market Incumbents: Cement laboratory certification relationships through quantum cascade laser platform investments that collapse multiple single-gas analyzers into unified optical paths. Deepen backward integration into precision infrared source manufacturing to neutralize Bavarian supply chokepoints. Defend against fleet procurement unbundling by anchoring multi-year telemetry service contracts with state enforcement agencies.
For New Entrants and Emerging Players: Enter via India's impending BS-VII transition window, where state transport authority test centers will mandate analyzer upgrades and metrology talent scarcity creates partnership openings. Target portable analyzer segments for roadside enforcement agencies in Texas and California replacing fixed tunnel infrastructure. Pursue third-party calibration service contracts with Pearl River Delta fleet operators who have already unbundled hardware from service.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision measurement specialists with stranded chemiluminescence bench portfolios awaiting NDIR refresh cycles. Long-term viability hinges on hydrogen combustion test bench capabilities for NH3 and N2O measurement as METI-funded Japanese laboratories establish protocol precedents. Watch regulatory harmonization talks between Brussels and Beijing as inflection indicator for SKU compression or certification fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Cascade Laser Platform Deployment | Collapses multiple single-gas analyzers into one optical path, halving capital expenditure per test lane at German OEM facilities. |
| Backward Integration into Infrared Source Manufacturing | Neutralizes Bavarian supply chokepoint vulnerability and secures margin control over NDIR module production. |
| Predictive Maintenance Contract Expansion | Extends customer lifetime value through remote calibration management, offsetting hardware margin compression from unbundled procurement. |
| Hydrogen Combustion Test Bench Development | Captures emerging demand for NH3 and N2O slip measurement as METI-funded Japanese laboratories establish protocol precedents. |
| Mobile Screening Unit Deployment | Replaces fixed tunnel infrastructure for California CARB and Texas enforcement agencies, commanding premium pricing for rapid-deployment hardware. |
Methodological Framework
Direct dialogue with powertrain test cell operators, regulatory compliance officers at MIIT and EPA, fleet procurement managers, and aftermarket service technicians grounded qualitative insights. Secondary validation drew from EPA Tier 4 precursor rule filings, MIIT telemetry mandate documentation, EU Green Deal enforcement timelines, and IHS Markit vehicle production databases. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up modeling built from analyzer procurement cycles across OEM certification facilities, government enforcement agencies, and aftermarket service chains. Segmentation dimensions spanned technology platform, product mobility tier, end-user capital intensity, and application workflow maturity. CAGRs were derived from regression against regulatory deadline clustering and fleet replacement patterns. Hydrogen combustion testing protocols and quantum cascade laser adoption curves served as industry-specific forecast inputs.
Inputs from OEM test cell operators and government procurement officers were available through the study window; gaps in real-time enforcement deployment data and unbundled service contract pricing introduce uncertainty bands around mobile analyzer projections. Forecasts reflect assumptions on regulatory harmonization trajectory and sensor cost inflation curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Vehicle Emission Testers Market