
 Global Automotive Wind Tunnel Market | 2026-2036
Global Automotive Wind Tunnel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Wind Tunnel Market Analysis
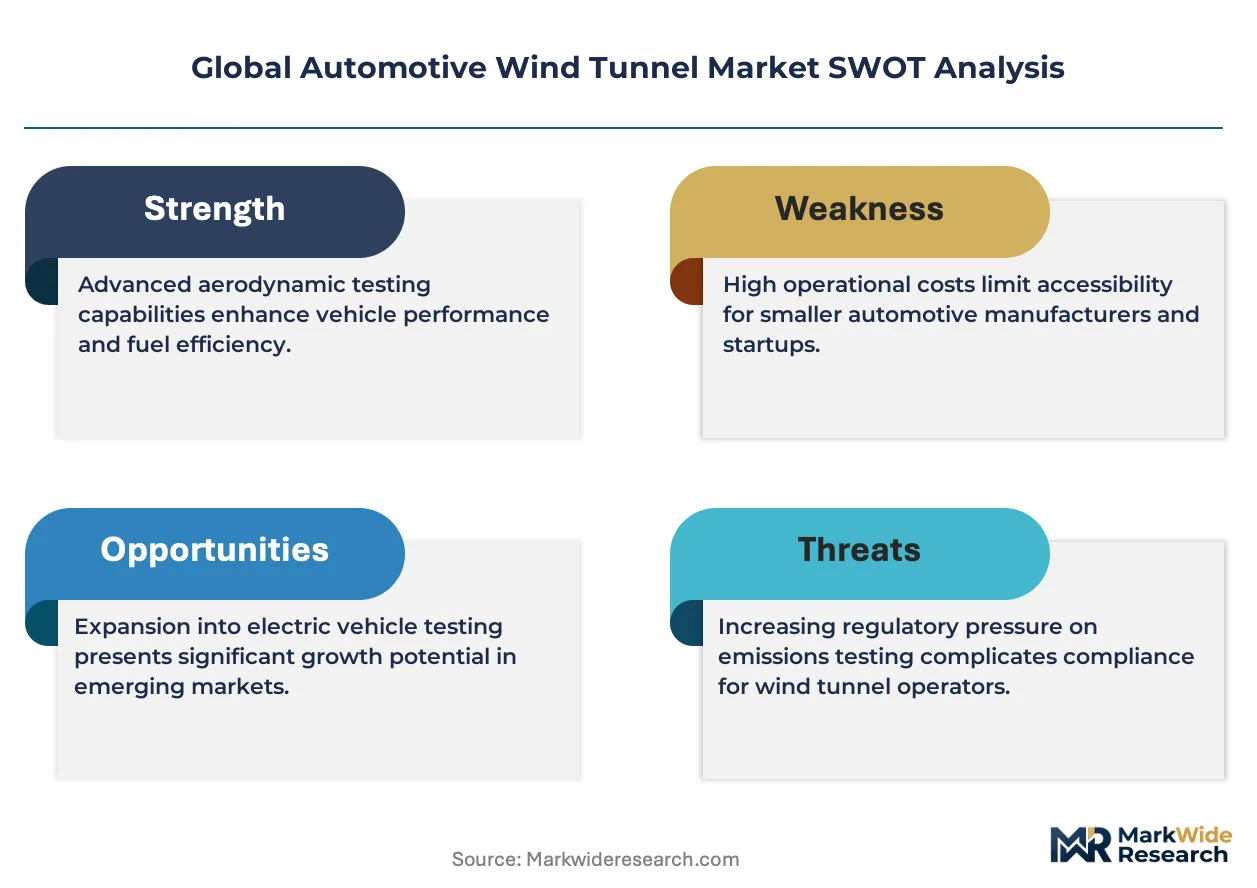
The shift from captive in-house wind tunnel ownership toward outsourced multi-source testing contracts is decoupling capital expenditure from test volume for mid-tier automotive suppliers. Siemens AG leverages its digital twin software portfolio to anchor hybrid physical-virtual testing workflows that reduce physical tunnel hours. Mahle GmbH sustains its position through specialized climatic wind tunnel services targeting thermal management validation for electric powertrains. RUAG Holding AG competes in the European motorsport and premium automotive segment with precision aerodynamic measurement systems.
Automotive wind tunnels are controlled airflow facilities that generate Reynolds-number-matched conditions from 10 to 250 km/h using axial fans or variable-frequency drives, enabling drag coefficient measurement, cooling flow mapping, and aeroacoustic source identification for road vehicle development. Closed jet technology dominates high-accuracy OEM validation programs where repeatability tolerances below 0.001 Cd are mandatory, while open jet configurations occupy motorsport and rapid prototyping applications where quick model changeover outweighs absolute precision. Testing services generate the largest revenue pool across service type segments, though design services are capturing margin expansion as simulation-to-test correlation requirements tighten.
The EU Green Deal and EPA tailpipe standards in the United States are forcing OEMs to document aerodynamic contributions toward fleet CO2 compliance, directly expanding third-party validation demand. ECE R101 and ISO 15016 testing protocols govern how drag values are measured and reported for regulatory homologation, creating barrier-to-entry effects for non-accredited tunnel operators. Stakeholders must monitor how China's MIIT new energy vehicle efficiency mandates and its evolving GB standards for aerodynamic drag reshape test program outsourcing patterns across Asia-Pacific supply chains.
Market Dynamics
Electric vehicle platform development is forcing aerodynamic validation into earlier design phases, compressing traditional testing timelines while expanding total tunnel hours demanded per vehicle program.
Growth Catalysts
- EU Green Deal fleet standards:Binding CO2 reduction mandates require documented aerodynamic contributions for regulatory homologation, expanding third-party validation contracts.
- Electric powertrain thermal management:Battery and motor cooling systems demand climatic wind tunnel testing across wider temperature ranges than internal combustion platforms.
- Germany's OEM facility concentration:Volkswagen, BMW, and Mercedes-Benz operate full-scale tunnels that anchor European testing capacity and attract supplier co-location.
Market Restraints
- Copper and rare-earth magnet costs:Variable-frequency drive systems for large axial fans face input price volatility that compresses equipment margins.
- Single-source fan blade suppliers:Precision-cast aluminum blade manufacturing concentrates in specialized foundries, creating supply bottlenecks for new tunnel construction.
- ECE R101 accreditation barriers:Mandatory certification for regulatory drag measurement creates fixed-cost entry thresholds that exclude smaller testing operators.
Strategic Opportunities
- India's PLI scheme for EV manufacturing:Domestic production incentives are attracting OEM assembly plants without matching wind tunnel infrastructure, creating service outsourcing demand.
- Digital twin convergence:CFD-to-physical correlation workflows combine simulation software with reduced-scale tunnel validation to compress development cycles.
- MIIT efficiency mandates in China:New energy vehicle aerodynamic drag thresholds are tightening faster than in-house testing capacity expansion, opening third-party contract windows.
Industry Challenges
- CFD-tunnel correlation expertise:Engineers capable of aligning computational models with physical measurement protocols remain scarce relative to demand from simulation-heavy workflows.
- Multi-year capex recovery:Full-scale climatic tunnels require decade-plus utilization commitments that strain balance sheets during EV transition uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Wind Tunnel Market |
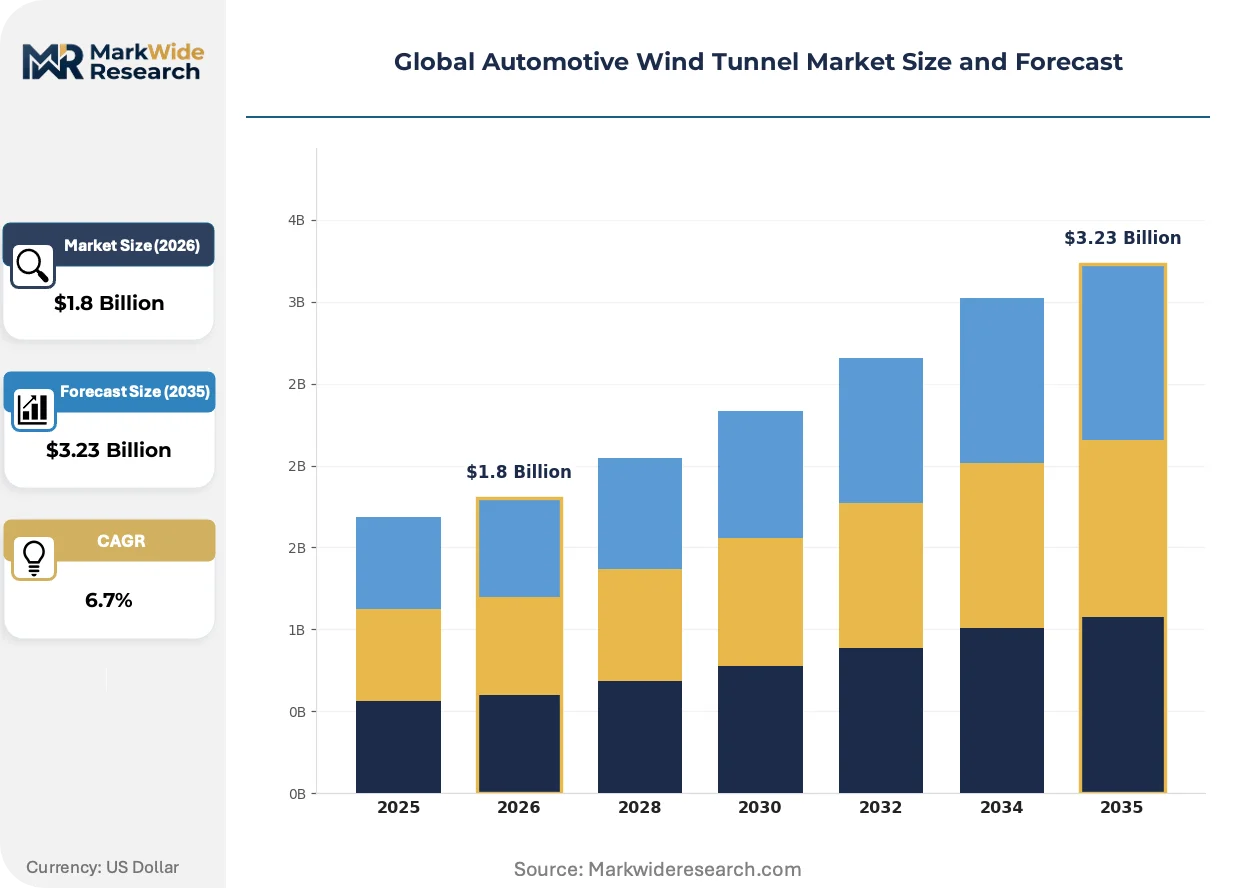
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerodynamic Testing, Component Testing, Performance Evaluation, Design Validation Technology: Open Jet, Closed Jet, Subsonic, Supersonic End User: OEMs, Tier-1 Suppliers, Research Institutions, Automotive Consultants Service Type: Testing Services, Consulting Services, Design Services, Validation Services |
| Companies Covered | Honda Aerodynamic Laboratory, Lockheed Martin Corporation, Siemens AG, Mitsubishi Heavy Industries, HORIBA MIRA Ltd., Mahle GmbH, Jacobs Engineering Group Inc., RUAG Holding AG, Audi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Wind Tunnel Market Emerging Trajectories
Testing workflows are fragmenting across physical-digital boundaries as simulation fidelity improves and regulatory documentation demands tighten simultaneously.
Moving ground belt systems with integrated boundary layer suction are modularizing to enable rapid reconfiguration between passenger car and commercial vehicle test setups. Tier-one suppliers in Germany and Japan are adopting these systems to serve mixed OEM portfolios without dedicated tunnel redundancy. This modularization is compressing capital requirements for multi-segment service providers while maintaining Reynolds-number fidelity.
EPA tailpipe standards and California's Advanced Clean Cars II framework are forcing drag coefficient documentation into fleet compliance submissions. OEMs must now correlate wind tunnel results with on-road validation protocols, expanding the scope of accredited testing services. The United States market is responding with expanded third-party tunnel certification investments to capture this regulatory-driven demand.
Automotive procurement departments are unbundling design validation from physical testing execution, creating separate contracts for simulation correlation versus tunnel hours. This purchasing pattern is displacing bundled in-house programs across mid-tier suppliers in South Korea and Japan. The shift is most visible among battery-electric platform teams seeking external validation of thermal-aerodynamic integration without captive facility ownership.
Global Automotive Wind Tunnel Market Segmentation
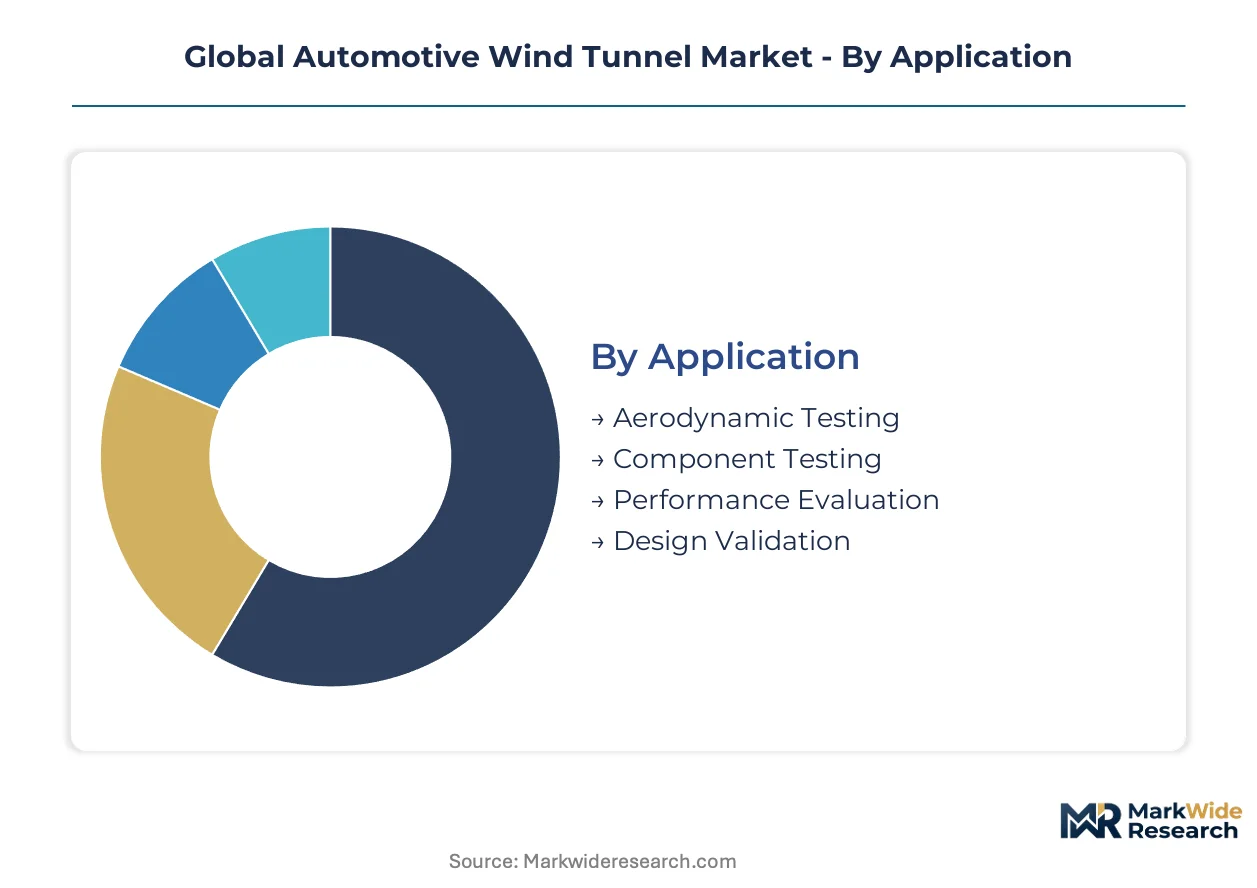
Automotive wind tunnel procurement divides sharply between captive OEM infrastructure and outsourced service contracts, with technology choices and regulatory accreditation requirements driving vendor selection criteria across each segment tier.
Application:
Program timing and regulatory submission deadlines determine which application category absorbs test volume.
- Aerodynamic Testing:Measures drag coefficient, lift forces, and pressure distribution using force balances and pressure taps across full-scale vehicle models. Volkswagen, BMW, and Mercedes-Benz operate dedicated tunnels in Germany where EU Green Deal fleet standards mandate documented Cd values for CO2 compliance submissions.
- Design Validation:Correlates computational fluid dynamics outputs with physical measurements to sign off production-intent body shapes before tooling commitment. Battery-electric platform teams concentrate validation demand in climatic tunnels capable of thermal-aerodynamic integration testing across temperature extremes from minus 20 to plus 40 degrees Celsius.
- Component Testing:Isolates cooling module performance, mirror aeroacoustics, and underbody flow patterns on sub-scale or hardware-in-loop rigs.
- Performance Evaluation:Benchmarks competitor vehicles and validates motorsport aerodynamic packages where repeatability tolerances relax in favor of rapid iteration cycles.
Volume sits with aerodynamic testing; growth tilts toward design validation.
Technology:
Accuracy requirements and capital recovery timelines separate open from closed jet configurations.
- Closed Jet:Encloses the test section within solid walls to eliminate free shear layer instability, achieving repeatability below 0.001 Cd for regulatory homologation under ECE R101 and ISO 15016 protocols. European OEM validation programs concentrate demand here, with Germany hosting the densest installed base of full-scale climatic closed jet facilities.
- Open Jet:Exposes the test section to ambient conditions, enabling rapid model changeover and accommodating oversized commercial vehicle prototypes. Motorsport development teams and rapid prototyping programs favor this configuration where absolute precision yields to iteration velocity.
- Subsonic:Covers the 0 to 250 km/h range relevant to road vehicle development using axial fan drives with variable-frequency motor control.
- Supersonic:Addresses specialized military and aerospace crossover applications with convergent-divergent nozzle designs rarely deployed in civilian automotive programs.
Capital deployment favors closed jet; flexibility premiums sustain open jet share in motorsport and commercial vehicle segments.
End User:
Facility ownership economics and test program confidentiality requirements shape buyer composition.
- OEMs:Operate captive tunnels for high-volume programs and competitively sensitive vehicle development, with Volkswagen, BMW, and Mercedes-Benz maintaining full-scale climatic facilities in Germany that anchor European testing capacity.
- Tier-1 Suppliers:Outsource validation to accredited third-party tunnels or lease capacity through multi-source contracts, decoupling capital expenditure from test volume during EV platform transitions.
- Research Institutions:Access national laboratory facilities or university-owned tunnels for fundamental aerodynamics and training programs.
- Automotive Consultants:Broker test program management and regulatory documentation services without direct facility operation.
Ownership concentrates with OEMs; outsourcing expands fastest among Tier-1 suppliers restructuring capital allocation.
Service Type:
Procurement unbundling separates simulation correlation from physical test execution.
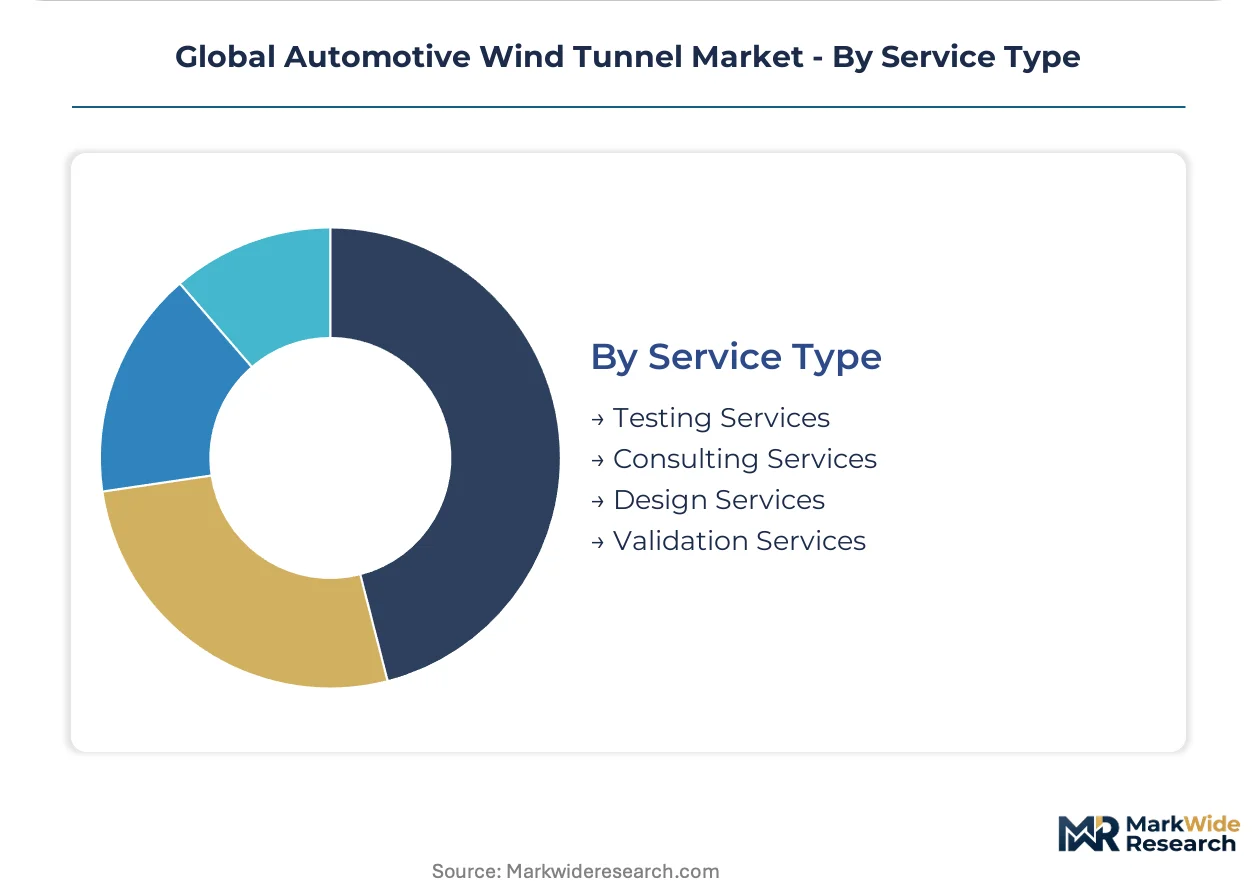
- Testing Services:Generates tunnel hours revenue through drag measurement, cooling flow mapping, and aeroacoustic source identification using instrumented full-scale or reduced-scale models.
- Design Services:Captures margin expansion from CFD-to-physical correlation workflows and shape optimization before metal cutting, with demand tightening as simulation fidelity requirements increase.
- Consulting Services:Advises on test program design, regulatory pathway navigation, and supplier qualification for ECE R101 accreditation.
- Validation Services:Packages documented test reports for EPA tailpipe standard submissions and EU fleet CO2 compliance evidence.
Revenue pools in testing services; margin expansion favors design services as correlation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-cast aluminum blade foundries in Germany and copper mining corridors in Chile anchor the automotive wind tunnel supply chain, with demand clustering around OEM engineering centers and regulatory compliance zones.
Germany
Volkswagen, BMW, and Mercedes-Benz operate full-scale climatic wind tunnel facilities in Wolfsburg, Munich, and Stuttgart. EU Green Deal fleet CO2 standards mandate documented aerodynamic contributions for homologation, expanding third-party validation contracts. The Stuttgart engineering corridor concentrates thermal-aerodynamic integration testing for battery-electric platforms.
United States
EPA tailpipe standards and California's Advanced Clean Cars II framework force drag coefficient documentation into fleet compliance submissions. OEMs must correlate wind tunnel results with on-road validation protocols. Detroit-area engineering centers and Southern California mobility clusters drive third-party tunnel certification investments.
China
MIIT new energy vehicle efficiency mandates tighten aerodynamic drag thresholds faster than in-house testing capacity expansion. Shanghai and Beijing automotive R&D centers outsource validation to accredited third-party tunnels. Yangtze River Delta manufacturing zones attract climatic tunnel service providers for thermal management testing.
Japan
METI efficiency regulations and JIS standards govern aerodynamic testing protocols for domestic and export vehicle programs. Nagoya-area engineering centers and Tokyo metropolitan R&D clusters concentrate climatic wind tunnel demand for hybrid and battery-electric powertrains. Tier-one suppliers increasingly unbundle design validation from physical testing execution.
India
PLI scheme incentives for EV manufacturing attract OEM assembly plants without matching wind tunnel infrastructure, creating service outsourcing demand. Tamil Nadu and Maharashtra automotive corridors lack full-scale climatic facilities relative to program volume. Third-party testing contracts are expanding to fill this capacity gap.
Global Automotive Wind Tunnel Market Vendor Landscape
Global majors compete with regional champions across facility accreditation and digital twin integration capabilities. The market structures around three tiers: captive OEM infrastructure operators, accredited third-party service providers, and hybrid physical-virtual testing specialists. Strategic moves concentrate on modular ground belt system deployment and ECE R101 accreditation expansion to capture regulatory-driven validation demand.
Within the hybrid physical-virtual tier, Siemens AG anchors digital twin software-to-tunnel correlation workflows. Mahle GmbH and RUAG Holding AG exemplify specialized service archetypes, with the former positioned around climatic validation and the latter occupying precision measurement segments. These three entities represent distinct competitive vectors: software-anchored integration, thermal-management specialization, and motorsport-adjacent precision systems.
| Leading Market Players |
|---|
| Honda Aerodynamic Laboratory |
| Lockheed Martin Corporation |
| Siemens AG |
| Mitsubishi Heavy Industries |
| HORIBA MIRA Ltd. |
| Mahle GmbH |
| Jacobs Engineering Group Inc. |
| RUAG Holding AG |
| Audi AG |
| Others |
Supply Flow & Price Mechanics
Precision-cast aluminum blade foundries in Germany and copper mining corridors in Chile concentrate specialized workforce pools that anchor labor-cost differentials across three-tier pricing structures spanning premium ECE R101-accredited validation, standard climatic testing, and economy rapid-prototyping services.
Pricing Analysis
Warranty and service bundling separates premium tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects ECE R101 accreditation status and climatic capability range. Price differentiation centers on certification grade and thermal-aerodynamic integration complexity. Pricing pressure stems from copper and rare-earth magnet cost volatility compressing equipment margins. Tier-1 suppliers exhibit highest price sensitivity due to capital decoupling strategies, while OEMs prioritize repeatability tolerances over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for precision-cast aluminum fan blades mandate multi-supplier qualification across German and Japanese foundries. Variable-frequency drive systems draw from copper supply chains anchored in Chile and copper refining concentrated in China. Permanent magnet dependencies rest on rare-earth processing corridors. Single-source vulnerability in specialized blade manufacturing creates bottleneck risk for new tunnel construction. Distribution runs through OEM direct procurement and Tier-1 supplier multi-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive wind tunnel sector sits in a technology-transition phase where digital twin workflows anchored in Siemens AG's simulation portfolio are displacing legacy captive facility ownership models.
For Market Incumbents: Hedge against simulation-to-test correlation margin compression by deepening ECE R101 accreditation portfolios and deploying modular ground belt systems that enable rapid reconfiguration between passenger car and commercial vehicle setups. Threats from CFD-heavy battery-electric platform teams reducing physical tunnel hours demand defensive certification investments. For New Entrants and Emerging Players: Digital-channel route through hybrid physical-virtual testing workflows offers lowest barrier-to-entry penetration. White-space targets concentrate in India's PLI scheme corridors lacking climatic infrastructure and China's MIIT-mandated third-party validation demand. Go-to-market through thermal-aerodynamic integration specialization for electric powertrains bypasses incumbent closed jet dominance. For Investors and Strategic Acquirers: Re-rating potential sits with accredited third-party service providers given EU Green Deal fleet standard enforcement tightening. Long-term viability over a multi-year window favors operators with ECE R101 certification and digital twin integration capabilities. Acquisition target archetype: regional climatic tunnel operators in Asia-Pacific with MIIT accreditation pathways. Signal to watch: MIIT efficiency mandate threshold acceleration outpacing in-house capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R101 Accreditation Expansion | Captures regulatory-driven validation demand from EU Green Deal fleet compliance submissions. |
| Modular Ground Belt System Deployment | Enables Tier-1 suppliers to serve mixed OEM portfolios without dedicated tunnel redundancy. |
| Digital Twin Software Integration | Compresses development cycles through CFD-to-physical correlation workflows for electric platforms. |
| Climatic Tunnel Capacity Addition | Addresses battery-electric thermal management testing across expanded temperature ranges. |
| Third-Party Validation Partnership | Decouples capital expenditure from test volume for mid-tier suppliers during EV transitions. |
Methodological Framework
Regulatory filings from EPA and ECHA, trade databases tracking precision-cast aluminum blade flows, and OEM annual disclosures formed the secondary backbone. Primary interviews with wind tunnel facility directors, Tier-1 supplier procurement leads, OEM platform engineers, and ECE R101 accreditation auditors combined with secondary validation. Bottom-up project pipeline analysis and top-down market sizing triangulated across the automotive aerodynamics sector.
Historical trendline analysis of tunnel utilization rates and capital expenditure cycles anchored the projection framework. Segmentation dimensions modeled include application type, jet configuration technology, end-user ownership structure, and service type unbundling patterns. CAGRs derived from regression analysis against electric vehicle platform development timelines and regulatory compliance deadline clustering. Industry-specific inputs incorporated MIIT efficiency mandate trajectories and EU Green Deal fleet standard phase-in schedules.
The model holds under steady regulatory enforcement timelines; deviation in MIIT mandate acceleration or ECE R101 protocol revision would shift capacity expansion assumptions materially. Deviation in rare-earth magnet supply disruption or copper price volatility would compress equipment margin outlooks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Durability Testing Market