
 ADAS Calibration Equipment Market | 2026-2036
ADAS Calibration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
ADAS Calibration Equipment Market Analysis
Equipment leasing and pay-per-use financing is narrowing the capital barrier for mid-sized repair chains seeking multi-sensor calibration capability. Robert Bosch GmbH leverages its OEM channel relationships to bundle calibration tools with diagnostic software subscriptions. Hella Gutmann Solutions GmbH anchors its position in European independent workshops through technician certification programs tied to its static calibration platforms. TEXA S.p.A. competes on integrated diagnostic-to-calibration workflows that reduce bay occupancy time.
ADAS calibration equipment comprises precision alignment tools, target assemblies, and diagnostic interfaces that restore sensor geometric accuracy to manufacturer specifications using laser triangulation, camera-to-target mapping, and radar reflector positioning. Static calibration tools dominate current installed bases due to lower facility requirements and broader protocol coverage across European and Asian vehicle platforms. Camera calibration systems represent the fastest-expanding technology segment as surround-view and interior monitoring mandates proliferate, while radar calibration systems command premium pricing tiers driven by 77 GHz and 4D imaging radar complexity. OEM service providers constitute the most concentrated end-user margin pool given captive specification control and multi-year service contracts.
The EU General Safety Regulation and UNECE R79/R157 frameworks mandate type-approved calibration procedures for lane-keeping and automated lane-change systems, compelling equipment vendors to pursue homologation partnerships. The US NHTSA FMVSS 127 final rule on automatic emergency braking will require standardized post-repair verification, expanding addressable demand beyond luxury vehicle segments. Stakeholders must monitor regulatory divergence between camera-centric European protocols and radar-weighted US testing architectures when prioritizing R&D allocation and regional distribution partnerships.
Market Dynamics
Windshield replacement and collision repair now trigger mandatory camera and radar recalibration, forcing automotive repair shops to absorb capital-intensive precision equipment or exit ADAS service lanes entirely.
Growth Catalysts
- EU General Safety Regulation:Mandates intelligent speed assistance and lane-keeping systems across all new vehicle types, compelling OEMs and independent workshops to install certified static calibration platforms.
- US FMVSS 127 final rule:NHTSA's automatic emergency braking standard requires standardized post-repair verification, extending calibration demand beyond luxury segments into mass-market collision repair.
- Surround-view camera proliferation:Multi-camera parking and interior monitoring systems multiply sensor count per vehicle, increasing recalibration frequency at glass replacement chains and dealership service departments.
Market Restraints
- Capital intensity:Static calibration platforms require precision-ground floor surfaces and controlled lighting, creating facility retrofit costs that exclude smaller independent garages from compliance.
- Protocol fragmentation:Each OEM maintains proprietary target geometries and software interfaces, forcing equipment vendors to pursue expensive homologation partnerships with limited volume guarantees.
- Technician certification bottlenecks:Hella Gutmann Solutions and Robert Bosch restrict advanced diagnostic access to certified technicians, limiting labor pool expansion and extending service appointment backlogs.
Strategic Opportunities
- Equipment-as-a-service models:Pay-per-use financing and leasing structures lower capital barriers for mid-sized repair chains seeking multi-sensor calibration capability without balance-sheet commitment.
- India aftermarket expansion:Rising vehicle safety content in domestic passenger cars creates first-mover advantage for calibration equipment vendors establishing technician training networks before regulatory mandates formalize.
- Diagnostic-to-calibration integration:Unified workflows that collapse fault identification and sensor realignment into single bay occupancy cycles capture premium positioning against standalone calibration tool vendors.
Industry Challenges
- Homologation timeline compression:UNECE R79 and R157 type-approval requirements for lane-keeping and automated lane-change systems force equipment vendors to synchronize hardware releases with shifting regulatory test protocols.
- Multi-protocol inventory burden:Repair shops must maintain target assemblies and software licenses for German, Japanese, and US OEM specifications simultaneously, straining working capital and storage capacity.
- Skill migration from mechanical to electronic:Traditional collision repair technicians lack optical alignment and radar reflector positioning competencies, requiring retraining programs that extend technician onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADAS Calibration Equipment Market |
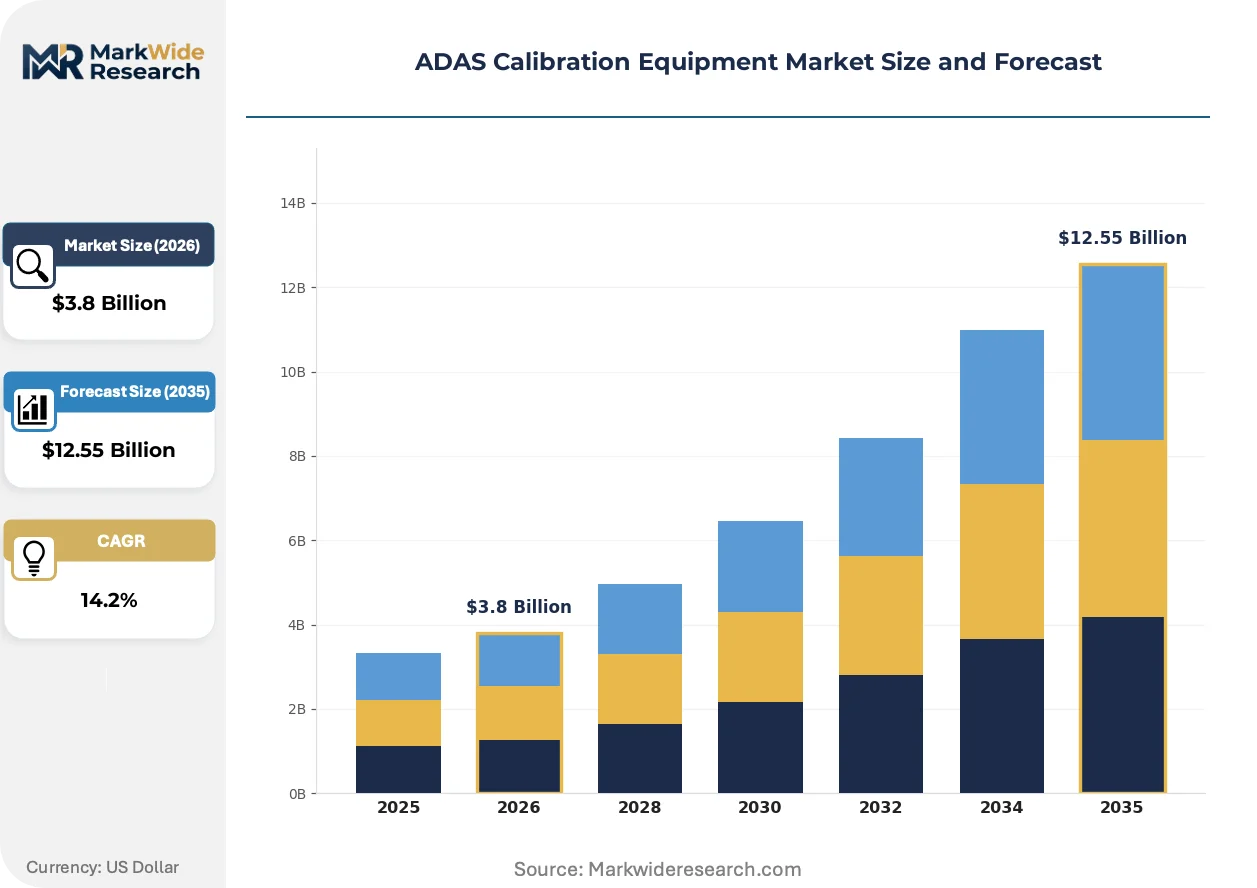
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Calibration Tools, Dynamic Calibration Tools, Advanced Diagnostic Equipment, Target Plates End User: Automotive Repair Shops, OEM Service Providers, Vehicle Manufacturers, Aftermarket Retailers Technology: Laser-Based Systems, Camera Calibration Systems, Radar Calibration Systems, Optical Measurement Technologies Distribution Channel: Direct Sales, Online Retail, Distributors, Service Centers |
| Companies Covered | Autel Intelligent Technology Co., Ltd., Hella Gutmann Solutions GmbH, Robert Bosch GmbH, John Bean USA, Beissbarth GmbH, Hunter Engineering Company, Snap-on Incorporated, MAHA Maschinenbau Haldenwang GmbH & Co. KG, TEXA S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADAS Calibration Equipment Market Emerging Trajectories
Virtualization of calibration procedures is compressing facility requirements and enabling remote diagnostic verification, while regulatory divergence between camera-centric European protocols and radar-weighted US architectures forces vendors into parallel development tracks.
Digital twin technology is virtualizing physical target-based calibration by simulating sensor geometric relationships through software-defined environments. Tier-1 OEM service departments in Germany and Japan are piloting these systems to reduce bay occupancy from 45 minutes to under 10 minutes for routine camera alignments. This compression is virtualizing the traditional static calibration revenue model and redirecting equipment spend toward diagnostic software subscriptions.
UNECE R157 type-approval frameworks for automated lane-change systems now mandate documented recalibration traceability, compelling equipment vendors to embed blockchain-verified audit logs directly into calibration tool firmware. European independent workshops face compliance deadlines that favor vendors with pre-homologated platform portfolios. German KBA inspection regimes are rejecting aftermarket repairs lacking certified calibration certificates, tightening specification control around OEM-authorized equipment channels.
Subscription-based diagnostic access is displacing perpetual licensing in North American collision repair chains, with monthly fees bundling calibration software updates, target geometry libraries, and remote technical support. Large multi-shop operators in Texas and California negotiate enterprise agreements that consolidate vendor relationships and standardize technician training across distributed locations. This consolidation concentrates purchasing power among regional repair consolidators and marginalizes standalone equipment vendors lacking national service networks.
ADAS Calibration Equipment Market Segmentation
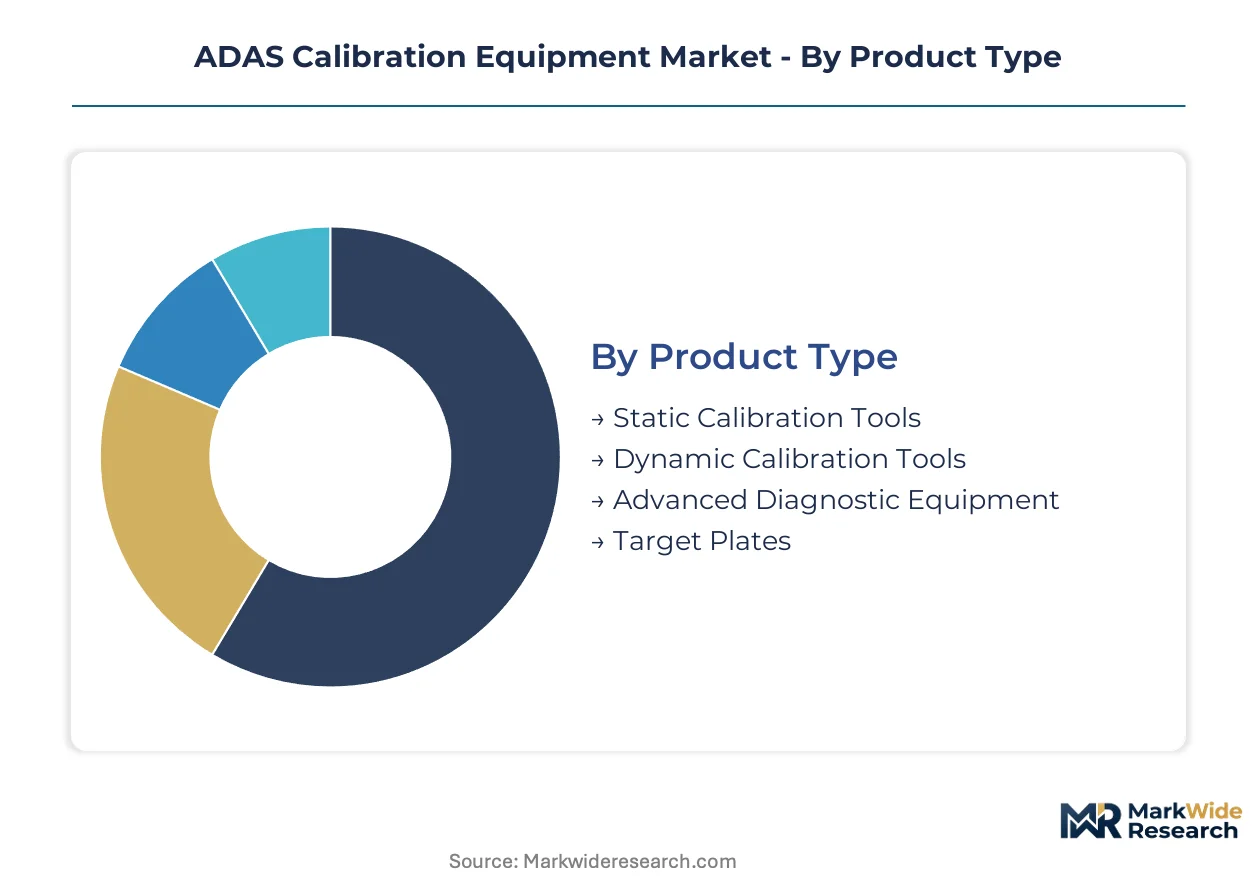
ADAS calibration equipment vendors pursue divergent segment strategies based on capital intensity, certification requirements, and technician training dependencies. Product architecture choices determine facility retrofit costs and recurring software revenue potential. End-user concentration shapes pricing power and service contract structures across OEM-captive versus independent channels.
Product Type:
Cost tier differentiation separates entry-level static platforms from premium dynamic systems requiring specialized bay infrastructure and environmental controls.
- Static Calibration Tools:Precision-ground floor surfaces and controlled lighting environments enable camera-to-target mapping without vehicle movement. German independent workshops and US glass replacement chains dominate procurement due to lower facility requirements and broader OEM protocol coverage.
- Dynamic Calibration Tools:Road-based sensor verification systems require dedicated test tracks or public road access with GPS synchronization and dynamic target vehicles. Japanese OEM service departments in Toyota City and Nagoya clusters favor these for final validation of lane-keeping systems before customer delivery.
- Advanced Diagnostic Equipment:Integrated fault identification and calibration command interfaces reduce bay occupancy cycles.
- Target Plates:Proprietary geometric patterns and reflector assemblies for specific OEM camera and radar specifications.
Static Calibration Tools hold installed capacity. Dynamic Calibration Tools is rotating up the share rankings.
End User:
Customer type concentration determines specification control, with OEM-captive channels enforcing proprietary protocols that marginalize independent competitors.
- OEM Service Providers:Manufacturer-authorized facilities in Stuttgart, Detroit, and Nagoya maintain exclusive access to pre-release target geometries and encrypted calibration software. Multi-year service contracts and captive parts pricing create the most concentrated margin pool in the value chain.
- Automotive Repair Shops:Independent collision repair and glass replacement chains face capital barriers from precision facility requirements and multi-protocol inventory burdens. Mid-sized US operators in Texas and California consolidate purchasing through enterprise agreements to offset technician certification costs.
- Vehicle Manufacturers:Assembly plant end-of-line calibration for camera, radar, and lidar systems before dealership delivery.
- Aftermarket Retailers:Parts distributors and equipment resellers serving non-certified repair channels with generic calibration accessories.
OEM Service Providers command pricing premiums. Automotive Repair Shops is gaining share fastest through consolidation.
Technology:
Application complexity separates optical alignment systems from electromagnetic sensor verification requiring anechoic chamber infrastructure.
- Camera Calibration Systems:Laser triangulation and structured light projection restore geometric accuracy for surround-view, forward-facing, and interior monitoring cameras. Demand concentrates in Germany and Japan where EU General Safety Regulation and domestic type-approval frameworks mandate documented recalibration traceability.
- Radar Calibration Systems:77 GHz and 4D imaging radar verification demands anechoic chambers or precision reflector positioning with millimeter-wave signal analysis. US NHTSA FMVSS 127 compliance deadlines are extending procurement beyond luxury vehicle segments into mass-market collision repair networks.
- Laser-Based Systems:High-precision distance measurement for static alignment reference points.
- Optical Measurement Technologies:Non-contact sensor positioning using photogrammetry and structured light.
Camera Calibration Systems dominates current revenue. Radar Calibration Systems exhibits the steepest expansion trajectory from regulatory mandates.
Distribution Channel:
Supply concentration favors direct relationships with large fleet operators and national repair chains, marginalizing fragmented distributor networks.
- Direct Sales:Vendor field engineers negotiate enterprise agreements with multi-shop operators, bundling equipment, software subscriptions, and technician certification programs. German KBA inspection regimes and US insurer direct repair programs favor vendors with national service networks and rapid technical response capabilities.
- Distributors:Regional equipment resellers serve independent garages with limited calibration volumes and sporadic replacement part needs.
- Online Retail:E-commerce platforms for standardized accessories, replacement targets, and software license renewals.
- Service Centers:Manufacturer-operated facilities providing equipment maintenance, calibration verification, and firmware updates.
Direct Sales captures the premium tier. Distributors is rotating up the share rankings through mid-market consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU General Safety Regulation and US NHTSA FMVSS 127 are forcing certified calibration infrastructure deployment across major automotive markets, with equipment procurement clustering around OEM service hubs and collision repair consolidation zones.
United States
Texas and California collision repair chains are consolidating purchasing power through enterprise agreements that bundle equipment leasing with technician certification. The NHTSA FMVSS 127 final rule on automatic emergency braking mandates standardized post-repair verification, extending calibration demand beyond luxury segments into mass-market glass replacement networks. Dallas-Fort Worth and Los Angeles metro areas host the densest concentrations of multi-shop operators deploying static calibration platforms.
Germany
Stuttgart and Munich OEM service departments maintain exclusive access to pre-release target geometries and encrypted calibration software under multi-year service contracts. The KBA inspection regime rejects aftermarket repairs lacking certified calibration certificates, tightening specification control around authorized equipment channels. Bavarian and Baden-Württemberg independent workshops face compliance deadlines that favor vendors with pre-homologated platform portfolios.
Japan
Toyota City and Nagoya clusters favor dynamic calibration systems for final validation of lane-keeping systems before customer delivery. Domestic type-approval frameworks mandate documented recalibration traceability, concentrating procurement among equipment vendors with embedded blockchain-verified audit logs. Chubu region OEM service departments pilot digital twin technology to compress bay occupancy from 45 minutes to under 10 minutes for routine camera alignments.
China
Yangtze River Delta and Pearl River Delta vehicle assembly plants drive end-of-line calibration equipment demand for camera, radar, and lidar systems before dealership delivery. The country's national automotive safety regulator is developing type-approval frameworks for intelligent driving systems that will formalize post-repair calibration requirements. Shanghai and Shenzhen technology corridors attract domestic equipment vendors establishing technician training networks ahead of regulatory mandate formalization.
India
Maharashtra and Tamil Nadu aftermarket expansion creates first-mover advantage for calibration equipment vendors establishing technician training networks before regulatory mandates formalize. Rising vehicle safety content in domestic passenger cars from Maruti Suzuki and Hyundai Motor India is generating initial procurement of static calibration platforms. Pune and Chennai industrial corridors concentrate glass replacement chain investment in multi-sensor calibration capability.
ADAS Calibration Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players for specification influence across OEM-captive and independent workshop segments. The vendor base stratifies into three tiers: multinational automotive suppliers with diagnostic software ecosystems, dedicated calibration equipment specialists with technician certification programs, and diversified tool manufacturers with distribution scale. Consolidation pressure concentrates among mid-sized repair chains seeking enterprise pricing leverage, while technology licensing and diagnostic-to-calibration workflow integration represent the dominant competitive moves reshaping procurement relationships.
Within the multinational supplier tier, Robert Bosch GmbH and Hella Gutmann Solutions GmbH exemplify channel-control strategies through OEM relationship leverage and certification-program anchoring. TEXA S.p.A. occupies a position exemplifying workflow integration specialists that collapse fault identification and sensor realignment into unified bay occupancy cycles. Autel Intelligent Technology Co., Ltd. represents scale-driven equipment fabricants competing on integrated diagnostic platform breadth.
| Leading Market Players |
|---|
| Autel Intelligent Technology Co., Ltd. |
| Hella Gutmann Solutions GmbH |
| Robert Bosch GmbH |
| John Bean USA |
| Beissbarth GmbH |
| Hunter Engineering Company |
| Snap-on Incorporated |
| MAHA Maschinenbau Haldenwang GmbH & Co. KG |
| TEXA S.p.A. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision-ground floor surface fabrication across Bavaria and Baden-Württemberg is compressing supplier margins while amplifying pricing power for vendors with captive manufacturing. Equipment buyers face extended lead times that force acceptance of bundled software subscriptions to secure delivery slots.
Pricing Analysis
Certification grade (CE marking tier) creates the primary spread between static calibration platforms, with KBA-homologated systems commanding substantial premiums over generic alternatives. Subscription-based SaaS tiers now dominate, bundling firmware updates and target geometry libraries into recurring revenue streams. Cost compression in mid-tier equipment is intensifying because glass replacement chains negotiate enterprise volume agreements. Independent garages exhibit highest price sensitivity, while OEM-captive service departments absorb premiums for encrypted calibration protocols.
Supply Chain Analysis
Export controls on precision laser measurement components under dual-use technology regulations limit flows from Germany and Japan to certain end-markets. Manufacturing concentrates in Germany, China, and the United States for alignment platforms and diagnostic interfaces. Production draws from specialized optical glass, precision-machined aluminum frames, and millimeter-wave radar reflectors. Single-source vulnerability runs through German suppliers of laser triangulation modules. Distribution runs through vendor field engineers for enterprise accounts and regional distributors for independent workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across protocol standards and certification regimes is creating niche opportunities for specialized equipment vendors. The shift from perpetual licensing to subscription access fragments purchasing authority and opens entry points for workflow-integrated challengers.
For Market Incumbents: Build certification moats by accelerating KBA and UNECE homologation timelines ahead of regulatory deadlines. Deepen backward integration into precision optical component manufacturing to insulate against German laser module supply constraints. Consolidate technician training networks to lock in multi-year service contracts with collision repair chains facing skill migration bottlenecks.
For New Entrants and Emerging Players: Build out India aftermarket presence before domestic safety mandates formalize, establishing technician certification networks in Maharashtra and Tamil Nadu. Target mid-sized US glass replacement chains in Texas and California with equipment-as-a-service financing that eliminates capital barriers. Pursue diagnostic-to-calibration workflow integration as the primary go-to-market angle against standalone tool vendors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-software tiers as recurring revenue displaces equipment sales. Long-term viability favors vendors with embedded regulatory compliance capabilities and national service networks. Acquisition targets should display pre-homologated platform portfolios and established OEM channel relationships. Watch for inflection when blockchain-verified audit logs become mandatory across EU member states.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Homologation Partnership | UNECE R79/R157 compliance locks in specification control for lane-keeping calibration protocols. |
| Technician Certification Network Expansion | Hella Gutmann Solutions and Bosch restrict advanced access to certified technicians, creating channel loyalty. |
| Diagnostic-to-Calibration Workflow Integration | TEXA S.p.A. collapses fault identification and sensor realignment into single bay occupancy cycles. |
| Equipment-as-a-Service Financing Launch | Pay-per-use structures lower capital barriers for mid-sized US repair chains in Texas and California. |
| Digital Twin Technology Pilot | German and Japanese OEM service departments compress bay occupancy from 45 minutes to under 10 minutes. |
Methodological Framework
A spread of perspectives from collision repair chain operations directors, OEM service department managers, glass replacement network procurement leads, and calibration equipment vendor sales executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed automotive suppliers, NHTSA FMVSS docket records, EU General Safety Regulation implementation guidance, and vehicle production databases. Bottom-up equipment unit economics and top-down addressable service bay calculations were triangulated for cross-verification.
Demand-supply balance dynamics across static and dynamic calibration platforms anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product architecture, end-user concentration, technology complexity, and regional regulatory cluster. CAGRs were derived from equipment refresh cycle analysis and mandate-driven installation base expansion. Key forecast inputs incorporated KBA inspection regime compliance deadlines and NHTSA FMVSS 127 implementation timelines.
Stress conditions across homologation timeline compression, protocol fragmentation, and technician certification bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM specification control persistence. Material shifts in UNECE type-approval requirements or NHTSA verification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Vehicle Radar Test System Market