
 Car Crash Simulator Systems and Services Market | 2026-2036
Car Crash Simulator Systems and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Car Crash Simulator Systems and Services Market Insights
European engineering software houses is consolidating around high-fidelity crash dynamics platforms. Dassault Systèmes leverages its integrated design-to-simulation workflow across French and German automotive clusters. Siemens AG anchors its position through hardware-in-the-loop testing infrastructure tied to major OEM validation centers. Ansys competes aggressively on solver speed for multi-material impact scenarios.
Car crash simulator systems and services encompass hardware rigs, software solvers, and professional services that replicate vehicle collision dynamics through finite element analysis and physical sled testing, typically operating at sampling rates exceeding 10 kHz to capture deformation, occupant kinematics, and restraint system performance for regulatory homologation and design optimization. The software segment leads value generation as automakers shift toward virtual certification pathways, while physics-based simulation commands premium pricing due to solver licensing complexity and specialist workforce requirements. Hardware retains structural importance for final validation stages, though its growth trajectory lags software adoption curves.
NHTSA's Federal Motor Vehicle Safety Standards, Euro NCAP assessment protocols, and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements collectively mandate repeatable crash test documentation that only validated simulation platforms can efficiently generate. China's MIIT is expanding mandatory new energy vehicle crash standards that require domestic and foreign suppliers to localize simulation service capabilities. Stakeholders must weigh capital allocation between proprietary solver development and strategic partnerships with established platform vendors as regulatory stringency tightens across major automotive production jurisdictions.
Market Dynamics
Virtual certification pathways are compressing hardware-in-the-loop testing cycles as automakers reallocate R&D budgets toward solver-based validation. This structural shift privileges software vendors with regulatory-grade platform credentials over traditional sled-testing equipment suppliers.
Growth Catalysts
- Euro NCAP protocol expansion:Updated assessment criteria for autonomous emergency braking and vulnerable road user protection mandate expanded simulation coverage for five-star ratings.
- Multi-material vehicle architectures:Carbon fiber-reinforced polymer and high-strength steel combinations in electric vehicle platforms require physics-based solvers capable of modeling complex failure modes.
- Japan's METI type-approval digitization:Streamlined documentation workflows for new energy vehicle homologation accelerate adoption of integrated design-to-simulation platforms among domestic OEMs.
Market Restraints
- Specialist workforce scarcity:Finite element analysis expertise for crash dynamics commands premium compensation, constraining service provider scaling in Germany and Japan.
- High-performance computing infrastructure costs:On-premise solver licensing and GPU cluster maintenance impose capital barriers for mid-tier engineering consultancies.
- Validation hardware dependency:Final regulatory submission still requires physical sled-test correlation, preventing full software substitution of capital-intensive crash facilities.
Strategic Opportunities
- China MIIT localization mandates:Foreign simulation suppliers must establish domestic service capabilities to support new energy vehicle crash standard compliance, creating partnership entry points.
- Real-time occupant modeling convergence:Integration of biomechanical finite element models with active restraint system control algorithms opens adjacent service revenue streams.
- Cloud-native solver delivery:Subscription-based access to elastic compute resources lowers barriers for tier-two suppliers and aftermarket safety researchers.
Industry Challenges
- Correlating virtual and physical test results:Regulatory authorities require documented margin-of-error protocols that extend certification timelines for novel solver implementations.
- Legacy platform integration friction:Established OEM validation centers face workflow disruption when migrating from decade-old proprietary codes to modern multi-physics environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Crash Simulator Systems and Services Market |
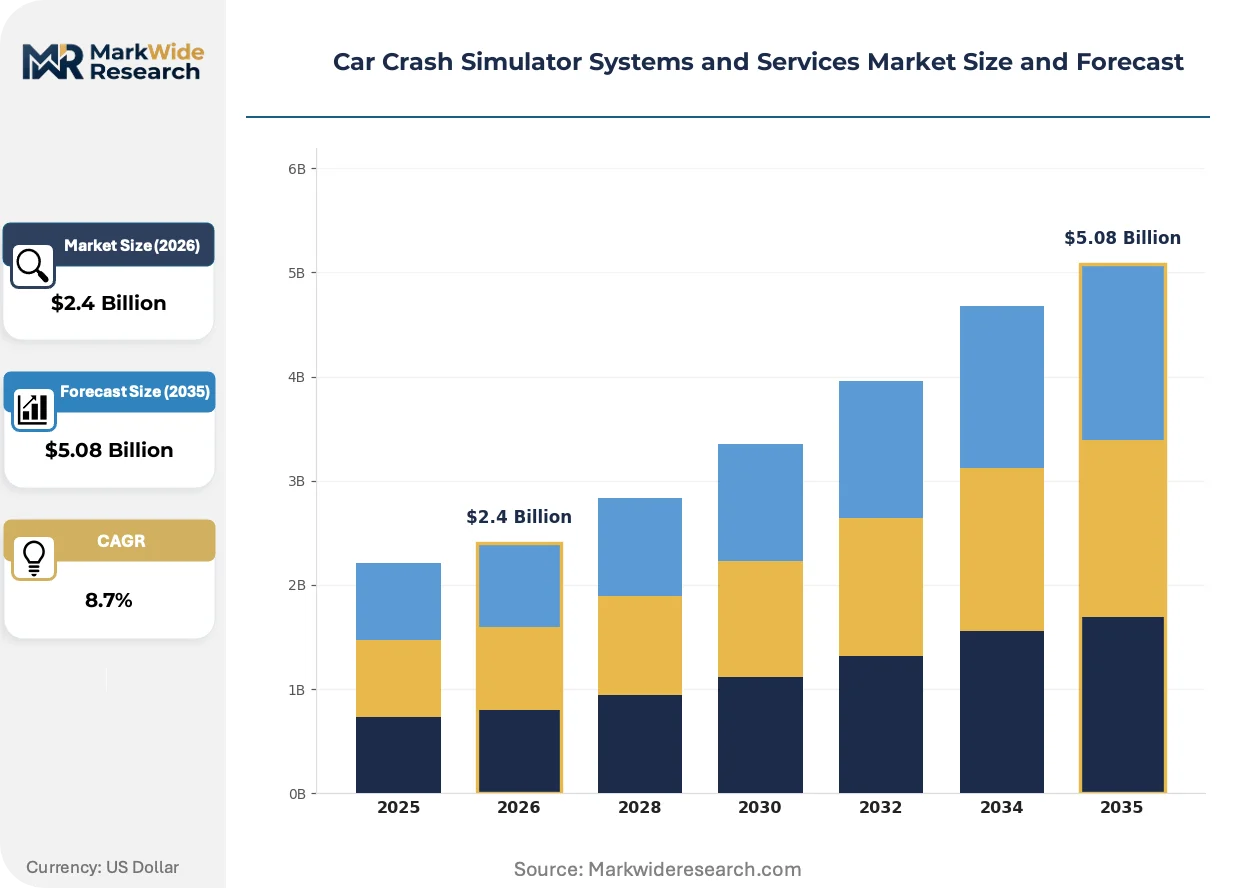
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Simulation Tools End User: Automakers, Research Institutions, Government Agencies, Training Facilities Technology: Virtual Reality, Augmented Reality, 3D Modeling, Physics-Based Simulation Application: Safety Testing, Design Validation, Driver Training, Research Development |
| Companies Covered | Dassault Systèmes, Altair Engineering, Ansys, ESI Group, Siemens AG, MSC Software Corporation, LSTC, AVL, Instron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Crash Simulator Systems and Services Market Trends and Innovations
Artificial intelligence is compressing simulation preprocessing timelines while regulatory authorities formalize acceptance criteria for machine-learning-augmented crash predictions. These developments are reconfiguring competitive advantage toward vendors with combined solver-AI credentials.
Physics-informed neural networks are integrating with traditional finite element solvers to accelerate mesh generation and material parameter calibration for complex impact scenarios. Tier-one suppliers in Germany and Japan are deploying these hybrid approaches for early-stage design iteration, reducing prototype iteration counts by half. The structural consequence is a compression of competitive differentiation toward preprocessing speed rather than raw solver throughput.
NHTSA's updated Federal Motor Vehicle Safety Standards documentation requirements now explicitly reference simulation correlation protocols for autonomous vehicle crashworthiness assessments. This regulatory clarity compels OEMs to maintain validated virtual testing capabilities alongside physical infrastructure. The software segment serving US-market homologation is responding with expanded technical support staffing and regulatory liaison services.
Automotive safety engineering procurement is consolidating around platform vendors offering integrated design, simulation, and regulatory submission workflows. Tier-two suppliers and specialist consultancies face displacement as OEM technical centers reduce vendor counts to streamline accountability. This concentration is most visible in French and German automotive clusters where Dassault Systèmes and Siemens AG anchor consolidated supply relationships.
Car Crash Simulator Systems and Services Market Segmentation
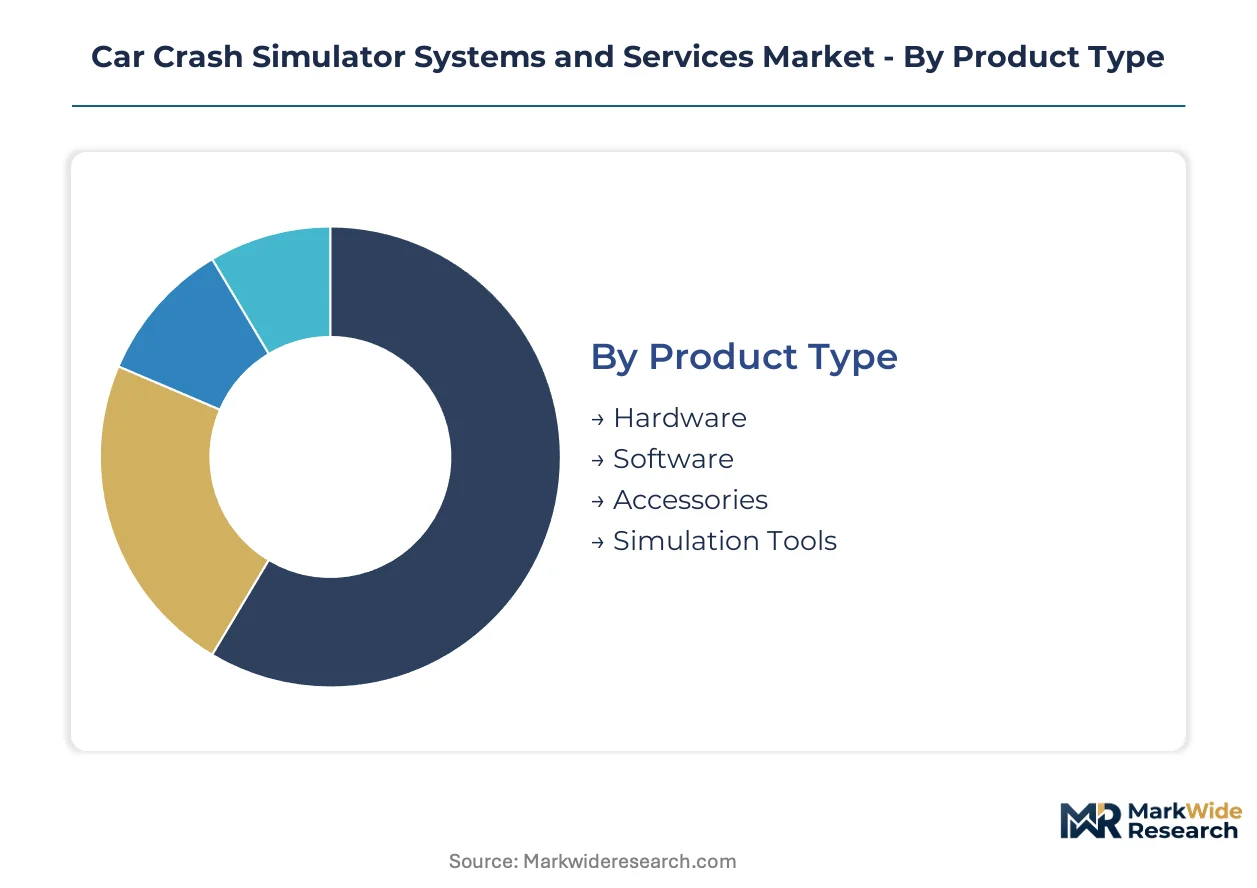
Car crash simulator procurement follows distinct decision hierarchies across product categories, end-user sophistication levels, and technology maturity tiers. Each segmentation dimension carries specific weight in budget allocation, vendor selection, and integration complexity for safety engineering workflows.
Product Type:
Capital intensity and regulatory validation requirements drive buyer segmentation across hardware, software, and supporting infrastructure tiers.
- Hardware:Physical sled rigs, impact barriers, and high-speed data acquisition systems operate at sampling rates exceeding 10 kHz to capture deformation kinematics. German and Japanese OEM validation centers prioritize hardware procurement for final regulatory submission correlation under NHTSA and Euro NCAP protocols. Hardware leads on scale.
- Software:Finite element analysis solvers and multi-physics simulation platforms command premium licensing fees due to specialist workforce requirements and regulatory-grade validation credentials. Automakers in France and Germany consolidate procurement around integrated design-to-simulation workflows. Software leads on momentum.
- Accessories:Sensor arrays, dummy instrumentation, and restraint system actuators complete testing configurations.
- Simulation Tools:Preprocessing mesh generators and post-processing visualization suites complement core solver investments.
Software licensing absorbs the largest share of R&D budgets as virtual certification pathways compress physical testing cycles.
End User:
Technical sophistication and regulatory accountability shape distinct procurement patterns across buyer categories.
- Automakers:Internal validation centers require end-to-end platforms spanning early design iteration through homologation submission. North American and European OEMs maintain proprietary solver ecosystems while licensing specialized modules for multi-material impact scenarios. Automakers lead on scale.
- Research Institutions:University engineering departments and national laboratories prioritize open-architecture solvers for method development and graduate training programs. Research Institutions lead on momentum.
- Government Agencies:Transport ministry testing facilities and regulatory bodies procure validated platforms for standard-setting and compliance verification.
- Training Facilities:Driver education centers and emergency response academies adopt simplified visualization systems for behavioral instruction rather than engineering validation.
Automakers concentrate procurement volume; research institutions expand most quickly as government research funding redirects toward virtual testing infrastructure.
Technology:
Immersion depth and computational fidelity define competitive positioning across visualization and simulation modalities.
- Physics-Based Simulation:Traditional finite element and multi-body dynamics solvers remain mandatory for regulatory submission due to documented correlation protocols with physical test results. Physics-Based Simulation leads on scale.
- Virtual Reality:Head-mounted display environments enable immersive design review and occupant egress studies for autonomous vehicle cabin configurations. Virtual Reality leads on momentum.
- Augmented Reality:Overlay visualization systems support real-time hardware-in-the-loop testing supervision and technician training workflows.
- 3D Modeling:CAD-integrated geometry preparation tools streamline mesh generation for complex vehicle architectures.
Physics-based solvers anchor regulatory compliance; virtual reality applications gain share fastest in early-stage design collaboration.
Application:
Regulatory mandate intensity and development timeline urgency segment demand across use cases.
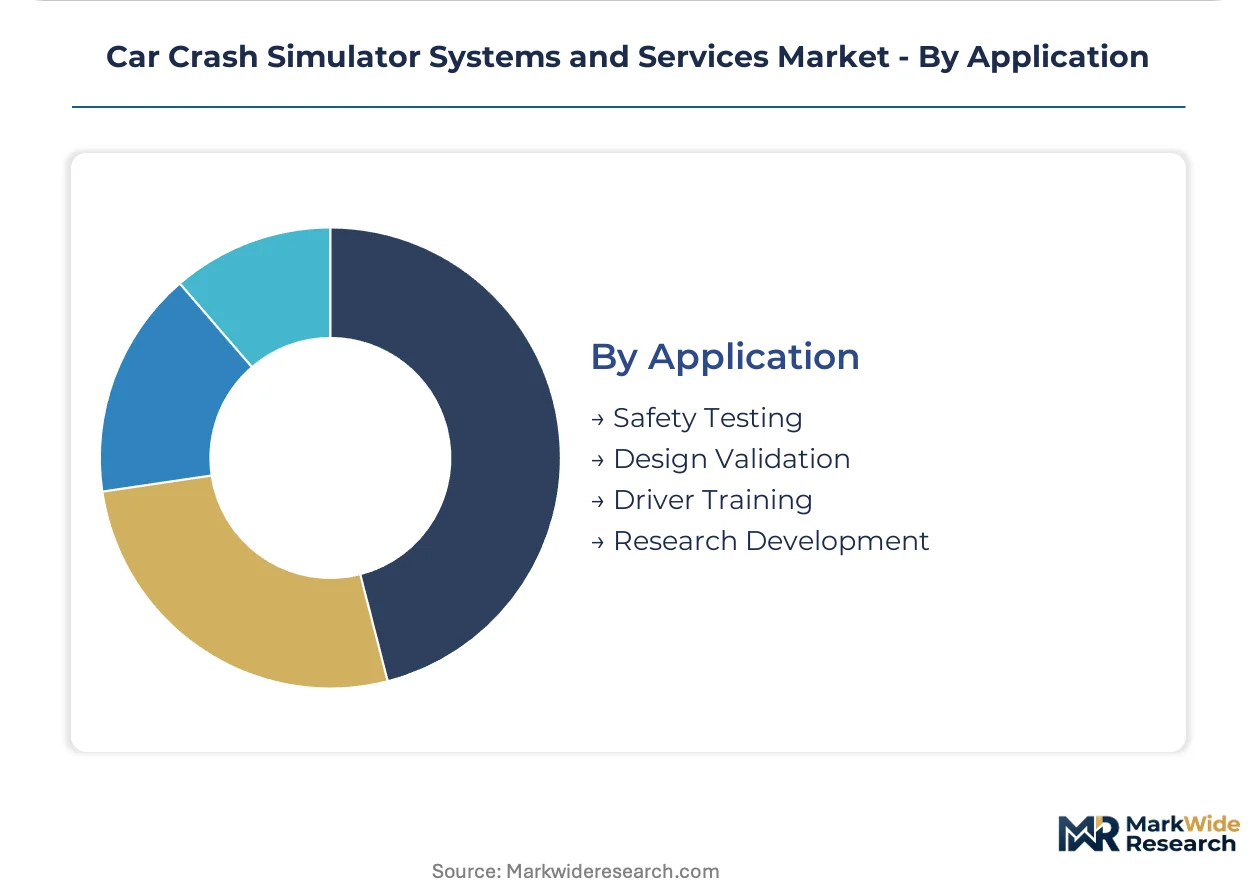
- Safety Testing:Regulatory homologation for NHTSA Federal Motor Vehicle Safety Standards and Euro NCAP ratings requires repeatable, documented simulation protocols. Safety Testing leads on scale.
- Research Development:Novel restraint system concepts and autonomous vehicle crashworthiness investigations demand exploratory solver capabilities with reduced validation overhead. Research Development leads on momentum.
- Design Validation:Iterative structural optimization for electric vehicle platforms combines multi-material modeling with manufacturing constraint integration.
- Driver Training:Behavioral simulation systems emphasize scenario variety and physiological response measurement over engineering precision.
Safety testing commands the largest procurement budgets; research development applications expand most quickly as new energy vehicle architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping crash simulation procurement as automakers migrate R&D investment toward jurisdictions offering streamlined virtual certification pathways. Compliance cost differentials between NHTSA documentation requirements and emerging Euro NCAP digitization protocols are accelerating facility relocation decisions.
United States
NHTSA's updated Federal Motor Vehicle Safety Standards explicitly mandate simulation correlation documentation for autonomous vehicle crashworthiness assessments. Detroit-area OEM technical centers are expanding solver licensing budgets to meet these submission requirements. Michigan's automotive engineering corridor now hosts the largest concentration of validated virtual testing platforms outside Germany.
Germany
KBA type-approval digitization and Euro NCAP protocol expansion drive procurement of integrated design-to-simulation workflows. Stuttgart and Munich automotive clusters anchor continental demand for physics-based solvers capable of multi-material electric vehicle modeling. Dassault Systèmes and Siemens AG maintain dominant platform positions across Baden-Württemberg and Bavaria validation centers.
Japan
METI's streamlined new energy vehicle homologation workflows accelerate adoption of finite element analysis platforms among domestic OEMs. Nagoya and Tokyo metropolitan engineering centers prioritize solver speed for carbon fiber-reinforced polymer impact scenarios. Toyota and Honda technical facilities are consolidating vendor relationships around regulatory-grade platform credentials.
China
MIIT's expanding mandatory new energy vehicle crash standards compel foreign suppliers to establish domestic simulation service capabilities. Shanghai and Beijing automotive R&D hubs are localizing high-performance computing infrastructure to support GB standard compliance. Domestic OEMs are redirecting procurement toward joint-venture platforms with established European solver vendors.
South Korea
MFDS automotive safety guidelines and KATRI testing protocols create demand for hardware-in-the-loop validation infrastructure. Seoul Capital Area engineering centers balance proprietary solver development with strategic licensing from established platform vendors. Hyundai-Kia technical facilities are expanding GPU cluster capacity to compress virtual certification timelines.
Car Crash Simulator Systems and Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery models and AI-augmented preprocessing capabilities. The vendor base organizes around three archetypes: integrated design-to-simulation platform providers, specialized finite element solver developers, and hardware-in-the-loop testing equipment fabricators. Consolidation pressure favors vendors with regulatory-grade validation credentials over pure-play software or hardware specialists. Dominant competitive moves include strategic partnerships with OEM validation centers and technology licensing agreements for multi-physics solver modules.
Within the integrated platform tier, Dassault Systèmes and Siemens AG exemplify consolidation winners anchoring supply relationships across European automotive clusters. Ansys occupies a position emphasizing solver speed specialization for complex impact scenarios. These three entities represent distinct strategic postures: end-to-end workflow integration, hardware-software bundling, and computational performance optimization respectively.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Altair Engineering |
| Ansys |
| ESI Group |
| Siemens AG |
| MSC Software Corporation |
| LSTC |
| AVL |
| Instron |
| Others |
Pricing and Supply Chain Analysis
Physics-based solver licensing is compressing cost economics for mid-tier engineering consultancies while concentrating procurement power among German and Japanese OEM validation centers with captive high-performance computing infrastructure. This technology shift simultaneously elevates entry barriers for hardware-in-the-loop testing equipment and privileges established platform vendors with regulatory-grade credentials.
Pricing Analysis
Distributor margins on finite element analysis software typically run thin as Dassault Systèmes, Siemens AG, and Ansys enforce direct-to-OEM licensing frameworks with volume-scaled discount tiers. Pricing stratifies across premium solver modules for multi-material impact scenarios, standard configurations for baseline crashworthiness validation, and economy-tier cloud-native subscriptions for tier-two suppliers. Cost compression in hardware sled rigs is intensifying because automakers are reallocating capital toward software solvers. Research institutions exhibit highest price sensitivity due to constrained public funding, while German automakers demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Certification gating through NHTSA correlation protocols and Euro NCAP validation requirements restricts qualified supplier pools to vendors with documented regulatory submission track records. Component manufacturing concentrates in Germany, Japan, and the United States for high-fidelity sensor arrays and data acquisition systems. Raw material dependencies include specialized GPU clusters for solver acceleration, precision-machined impact barriers, and biomechanical dummy instrumentation. Single-source vulnerability runs through proprietary solver codebase licensing from dominant platform providers. Distribution runs through OEM technical center procurement offices with direct vendor relationships, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car crash simulator market functions as a regulatory compounder where NHTSA's updated Federal Motor Vehicle Safety Standards for autonomous vehicle crashworthiness documentation perpetually refresh demand cycles for validated virtual testing platforms.
For Market Incumbents: Deepen regulatory liaison capabilities to secure preferred vendor status under evolving Euro NCAP digitization protocols and MIIT localization mandates in China. Incumbents should anchor hardware-software bundling contracts with Stuttgart and Munich automotive clusters to defend against cloud-native entrants offering elastic compute subscription models. Vertical integration into GPU cluster provisioning for client validation centers represents a defensible margin lever. For New Entrants and Emerging Players: MIIT's expanding mandatory new energy vehicle crash standards in China opens a window for joint-venture partnerships with domestic OEMs lacking established European solver relationships. New entrants should target tier-two engineering consultancies in South Korea and China with subscription-based preprocessing tools that circumvent upfront licensing capital barriers. A regulatory arbitrage go-to-market angle emphasizing streamlined documentation workflows for METI type-approval digitization accelerates initial traction. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized finite element solver developers with narrow regulatory credentials but proven correlation protocols. Long-term viability hinges on consolidation into integrated platform ecosystems over a 5-10 year horizon as OEM procurement concentrates around end-to-end workflow vendors. Acquisition targets should demonstrate validated NHTSA or Euro NCAP submission track records. The signal to watch is regulatory authority acceptance of machine-learning-augmented crash predictions, which would revalue hybrid AI-solver capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | NHTSA and Euro NCAP validation credentials anchor OEM procurement decisions and exclude unqualified competitors. |
| Cloud-Native Solver Delivery | Subscription access to elastic compute resources lowers barriers for tier-two suppliers and aftermarket safety researchers. |
| AI-Augmented Preprocessing Development | Physics-informed neural networks compress mesh generation timelines and differentiate vendor capabilities in early-stage design iteration. |
| China Localization Partnership | MIIT mandates for domestic simulation service capabilities create joint-venture entry points for foreign platform vendors. |
| Hardware-in-the-Loop Integration | Siemens AG's bundled testing infrastructure secures anchor positions across German OEM validation centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, regulatory affairs specialists at NHTSA and KBA, and simulation software R&D directors with secondary validation against SEC filings, Euro NCAP protocol documentation, MIIT regulatory notices, and automotive production databases from IHS Markit. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verified market estimates across hardware, software, and services tiers.
Segment-weighting approaches distributed value estimates across product type, end user sophistication, technology modality, and application intensity, with additional stratification by regional regulatory cluster and OEM tier. CAGRs were derived from regression analysis of historical procurement patterns and projected R&D budget reallocation toward virtual certification pathways across the analysis window. Industry-specific forecast inputs included electric vehicle platform proliferation rates and documented correlation protocol acceptance timelines for machine-learning-augmented solvers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated regulatory digitization or prolonged physical testing mandates. Forecasts reflect assumptions regarding OEM consolidation of vendor relationships and cloud-native adoption curves among mid-tier engineering consultancies. A model refresh is warranted upon material change in NHTSA or Euro NCAP simulation correlation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Motor Testing Equipment Market