
 Commercial Vehicle and Off-Highway RADAR Market | 2026-2036
Commercial Vehicle and Off-Highway RADAR Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle and Off-Highway RADAR Market Analysis
Silicon germanium is decoupling from traditional gallium arsenide in RF front-end fabrication, lowering unit costs for 77 GHz transceiver modules. Robert Bosch GmbH leverages captive semiconductor foundry partnerships to secure wafer supply for its commercial vehicle RADAR portfolio. Continental AG anchors European production of long-range detection systems for heavy-duty trucking. NXP Semiconductors N.V. competes on integrated system-on-chip architectures that consolidate digital signal processing with analog RF functions.
Commercial Vehicle and Off-Highway RADAR denotes electromagnetic sensing equipment operating between 24 GHz and 77 GHz, transmitting frequency-modulated continuous wave signals and processing reflected echoes to determine object range, velocity, and azimuth in environments with dust, vibration, and temperature extremes spanning minus forty to eighty-five degrees Celsius. Its primary purpose is to automate hazard detection where optical sensors degrade from particulate contamination or lighting variability. FMCW RADAR occupies the dominant share of product type revenue due to superior range resolution and simultaneous multi-target tracking capability. Long-range technology segments command premium positioning in highway trucking applications, while short-range units penetrate construction equipment for blind-spot monitoring where maneuvering precision outweighs detection distance.
The European Union General Safety Regulation mandates intelligent speed assistance and advanced emergency braking for new commercial vehicles, directly expanding addressable RADAR volume. EPA emissions compliance timelines in the United States indirectly accelerate sensor adoption as powertrain electrification demands tighter vehicle packaging and automated energy management. NHTSA pending rulemakings on heavy-truck automatic emergency braking will determine whether North American specification convergence with European mandates occurs. Stakeholders must monitor whether Chinese MIIT domestic certification requirements evolve to favor local suppliers over incumbent European and Japanese module producers.
Market Dynamics
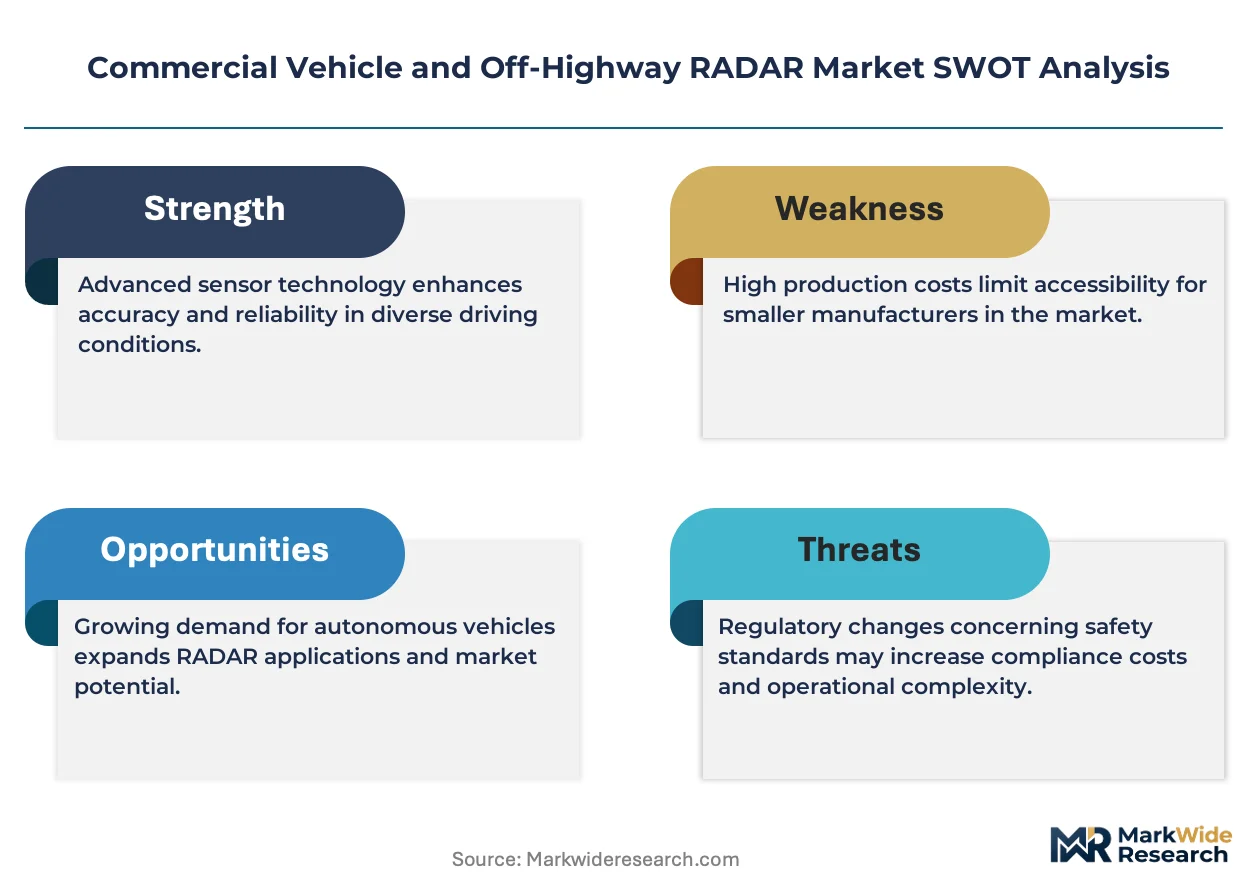
Fleet electrification is compressing engine bay volume and forcing RADAR module miniaturization while simultaneously raising thermal management demands in commercial vehicle architectures.
Growth Catalysts
- EU General Safety Regulation:Mandates intelligent speed assistance and advanced emergency braking for new commercial vehicles sold across member states, directly expanding OEM-installed RADAR volume.
- Silicon germanium process migration:Semiconductor fabrication shifts from gallium arsenide to SiGe substrates, cutting transceiver module costs and enabling 77 GHz deployment in price-sensitive construction equipment.
- Australian mining automation:Collision avoidance system procurement accelerates in Western Australian iron ore operations where dust and vibration degrade optical sensor reliability.
Market Restraints
- Wafer supply concentration:RF semiconductor foundry capacity clusters in Taiwan and South Korea, exposing module producers to single-source geographic risk.
- Electromagnetic spectrum fragmentation:Divergent 24 GHz versus 77 GHz regional approvals force dual-SKU inventory and complicate global platform standardization.
- Lidar cost compression:Solid-state optical ranging units approach price parity in short-range applications, threatening RADAR's blind-spot monitoring dominance.
Strategic Opportunities
- Indian construction equipment retrofit:Telematics mandates under the country's automotive regulatory framework create aftermarket RADAR attachment demand in earthmoving fleets.
- 4D imaging convergence:Integration of elevation data with traditional range-velocity-azimuth outputs enables automated grading and excavation precision.
- Brazil agribusiness automation:Harvester collision avoidance system penetration remains below ten percent in soybean and sugarcane operations, offering first-mover positioning.
Industry Challenges
- RF systems engineering scarcity:Commercial vehicle OEMs compete with consumer electronics and defense contractors for millimeter-wave antenna design talent.
- Multi-sensor fusion complexity:Integrating RADAR returns with camera and ultrasonic inputs demands new vehicle network architectures and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle and Off-Highway RADAR Market |
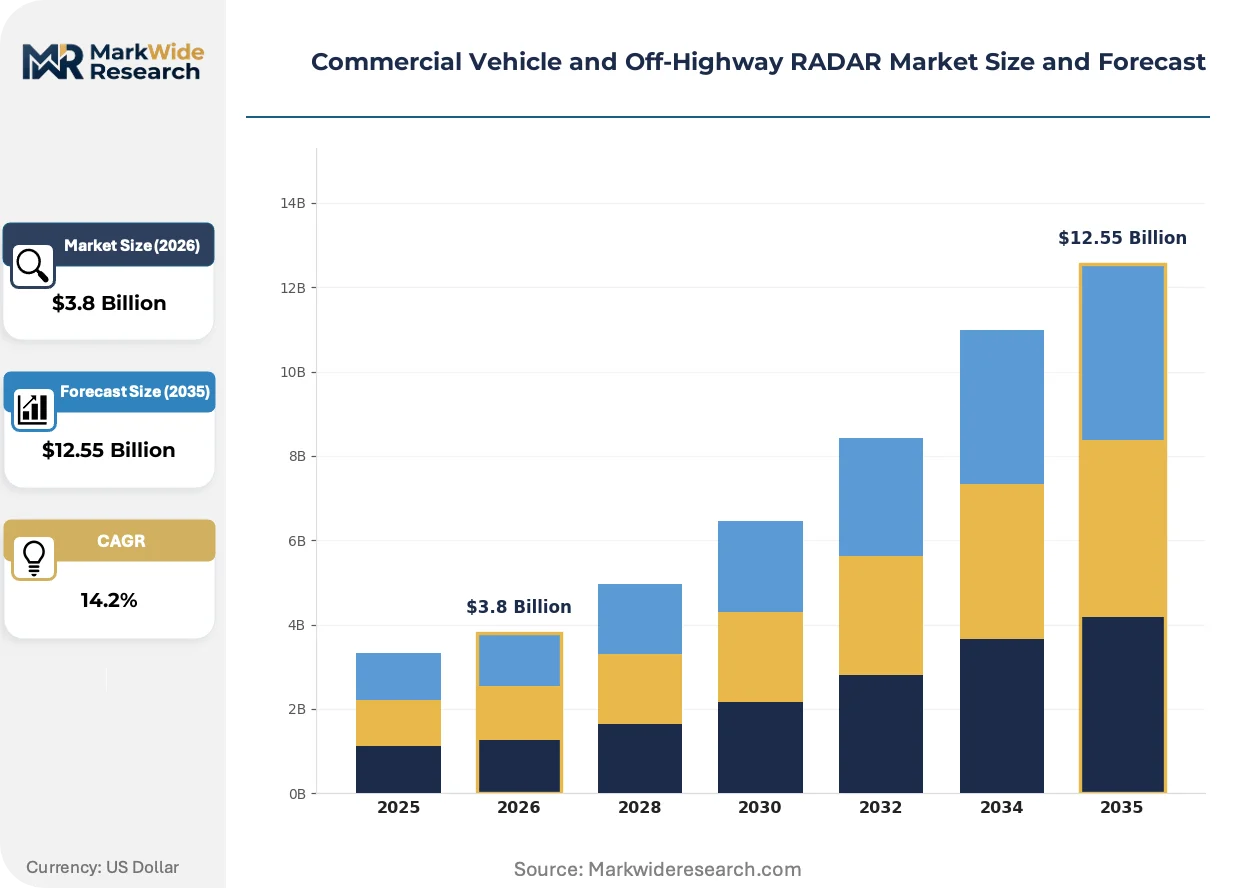
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FMCW RADAR, Pulse RADAR, Doppler RADAR, Imaging RADAR End User: Construction, Agriculture, Transportation, Mining Technology: Short Range, Medium Range, Long Range, Ultra Long Range Application: Obstacle Detection, Collision Avoidance, Traffic Monitoring, Fleet Management |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aptiv Plc, Denso Corporation, Infineon Technologies AG, NXP Semiconductors N.V, ZF Friedrichshafen AG, Valeo S.A, Magna International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle and Off-Highway RADAR Market Emerging Trajectories
Semiconductor packaging and signal processing architectures are converging to shrink module footprints while expanding detection fidelity in harsh-environment applications.
System-on-chip RADAR processors are modularizing front-end and digital back-end functions onto single die configurations. Heavy-duty truck OEMs in Germany and Japan are qualifying these consolidated architectures for highway-speed adaptive cruise control. This consolidation is modularizing tiered supplier relationships and compressing bill-of-material layers.
The EPA's pending heavy-duty automatic emergency braking rulemaking is forcing North American specification alignment with European mandates. Truck manufacturers face dual-homologation costs if divergence persists. Long-haul fleet procurement departments are accelerating pre-compliance orders to lock in current sensor configurations before mandate effective dates.
Aftermarket retrofit channels are capturing an expanding share of construction equipment safety system deployment. Independent distributors in Texas and Alberta are building installation networks that bypass OEM dealer capture. Mining contractors in Queensland and Chile are sourcing blind-spot modules directly through these channels to avoid fleet downtime.
Commercial Vehicle and Off-Highway RADAR Market Segmentation
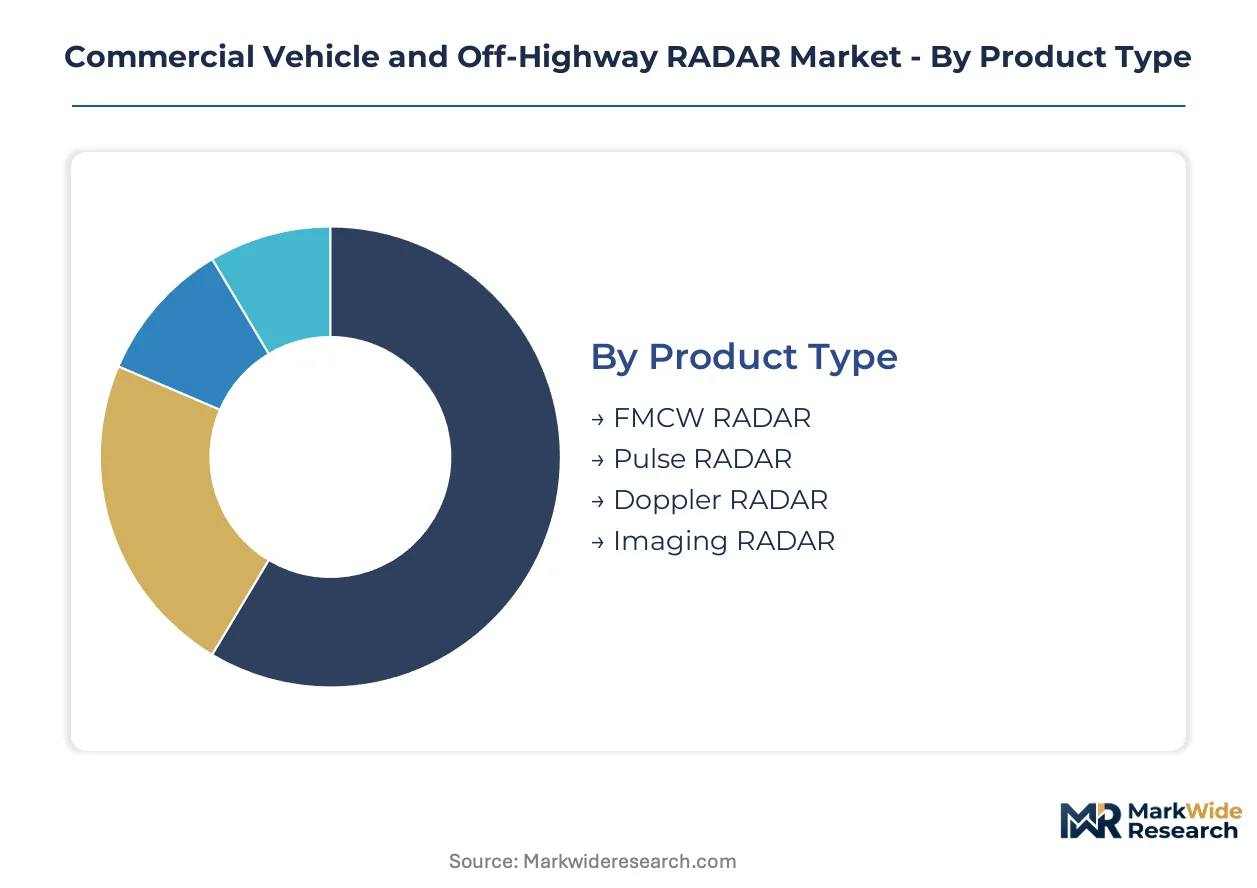
Segmentation in commercial vehicle and off-highway RADAR reveals how electromagnetic sensing architectures diverge across duty cycles, environmental exposure, and automation intensity. Understanding these partitions exposes where module suppliers can standardize platforms versus where customization commands premium positioning.
Product Type:
Customization versus standardization tension runs deepest here, as frequency-modulated continuous wave architectures scale across price tiers while imaging arrays remain bespoke to precision agriculture and autonomous mining.
- FMCW RADAR:Frequency-modulated continuous wave modulation enables simultaneous range and velocity measurement through chirp signal processing. Western Australian iron ore fleets specify these units for collision avoidance where dust penetration exceeds optical sensor limits. Leading the category by volume: FMCW RADAR. Growing fastest: Imaging RADAR.
- Imaging RADAR:Multiple-input multiple-output antenna arrays generate elevation maps for automated grading and excavation depth control. German OEMs qualify these for highway-speed adaptive cruise in heavy-duty trucking where lane-keeping precision demands vertical resolution.
- Pulse RADAR:Time-of-flight measurement suits short-range obstacle detection in warehouse yard tractors.
- Doppler RADAR:Velocity-only detection finds residual application in conveyor belt speed monitoring at bulk material handling sites.
Standard FMCW platforms absorb volume; imaging variants capture margin in precision automation.
End User:
Cost tier stratification separates retrofit-sensitive construction fleets from mandate-driven highway transportation.
- Transportation:Long-haul trucking and urban freight carriers face EU General Safety Regulation mandates for intelligent speed assistance and automatic emergency braking. German and Swedish OEMs integrate 77 GHz long-range modules as standard equipment on highway tractors.
- Mining:Surface and underground operations in Chile, Australia, and Canada deploy collision avoidance systems where vibration and particulate contamination degrade lidar reliability. Procurement concentrates through direct contractor relationships bypassing traditional dealer networks.
- Construction:Earthmoving and material handling equipment retrofit channels in Texas and Alberta capture blind-spot monitoring demand from independent fleet operators.
- Agriculture:Harvester automation in Brazilian soybean and sugarcane operations remains underpenetrated, offering first-mover positioning for obstacle detection during night harvesting.
Dominant procurement volume flows through transportation OEM integration; mining contractors drive aftermarket premium pricing.
Technology:
Detection range specifications map directly to vehicle kinetic energy and stopping distance requirements across operating environments.
- Long Range:200-plus meter detection supports highway-speed adaptive cruise control and forward collision warning in heavy-duty trucks. Module miniaturization pressures intensify as electrification compresses engine bay packaging.
- Short Range:Blind-spot monitoring and rear cross-traffic alert dominate construction equipment where maneuvering precision outweighs detection distance. Brazilian and Indian earthmoving fleets drive retrofit attachment demand.
- Medium Range:50-150 meter coverage addresses urban freight distribution and regional delivery routes.
- Ultra Long Range:300-plus meter specification serves autonomous haulage in open-pit mining with extended reaction windows.
Long-range modules anchor OEM specification sheets; short-range variants proliferate through independent distributor channels.
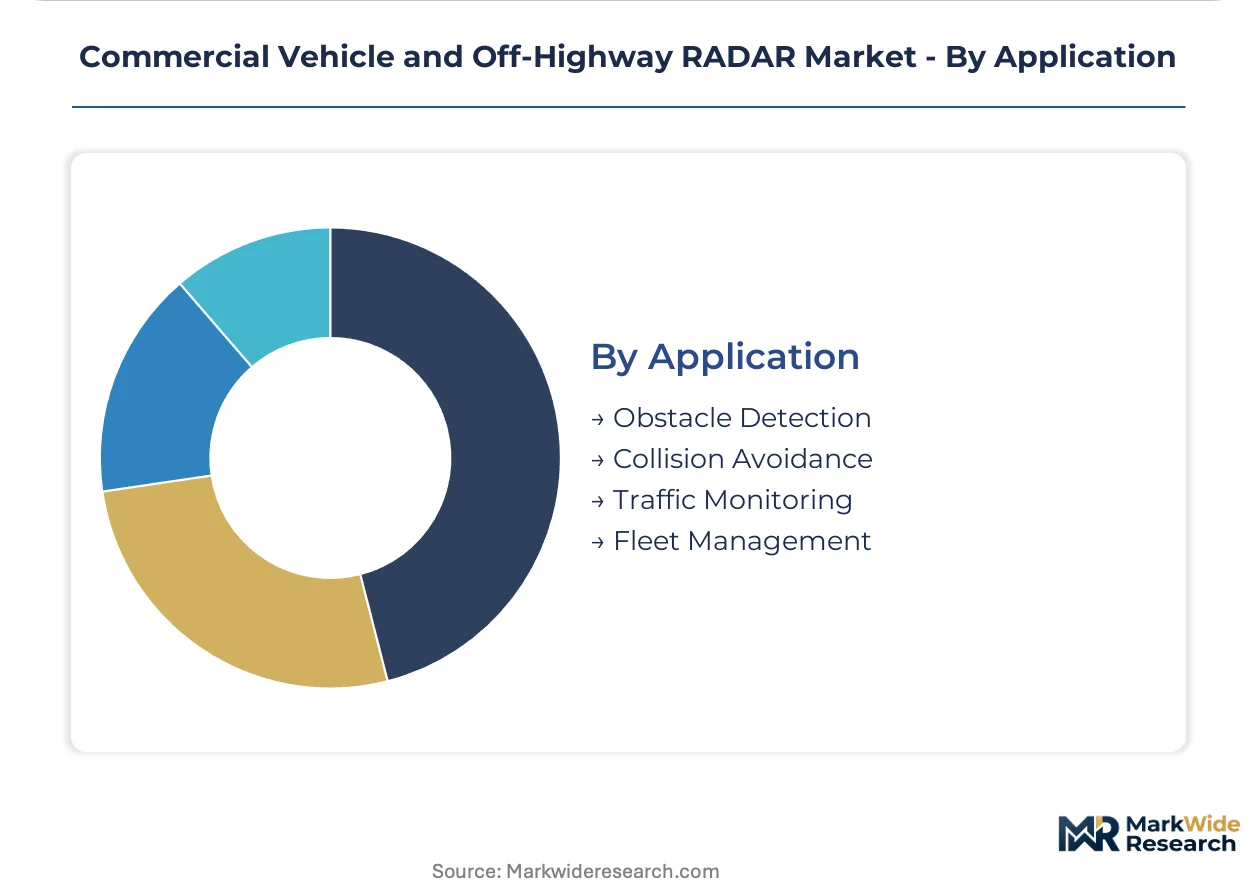
Application:
Functional use case maturity separates regulatory-mandated safety systems from operational efficiency tools still proving return on investment.
- Collision Avoidance:Automatic emergency braking and forward collision warning systems face expanding regulatory mandates across EU member states and pending NHTSA rulemaking in the United States. Fleet procurement departments accelerate pre-compliance orders to lock sensor configurations before effective dates.
- Fleet Management:Integration of RADAR returns with telematics platforms enables predictive maintenance and fuel optimization. Indian construction equipment mandates under the country's automotive regulatory framework create aftermarket attachment demand.
- Obstacle Detection:Static and dynamic object identification supports autonomous navigation in controlled environments.
- Traffic Monitoring:Vehicle-to-infrastructure deployment remains experimental in smart highway pilot programs.
Collision avoidance commands installed base; fleet management integration represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, China, and Australia concentrate RADAR module assembly through tax-advantaged manufacturing parks. These zones attract tier-one suppliers seeking proximity to OEM electrification programs and mining automation hubs.
Germany
EU General Safety Regulation mandates accelerate OEM integration of 77 GHz long-range systems for highway trucking. KBA homologation requirements enforce stringent electromagnetic compatibility standards for commercial vehicle platforms. Stuttgart and Ingolstadt anchor captive semiconductor partnerships between Robert Bosch GmbH and foundry operators serving the European truck market.
United States
NHTSA pending automatic emergency braking rulemaking drives pre-compliance procurement from long-haul fleet operators. EPA heavy-duty emissions timelines compress engine bay packaging and intensify thermal management demands for RADAR modules. Michigan and Texas host independent distributor networks capturing aftermarket construction equipment retrofit demand.
Australia
Western Australian iron ore operations deploy collision avoidance systems where dust penetration degrades optical sensor reliability. TGA-equivalent mining safety regulations mandate proximity detection in surface and underground contractor fleets. Perth functions as procurement coordination hub for autonomous haulage programs across Pilbara operations.
China
MIIT domestic certification requirements evolve toward favoring local module suppliers over incumbent European and Japanese producers. Dual carbon goals accelerate electrification in commercial vehicle segments and compress sensor packaging constraints. Yangtze River Delta clusters concentrate RF semiconductor foundry capacity for 24 GHz and 77 GHz transceiver production.
Brazil
ANVISA-aligned agricultural safety protocols create first-mover positioning for harvester collision avoidance in soybean and sugarcane operations. Underpenetration below ten percent in mechanized farming fleets attracts aftermarket attachment demand. São Paulo state anchors distribution networks serving agribusiness automation in Mato Grosso and Goiás production belts.
Commercial Vehicle and Off-Highway RADAR Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one automotive suppliers capturing OEM-integrated highway trucking volumes while independent fabricators serve mining and construction retrofit channels. The vendor base organizes around three strategic archetypes: captive semiconductor foundry operators, modular system-on-chip consolidators, and aftermarket distribution specialists. Consolidation pressures intensify as electrification compresses bill-of-material layers and forces tiered supplier rationalization. Dominant competitive moves include backward integration into wafer supply and geographic expansion through Australian and Brazilian mining contractor relationships.
Among German-based diversified automotive suppliers, Robert Bosch GmbH and Continental AG exemplify the captive-foundry archetype through semiconductor partnerships securing 77 GHz wafer allocation. ZF Friedrichshafen AG occupies a position within the long-range detection tier, anchoring European production capacity for heavy-duty truck sensing platforms. These three entities represent distinct strategic postures: Bosch leverages vertical semiconductor control, Continental emphasizes highway-speed adaptive cruise qualification, and ZF concentrates R&D investment in commercial vehicle-specific environmental hardening.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aptiv Plc |
| Denso Corporation |
| Infineon Technologies AG |
| NXP Semiconductors N.V |
| ZF Friedrichshafen AG |
| Valeo S.A |
| Magna International Inc |
| Others |
Supply Flow & Price Mechanics
Highway trucking OEMs in Germany and Sweden concentrate procurement volume for 77 GHz long-range modules, locking in contract-based long-term offtake pricing with tier-one suppliers. This buyer concentration favors volume-scale negotiations over spot-market flexibility, compressing margins for module producers serving fragmented construction equipment retrofit channels.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to Australian mining contractors requiring immediate collision avoidance system deployment to meet TGA-equivalent safety mandates. Pricing stratifies across automotive-grade certification tiers, with KBA-homologated modules commanding substantial premiums over industrial-grade alternatives. Cost compression in 24 GHz short-range units is intensifying because silicon germanium process migration enables foundry scale economies. Brazilian agribusiness fleets exhibit highest price sensitivity, while EU-mandated highway trucking segments absorb premium positioning with limited negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for RF semiconductor foundry capacity, exposing module producers to geographic concentration risk. Wafer supply draws from captive partnerships between Robert Bosch GmbH and European foundry operators, while NXP Semiconductors N.V. sources from diversified Asian facilities. Gallium arsenide substrate availability and 77 GHz transceiver die yield rates constitute critical input dependencies. Tariff exposure on Chinese-manufactured 24 GHz modules threatens cost structures for price-sensitive construction segments. Distribution runs through OEM-integrated channels for highway trucking and independent distributor networks for mining and construction retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Captive semiconductor foundry partnerships represent the decisive upstream lever separating tier-one suppliers from module assemblers exposed to wafer allocation volatility.
For Market Incumbents: Anchor long-range highway trucking specifications through KBA homologation investment before NHTSA rulemaking crystallizes North American requirements. Secure gallium arsenide wafer supply through backward integration or long-term offtake agreements to defend against silicon germanium process disruption. Consolidate tier-two supplier relationships as electrification compresses bill-of-material layers and forces rationalization. For New Entrants and Emerging Players: Launch via independent distributor channels in Texas and Alberta serving construction equipment retrofit demand outside OEM dealer capture. Target Brazilian harvester collision avoidance where ANVISA-aligned safety protocols create first-mover positioning below ten percent penetration. Prioritize 4D imaging RADAR integration for automated grading applications in Australian iron ore operations. For Investors and Strategic Acquirers: The window for entry favors system-on-chip consolidators with modular front-end and digital back-end integration capabilities. Mid-term viability rests on qualification timelines for highway-speed adaptive cruise control in German and Japanese OEM platforms. Watch NHTSA automatic emergency braking rulemaking as the signal for North American specification convergence with EU mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Foundry Partnership | Secures wafer allocation for 77 GHz transceiver production against Taiwan concentration risk. |
| 4D Imaging RADAR Development | Enables elevation mapping for automated grading in Western Australian mining operations. |
| Aftermarket Distribution Network Buildout | Captures construction equipment retrofit demand outside OEM dealer channels in Alberta. |
| KBA Homologation Investment | Locks highway trucking specifications before EPA emissions timelines compress packaging. |
| SiGe Process Migration | Reduces unit costs for 77 GHz modules in price-sensitive Brazilian agribusiness segments. |
Methodological Framework
Multi-period observation of OEM platform engineering timelines, mining contractor procurement patterns, and semiconductor foundry capacity utilization anchored the trend analysis, supplemented by interviews with tier-one supplier procurement directors, RF systems engineering leads at commercial vehicle OEMs, aftermarket distribution operators in Texas and Alberta, and mining safety compliance officers in Western Australia. Secondary validation drew from EPA heavy-duty emissions filings, NHTSA rulemaking dockets, EU General Safety Regulation implementation guidance, MIIT certification databases, and vehicle production registration data. Bottom-up module shipment estimates triangulated against top-down OEM platform content assumptions.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework across the projection horizon. Detection range specifications, environmental hardening requirements, and regional regulatory mandate timelines served as industry-specific forecast inputs. CAGRs were derived from installed base penetration curves and replacement cycle assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state lidar cost compression would alter the outlook for short-range RADAR blind-spot monitoring dominance. Forecasts reflect assumptions about EU mandate enforcement timing, NHTSA rulemaking finalization, and Chinese domestic certification evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market