
 Automotive License Plate Light Market | 2026-2036
Automotive License Plate Light Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive License Plate Light Market Outlook
Chinese LED component manufacturers is pivoting toward module-level supply for rear-vehicle lighting assemblies. HELLA GmbH & Co. KGaA leverages its European production footprint to sustain OEM relationships with premium German automakers. Koito Manufacturing Co., Ltd. anchors Asian supply chains through integrated lamp manufacturing. OSRAM GmbH competes on phosphor-converted LED architectures that differentiate thermal performance in compact housings.
An automotive license plate light is a sealed illumination device, typically rated at 5W to 15W and producing 50 to 150 lumens, designed to render registration characters visible at 15 meters under darkness. Manufacturers mold polycarbonate or PMMA lenses over SMD LED arrays or filament bulbs, then pot the assembly to meet IP67 ingress standards against road spray and pressure washing. LED product type now dominates value contribution as thermal management advances shrink module depth below 20mm, enabling integration into slim bumper profiles. OEM installation type captures the majority of volume, though aftermarket channels gain traction where vehicle parc age exceeds seven years and owners replace failed units independently.
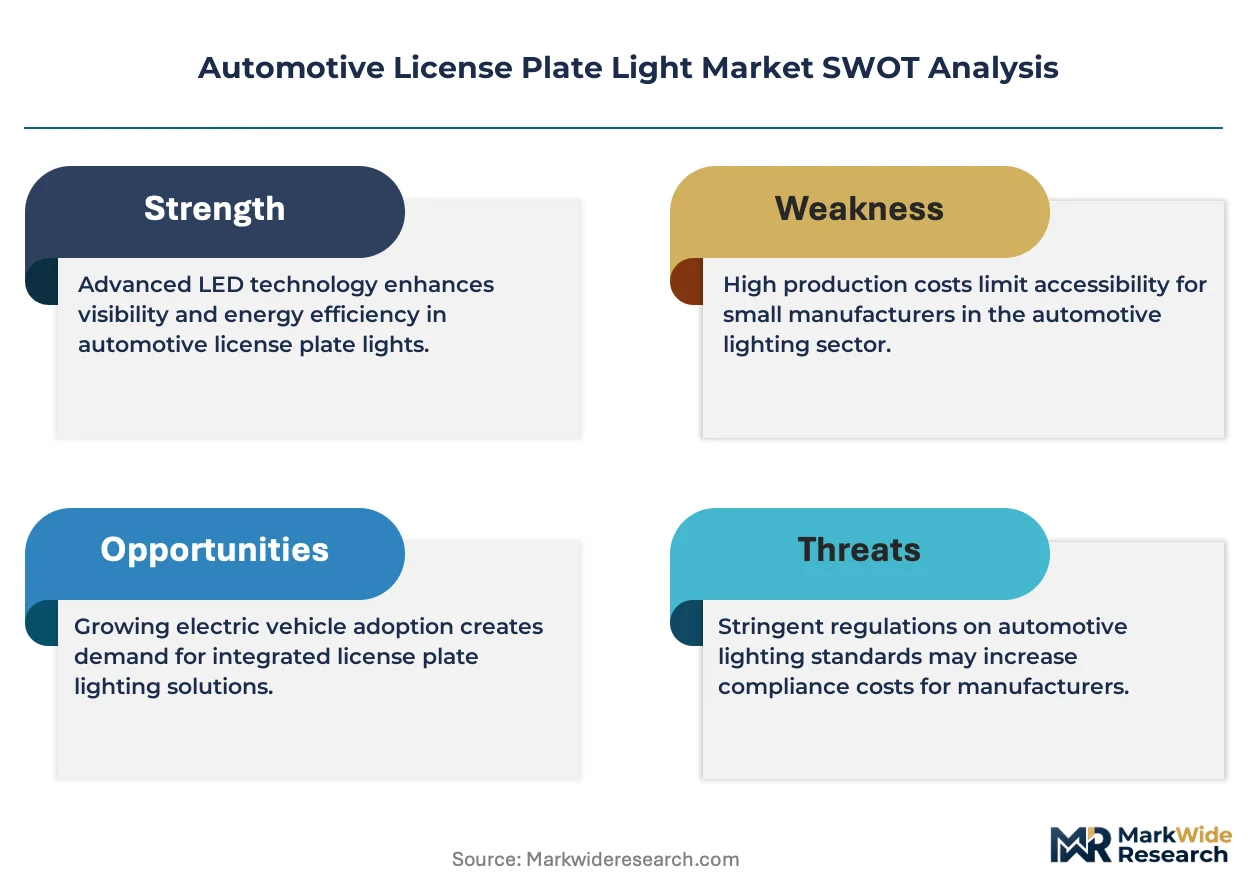
NHTSA Federal Motor Vehicle Safety Standard 108 mandates minimum illuminance and color rendering for US license plate visibility, while ECE Regulation 48 governs European homologation of rear-position lamps including plate illumination. China's GB standards and MIIT certification requirements enforce similar photometric thresholds for domestic-market vehicles. Stakeholders must monitor divergence between regional color-temperature specifications and the shift toward software-defined lighting architectures that could eliminate dedicated hardware entirely.
Market Dynamics
LED thermal management advances are compressing module depth below 20mm, enabling integration into slim bumper profiles and forcing suppliers to consolidate rear-light assemblies or exit dedicated plate illumination entirely.
Growth Catalysts
- State-level inspection tightening:Commercial fleet operators in the United States face expanded retrofit mandates as visibility enforcement intensifies.
- Module consolidation:European OEMs embed license plate illumination within rear-light modules, reducing part count and assembly complexity.
- GB standards enforcement:China's MIIT certification requirements for domestic-market vehicles sustain replacement demand for non-compliant legacy units.
Market Restraints
- Phosphor cost volatility:Rare-earth phosphor prices fluctuate with Chinese export quotas, squeezing margin on high-CRI LED architectures.
- Supplier concentration risk:Polycarbonate lens molding capacity clusters in German and Chinese tier-2 suppliers, creating single-source vulnerability.
- Software-defined substitution:Programmable rear-light arrays threaten to eliminate dedicated plate hardware entirely in premium vehicle segments.
Strategic Opportunities
- Aftermarket channel expansion:Vehicle parc age exceeding seven years in the United States drives independent owner replacement of failed sealed units.
- Dual-carbon alignment:China's national carbon goals incentivize LED retrofits in commercial fleets, opening module-level supply contracts.
- Rear-module integration:Convergence of camera, radar, and lighting functions creates white space for suppliers with mechatronics capability.
Industry Challenges
- Homologation timeline compression:ECE Regulation 48 certification cycles lag behind OEM platform development schedules, forcing parallel validation tracks.
- Thermal engineering scarcity:Compact housing design for sub-20mm depths requires specialized CFD simulation talent concentrated in German and Japanese engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive License Plate Light Market |
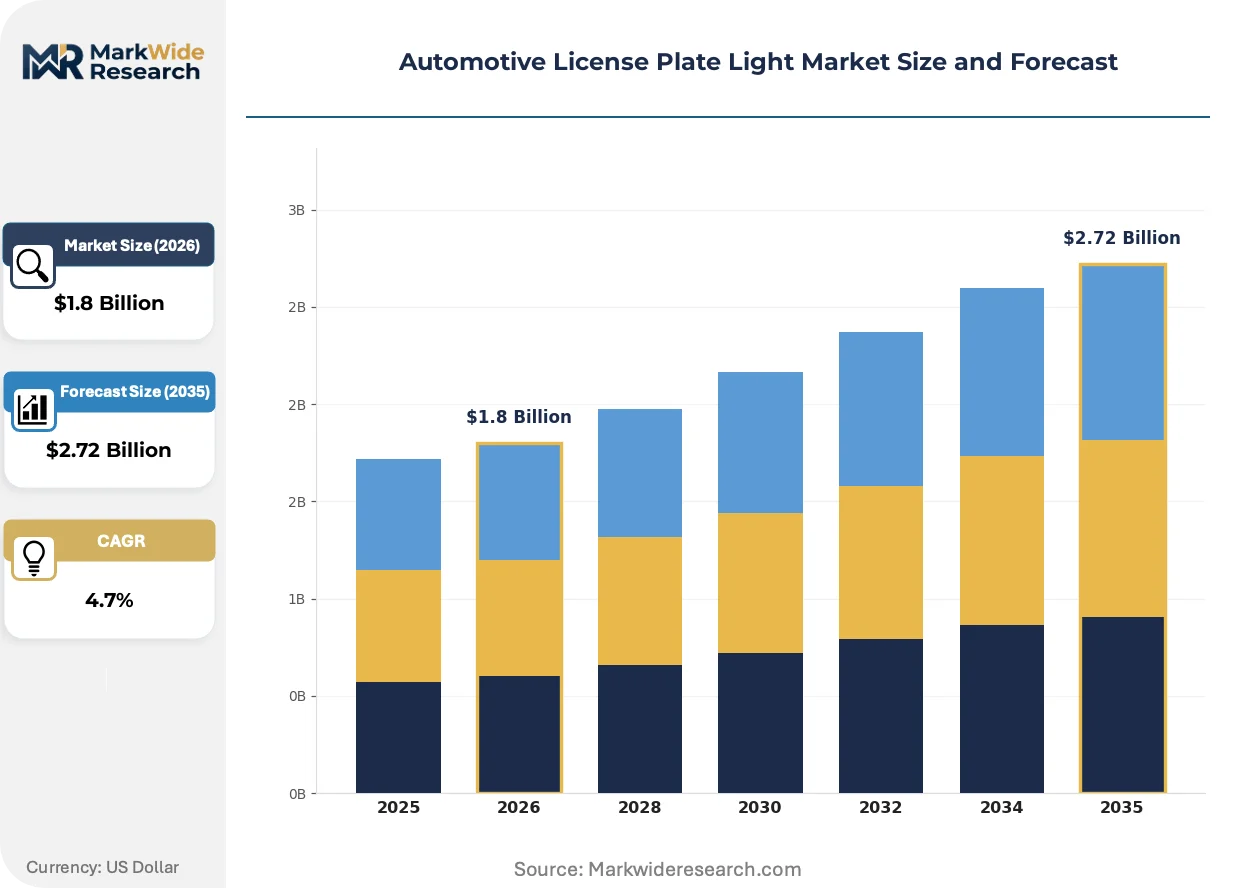
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Incandescent Installation Type: OEM, Aftermarket, Plug-and-Play, Custom Fit Vehicle Type: Passenger Cars, SUVs, Trucks, Motorcycles Power Source: 12V DC, 24V DC, Battery-Powered, Solar |
| Companies Covered | HELLA GmbH & Co. KGaA, Koito Manufacturing Co., Ltd., OSRAM GmbH, Stanley Electric Co., Ltd., Valeo S.A., Magneti Marelli S.p.A., Philips (Signify N.V.), ZKW Group, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive License Plate Light Market Strategic Shifts
Active reshaping in this market centers on physical integration of discrete functions, regulatory pressure on visibility verification, and channel fragmentation between captive OEM supply and independent aftermarket access.
Surface-mount device LED arrays with ceramic substrate thermal cores are modularizing plate illumination into multi-function rear clusters. Tier-1 lamp manufacturers adopt these architectures within 24-month platform cycles. The shift compresses the addressable market for standalone plate light suppliers while expanding content-per-vehicle for integrated module producers.
REACH substance restrictions on halogenated flame retardants in automotive plastics are forcing polycarbonate compound reformulation. European lens molders face 18-month material qualification timelines. The regulation most affects suppliers serving German premium OEMs, who have accelerated in-house polymer development to maintain homologation schedules.
Fleet procurement teams now source replacement plate lights through consolidated MRO distributors rather than traditional automotive aftermarket channels. Independent repair shops in the United States lose direct supplier relationships as national fleet service contracts centralize purchasing. This pattern concentrates volume with distributors holding NHTSA compliance documentation capabilities.
Automotive License Plate Light Market Segmentation
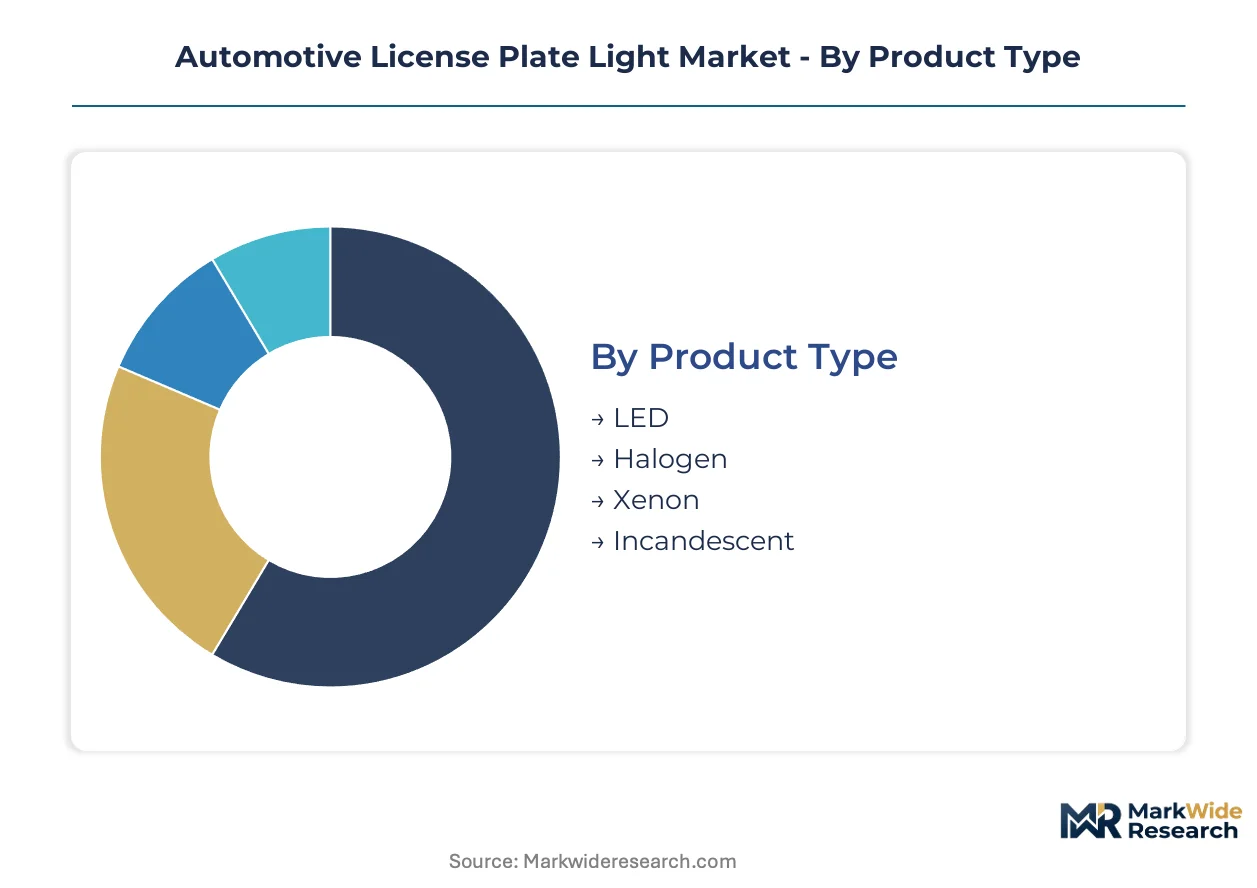
Segmentation in the Automotive License Plate Light Market reveals how thermal management constraints and integration depth reshape supplier economics. Technology choice and installation channel determine margin structure, while vehicle electrification and fleet digitization redirect demand toward specific power architectures.
Product Type:
Integration depth varies sharply across illumination technologies, with surface-mount architectures enabling module consolidation while legacy formats persist in cost-sensitive replacement cycles.
- LED:Ceramic-substrate SMD arrays with phosphor-converted architectures deliver 50-150 lumens in sub-20mm housings. Demand clusters in Germany where ECE Regulation 48 homologation timelines favor thermally validated LED suppliers for premium OEM rear-module integration.
- Halogen:Tungsten-filament designs in sealed glass envelopes maintain 5W-15W ratings for legacy vehicle parc compatibility. Fleet operators in the United States source these through consolidated MRO distributors as NHTSA inspection standards tighten on commercial vehicles.
- Xenon:High-intensity discharge capsules require external ballast electronics and occupy deeper housing profiles.
- Incandescent:Standard bulb formats persist in aftermarket channels for vehicles exceeding seven years of age.
Volume placements concentrate in LED; the faster expansion belongs to halogen retrofit demand from aging commercial fleets.
Installation Type:
Channel economics split between captive OEM supply with long-term platform commitments and fragmented aftermarket access where compliance documentation determines distributor concentration.
- OEM:Tier-1 lamp manufacturers deliver pre-validated modules synchronized to 24-month vehicle platform cycles. German premium automakers consolidate supplier relationships through integrated rear-light assemblies that embed plate illumination.
- Aftermarket:Independent repair shops and vehicle owners source replacement sealed units through distributors holding NHTSA compliance documentation. United States vehicle parc age exceeding seven years sustains this channel despite procurement centralization.
- Plug-and-Play:Pre-wired assemblies with standardized connectors reduce installation labor for independent technicians.
- Custom Fit:Bespoke housings for modified or classic vehicles require manual alignment and sealing.
Revenue concentrates in OEM; aftermarket channels are climbing the fastest as fleet procurement patterns shift toward distributor consolidation.
Vehicle Type:
Application intensity varies with bumper depth constraints and regulatory enforcement rigor across passenger, commercial, and two-wheel categories.
- Passenger Cars:Slim bumper profiles in sedans and hatchbacks drive demand for sub-20mm LED modules. Chinese domestic-market vehicles face MIIT certification requirements that sustain replacement cycles for non-compliant legacy units.
- SUVs:Higher mounting positions and deeper housing allowances accommodate broader technology flexibility. United States consumer preference for larger vehicles sustains volume in this segment.
- Trucks:Commercial fleet specifications prioritize durability and inspection compliance over integration depth.
- Motorcycles:Minimalist housing requirements favor compact LED arrays with exposed thermal management.
Shipments cluster in passenger cars; SUVs are gaining share fastest as platform architectures standardize across body styles.
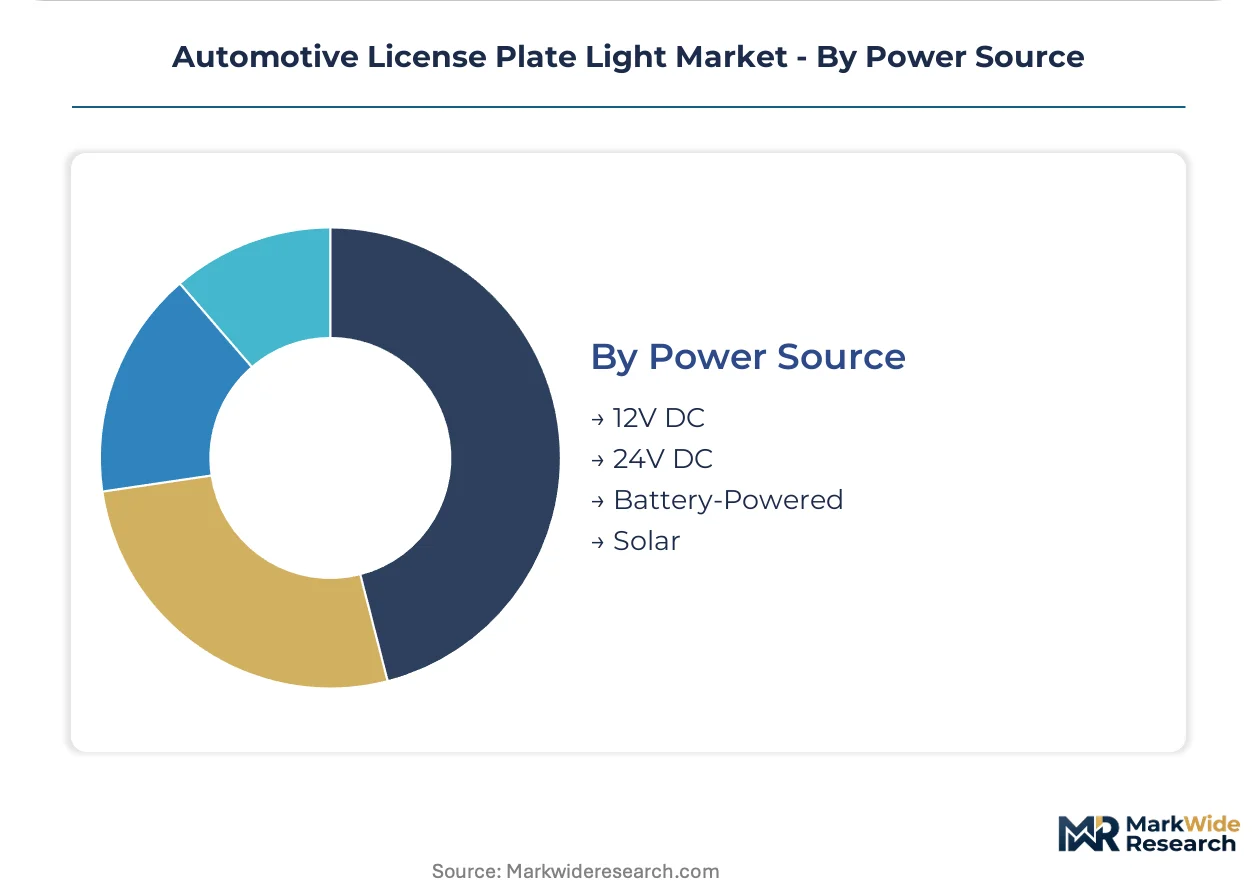
Power Source:
Electrification trajectories and commercial fleet duty cycles determine voltage architecture selection, with thermal load and wiring harness compatibility as critical constraints.
- 12V DC:Standard passenger vehicle electrical systems dominate volume. German and Japanese OEMs specify 12V LED drivers with integrated thermal protection for rear-module consolidation.
- 24V DC:Heavy-duty commercial trucks and buses require higher-voltage architectures to reduce current draw on long harness runs. Fleet operators in the United States specify 24V LED retrofits as state-level inspection standards tighten.
- Battery-Powered:Auxiliary units for trailer and temporary mounting applications bypass vehicle electrical systems.
- Solar:Self-contained photovoltaic charging for off-road and specialty vehicles with minimal nighttime duty cycles.
Volume concentrates in 12V DC; 24V DC is expanding most quickly as commercial fleet electrification and inspection mandates converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth phosphor deposits in China's Jiangxi Province anchor the upstream supply chain for LED architectures, while polycarbonate compounding clusters in Germany's Ruhr region and assembly integration centers in the US Midwest shape downstream value distribution.
United States
Commercial fleet operators dominate volume demand as NHTSA inspection standards tighten on visibility compliance. State-level enforcement variations create patchwork retrofit requirements across jurisdictions. Detroit-area Tier-1 suppliers consolidate rear-module production for domestic OEM platform cycles.
Germany
Premium automakers drive specification intensity through integrated rear-light assemblies that embed plate illumination. ECE Regulation 48 homologation timelines favor thermally validated LED suppliers with established KBA certification pathways. Stuttgart and Munich engineering centers concentrate CFD simulation talent for sub-20mm housing design.
China
Domestic-market vehicle production sustains replacement cycles under MIIT certification requirements for GB standards compliance. Yangtze River Delta component manufacturers pivot toward module-level supply for rear-vehicle lighting assemblies. Shenzhen and Shanghai house the dominant polycarbonate lens molding capacity serving Asian OEMs.
Japan
Integrated lamp manufacturing anchors Asian supply chain resilience through just-in-time delivery systems. METI efficiency standards for automotive lighting components accelerate LED adoption in domestic production. Nagoya and Tokyo metropolitan areas concentrate thermal engineering expertise for compact housing architectures.
South Korea
Hyundai-Kia platform standardization creates volume opportunities for validated module suppliers. Domestic LED component production scales to serve both captive OEM demand and export markets. Seoul Capital Area hosts the primary concentration of rear-light assembly integration facilities.
Automotive License Plate Light Market Competitive Environment
Global majors compete with regional champions across thermal engineering capability and homologation access. The vendor base stratifies into three tiers: integrated lamp manufacturers with captive OEM relationships, specialized LED component suppliers with phosphor-conversion expertise, and polycarbonate lens molders with automotive-grade compound qualifications. Consolidation pressures intensify as module depth requirements compress below 20mm, forcing standalone plate light suppliers to either integrate into rear-light assemblies or exit the category entirely. Dominant competitive moves include strategic partnerships for mechatronics convergence and geographic expansion to capture fleet retrofit demand.
Among Germany-based lighting specialists, HELLA GmbH & Co. KGaA and OSRAM GmbH exemplify the integrated component-to-module archetype, leveraging established European production footprints and KBA homologation pathways. Japanese fabricators Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions within the Asian supply chain tier, anchoring just-in-time delivery systems for domestic OEM platform cycles. These named entities represent the competitive density around thermal management and regulatory certification rather than exhaustive market coverage.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Koito Manufacturing Co., Ltd. |
| OSRAM GmbH |
| Stanley Electric Co., Ltd. |
| Valeo S.A. |
| Magneti Marelli S.p.A. |
| Philips (Signify N.V.) |
| ZKW Group |
| Robert Bosch |
| Others |
Value Chain & Pricing Dynamics
Rare-earth phosphor costs originating in Chinese export quotas cascade through LED module pricing tiers, compressing margins for high-CRI architectures while fleet procurement centralization in the United States concentrates volume leverage with MRO distributors holding NHTSA compliance documentation.
Pricing Analysis
Warranty bundling separates OEM supply contracts from aftermarket transactions, with premium German automakers demanding multi-year homologation support while independent repair shops absorb unbundled replacement risk. Pricing stratifies across premium, standard, and economy tiers based on thermal validation depth and KBA certification status. Cost compression in the halogen retrofit segment is intensifying because fleet operators consolidate purchasing through national MRO contracts. Commercial fleet buyers exhibit highest price sensitivity; premium OEM platform engineers prioritize thermal performance over unit cost.
Supply Chain Analysis
KBA and ECE Regulation 48 certification gates concentrate qualified supply among German, Chinese, and Japanese manufacturers with established homologation pathways. Rare-earth phosphors, ceramic LED substrates, and automotive-grade polycarbonate compounds anchor upstream dependencies. Single-source vulnerability clusters in Jiangxi Province phosphor refining and Ruhr region lens molding capacity. Distribution runs through Tier-1 lamp manufacturers to OEM assembly plants, with aftermarket channels fragmenting toward consolidated MRO distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as module depth requirements below 20mm force suppliers to control thermal engineering and polycarbonate compounding in-house to defend margin structure.
For Market Incumbents: Extend thermal engineering capabilities through captive CFD simulation talent acquisition in Stuttgart and Nagoya engineering centers. Secure long-term polycarbonate compound qualifications ahead of REACH flame-retardant restrictions. Software-defined lighting architectures threaten dedicated plate hardware elimination; backward integration into ceramic substrate production reduces phosphor cost volatility exposure.
For New Entrants and Emerging Players: Independent repair shops in the United States represent an underserved buyer archetype as national fleet contracts bypass traditional automotive aftermarket channels. Target commercial fleet MRO distributors lacking NHTSA compliance documentation capabilities. White space exists in 24V DC LED retrofits for heavy-duty trucks facing state-level inspection tightening. Go-to-market leverage rests on pre-certified module offerings with consolidated warranty terms.
For Investors and Strategic Acquirers: ECE Regulation 48 homologation timeline compression is the leading indicator that thermal validation capacity will command scarcity premiums. Long-term viability favors suppliers with integrated rear-module production and established KBA certification pathways. Acquisition targets should display mechatronics convergence capability for camera-radar-lighting integration. Watch for German premium OEM platform standardization announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Rear-Module Integration | Consolidates plate illumination into multi-function clusters, reducing part count for European OEMs. |
| Ceramic Substrate Backward Integration | Captures thermal management value chain segment critical to sub-20mm housing performance. |
| REACH-Compliant Polymer Development | Accelerates 18-month material qualification timelines for German premium automaker supply. |
| 24V DC Fleet Retrofit Certification | Opens commercial vehicle replacement cycles under tightening NHTSA state inspection standards. |
| Mechatronics Capability Acquisition | Positions suppliers for convergence of camera, radar, and lighting functions in bumper assemblies. |
Study Parameters
Independent corroboration across Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and thermal engineering specialists underwrites the qualitative findings. Primary interviews with fleet operations managers and MRO purchasing directors combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA compliance filings, and ECE homologation records established demand-side parameters. Bottom-up triangulation across LED component shipments and top-down reconciliation against vehicle platform cycles anchored volume estimates.
Comparable-period anchoring to historical platform development cycles and retrofit replacement rates informed the projection framework across the analysis window. Segmentation modeling incorporated product type, installation channel, vehicle class, and voltage architecture dimensions. CAGRs derived from regression analysis against regulatory enforcement intensity and fleet age distribution patterns. Forecast inputs included polycarbonate compound qualification timelines and phosphor export quota volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to software-defined lighting substitution rates and REACH regulatory expansion. Forecasts reflect documented assumptions regarding OEM platform cycle synchronization and fleet procurement centralization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automobile Accessories Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Europe Torque Vectoring Market