
 Automotive Hardware-In-The-Loop Simulation Market | 2026-2036
Automotive Hardware-In-The-Loop Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hardware-In-The-Loop Simulation Market Insights
Software-defined vehicle architectures is tilting development budgets toward virtual validation environments. dSPACE GmbH leverages deep integration with automotive toolchains to anchor its position in European OEM programs. OPAL-RT Technologies Inc. specializes in power electronics simulation, while Vector Informatik GmbH dominates network and ECU test coverage. Typhoon HIL Inc. competes on FPGA-based real-time performance for grid-tied automotive applications.
Automotive Hardware-In-The-Loop Simulation employs real-time processors coupled with physical I/O interfaces to execute mathematical vehicle models against actual electronic control units, compressing validation cycles from months to days. Simulation Platforms and Testing Tools capture the largest margin pools as OEMs consolidate vendor relationships around integrated bench ecosystems. Electric Vehicles and Advanced Driver Assistance Systems represent the fastest-growing application clusters, driven by the complexity of battery management algorithms and sensor fusion validation.
NHTSA crashworthiness protocols, EPA emissions certification requirements, and ISO 26262 functional-safety standards collectively mandate traceable, repeatable test evidence that HIL systems generate efficiently. ECE regulations in Europe and GB standards in China impose parallel conformity pressures, widening addressable demand. Stakeholders must weigh vendor lock-in risks against the integration depth required for next-generation zonal E/E architectures.
Market Dynamics
ISO 26262 functional-safety mandates across Germany, Japan, and the United States are forcing OEM validation labs to replace physical prototyping with real-time simulation, compressing development cycles from months to days while tightening traceability requirements.
Growth Catalysts
- Powertrain electrification:Battery management algorithm complexity for electric vehicles demands real-time verification that HIL platforms deliver. OEMs in Germany and Japan prioritize this capability.
- NHTSA crashworthiness protocols:Traceable, repeatable test evidence requirements mandate automated validation systems that generate compliant documentation efficiently.
- Sensor fusion validation:Advanced Driver Assistance Systems integration requires simultaneous multi-sensor simulation that physical testing cannot replicate at scale.
Market Restraints
- FPGA hardware costs:Real-time processor and I/O interface procurement represents substantial upfront capital expenditure for mid-tier suppliers.
- Vendor ecosystem concentration:European toolchains dominate OEM program integration, creating switching friction for alternative platform providers.
- Legacy ECU compatibility:Zonal E/E architecture migration requires bridging incompatible communication protocols that extend validation timelines.
Strategic Opportunities
- Grid-tied automotive applications:Vehicle-to-grid integration testing for bidirectional charging systems opens specialized simulation demand.
- EPA emissions certification:Powertrain control module validation for hybrid architectures creates recurring service revenue streams.
- China GB standards alignment:Domestic OEM expansion requires localized HIL bench configurations that foreign vendors underpenetrate.
Industry Challenges
- Embedded systems engineering talent:Real-time modeling and hardware interface design expertise scarcity constrains bench deployment velocity.
- Multi-domain integration complexity:Power electronics, network, and ECU test coverage consolidation demands cross-functional team coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hardware-In-The-Loop Simulation Market |
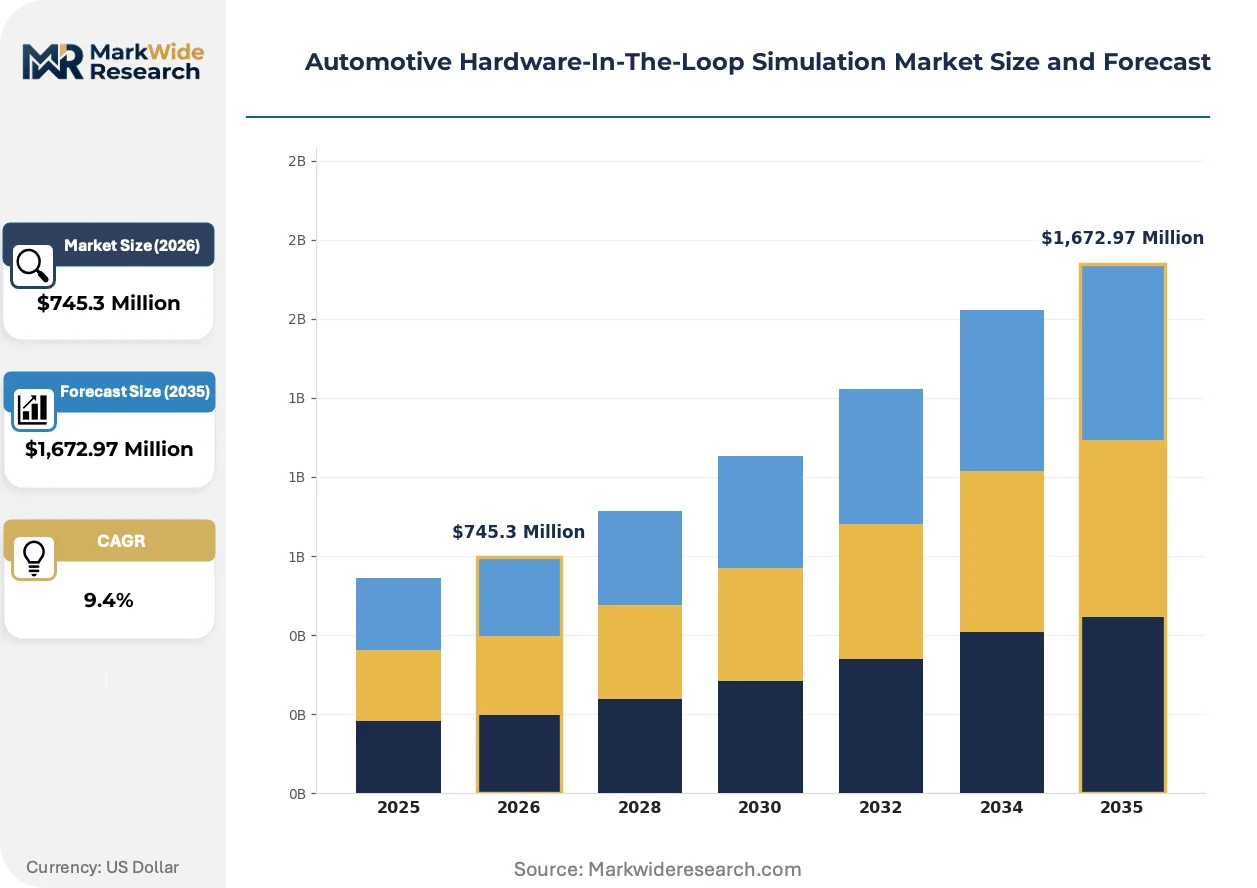
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,672.97 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Platforms, Testing Tools, Interface Solutions, Calibration Systems Technology: Real-Time Simulation, Model-Based Design, Software-in-the-Loop, Co-Simulation Application: Vehicle Dynamics, Powertrain Testing, Advanced Driver Assistance Systems, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Research Institutions, Engineering Firms |
| Companies Covered | dSPACE GmbH, OPAL-RT Technologies Inc., Vector Informatik GmbH, Robert Bosch GmbH, Continental AG, Magna International Inc., Softing Automotive Electronics GmbH, Typhoon HIL Inc., IPG Automotive GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hardware-In-The-Loop Simulation Market Trends and Innovations
Software-defined vehicle architectures are fundamentally restructuring how automotive validation budgets flow, tilting investment toward virtual environments that execute mathematical models against physical control units.
FPGA-based simulation hardware is digitizing power electronics testing by executing nanosecond-resolution switching models that CPU-based systems cannot achieve. Tier-1 suppliers in Germany and Japan are adopting these platforms for inverter and DC-DC converter verification. This capability is digitizing the boundary between laboratory validation and production release, collapsing traditional stage-gate timelines.
EU AI Act algorithmic transparency requirements are mandating documented decision-path verification for autonomous driving functions. Automotive OEMs must now generate auditable simulation traces that explain control unit responses to synthetic scenarios. European validation labs are responding by integrating formal verification methods into existing HIL workflows.
Consolidated vendor relationships are displacing point-tool procurement as OEMs demand integrated bench ecosystems spanning simulation platforms and testing tools. Tier-1 suppliers now specify single-source accountability for complete validation chains. This concentration is most visible in German OEM programs, where procurement teams prioritize toolchain interoperability over best-of-breed component selection.
Automotive Hardware-In-The-Loop Simulation Market Segmentation
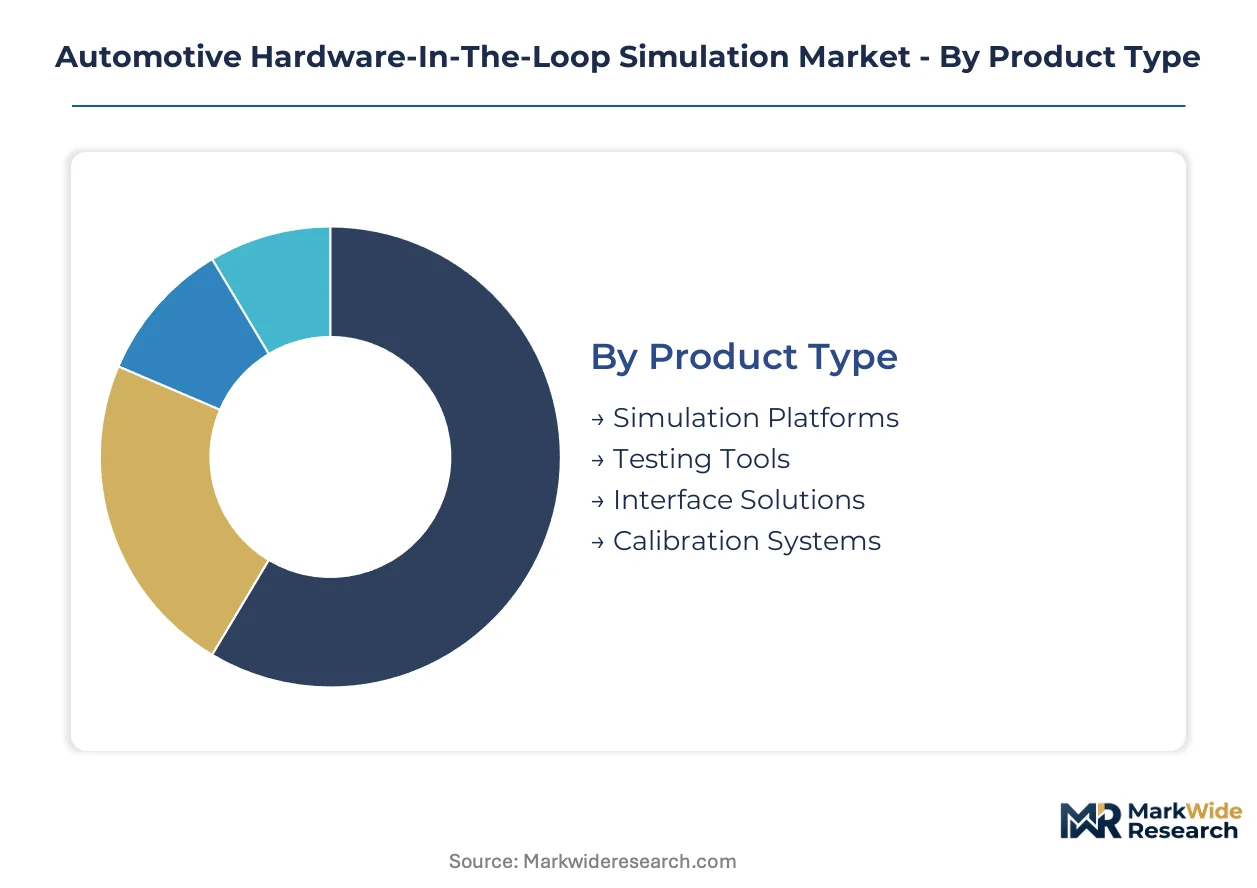
HIL segmentation reflects how validation workflows fragment across hardware abstraction layers and organizational boundaries. Procurement patterns diverge sharply between integrated platform buyers and modular tool assemblers.
Product Type:
Use-case spectrum spans full-stack bench ecosystems down to single-purpose interface modules, with procurement scope determining margin capture and vendor stickiness.
- Simulation Platforms:Integrated real-time processor systems execute multi-domain vehicle models against physical ECUs through deterministic I/O channels. OEM validation labs in Germany and Japan consolidate procurement around these systems to compress ISO 26262 compliance timelines.
- Testing Tools:Specialized software environments automate test case generation, execution logging, and traceability documentation for regulatory submission. Tier-1 suppliers leverage these tools to service multiple OEM programs without bench duplication.
- Interface Solutions:Signal conditioning and protocol translation hardware bridges simulation processors to legacy ECU communication buses.
- Calibration Systems:Parameter tuning workstations enable real-time model adjustment during hardware-in-the-loop execution.
The dominant share belongs to Simulation Platforms, while Testing Tools is closing the gap fastest.
Technology:
Cost tier segmentation separates nanosecond-resolution FPGA investments from CPU-based approaches suited to lower-frequency validation domains.
- Real-Time Simulation:Deterministic execution guarantees sub-millisecond latency for closed-loop control testing, with FPGA-based implementations commanding premium positioning for power electronics applications. Battery management system verification in electric vehicle programs drives concentration here.
- Model-Based Design:Graphical modeling environments auto-generate production code from simulation artifacts, collapsing traditional hand-coding stages. European OEMs mandate this workflow for zonal E/E architecture development.
- Software-in-the-Loop:PC-based algorithm validation without hardware I/O reduces early-stage iteration cost.
- Co-Simulation:Federated execution links specialized tools across mechanical, electrical, and thermal domains.
Real-Time Simulation holds the revenue concentration, though Model-Based Design is expanding most quickly as code generation mandates tighten.
Application:
Customer type fragmentation maps directly to regulatory exposure, with crashworthiness and emissions certification creating divergent technical requirements.
- Powertrain Testing:Engine control module and transmission calibration validation against EPA emissions protocols and Euro 7 standards. Hybrid architecture complexity in German and Japanese OEM portfolios sustains demand concentration.
- Advanced Driver Assistance Systems:Multi-sensor fusion verification requiring simultaneous camera, radar, and lidar simulation that physical track testing cannot replicate at scale. NHTSA crashworthiness documentation mandates drive procurement.
- Vehicle Dynamics:Chassis control and steering system validation for ride-handling tradeoffs.
- Electric Vehicles:Battery management algorithm and inverter switching verification for bidirectional charging integration.
Powertrain Testing retains the largest installed base, yet Advanced Driver Assistance Systems is gaining share fastest on sensor fusion complexity.
End User:
Supply concentration tilts toward OEM captive labs, though service-based models are penetrating mid-tier supplier tiers.
- OEMs:In-house validation centers maintain direct control over functional safety evidence generation for ISO 26262 audits, with German and Japanese manufacturers operating the most extensive bench networks. Consolidated vendor relationships reduce integration risk.
- Tier-1 Suppliers:Component specialists operate shared service labs across multiple OEM programs, amortizing platform investment through volume. Engineering firms in this tier face FPGA hardware cost barriers.
- Research Institutions:Academic and government labs advance simulation methodology without production validation mandates.
- Engineering Firms:Consultancies provide surge capacity and specialized expertise for program-specific validation campaigns.
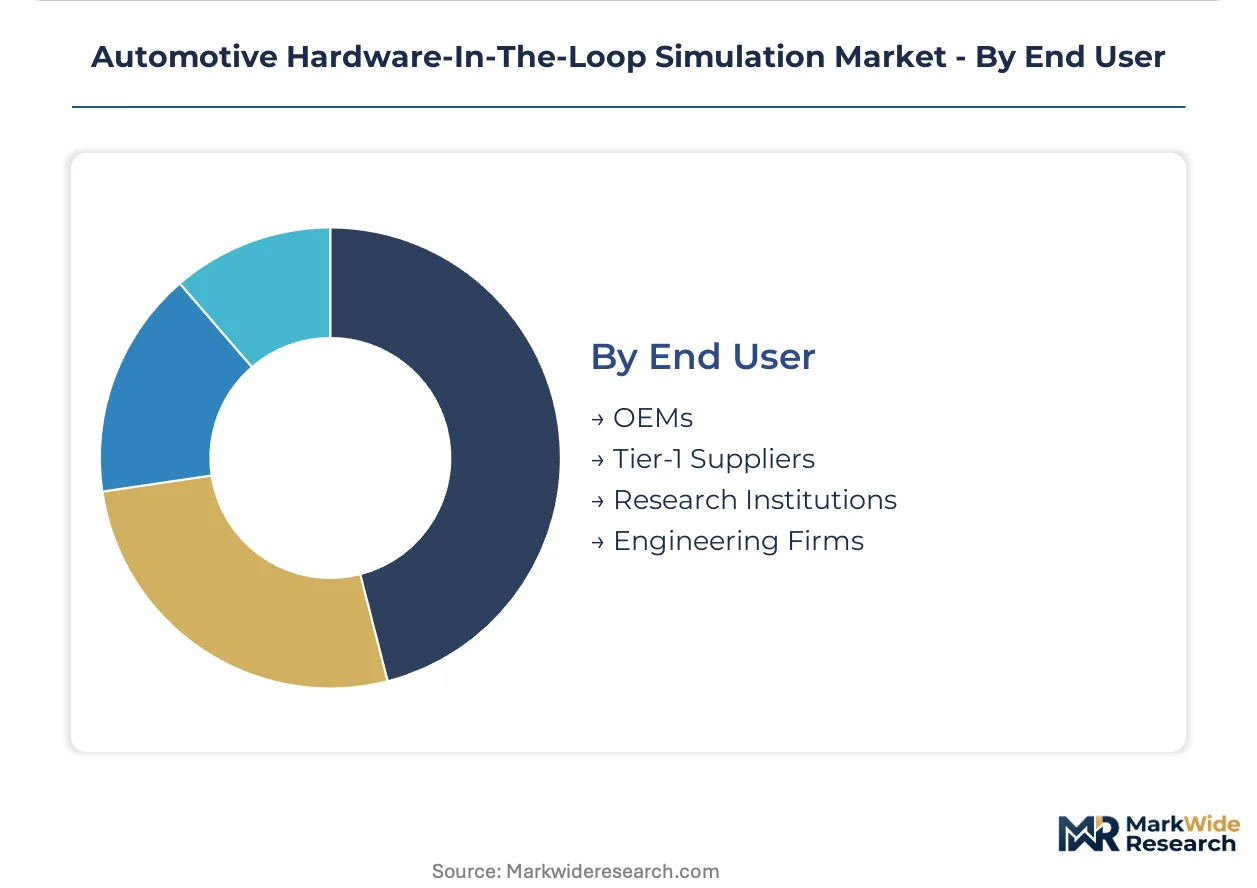
OEMs command the dominant procurement volume, while Tier-1 Suppliers are climbing the fastest on shared-service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports automotive validation equipment to Japanese and US OEM programs, with hardware-in-the-loop benches flowing through established supplier networks into captive validation labs across three continents.
United States
NHTSA crashworthiness protocols and EPA emissions certification drive procurement of traceable test systems. The Department of Transportation mandates documented validation evidence for autonomous driving functions. Detroit's automotive corridor concentrates Tier-1 supplier labs where shared-service models amortize platform investment across multiple OEM programs.
Germany
ISO 26262 functional-safety mandates from KBA tighten evidence requirements for powertrain electrification. The EU AI Act imposes algorithmic transparency documentation on autonomous vehicle validation. Stuttgart and Munich anchor extensive OEM captive networks where consolidated vendor relationships reduce integration risk for zonal E/E architectures.
Japan
METI industrial policy prioritizes battery management algorithm verification for export-bound electric vehicles. JIS standards alignment with international functional-safety frameworks streamlines cross-border certification. Nagoya's manufacturing belt hosts concentrated Tier-1 engineering operations serving Toyota and Honda validation programs.
China
GB standards for intelligent connected vehicles mandate domestic HIL bench configurations that foreign vendors underpenetrate. MIIT regulations on new energy vehicle safety testing accelerate localized procurement. Shanghai and Shenzhen clusters drive demand for power electronics simulation supporting bidirectional charging integration.
South Korea
MFDS automotive safety guidelines and national semiconductor self-sufficiency goals shape validation infrastructure investment. Government-backed battery technology initiatives require real-time simulation for cell management system verification. Seoul Capital Area OEMs operate integrated bench ecosystems spanning Hyundai and Kia development centers.
Automotive Hardware-In-The-Loop Simulation Market Competitive Landscape
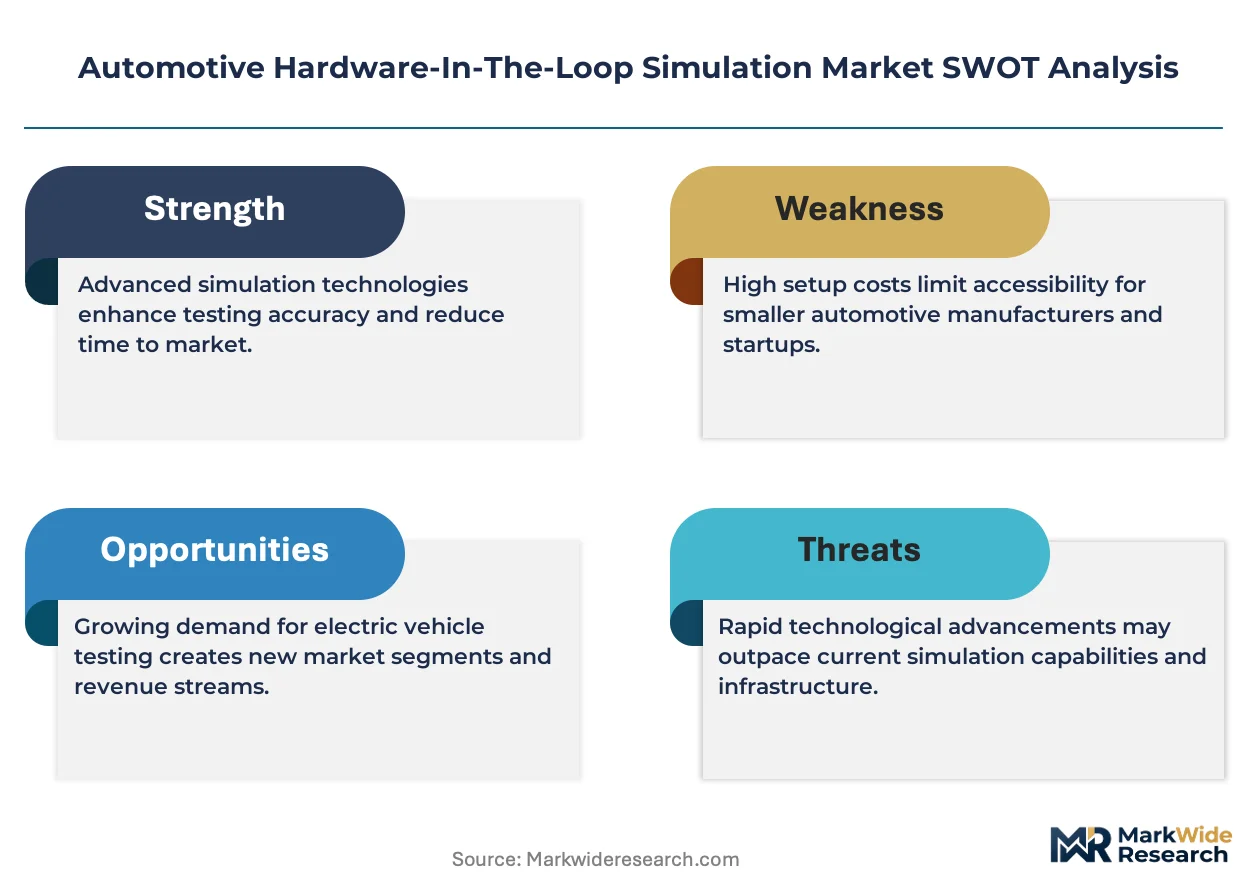
On the supply side, the industry is consolidating around integrated platform providers that span simulation processors, testing software, and calibration workstations. Tier-1 suppliers now demand single-source accountability for complete validation chains, displacing point-tool procurement. Three archetypes dominate: European toolchain integrators, North American power electronics specialists, and automotive Tier-1 captive solution providers. Competitive moves concentrate on strategic partnerships with semiconductor vendors and geographic expansion through localized service subsidiaries.
Within the European toolchain tier, dSPACE GmbH exemplifies deep automotive integration, while Vector Informatik GmbH anchors network and ECU test coverage. Typhoon HIL Inc. represents the FPGA-based real-time performance specialization for grid-tied applications. These three occupy positions across the spectrum from full-stack bench ecosystems to targeted interface solutions, reflecting how vendor selection criteria vary between OEM captive labs and shared-service Tier-1 operations.
| Leading Market Players |
|---|
| dSPACE GmbH |
| OPAL-RT Technologies Inc. |
| Vector Informatik GmbH |
| Robert Bosch GmbH |
| Continental AG |
| Magna International Inc. |
| Softing Automotive Electronics GmbH |
| Typhoon HIL Inc. |
| IPG Automotive GmbH |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-to-Hamburg freight corridors carry FPGA processors and real-time I/O modules from Asian semiconductor foundries to German OEM validation labs, with logistics cost volatility amplifying the technology-generation pricing gap between CPU-based and FPGA-based HIL systems while compressing margins for mid-tier suppliers dependent on spot procurement.
Pricing Analysis
Next-generation FPGA-based simulation hardware commands substantial premiums over prior-generation CPU platforms, while early-generation software-in-the-loop tools face price erosion from open-source alternatives. Three-tier pricing structure across premium FPGA systems, standard CPU-based benches, and economy SIL configurations reflects performance tier and certification depth. Pricing pressure stems from OEM consolidation around single-source vendors demanding volume discounts. Tier-1 suppliers exhibit highest price sensitivity due to shared-service model pressures, while German OEM captive labs prioritize integration depth over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for automotive HIL hardware, with semiconductor fabrication concentrated in Taiwan, South Korea, and China. Real-time processors, high-speed I/O interfaces, and specialized FPGA chips draw from concentrated foundry capacity. Single-source vulnerability in advanced node semiconductor supply threatens delivery timelines for next-generation power electronics simulation. Distribution runs through authorized distributor networks serving OEM captive labs and Tier-1 engineering centers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive HIL simulation operates as a defensive-moat market where regulatory entrenchment creates substantial switching costs for OEM validation labs locked into ISO 26262-compliant toolchains.
For Market Incumbents: Harden vendor lock-in through deeper integration with zonal E/E architecture development workflows and exclusive certification partnerships with KBA and NHTSA. Expand FPGA-based power electronics simulation capacity to defend against emerging powertrain electrification specialists. Prioritize backward integration into real-time processor design to secure supply against semiconductor foundry allocation constraints. For New Entrants and Emerging Players: Build out localized HIL bench configurations for China's GB standards compliance, the most penetrable geography given foreign vendor underpenetration. Target shared-service Tier-1 supplier labs with modular interface solutions that bypass full-platform procurement barriers. Lead with vehicle-to-grid bidirectional charging simulation as a differentiated entry angle. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier-1 captive solution providers seeking to monetize non-core validation assets. Long-term viability hinges on software-defined vehicle architecture transition sustaining virtual validation demand. Monitor EPA emissions certification timeline acceleration as the critical inflection signal for powertrain HIL demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around integrated bench ecosystems reduces vendor fragmentation and integration risk for German validation programs. |
| Battery Supply Agreement | Cell manufacturer partnerships secure FPGA processor allocation priority for electric vehicle powertrain simulation capacity expansion. |
| Software-Defined Vehicle Investment | Virtual validation environment development aligns HIL procurement with zonal E/E architecture migration timelines at Japanese OEMs. |
| Geographic Manufacturing Footprint | Localized assembly in China addresses GB standards mandates while reducing tariff exposure on semiconductor imports. |
| Charging Infrastructure Partnership | Grid-tied automotive application testing opens specialized revenue streams for bidirectional charging system verification. |
Research Methodology
The analysis maps simulation platforms, testing tools, interface solutions, and calibration systems, each validated through primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, HIL system integration specialists, and semiconductor distribution channel managers, cross-referenced against vehicle production databases, IHS Markit registration data, SEC filings from publicly traded automotive suppliers, and customs records for FPGA processor trade flows, with bottom-up segment sizing triangulated against top-down automotive R&D expenditure trends.
Assumptions held fixed include ISO 26262 functional-safety mandate enforcement timelines and NHTSA crashworthiness protocol documentation requirements, while electric vehicle penetration rates and zonal E/E architecture adoption curves varied across sensitivity scenarios. The projection horizon spans product type, technology generation, application cluster, and end-user tier dimensions, with CAGRs derived from segment-level growth trajectory analysis incorporating battery management algorithm complexity curves and ADAS sensor fusion validation demand curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor foundries into HIL system assembly would shift outcomes through supply structure transformation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market