
 Automotive Simulation Market | 2026-2036
Automotive Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Simulation Market Intelligence
Subscription-based access to software-defined simulation modules is decoupling perpetual licensing from core engineering workflows. Ansys leverages physics-based solver integration across multiphysics domains to anchor high-fidelity automotive applications. Siemens sustains broad portfolio coverage spanning design through manufacturing execution, while dSPACE GmbH specializes in hardware-in-the-loop validation systems for embedded control testing.
Automotive simulation encompasses computational modeling environments that replicate vehicle subsystems, operating conditions, and crash scenarios through finite element analysis, multibody dynamics, and real-time processor-in-the-loop architectures. These systems enable predictive validation of structural integrity, thermal management, and control algorithm performance prior to physical prototyping. Driving simulators and crash test simulators command established installed bases with mature margin profiles, whereas autonomous vehicle testing applications within the application dimension exhibit accelerated uptake as lidar-to-software integration complexity intensifies. Hardware-in-the-loop technology dominates validation workflows for powertrain electronic control units, while virtual reality simulation occupies emerging niches in human-factors driver training.
NHTSA Federal Motor Vehicle Safety Standards and EPA greenhouse gas emissions regulations in the United States mandate exhaustive pre-homologation validation that simulation platforms address. ECE R94/R95 pedestrian and occupant protection protocols in Europe, alongside CE marking requirements for software tools, shape product development roadmaps and market access criteria. Stakeholders must weigh capital allocation between proprietary solver development and cloud-native platform partnerships as OEM procurement criteria shift toward interoperability and scalable compute licensing.
Market Dynamics
Virtual prototyping is compressing physical test cycles as OEM procurement criteria pivot toward scalable compute licensing and interoperability standards. This structural shift reconfigures capital allocation between proprietary solver stacks and cloud-native partnerships.
Growth Catalysts
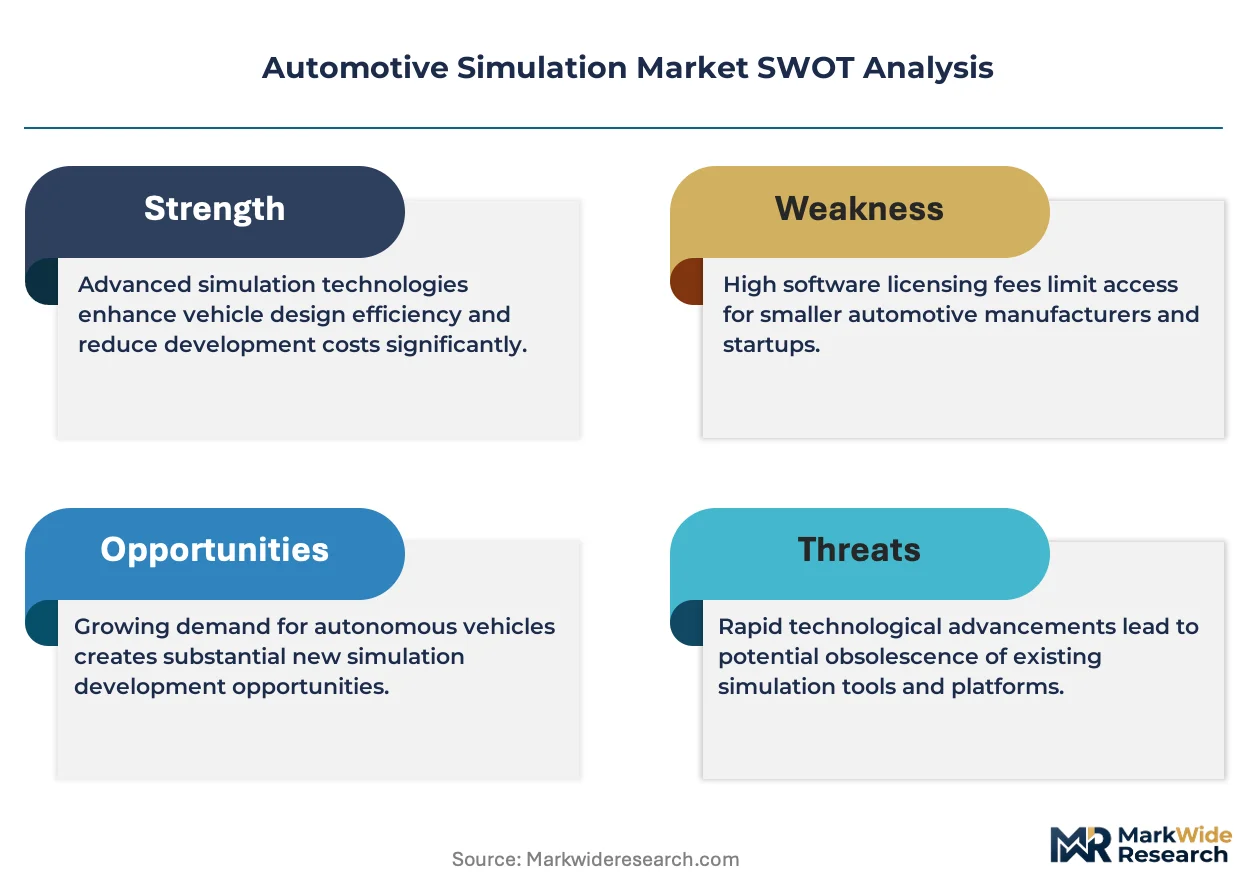
- NHTSA Crashworthiness Mandates:Federal Motor Vehicle Safety Standards compel exhaustive pre-homologation validation through digital environments, expanding hardware-in-the-loop deployment for structural integrity verification.
- Powertrain Electrification:Battery thermal management and electric motor control algorithms demand multiphysics simulation that finite element analysis platforms deliver with predictive fidelity.
- German Engineering Clusters:Stuttgart and Munich concentrate automotive R&D procurement, where regulatory stringency from KBA type-approval processes accelerates local adoption of real-time processor-in-the-loop systems.
Market Restraints
- Specialized Talent Scarcity:Shortages of computational fluid dynamics engineers and embedded control specialists inflate wage costs and extend implementation timelines.
- High-Performance Computing Infrastructure:Capital intensity of on-premise GPU clusters and cloud compute subscriptions strains mid-tier supplier budgets.
- CE Marking Complexity:Software tool certification requirements under EU machinery directives create compliance friction for non-European vendors seeking market access.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive manufacturing are attracting OEM engineering centers to Pune and Chennai, creating demand for localized simulation services.
- Autonomous Vehicle Validation:Lidar-to-software integration complexity is opening white space for sensor fusion simulation and scenario-based testing platforms.
- Digital Twin Convergence:Integration of physics-based solvers with manufacturing execution systems enables closed-loop product lifecycle management.
Industry Challenges
- ISO 26262 Certification Timelines:Functional safety validation for automotive software extends development cycles and requires specialized third-party assessment.
- Legacy Toolchain Integration:Embedded control units with decade-old architectures resist seamless migration to modern hardware-in-the-loop environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Simulation Market |
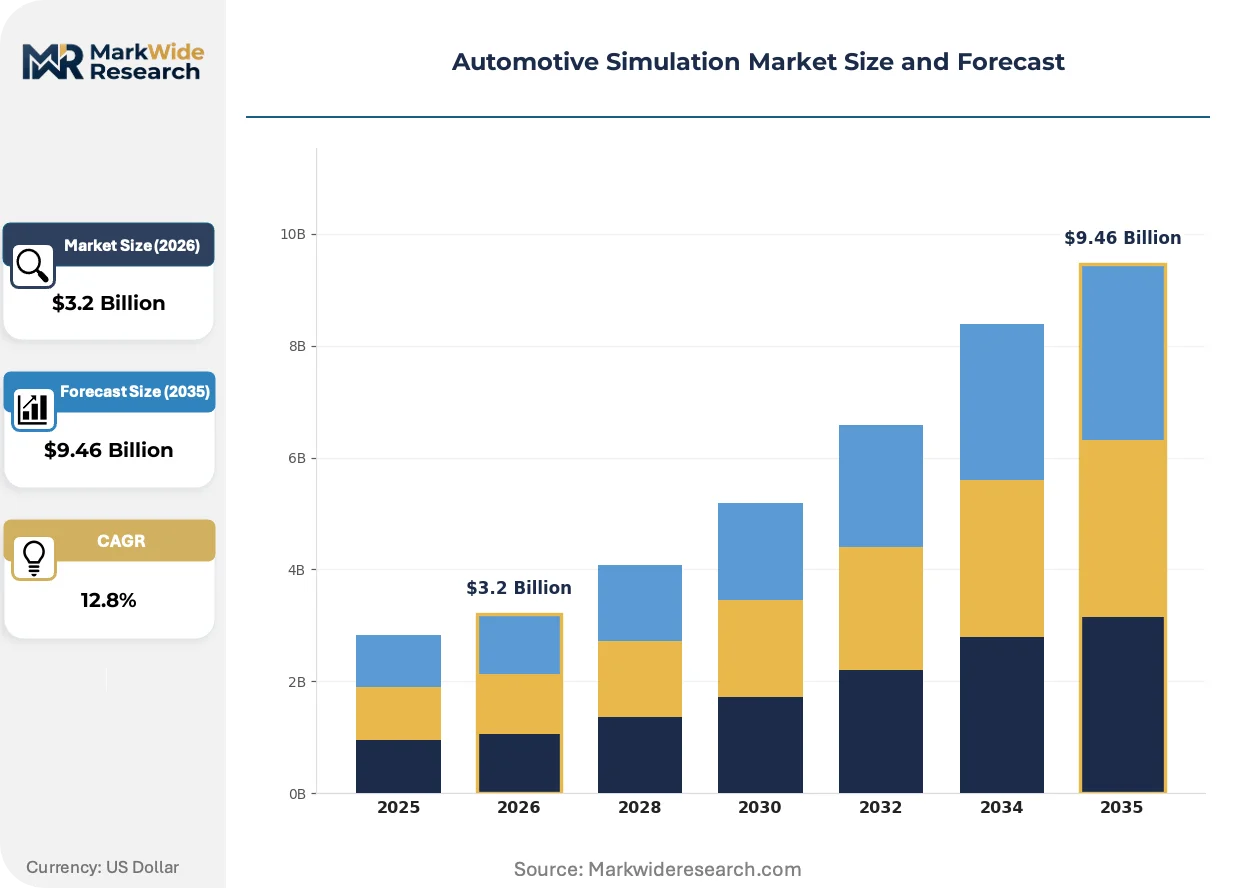
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $9.46 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driving Simulators, Vehicle Dynamics Simulators, Engine Simulators, Crash Test Simulators, Environment Simulators Technology: Real-Time Simulation, Offline Simulation, Hardware-in-the-Loop, Software-in-the-Loop, Virtual Reality Simulation Application: Design Validation, Safety Testing, Driver Training, Autonomous Vehicle Testing, Powertrain Optimization End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Research Institutes |
| Companies Covered | dSPACE GmbH, Autodesk, Ansys, Altair, PTC, Dassault Systèmes, ESI Group, Cognata, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Simulation Market Strategic Shifts & Innovations
Subscription-based licensing models are decoupling perpetual software ownership from core engineering workflows, while physics fidelity requirements intensify across electrification and autonomy programs.
Real-time ray tracing for sensor simulation is rewriting validation economics for autonomous perception stacks. Tier 1 suppliers are adopting these rendering engines at accelerated procurement cycles. The technology is rewriting the cost structure of camera and lidar hardware validation by collapsing photorealistic scenario generation from months to days.
EU Green Deal vehicle performance standards are mandating lifecycle emissions accounting that extends simulation requirements from tailpipe to manufacturing. Automotive OEMs must now model energy consumption across production, use-phase, and end-of-life. Battery cell manufacturers in Germany and France are responding by integrating thermal runaway prediction into early-stage pack design.
Consolidated vendor relationships are displacing point-solution procurement as engineering departments prioritize platform interoperability. Procurement teams now bundle finite element, multibody dynamics, and control validation under single master agreements. This concentration is most visible in German OEM engineering centers, where preferred supplier frameworks now span design through manufacturing execution.
Automotive Simulation Market Segmentation
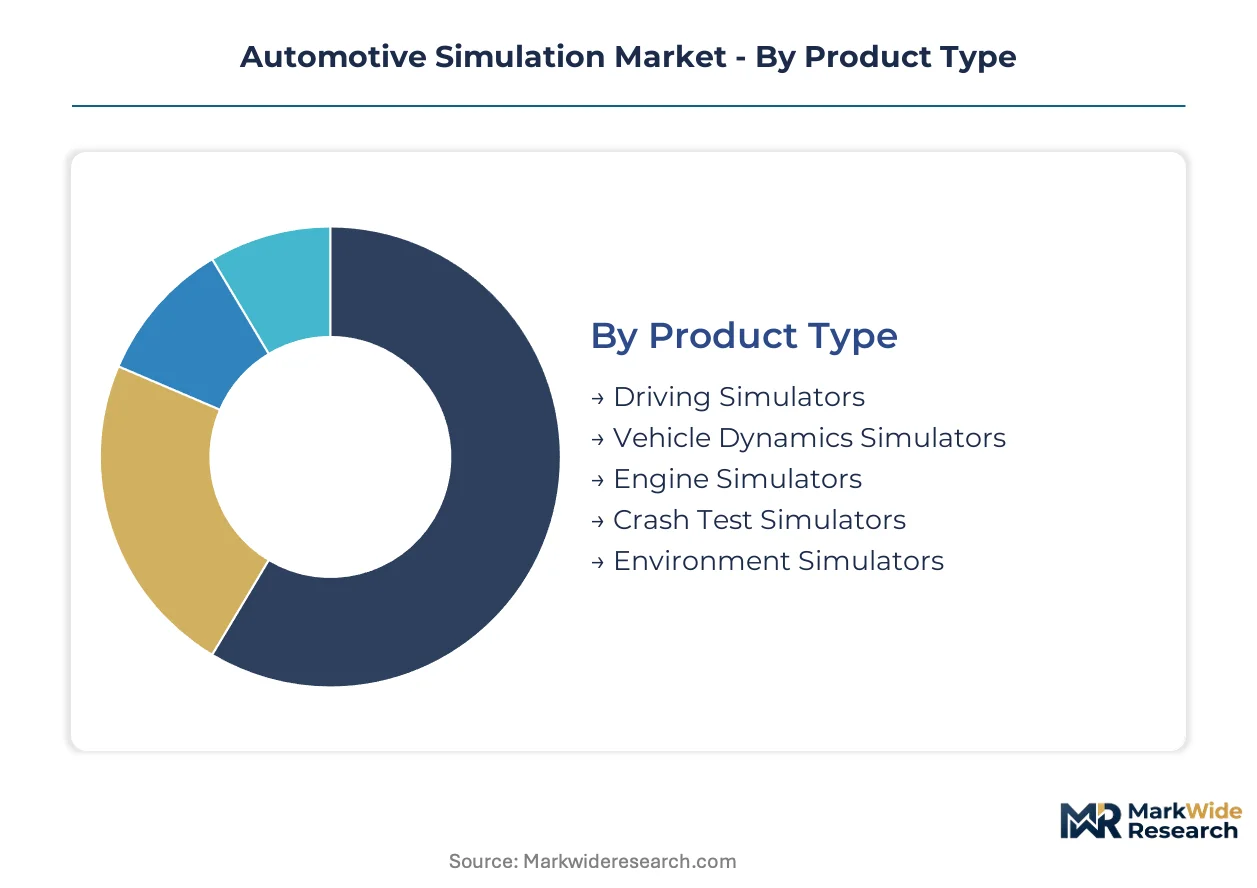
Automotive simulation procurement pivots on validation fidelity requirements and integration complexity across the development lifecycle. OEMs prioritize segments that compress physical prototyping cycles while meeting NHTSA and ECE homologation mandates.
Product Type:
Purchase decisions track validation scope — from human-factors training through destructive crash analysis.
- Driving Simulators:Full-cab motion platforms replicate vehicle dynamics and traffic scenarios for human-factors research. German OEM engineering centers in Stuttgart deploy these systems for driver behavioral studies ahead of ADAS feature releases.
- Crash Test Simulators:Finite element analysis environments model structural deformation and occupant kinematics under NHTSA FMVSS and ECE R94 protocols. These systems eliminate costly physical barrier tests while accelerating pedestrian protection compliance timelines.
- Vehicle Dynamics Simulators:Multibody dynamics platforms replicate suspension behavior and handling limits across virtual proving grounds.
- Engine Simulators:Combustion and thermal models optimize ICE efficiency and emissions profiles prior to hardware builds.
- Environment Simulators:Atmospheric and road condition replication supports climatic durability validation.
Volume sits with crash test simulators; growth tilts toward driving simulators as ADAS human-factors requirements expand.
Technology:
Integration architecture determines procurement — from offline preprocessing through real-time embedded validation.
- Hardware-in-the-Loop:Physical ECU integration with real-time processor architectures validates powertrain and chassis control algorithms under fault injection scenarios. dSPACE systems dominate German OEM validation workflows for KBA type-approval documentation.
- Software-in-the-Loop:Pure virtual execution environments enable early-stage algorithm development without hardware dependencies. Battery management system developers leverage these platforms for thermal runaway prediction before cell procurement.
- Real-Time Simulation:Deterministic execution guarantees for safety-critical control loop validation.
- Offline Simulation:High-fidelity physics preprocessing for detailed structural and thermal analysis.
- Virtual Reality Simulation:Immersive visualization for design review and driver training applications.
Hardware-in-the-Loop commands the largest installed base; Software-in-the-Loop is expanding most quickly as electrification programs front-load control algorithm development.
Application:
Regulatory pressure and program risk shape spending allocation across the validation spectrum.
- Autonomous Vehicle Testing:Sensor fusion simulation and scenario-based validation platforms address lidar-to-software integration complexity. Real-time ray tracing engines compress photorealistic scenario generation from months to days for camera and lidar hardware verification.
- Safety Testing:Pre-homologation validation environments satisfy NHTSA crashworthiness and ECE pedestrian protection mandates. These applications require traceable documentation for regulatory submission packages.
- Design Validation:Structural integrity and thermal management verification prior to prototype fabrication.
- Driver Training:Human-factors skill development and emergency response scenario rehearsal.
- Powertrain Optimization:Efficiency and emissions calibration for electrified and conventional propulsion systems.
Safety testing absorbs the greatest procurement volume; autonomous vehicle testing exhibits the steepest expansion trajectory as SAE Level 3+ programs advance.
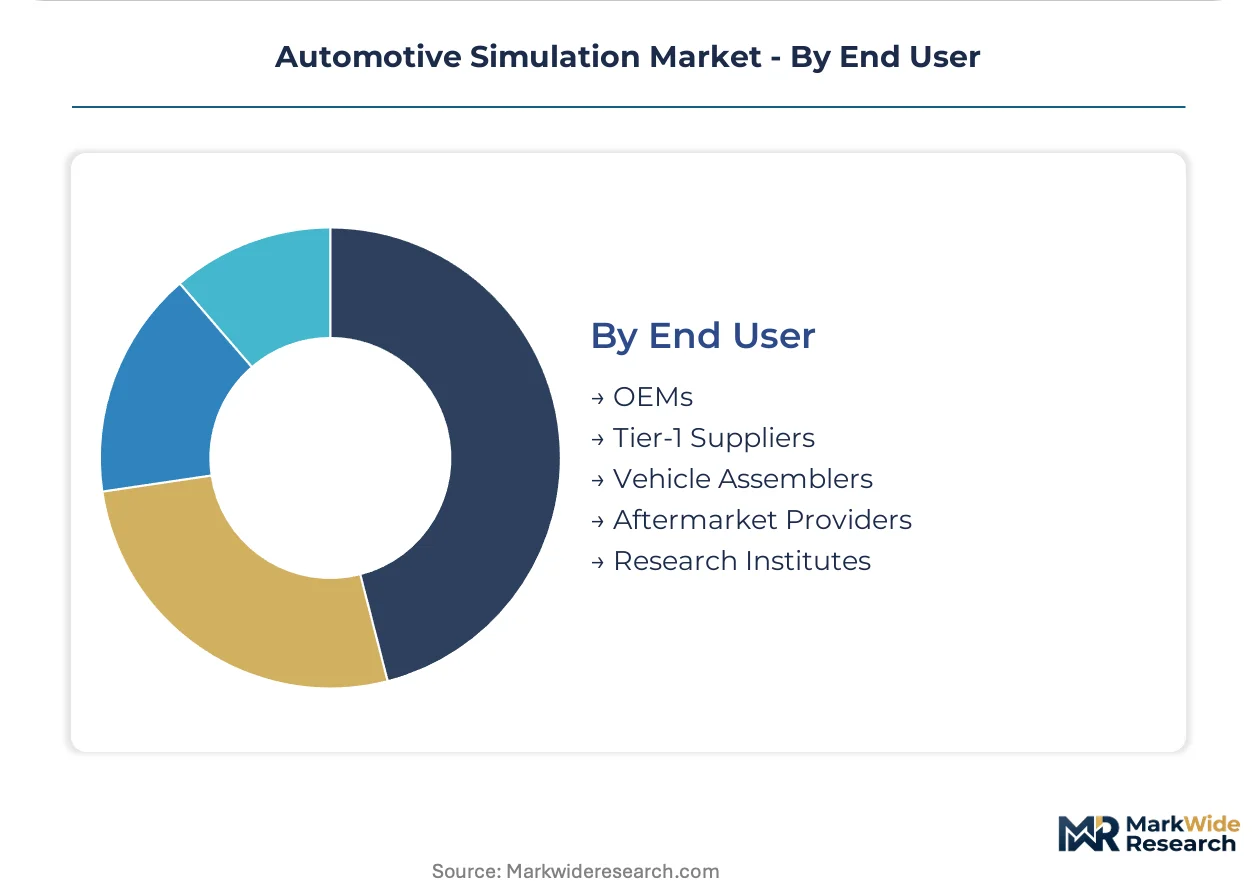
End User:
Scale and integration depth differentiate procurement patterns across the supply chain hierarchy.
- OEMs:Full-platform simulation estates spanning design through manufacturing execution. Volkswagen and BMW maintain captive engineering centers in Germany with preferred supplier frameworks covering multiphysics through hardware-in-the-loop validation.
- Tier-1 Suppliers:Subsystem-focused validation for brake, steering, and powertrain components delivered to multiple OEM platforms.
- Vehicle Assemblers:Integration-focused testing for final assembly quality and calibration verification.
- Aftermarket Providers:Diagnostic and retrofit validation for component replacement scenarios.
- Research Institutes:Academic and government-funded exploration of advanced simulation methodologies.
OEMs concentrate absolute spending; Tier-1 suppliers are gaining share fastest as platform standardization drives outsourced subsystem validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive simulation production concentrates in engineering-intensive economies while consumption spreads across manufacturing centers. Germany and the United States anchor software development and hardware-in-the-loop system production. China and India absorb growing volumes as domestic automotive engineering capabilities mature.
United States
NHTSA Federal Motor Vehicle Safety Standards and EPA emissions protocols drive hardware-in-the-loop procurement for powertrain and crashworthiness validation. Detroit-based engineering centers maintain captive simulation estates for pre-homologation documentation. Michigan and California clusters concentrate Tier-1 supplier validation facilities serving domestic OEM platforms.
Germany
KBA type-approval stringency accelerates real-time processor-in-the-loop adoption for embedded control verification. Stuttgart and Munich engineering clusters anchor multiphysics simulation procurement across Volkswagen and BMW captive centers. EU Green Deal lifecycle emissions mandates extend modeling requirements from vehicle use-phase into manufacturing energy consumption.
China
MIIT new energy vehicle regulations mandate digital validation for battery thermal management and motor control systems. Shanghai and Shenzhen engineering centers expand local simulation procurement as domestic OEMs advance SAE Level 3+ autonomy programs. Dual carbon goals intensify demand for manufacturing-phase energy modeling alongside vehicle performance simulation.
India
PLI scheme production-linked incentives attract OEM engineering centers to Pune and Chennai, creating localized demand for simulation services. BIS automotive standards adoption accelerates pre-homologation digital validation requirements. Tamil Nadu and Maharashtra clusters concentrate emerging Tier-1 supplier engineering operations requiring hardware-in-the-loop capabilities.
Japan
METI carbon neutrality roadmaps compel lifecycle emissions simulation extending from vehicle operation into supply chain energy accounting. Toyota and Honda engineering centers in Aichi Prefecture sustain multiphysics solver procurement for hybrid powertrain optimization. JIS standards alignment shapes software tool certification requirements for domestic market access.
Automotive Simulation Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the automotive simulation value chain. The market exhibits tiered concentration with integrated multiphysics platforms at the apex and specialized hardware-in-the-loop vendors occupying mid-tier positions. Three archetypes dominate: full-platform engineering software conglomerates, embedded control validation specialists, and sensor simulation pure-plays. Competitive dynamics center on strategic partnerships with cloud infrastructure providers and vertical integration into manufacturing execution systems.
Among German-based embedded control specialists, dSPACE GmbH exemplifies the hardware-in-the-loop archetype with concentrated presence in KBA type-approval workflows. Ansys and Siemens occupy positions spanning multiphysics through manufacturing execution, representing the integrated platform tier. Autodesk and Altair sit within the design-focused simulation segment with established presence in automotive styling and structural validation workflows.
| Leading Market Players |
|---|
| dSPACE GmbH |
| Autodesk |
| Ansys |
| Altair |
| PTC |
| Dassault Systèmes |
| ESI Group |
| Cognata |
| Siemens |
| Others |
Cost & Logistics Intelligence
GPU compute pricing indices cascade through automotive simulation supply chains, compressing margins for mid-tier suppliers while concentrating pricing power with cloud-native platform vendors serving German and US OEM engineering centers.
Pricing Analysis
Margin tightening in hardware-in-the-loop systems reflects GPU cluster procurement costs and specialized embedded control engineering wages. Three-tier pricing structure across premium, standard, and economy levels segments by solver fidelity and certification grade—ISO 26262-compliant platforms command sustained premiums. Cost-down pressure on software-in-the-loop modules accelerates because battery management system developers front-load algorithm development. Tier-1 suppliers exhibit highest price sensitivity; captive OEM engineering centers in Stuttgart and Munich demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai anchor hub-and-spoke fulfillment patterns for hardware-in-the-loop systems and multiphysics solver licenses. Manufacturing concentrates in Germany, the United States, and China. Supply chains draw from high-performance GPU semiconductors, real-time processor architectures, and physics solver software stacks. Single-source vulnerability in NVIDIA GPU supply creates structural exposure. Distribution runs through direct OEM master agreements and Tier-1 supplier framework contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive simulation capacity bottlenecks in computational fluid dynamics engineering and GPU cluster availability prop pricing power for vendors with captive talent pipelines and cloud infrastructure partnerships.
For Market Incumbents: Deploy solver-platform bundling to defend against sensor simulation pure-plays encroaching on autonomous vehicle validation budgets. Consolidate preferred supplier frameworks across German OEM engineering centers to lock out point-solution competitors. Deepen backward integration into real-time processor architectures to reduce NVIDIA GPU dependency. For New Entrants and Emerging Players: The premium-economy pricing gap in Indian PLI scheme engineering centers creates white-space entry for localized hardware-in-the-loop services. Target scenario-based testing platforms for SAE Level 3+ programs where ray tracing engine procurement cycles compress. Pursue cloud-native SaaS delivery to bypass on-premise infrastructure barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor embedded control validation specialists with KBA type-approval relationships in Germany. Long-term viability hinges on interoperability certification and manufacturing execution system integration depth. Watch NHTSA rulemaking on autonomous vehicle validation requirements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces toolchain fragmentation across Volkswagen and BMW captive engineering centers. |
| Battery Supply Agreement | Secures thermal runaway simulation capacity for EU Green Deal compliance timelines. |
| Software-Defined Vehicle Investment | Aligns hardware-in-the-loop procurement with over-the-air update validation workflows. |
| Geographic Manufacturing Footprint | Localizes simulation services for India PLI scheme engineering centers in Pune. |
| Charging Infrastructure Partnership | Extends powertrain optimization simulation into grid-integration validation scenarios. |
Research Approach
SEC 10-K filings, OEM procurement documentation, and hyperscaler capex disclosures formed the secondary backbone of this analysis. Primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, hardware-in-the-loop integration specialists, and automotive regulatory affairs directors validated demand assumptions. Bottom-up and top-down triangulation cross-checked segment sizing against vehicle production databases and IHS Markit registration data.
Historical trendline analysis established baseline penetration rates for hardware-in-the-loop and software-in-the-loop technologies across the projection horizon. The analytical framework modeled segmentation across propulsion architecture, validation application, end-user tier, and regional production cluster. CAGRs derived from slope-adjusted growth rate analysis incorporating NHTSA regulatory timeline assumptions and EU Green Deal implementation pacing.
Inputs from OEM procurement teams and Tier-1 engineering centers were available through the study window; gaps in autonomous vehicle program disclosure introduce uncertainty bands around sensor simulation demand forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Railway Maintenance Machinery Market
Automotive Testing and Simulation
Torque Testers Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market