
 Marine AIS Monitoring System Market | 2026-2036
Marine AIS Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine AIS Monitoring System Market Insights
The marine AIS monitoring system market is restructuring around a widening capability gap between defense-grade platforms and commercial vessel mandates. Kongsberg Gruppen ASA leverages its sonar and maritime domain heritage to anchor premium coastal surveillance contracts. Furuno Electric Co., Ltd. competes through dense distribution across Japanese and Southeast Asian fishing fleets. Saab AB differentiates via integrated naval C4ISR architectures that embed AIS as one sensor layer among many.
A marine AIS monitoring system combines automated transponder networks, VHF data link protocols, and differential GNSS positioning to broadcast vessel identity, course, speed, and navigational status to shore stations and nearby ships. Terrestrial AIS shore stations and satellite AIS constellations form complementary coverage layers, with satellite AIS addressing high seas gaps beyond VHF radio horizon. Class A AIS transponders dominate commercial shipping installations due to SOLAS carriage mandates, while harbor authorities and maritime security agencies drive demand for base stations and repeaters that build coastal surveillance grids. Vessel traffic management applications absorb the largest share of institutional procurement budgets, though cargo tracking integrations with logistics platforms represent the fastest-expanding use case as supply chain visibility requirements intensify.
The International Maritime Organization's SOLAS Convention Chapter V mandates AIS carriage for vessels exceeding 300 gross tons on international voyages, while the EU Maritime Safety Agency enforces regional monitoring standards through SafeSeaNet. The US Coast Guard administers Nationwide Automatic Identification System compliance for domestic waterways under FCC equipment authorization rules. Stakeholders must weigh satellite AIS constellation reliability against terrestrial network densification as Arctic shipping routes extend operational seasons and challenge existing coverage models.
Market Dynamics
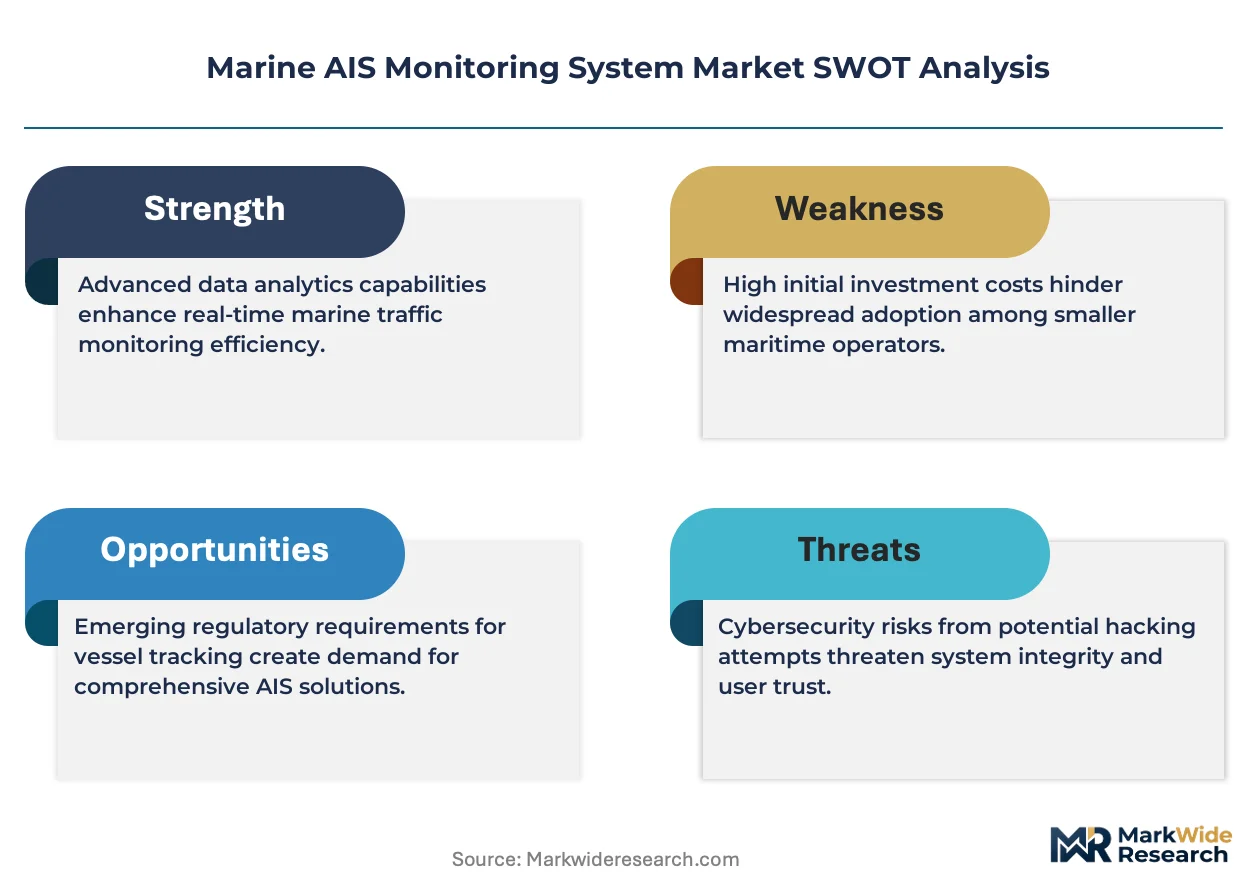
The marine AIS monitoring system market is restructuring around a widening capability gap between defense-grade platforms and commercial vessel mandates. Satellite AIS constellation expansion and terrestrial VHF network densification are creating overlapping coverage models that force procurement choices between redundancy and cost optimization.
Growth Catalysts
- IMO SOLAS Chapter V carriage mandates:Mandatory AIS installation for vessels exceeding 300 gross tons on international voyages drives equipment refresh cycles across commercial fleets.
- Arctic shipping route extension:Longer operational seasons along Northern Sea Route corridors expose coverage gaps that satellite AIS constellations address.
- Port authority modernization programs:Vessel traffic management system upgrades in Rotterdam and Singapore accelerate base station and repeater deployment.
Market Restraints
- Terrestrial VHF radio horizon limitations:Coastal base stations cannot track vessels beyond approximately 40 nautical miles, creating persistent high-seas monitoring blind spots.
- Dual-network infrastructure redundancy costs:Harbor authorities face capital duplication when maintaining parallel terrestrial and satellite AIS reception capabilities.
- GNSS signal vulnerability:AIS positioning accuracy depends on differential GPS corrections that degrade during solar flare events or intentional jamming.
Strategic Opportunities
- Cargo tracking-logistics platform integration:Supply chain visibility requirements from shippers like Maersk and MSC create demand for AIS data API services.
- Fishing fleet regulatory compliance:EU Fisheries Control Agency mandates for vessel monitoring systems in Atlantic and Mediterranean waters expand addressable market.
- Machine learning-anomaly detection convergence:Pattern recognition algorithms applied to AIS track histories enable predictive maintenance and collision risk scoring for insurers.
Industry Challenges
- Maritime RF engineer scarcity:Specialized expertise in VHF propagation modeling and coastal antenna siting concentrates among aging workforce cohorts in Norway and Japan.
- Multi-source data fusion complexity:Integrating AIS feeds with radar, electro-optical, and sonar tracks requires custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine AIS Monitoring System Market |
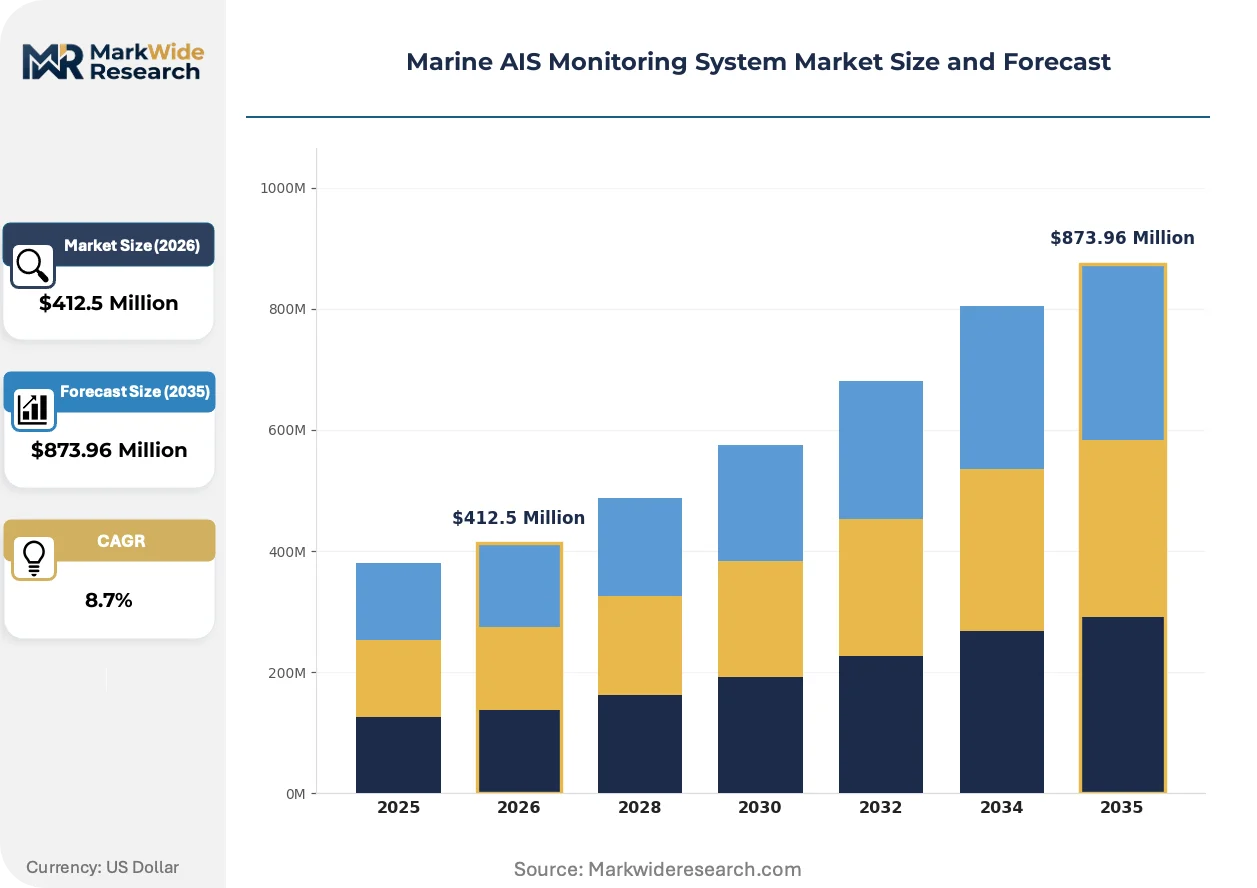
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transponders, Class A AIS, Class B AIS, Base Stations, Repeaters Technology: Satellite AIS, Terrestrial AIS, VHF Data Link, Differential GPS, GNSS Integration Application: Vessel Traffic Management, Search and Rescue, Cargo Tracking, Navigation Safety, Coastal Surveillance End User: Harbor Authorities, Maritime Security Agencies, Shipping Companies, Offshore Operators |
| Companies Covered | Saab AB, ORBCOMM Inc, Furuno Electric Co., Ltd., Kongsberg Gruppen ASA, L3Harris Technologies, Inc., SRT Marine Systems plc, Garmin Ltd., Thales Group, ExactEarth Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine AIS Monitoring System Market Trends and Innovations
Sensor fusion architectures and AI-driven analytics are compressing the value chain between raw AIS data collection and actionable maritime intelligence. Three developments are reshaping competitive positioning and procurement patterns.
Satellite AIS receiver payloads on low-earth orbit constellations are integrating with synthetic aperture radar for all-weather vessel detection. Spire Global and Kleos Space are deploying hybrid RF-SAR satellites that correlate AIS broadcasts with radar imagery when transponders are disabled or malfunctioning. This convergence is integrating dark vessel tracking capabilities into previously commodity data services, compressing margins for pure-play AIS aggregators.
The EU Maritime Safety Agency's SafeSeaNet evolution toward real-time data exchange mandates is forcing equipment certification updates. Vessel traffic service operators must upgrade shore station software to handle enhanced message types 27 (long-range AIS) and 6 (binary addressed). Mediterranean port authorities in Italy and Greece are prioritizing compliance investments ahead of North Sea counterparts, creating asynchronous procurement waves across European coastal zones.
Charter operators and commodity traders are consolidating AIS data purchasing through specialized maritime intelligence platforms rather than direct satellite operator contracts. This intermediation concentrates negotiating leverage with data aggregators like MarineTraffic and VesselFinder, compressing pricing power for raw feed providers. The shift is most visible in Singapore and London trading desks, where freight derivatives analysts require normalized historical track databases rather than real-time streaming access.
Marine AIS Monitoring System Market Segmentation
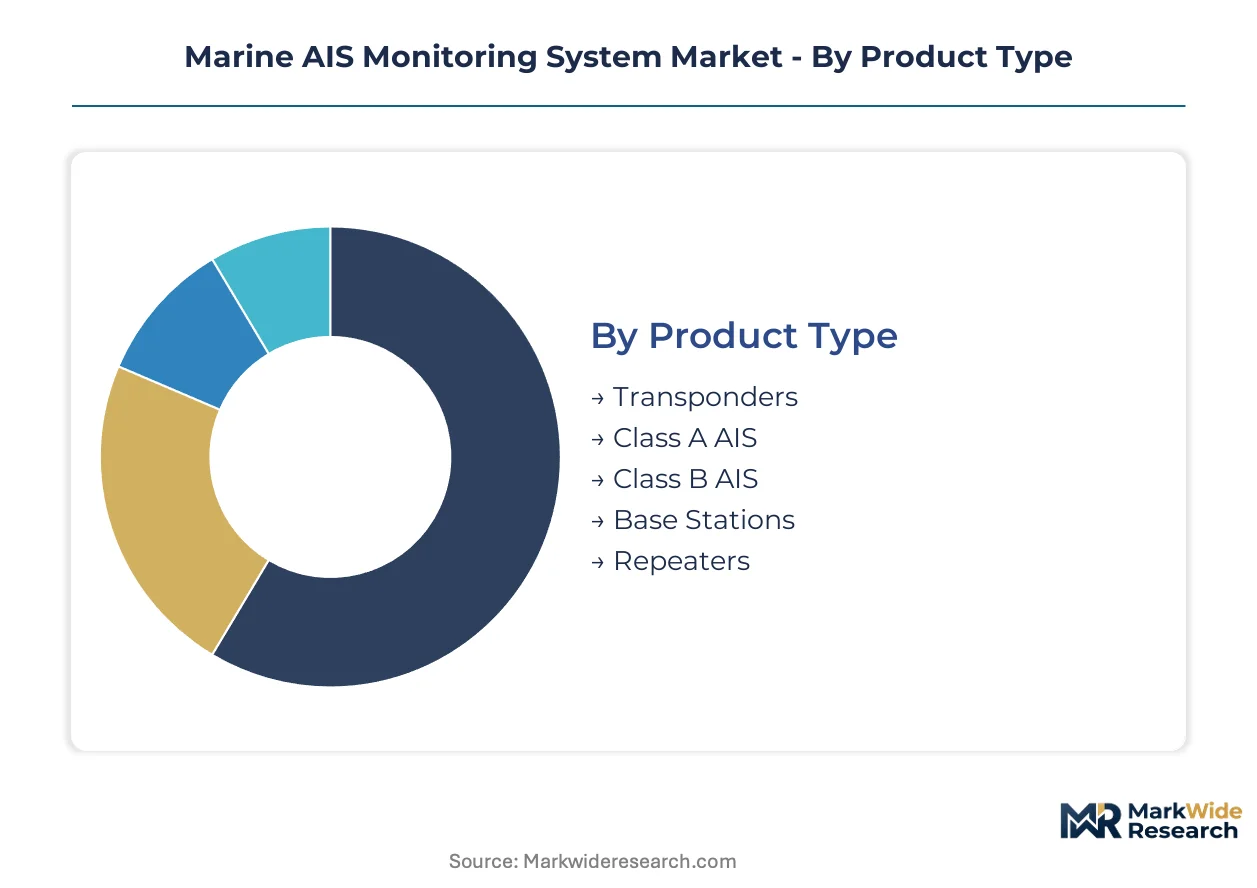
Marine AIS monitoring systems fragment across four critical dimensions that determine procurement priorities and margin structures. Product type splits between mandated carriage equipment and discretionary coastal infrastructure. Technology choices force trade-offs between coverage reach and capital intensity.
Product Type:
Volume concentrates in SOLAS-mandated carriage equipment, while premium margins attach to coastal surveillance infrastructure requiring site-specific engineering.
- Transponders:Self-contained broadcast units integrating VHF transmitter, GPS receiver, and microcontroller for automated vessel identification. SOLAS Chapter V mandates drive replacement cycles across commercial fleets operating from Rotterdam to Singapore. Harbor authorities in Busan and Shanghai absorb the highest procurement volumes for new-build installations.
- Class A AIS:High-power transponders transmitting at 12.5 watts with update rates under 10 seconds for vessels exceeding 300 gross tons. Demand clusters around container fleets and tanker operators navigating the Malacca Strait and English Channel corridors. IMO carriage requirements force equipment refresh every 5-7 years across international shipping.
- Class B AIS:Lower-power units at 2 watts designed for recreational vessels and fishing fleets under SOLAS thresholds. Japanese and Norwegian coastal authorities subsidize installations to reduce collision risk in congested archipelago waters.
- Base Stations:Shore-mounted VHF receivers building terrestrial coverage grids for vessel traffic services. Port authorities in Hamburg and Los Angeles prioritize densification to eliminate shadow zones behind harbor infrastructure.
- Repeaters:Relay stations extending VHF radio horizon beyond 40-nautical-mile limits. Mediterranean coastal surveillance programs in Italy and Greece deploy chains across island chains where terrain blocks direct shore reception.
Today's leader: Transponders. Tomorrow's challenger: Base Stations.
Technology:
Application context determines whether reach or latency commands procurement decisions, with Arctic operators and coastal traffic managers diverging sharply.
- Satellite AIS:Space-based receivers on low-earth orbit constellations capturing broadcasts beyond VHF radio horizon. Arctic route operators along the Northern Sea Route depend on satellite coverage where terrestrial infrastructure is absent. Spire Global and Kleos Space compete on revisit frequency and hybrid SAR correlation.
- Terrestrial AIS:Coastal VHF receiver networks providing sub-second latency for real-time traffic management. Singapore's port authority operates the densest shore station grid globally, with 50+ receivers covering approaches to the world's busiest container port.
- VHF Data Link:Marine mobile service spectrum at 161.975 and 162.025 MHz carrying AIS messages 1, 2, 3, 5, 18, 19, 24, and 27. US Coast Guard FCC equipment authorization rules govern transmitter certification for domestic waterways.
- Differential GPS:Correction signals improving AIS position accuracy to sub-10-meter precision. Solar flare vulnerability and intentional jamming in Eastern Mediterranean shipping lanes expose operational risk.
- GNSS Integration:Multi-constellation receivers combining GPS, GLONASS, Galileo, and BeiDou for resilience. EU Maritime Safety Agency SafeSeaNet mandates dual-constellation capability for enhanced message type 27 compliance.
Terrestrial AIS anchors current procurement budgets. Satellite AIS gains share fastest where ice retreat extends navigation seasons.
Application:
Institutional buyers dominate vessel traffic management, while cargo tracking attracts new commercial spend from logistics platforms seeking supply chain visibility.
- Vessel Traffic Management:Shore-based coordination of vessel movements through congested waterways and port approaches. Rotterdam's port authority invested in AI-enhanced traffic prediction layering AIS with radar and CCTV fusion.
- Search and Rescue:Distress alert correlation with AIS identity for rapid resource dispatch. Norwegian Joint Rescue Coordination Centres integrate AIS with 406 MHz beacon registrations for North Sea coverage.
- Cargo Tracking:Container-level visibility through vessel AIS correlation with terminal operating systems. Maersk and MSC contract MarineTraffic and VesselFinder for normalized historical track databases supporting freight derivatives analysis.
- Navigation Safety:Collision avoidance through reciprocal vessel awareness within VHF range. IMO performance standards mandate minimum detection ranges for Class A installations.
- Coastal Surveillance:Maritime domain awareness for security agencies monitoring territorial waters. Saab AB embeds AIS within integrated C4ISR architectures for Swedish and Finnish naval commands.
Vessel Traffic Management commands institutional budgets. Cargo Tracking expands most quickly as supply chain digitization accelerates.
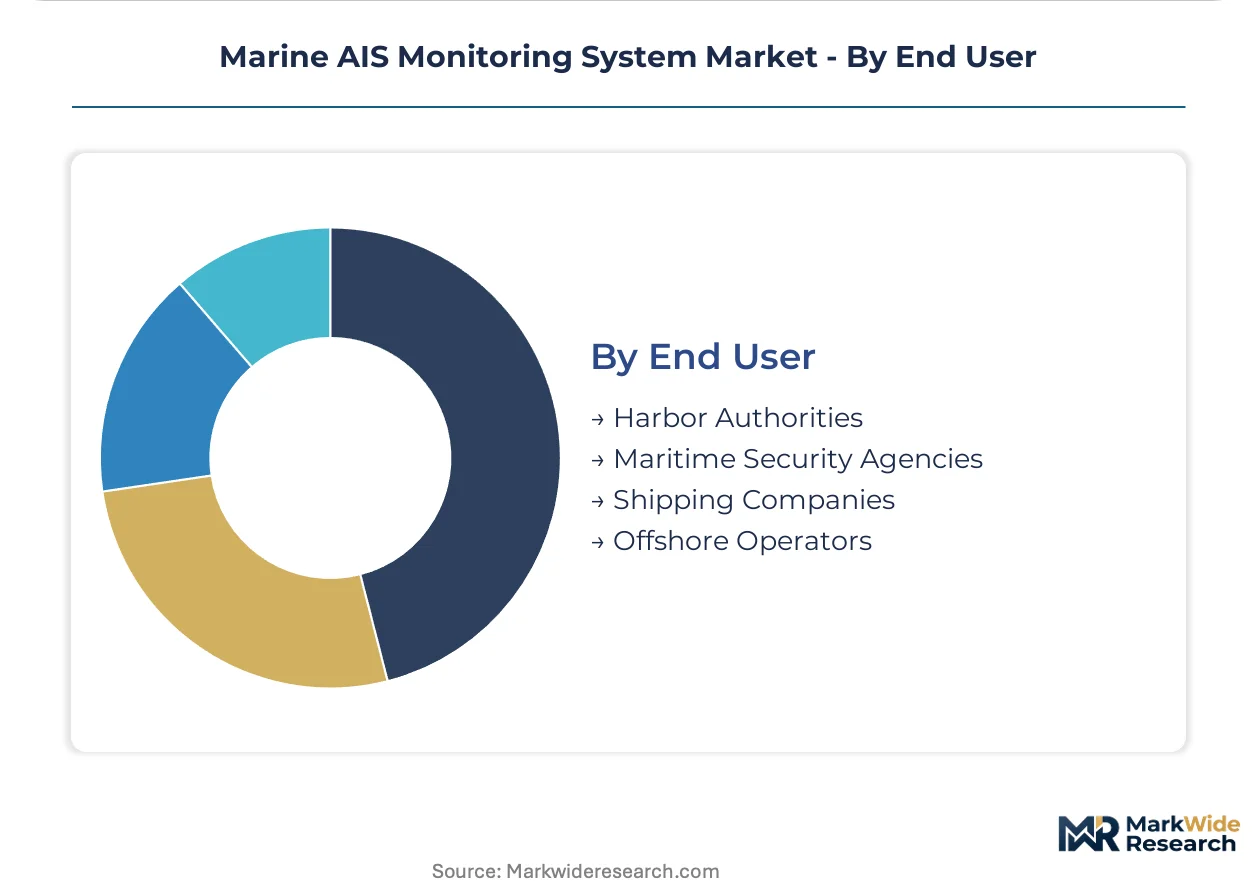
End User:
Procurement authority separates between regulatory compliance spend and discretionary security investment, with very different sales cycles and technical specifications.
- Harbor Authorities:Port operators managing vessel traffic services and berth allocation. Singapore, Rotterdam, and Shanghai anchor global demand for base station densification and software upgrades.
- Maritime Security Agencies:Naval and coast guard organizations requiring dark vessel detection and anomaly detection. EU Fisheries Control Agency mandates drive vessel monitoring system installations across Atlantic and Mediterranean fishing fleets.
- Shipping Companies:Commercial fleet operators satisfying SOLAS carriage requirements and optimizing voyage economics. Container lines consolidate AIS data purchasing through specialized maritime intelligence platforms rather than direct satellite contracts.
- Offshore Operators:Oil, gas, and wind farm developers protecting assets and coordinating supply vessels. North Sea offshore wind construction zones require AIS-SAR fusion for all-weather traffic monitoring where radar clutter from turbine installations degrades conventional detection.
Harbor Authorities anchor equipment procurement volumes. Maritime Security Agencies represent the steepest expansion trajectory as dark vessel tracking requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore outpaces Rotterdam in base station density per square nautical mile, while Norway's Arctic corridor investments diverge sharply from Mediterranean compliance-focused procurement patterns.
United States
The US Coast Guard administers Nationwide Automatic Identification System compliance through FCC equipment authorization rules governing domestic waterways. Port authorities in Los Angeles and Long Beach prioritize base station densification to eliminate shadow zones behind harbor infrastructure. Offshore wind construction zones along the Atlantic seaboard drive demand for AIS-SAR fusion capabilities.
Norway
Arctic route operators along the Northern Sea Route depend on satellite AIS coverage where terrestrial infrastructure remains absent. Norwegian Joint Rescue Coordination Centres integrate AIS with 406 MHz beacon registrations for North Sea search and rescue coverage. Kongsberg Gruppen ASA leverages its sonar heritage to anchor premium coastal surveillance contracts along the country's fjord-indented coastline.
Singapore
The Maritime and Port Authority operates the densest shore station grid globally, with 50-plus receivers covering approaches to the world's busiest container port. Vessel traffic management system upgrades accelerate procurement of base stations and repeaters. Trading desks in the city-state consolidate AIS data purchasing through specialized maritime intelligence platforms rather than direct satellite operator contracts.
Germany
EU Maritime Safety Agency SafeSeaNet mandates drive equipment certification updates across North Sea and Baltic port authorities. The country's national maritime regulator enforces real-time data exchange standards requiring shore station software upgrades for enhanced message type 27 handling. Hamburg's port authority leads European investment in AI-enhanced traffic prediction layering AIS with radar fusion.
Japan
Furuno Electric Co., Ltd. competes through dense distribution across Japanese and Southeast Asian fishing fleets. The country's coastal authorities subsidize Class B AIS installations to reduce collision risk in congested archipelago waters. METI standards govern differential GPS correction signal resilience requirements for domestic vessel traffic services.
Marine AIS Monitoring System Market Competitive Landscape
Top-tier vendors anchor defense-grade coastal surveillance contracts, while mid-tier specialists compete on commercial fleet carriage equipment refresh cycles. The vendor base stratifies across integrated naval C4ISR architects, satellite constellation operators, and dense distribution networks serving fishing and recreational fleets. Two strategic archetypes dominate: heritage maritime technology conglomerates with sonar and naval systems lineage, and pure-play satellite data aggregators building normalized historical track databases. Competitive moves concentrate on hybrid RF-SAR payload integration and API service intermediation that compresses pricing power for raw feed providers.
Within the defense-grade tier, Saab AB and Kongsberg Gruppen ASA exemplify integrated C4ISR architectures that embed AIS as one sensor layer among radar, electro-optical, and sonar tracks. Furuno Electric Co., Ltd. occupies a position representing dense coastal distribution networks serving archipelago fisheries and recreational vessel mandates. These three anchors illustrate the widening capability gap between premium coastal surveillance platforms and commoditized carriage equipment.
| Leading Market Players |
|---|
| Saab AB |
| ORBCOMM Inc |
| Furuno Electric Co., Ltd. |
| Kongsberg Gruppen ASA |
| L3Harris Technologies, Inc. |
| SRT Marine Systems plc |
| Garmin Ltd. |
| Thales Group |
| ExactEarth Ltd |
| Others |
Pricing and Supply Chain Analysis
Specialized maritime RF engineering talent concentrates in aging workforce cohorts across Norway and Japan, creating labor-cost differentials that widen pricing spreads between premium coastal surveillance platforms and commoditized carriage equipment. VHF propagation modeling expertise and coastal antenna siting capabilities command substantial wage premiums, compressing margins for mid-tier vendors while defense-grade integrators pass through these costs to government buyers.
Pricing Analysis
Bundled data services versus unbundled raw feed access defines the dominant pricing split across marine AIS markets. Subscription-tiered SaaS models anchor cargo tracking and logistics platform integrations, while project-based contracting governs coastal surveillance infrastructure deployments. Price differentiation rests on certification grade—IMO SOLAS Chapter V compliance versus EU Maritime Safety Agency SafeSeaNet enhanced message handling—and geographic delivery cost differentials for remote Arctic installations. Pricing pressure stems from data aggregator intermediation concentrating negotiating leverage with platforms like MarineTraffic and VesselFinder. Harbor authorities exhibit highest price sensitivity due to budget-constrained base station densification programs, while maritime security agencies demonstrate lowest sensitivity given mission-critical dark vessel tracking requirements.
Supply Chain Analysis
Certification and qualification gating through FCC equipment authorization rules, EU Maritime Safety Agency mandates, and IMO performance standards filters component suppliers and system integrators. Manufacturing concentrates in Japan, Norway, and Sweden, with Furuno Electric leveraging dense domestic distribution and Kongsberg Gruppen anchoring premium coastal surveillance production. Raw material dependencies include VHF transmitter modules, multi-constellation GNSS receivers, and marine-grade enclosures rated for salt corrosion. Single-source vulnerability concentrates in specialized AIS base station processors qualified for SafeSeaNet real-time data exchange. Distribution runs through direct port authority procurement for infrastructure, maritime electronics distributors for fleet carriage equipment, and specialized data aggregators for API-accessible cargo tracking services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine AIS markets offer margin expansion through satellite-terrestrial hybrid payload integration and premium-tier coastal surveillance upgrades. Cost compression in commoditized transponder manufacturing is offset by AI-enhanced traffic prediction software attach rates.
For Market Incumbents: Anchor defense-grade coastal surveillance contracts through integrated C4ISR architectures that embed AIS within multi-sensor fusion platforms. Deepen backward integration into VHF transmitter module production to offset component cost volatility. Invest in machine learning anomaly detection capabilities to differentiate against pure-play data aggregators threatening software margin structures. For New Entrants and Emerging Players: Launch via API-first cargo tracking services targeting logistics platforms seeking supply chain visibility without direct satellite operator contracts. Arctic route operators along the Northern Sea Route represent the most penetrable geography given satellite coverage gaps and absence of terrestrial infrastructure. Target EU Fisheries Control Agency vessel monitoring system mandates across Atlantic and Mediterranean fishing fleets as a regulatory-driven entry wedge. For Investors and Strategic Acquirers: Satellite constellation operators with hybrid RF-SAR payload capabilities are the most active acquirer in this space, seeking to integrate dark vessel tracking and all-weather detection. Long-term viability centers on data fusion middleware and predictive analytics layers rather than raw feed commoditization. Monitor Arctic shipping season extension patterns as the critical inflection indicator for satellite AIS capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid RF-SAR Payload Integration | Spire Global and Kleos Space correlate AIS broadcasts with radar imagery for dark vessel detection. |
| AI-Enhanced Traffic Prediction | Rotterdam's port authority layers AIS with radar and CCTV fusion for congestion forecasting. |
| API Service Intermediation | MarineTraffic consolidates negotiating leverage, compressing pricing power for raw feed providers. |
| SafeSeaNet Compliance Upgrades | Mediterranean port authorities prioritize enhanced message type 27 handling ahead of North Sea counterparts. |
| Arctic Satellite Constellation Expansion | Longer Northern Sea Route operational seasons expose coverage gaps demanding space-based reception. |
Research Methodology
Coverage spans North Sea, Mediterranean, and East Asian shipping corridors, with primary inputs from each maritime regulatory cluster. The analysis combines primary interviews with vessel traffic service operators, port authority procurement managers, maritime electronics distributors, and satellite data platform engineers with secondary validation through IMO SOLAS Convention documentation, EU Maritime Safety Agency SafeSeaNet technical specifications, US Coast Guard FCC equipment authorization filings, and customs trade data for AIS transponder imports. Bottom-up equipment installation counts triangulate against top-down maritime fleet registry analysis.
Granularity-level modeling disaggregates volume and value across product type, technology choice, application context, and end-user procurement authority throughout the projection horizon. Segmentation dimensions include SOLAS mandate tier, satellite versus terrestrial reception architecture, vessel traffic management versus cargo tracking use case, and harbor authority versus maritime security agency buyer type. CAGRs derive from equipment refresh cycle analysis, port modernization program timelines, and Arctic route extension scenarios. Forecast inputs incorporate differential GPS correction signal resilience requirements and multi-constellation GNSS receiver adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Arctic ice retreat or intensified Eastern Mediterranean GNSS jamming incidents. Model assumptions reflect documented regulatory enforcement patterns, satellite constellation deployment schedules, and port authority capital expenditure commitments. A model refresh is warranted upon material change in IMO SOLAS Chapter V carriage threshold revisions or EU Maritime Safety Agency real-time data exchange mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Military Marine Engine Market
Marine
Marine Electronics Market
Marine
Global Foldable Inflatable Boats Market
Marine
Marine Growth Removal Tool Market
Marine
Ship/Boat Keel Market
Marine
Marine Propeller Market
Marine
Marine Gas Oil Market
Marine
Marine Beacon Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Passenger Vessel Propeller Market
Marine
North America Naval Vessels Market
Marine
Marine Stabilizers Market
Marine
Tele-Operated Marine Drone Market
Marine
Boat Control Lever Market
Marine
North Sea Offshore Support Vessels Market
Marine
Electric Ship Market