
 Autonomous Vehicle Market | 2026-2036
Autonomous Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicle Market Intelligence
The UNECE WP.29 regulation on Automated Lane Keeping Systems is recalibrating the cost-of-entry calculus for Level 3 vehicle deployment. Waymo leverages its extensive real-world and simulated driving data to refine its AI models for ride-hailing services. In parallel, Baidu Apollo positions its open-source platform to capture a share of the Chinese market. Aptiv specializes in providing the underlying sensor and software architecture to multiple automakers.
An autonomous vehicle operates without human intervention by using an integrated suite of sensors and software to perceive its environment and navigate. Its core function relies on a 'sense-plan-act' cycle, processing data from Lidar, radar, and cameras to make real-time driving decisions. While Level 2 systems are now common in new passenger cars, development focus is on perfecting Level 4 for fleet operators. In terms of hardware, Lidar technology remains a key differentiator for high-level autonomy, commanding significant investment.
The US National Highway Traffic Safety Administration (NHTSA) provides guidance through its Automated Driving Systems 2.0 framework. The EU's upcoming regulations on vehicle type-approval set stringent safety requirements. China's Ministry of Industry and Information Technology (MIIT) directs national standards for intelligent connected vehicles, shaping market access. Stakeholders must navigate this fragmented regulatory landscape to achieve commercial scale.
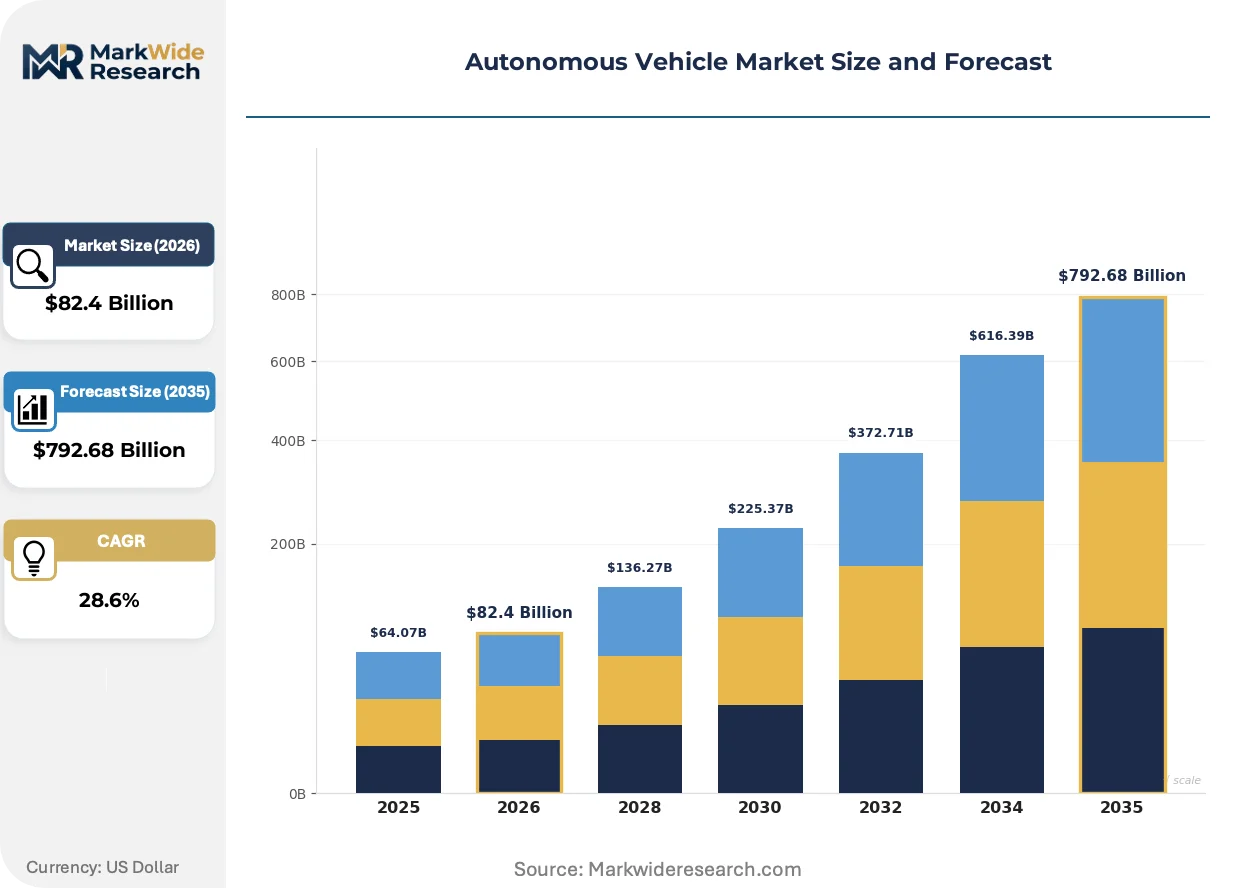
Market Dynamics
The pursuit of Level 4 autonomy for commercial fleets in logistics and ride-hailing is the central force shaping the market. This focus stems from the strong economic case for operational efficiency, supported by emerging regulatory frameworks from bodies like NHTSA and MIIT.
Growth Catalysts
- Regulatory Standardization:The UNECE WP.29 regulation on Automated Lane Keeping Systems provides a clear technical and approval framework, encouraging OEM investment into Level 3 systems for passenger vehicles across signatory nations.
- Sensor Fusion Maturity:Advancements in combining data from Lidar, radar, and high-resolution cameras enhance system reliability in adverse weather, expanding the operational design domain for autonomous trucks and shuttles.
- Logistics Sector Demand:The global logistics industry is driving development of autonomous long-haul trucks to mitigate driver shortages, reduce fuel consumption through optimized driving, and increase asset utilization with near-continuous operation.
Market Restraints
- Component Cost Structure:The high unit cost of automotive-grade Lidar sensors and the powerful centralized computing hardware required for Level 4 autonomy remains a primary barrier to mass-market passenger vehicle adoption.
- Safety Validation Complexity:Verifying and validating the performance of AI-based driving software across a near-infinite number of real-world edge cases presents a significant technical and computational hurdle for developers.
- Regulatory Fragmentation:Inconsistent and evolving state-level regulations, particularly within the United States, create legal uncertainty and operational complexity for deploying commercial autonomous services across jurisdictional lines.
Strategic Opportunities
- Off-Highway Applications:Specialized autonomous systems for vehicles in contained environments like mining, agriculture, and port logistics offer significant opportunities due to clear ROI, controlled operating conditions, and fewer regulatory obstacles.
- V2X Integration:The convergence of 5G connectivity and Vehicle-to-Everything (V2X) communication with onboard sensor suites enables cooperative perception, which can drastically improve safety and efficiency in dense urban areas.
- Simulation-as-a-Service:Providing sophisticated virtual testing and validation platforms to smaller developers and Tier-2 suppliers represents a growing service-based opportunity, lowering the barrier to entry for software development.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of software and systems engineers with expertise in both machine learning and functional safety standards like ISO 26262 constrains development capacity across the industry.
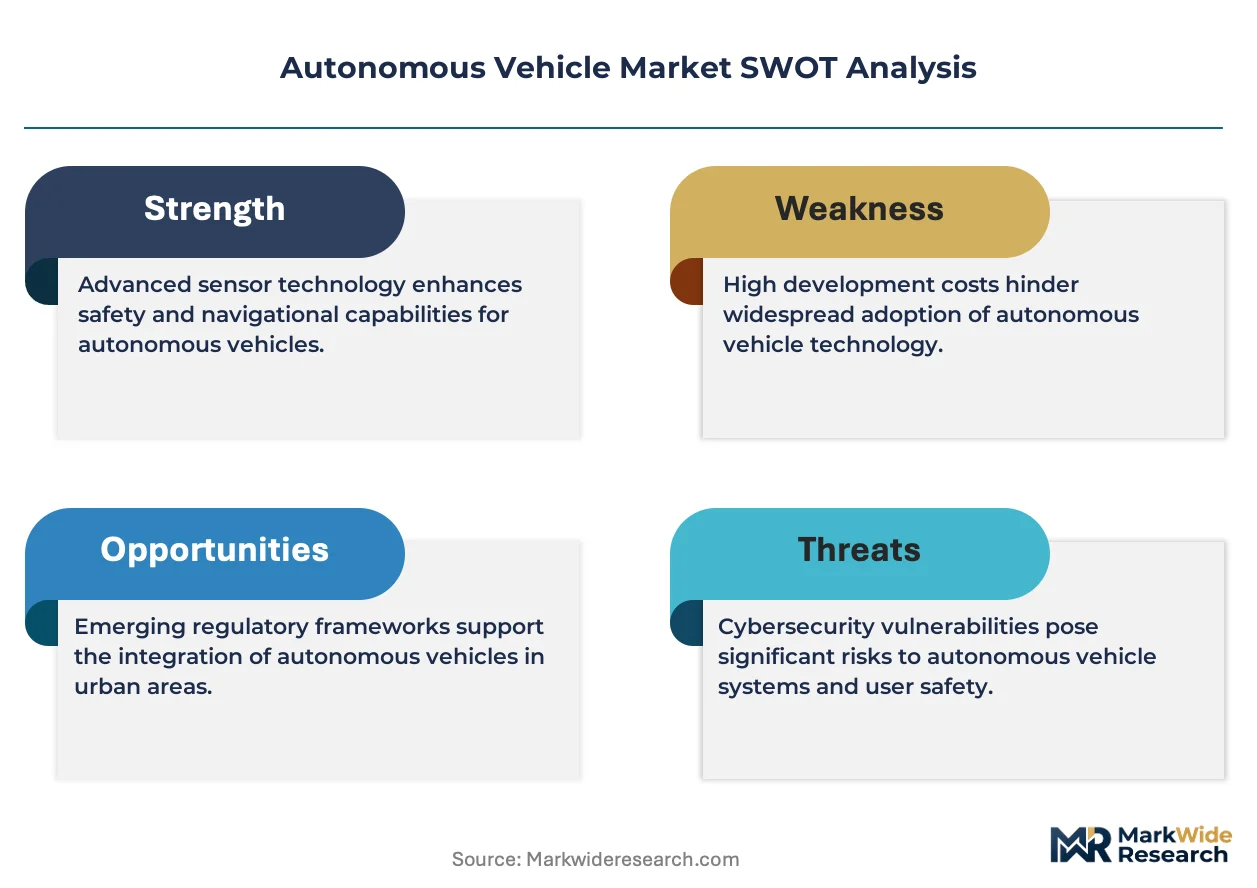
- Cybersecurity Vulnerabilities:Ensuring the security of the entire vehicle's electronic architecture against malicious attacks is a critical operational challenge, demanding robust security-by-design principles and secure over-the-air update mechanisms.
- Public Trust and Acceptance:Building public confidence in autonomous technology is a major hurdle that depends on transparent safety reporting and demonstrating reliable performance, directly impacting the pace of regulatory approval and adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicle Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $792.68 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Level of Autonomy: Level 1, Level 2, Level 3, Level 4, Level 5 Vehicle Type: Passenger Cars, Commercial Trucks, Delivery Drones, Specialty Robots, Personal Mobility Devices Sensor Technology: Lidar, Radar, Ultrasonic, Cameras, Infrared Sensors End User Segment: Fleet Operators, Public Transit Authorities, Logistics Providers, Ride-Hailing Services |
| Companies Covered | Waymo, Tesla, Cruise, Aurora Innovation, Mobileye, Zoox, Aptiv, Nuro, Baidu Apollo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicle Market Strategic Shifts & Innovations
Innovation is pivoting from hardware-centric design to software-defined vehicle architectures supported by massive data ecosystems. This transition prioritizes continuous AI model refinement and large-scale simulation, enabling faster development cycles than hardware-only upgrades.
Centralized computing platforms consolidate processing from multiple sensors and domains into a single, powerful system-on-a-chip. Automakers and Tier-1 suppliers are rapidly adopting these architectures to reduce complexity, weight, and cost in new vehicle electrical designs. This architectural shift is integrating previously siloed functions like infotainment and ADAS, enabling more complex features via over-the-air updates.
The UNECE WP.29 regulation on Cybersecurity (UN R155) mandates a certified management system for new vehicle type approvals. This forces automakers to implement robust processes for managing cyber risk throughout the vehicle lifecycle. Vehicle manufacturers in Europe, Japan, and South Korea are most affected, redesigning software development and supply chain security to ensure compliance.
Fleet operators increasingly purchase autonomous driving capability as a recurring subscription service, avoiding a one-time hardware and software purchase. This "AV-as-a-Service" model converts a large capital expenditure into a predictable operating expense for logistics and ride-hailing companies. The model is most prominent in commercial trucking and robotaxi segments in the United States and China.
Autonomous Vehicle Market Segmentation
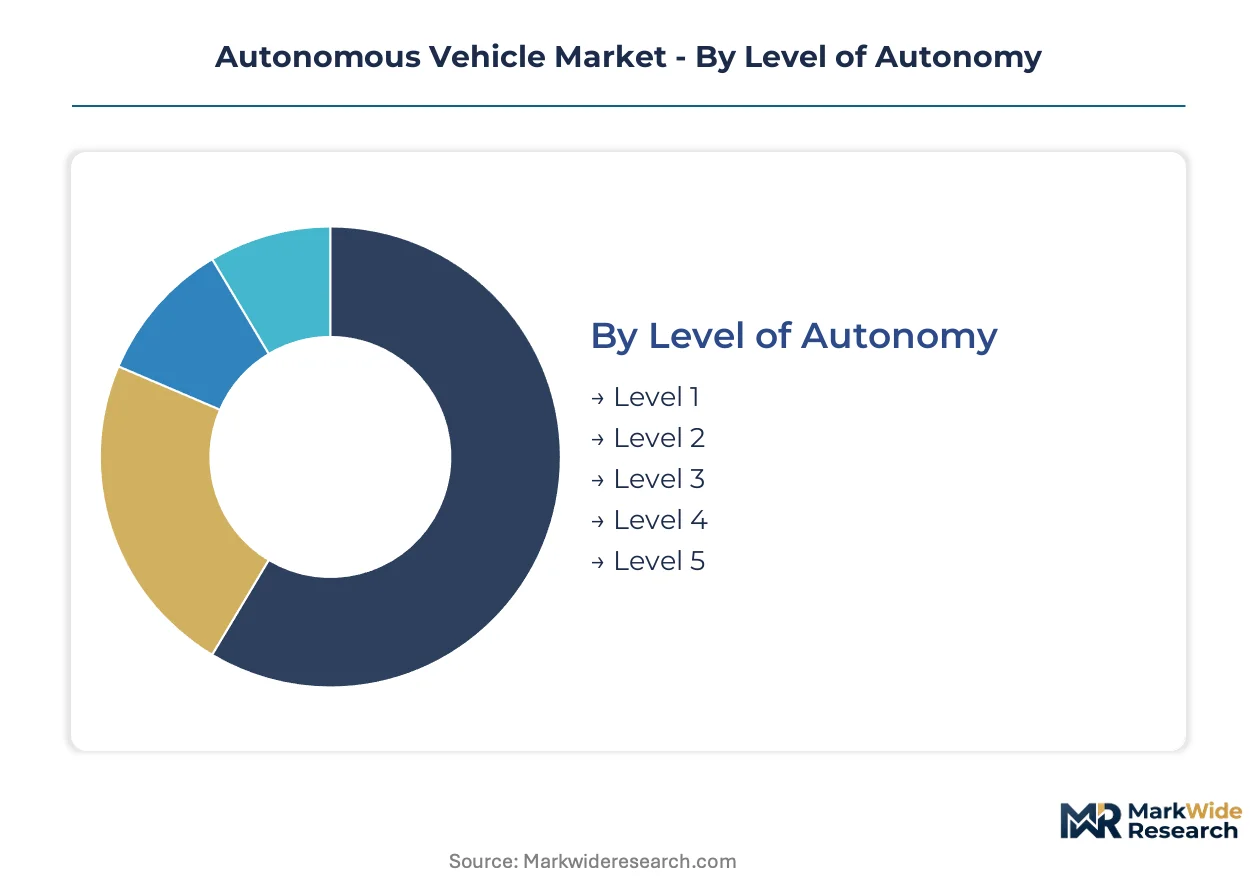
Autonomous vehicles require precise classification to understand market dynamics and technology adoption. Analyzing distinct market segments reveals varying investment priorities and regulatory impacts. This granular view helps stakeholders align development with specific operational needs and commercial opportunities.
Level of Autonomy:
The capital intensity of autonomous vehicle development scales significantly with higher levels of autonomy, reflecting increasing software complexity and validation requirements.
- Level 4:These systems operate autonomously under specific operational design domains, requiring no human intervention. Demand concentrates in commercial fleets for ride-hailing and logistics, driven by the economic case for driverless operations in defined areas.
- Level 3:Vehicles with Level 3 autonomy can perform dynamic driving tasks under certain conditions but require human takeover when prompted. Regulatory frameworks like UNECE WP.29 encourage OEM investment for passenger vehicles in Europe and Asia.
- Level 1:Basic driver assistance features, such as adaptive cruise control or lane keeping assistance, enhance safety and convenience in passenger cars.
- Level 2:Partial automation where the vehicle controls both steering and acceleration/deceleration, but the human driver must monitor the environment.
- Level 5:Full automation under all driving conditions, equivalent to human driving capability, represents the long-term aspirational goal for autonomous systems.
Most installed capacity flows through Level 2 systems. Expansion is steepest in Level 4 deployments.
Vehicle Type:
Different vehicle types dictate distinct operational environments and regulatory pathways for autonomous technology integration.
- Commercial Trucks:These heavy-duty vehicles incorporate autonomous systems for long-haul logistics, addressing driver shortages and optimizing fuel efficiency. Demand concentrates in the United States and China, propelled by favorable testing regulations for freight corridors.
- Passenger Cars:Autonomous features in passenger cars range from basic driver assistance to conditional automation, enhancing safety and driver comfort. Mass market adoption hinges on cost reduction and robust safety validation across diverse driving scenarios.
- Delivery Drones:Unmanned aerial vehicles equipped with autonomous navigation for last-mile package delivery in urban and suburban areas.
- Specialty Robots:Autonomous ground vehicles designed for specific tasks in controlled environments like warehouses, agriculture, and mining operations.
- Personal Mobility Devices:Small, self-driving vehicles or scooters offering individual transportation solutions, often within urban or campus settings.
Commercial trucks demonstrate the highest current value proposition. Delivery drones are expanding most quickly.
Sensor Technology:
The maturity and cost-effectiveness of various sensor technologies directly influence the feasibility and reliability of autonomous driving systems.
- Lidar:Light Detection and Ranging sensors provide high-resolution 3D point clouds for precise object detection and mapping, critical for high-level autonomy. Significant investment flows into Lidar development for Level 4 commercial fleets.
- Cameras:Optical sensors capture visual data, enabling object recognition, lane keeping, and traffic sign interpretation, often serving as a primary input for AI models. Their ubiquity in new passenger cars drives continuous software refinement.
- Radar:Radio Detection and Ranging sensors detect object speed and distance, performing reliably in adverse weather conditions where optical sensors struggle.
- Ultrasonic:Short-range acoustic sensors are primarily used for parking assistance and low-speed object detection around the vehicle perimeter.
- Infrared Sensors:These sensors detect heat signatures, enhancing night vision capabilities and pedestrian detection in low-light environments.
Camera technology maintains the broadest installed base. Lidar adoption is climbing the fastest in advanced systems.
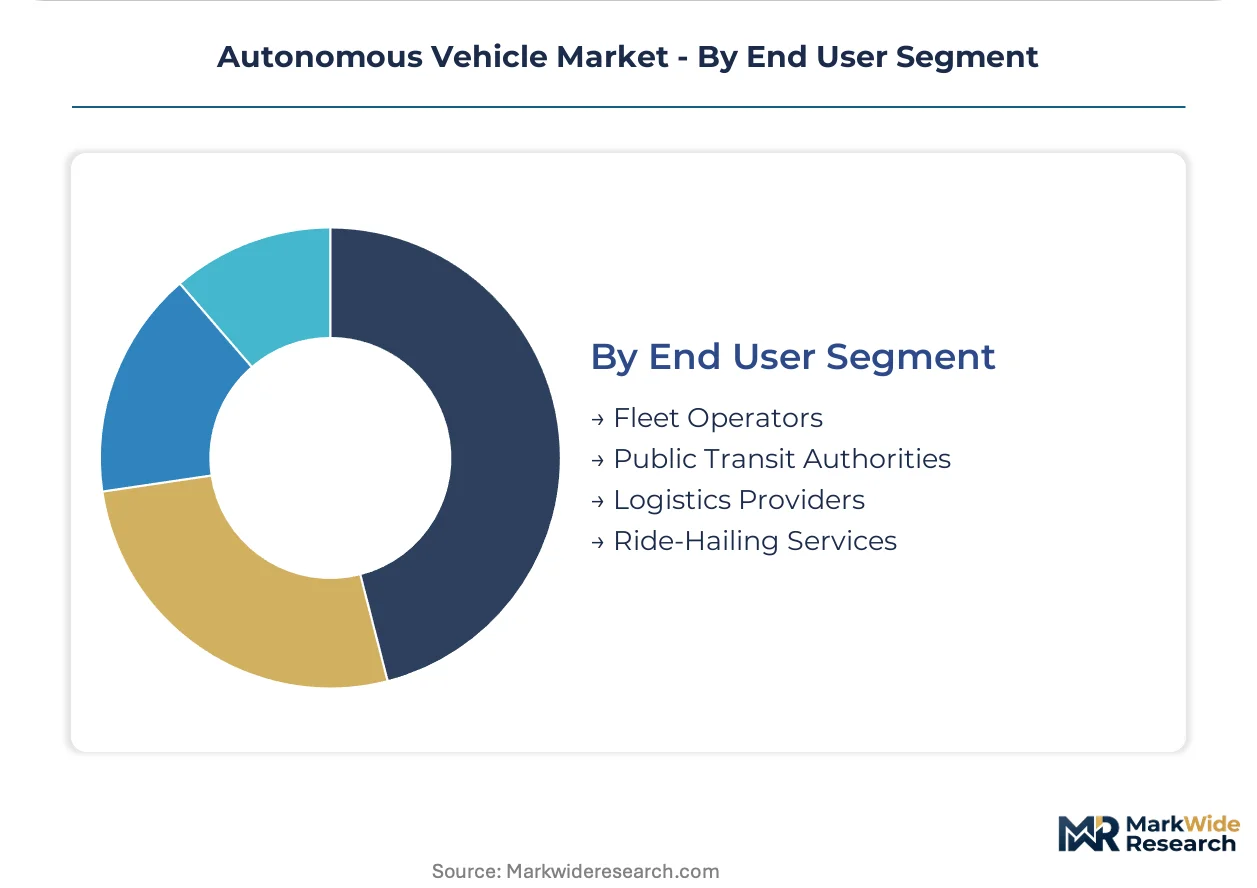
End User Segment:
Different end-user segments exhibit distinct operational requirements and economic incentives for deploying autonomous vehicle solutions.
- Logistics Providers:Companies managing supply chains leverage autonomous commercial trucks to optimize routes, reduce labor costs, and increase asset utilization. This segment drives significant investment in long-haul autonomy across the United States and China.
- Ride-Hailing Services:Autonomous vehicles enable ride-hailing companies to reduce operational expenses by eliminating driver salaries, improving service consistency and availability. Waymo and Baidu Apollo focus on this segment for urban mobility.
- Fleet Operators:Businesses managing vehicle fleets for various purposes, including corporate shuttles or utility services, seek efficiency gains from autonomous technology.
- Public Transit Authorities:Government agencies and municipal operators explore autonomous shuttles and buses to enhance public transportation efficiency and expand service coverage.
Logistics providers represent the largest current revenue opportunity. Ride-hailing services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States workforce and research institutions anchor significant autonomous vehicle development, particularly for Level 4 systems. This concentration drives innovation in both software and hardware for advanced systems. Regulatory frameworks in key nations are shaping deployment strategies and fostering regional specialization.
United States
Demand for Level 4 autonomous commercial trucks and ride-hailing services drives significant investment across US states. NHTSA's Automated Driving Systems 2.0 framework provides essential guidance for safety validation among developers. Silicon Valley and Arizona serve as major testing grounds, fostering rapid iteration of AI models for urban and long-haul applications.
China
Chinese government initiatives actively propel autonomous vehicle adoption for logistics and urban mobility. MIIT directs national standards for intelligent connected vehicles, influencing market access and technology development. Beijing and Shanghai host extensive pilot programs, accelerating real-world data collection and large-scale fleet operations.
Germany
German engineering expertise strongly supports Level 3 passenger vehicle deployment and specialized Lidar development for high-end automotive applications. The EU's upcoming type-approval regulations set stringent safety requirements for new vehicles entering the market. Munich and Stuttgart remain critical automotive innovation hubs, focusing on high-precision sensor integration and ADAS refinement.
Japan
Japanese automakers actively pursue Level 3 autonomy for passenger cars, emphasizing safety and reliability through robust testing. UNECE WP.29 regulation provides a clear framework for advanced driver assistance systems, encouraging OEM investment. Tokyo and Nagoya are centers for V2X integration research, enhancing cooperative perception and smart city mobility solutions.
Autonomous Vehicle Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the autonomous vehicle market, creating a dynamic competitive environment. The market structure exhibits consolidation within core sensor and software architecture providers, reflecting high capital intensity. Strategic archetypes include full-stack autonomous driving developers, specialized component suppliers, and dedicated ride-hailing or logistics service operators. Dominant competitive moves involve strategic partnerships for ecosystem expansion and technology licensing to accelerate development across various vehicle platforms.
Full-stack autonomous driving developers like Waymo exemplify the integration of extensive real-world and simulated driving data, primarily for AI model refinement in ride-hailing services. Baidu Apollo, a prominent Chinese entity, anchors the open-source platform approach, fostering a broader ecosystem for autonomous technology development and deployment within its domestic market. Specialized component and software providers such as Aptiv sit within the critical supply chain, delivering underlying sensor and software architecture to multiple automakers and fleet operators globally. These entities represent distinct strategic approaches to market penetration and technology commercialization.
| Leading Market Players |
|---|
| Waymo |
| Tesla |
| Cruise |
| Aurora Innovation |
| Mobileye |
| Zoox |
| Aptiv |
| Nuro |
| Baidu Apollo |
Cost & Logistics Intelligence
Software-defined vehicle architectures, characterized by centralized computing platforms, are reshaping cost economics and concentrating supply for high-performance processors and specialized AI software. This transition affects both the capital expenditure for hardware and the operational expenditure for continuous software updates.
Pricing Analysis
The bundled-vs-unbundled service split drives pricing differentiation across the autonomous vehicle market. Commercial fleet operators often purchase autonomous driving capability as a recurring subscription service, converting capital expenditure into predictable operating costs. Price differentiation stems from the specific operational design domain (ODD) capabilities and the level of post-deployment support. Pricing pressure on hardware components intensifies due to increasing scale and competition, while software services command a premium based on validated performance. Logistics providers demonstrate lower price sensitivity due to the strong economic case for operational efficiency, unlike mass-market passenger vehicle consumers.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the complex supply chain for autonomous vehicle components. Geographic supply concentration for critical hardware such as high-performance computing chips resides primarily in Taiwan and the United States. Lidar components and advanced sensor arrays are sourced globally, with key suppliers in Germany and Japan. The supply chain relies heavily on specialized semiconductor fabrication and advanced optical manufacturing. Single-source vulnerability for specific processing units represents a structural risk. Distribution of integrated systems often occurs directly to major automakers and fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operational efficiency gains from Level 4 autonomy position this market as a margin-expansion story, driven by the elimination of driver costs in commercial applications.
For Market Incumbents: Hedge against market fragmentation by investing in standardized software platforms that can adapt to diverse regulatory environments. Form strategic partnerships with Tier-1 sensor suppliers to secure advanced Lidar and camera technology. Prioritize investment in robust simulation and validation tools to achieve ISO 26262 functional safety compliance. Address the persistent talent scarcity by establishing internal AI and systems engineering academies.
For New Entrants and Emerging Players: Launch via specialized off-highway applications where controlled environments reduce regulatory and technical complexity. Target the simulation-as-a-service segment, offering sophisticated virtual testing platforms to smaller developers. Focus on niche V2X integration solutions for smart city infrastructure, which represents a penetrable segment with clear ROI. Develop proprietary AI models for specific edge cases in logistics or mining operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component suppliers with proprietary Lidar technology or advanced sensor fusion capabilities. The long-term viability of the market hinges on scalable, safe, and cost-effective Level 4 deployments. Target AI model validation specialists or cybersecurity firms focused on automotive embedded systems. The signal to watch is the widespread adoption of a harmonized international safety validation framework like those from UNECE.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates deployment across diverse vehicle types. |
| Sensor Fusion R&D | Enhances system reliability in adverse conditions, expanding the operational design domain. |
| Cybersecurity Investment | Protects vehicle electronic architectures against malicious attacks and ensures data integrity. |
| Simulation-as-a-Service Expansion | Lowers barriers to entry for software development and accelerates validation cycles. |
| V2X Communication Partnership | Improves cooperative perception and overall safety in complex urban driving scenarios. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core for this market assessment. This approach integrates insights from primary interviews with autonomous driving engineers, fleet managers, regulatory compliance officers, and Lidar manufacturers. Secondary validation draws from publicly available data sources, including MIIT reports, NHTSA guidance, UNECE WP.29 documents, and company financial filings.
An input-output matrix frames the forecast framework across the analysis window. The model segments the market by level of autonomy, vehicle type, sensor technology, end-user segment, and regulatory compliance region. Compound annual growth rates (CAGRs) are derived through regression analysis on historical data and projected adoption curves. Key forecast inputs include Lidar unit costs and Level 4 deployment rates in commercial logistics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or major public safety incidents. All quantitative projections reflect assumptions regarding technological advancements and market acceptance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Technology Market