
 Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market | 2026-2036
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market Insights
API 653-compliant inspection-grade autonomy is redrawing competitive thresholds for tank farm robotics. Square Robot leverages its marine-proven magnetic adhesion systems to anchor deepwater terminal contracts. Eddyfi Technologies sustains technology leadership through phased-array ultrasonic integration. Waygate Technologies dominates radiographic inspection channels while extending software-defined analytics to corrosion-mapping workflows.
Autonomous tank farm inspection and corrosion mapping robot systems deploy magnetically-adherent or tracked mobile platforms carrying non-destructive testing payloads across petroleum storage surfaces, typically operating at shell thickness measurement resolutions below 0.1 millimeter to detect pitting and wall loss before structural failure. Wheeled robots lead deployment counts in aboveground cone-roof tank farms where flat-bottom floors permit continuous magnetic traction, while tracked configurations gain share in floating-roof installations with radial obstacle fields. Ultrasonic testing modules command the largest technology segment by installed base, though magnetic flux leakage arrays are accelerating in sour-service crude terminals where hydrogen-induced cracking demands full-coverage scanning.
API 653 standards enforced by the EPA and state-level environmental regulators in Texas and Louisiana mandate internal inspection intervals that robotic systems compress from multi-week human entries to single-shift autonomous runs. OSHA confined-space entry rules further elevate robot demand by eliminating human exposure to hydrocarbon atmospheres and fall hazards. Stakeholders must weigh captive maintenance-fleet economics against third-party inspection-service contracts as sensor fusion capabilities and fleet-management software mature.
Market Dynamics
API 653 inspection interval compression is forcing terminal operators to choose between captive robotic fleets and third-party inspection contracts, restructuring procurement economics across petroleum storage infrastructure.
Growth Catalysts
- OSHA confined-space rules:Elimination of human entry into hydrocarbon atmospheres and fall hazards drives mandatory robot deployment in aboveground storage tanks across US Gulf Coast terminals.
- Phased-array ultrasonic modules:Resolution below 0.1 millimeter for pitting detection enables predictive maintenance before structural failure, accelerating replacement of manual ultrasonic thickness gauging.
- Texas and Louisiana environmental enforcement:State-level EPA coordination tightens tank integrity mandates, compressing multi-week human inspection cycles into single-shift autonomous runs.
Market Restraints
- Permanent magnet supply concentration:Rare-earth magnet dependency for adhesion systems creates input cost volatility tied to Chinese export quotas and processing capacity.
- Magnetic flux leakage calibration:Hydrogen-induced cracking detection in sour-service crude requires specialized sensor arrays that limit vendor pool depth and extend qualification timelines.
- Floating-roof geometric complexity:Radial obstacle fields and pontoon variations restrict wheeled platform traction, forcing tracked configurations with higher unit economics and maintenance burden.
Strategic Opportunities
- Deepwater terminal expansion:Marine-proven magnetic adhesion systems anchor contracts in coastal Louisiana and Texas where tank farms integrate with offshore loading infrastructure.
- Software-defined analytics convergence:Integration of radiographic inspection data with corrosion-mapping workflows enables real-time wall-loss prediction, displacing post-inspection manual reporting.
- European F-Gas Regulation alignment:Tank vapor recovery system inspections create adjacent demand for autonomous platforms in Rotterdam and Antwerp storage clusters.
Industry Challenges
- API 653 inspector certification crossover:Human inspectors require retraining for robot fleet supervision, creating talent pipeline friction as autonomous systems scale.
- Legacy tank farm SCADA integration:Proprietary communication protocols in decades-old terminal infrastructure demand custom middleware development for robot fleet management.
- Sensor fusion standardization delays:Competing data formats between ultrasonic, magnetic flux leakage, and radiographic modules complicate unified corrosion mapping databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market |
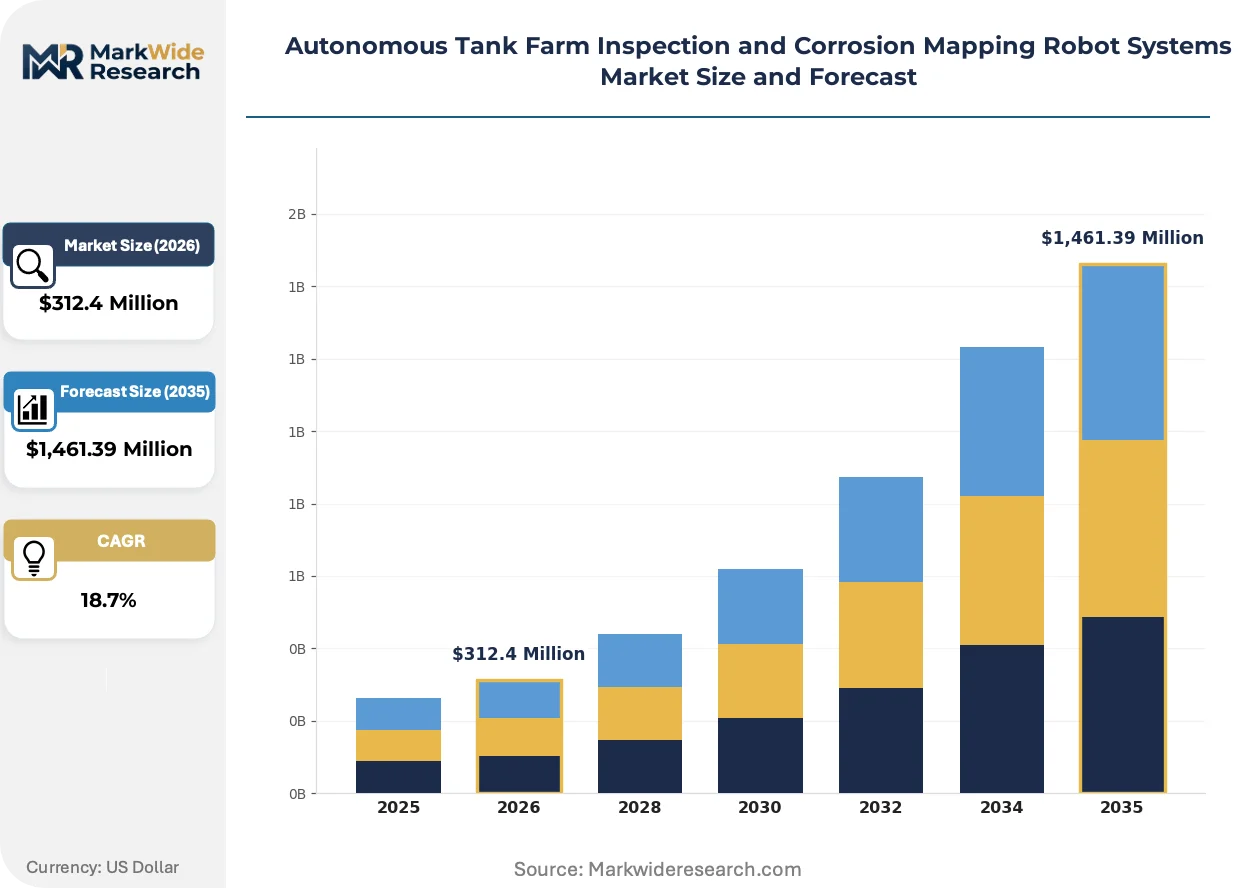
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheeled Robots, Tracked Robots, Legged Robots, Hybrid Robots Technology: Lidar Scanning, Ultrasonic Testing, Infrared Thermography, Magnetic Flux Leakage Application: Corrosion Mapping, Structural Integrity Assessment, Leak Detection, Surface Cleaning End User: Oil Storage Operators, Petrochemical Plants, Tank Maintenance Firms, Pipeline Inspectors |
| Companies Covered | Square Robot, Sonomatic, AYA Robotics, TechCorr, IRISNDT, TCR Arabia, Eddyfi Technologies, Waygate Technologies, Inuktun Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market Trends and Innovations
Autonomous inspection platforms are bifurcating into specialized configurations optimized for distinct tank architectures, with sensor payload modularity becoming the primary competitive differentiator.
Phased-array ultrasonic testing is bifurcating corrosion detection workflows. Sour-service crude terminals in the US Gulf Coast are adopting full-coverage scanning arrays at accelerated procurement cycles. The technology is bifurcating market structure between premium sensor-integrated platforms and basic thickness-gauging retrofits.
EPA coordination with state environmental regulators in Texas and Louisiana is tightening API 653 enforcement timelines. Terminal operators face compressed inspection windows that disqualify manual entry methods. Aboveground cone-roof tank farms with flat-bottom floors are responding fastest through wheeled robot fleet deployment.
Service contract unbundling is fragmenting procurement relationships. Third-party inspection vendors are separating hardware provision from data analytics subscriptions, displacing bundled turnkey arrangements. This restructuring is most visible in North American terminal operator RFPs where fleet ownership economics now compete with per-inspection pricing.
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market Segmentation
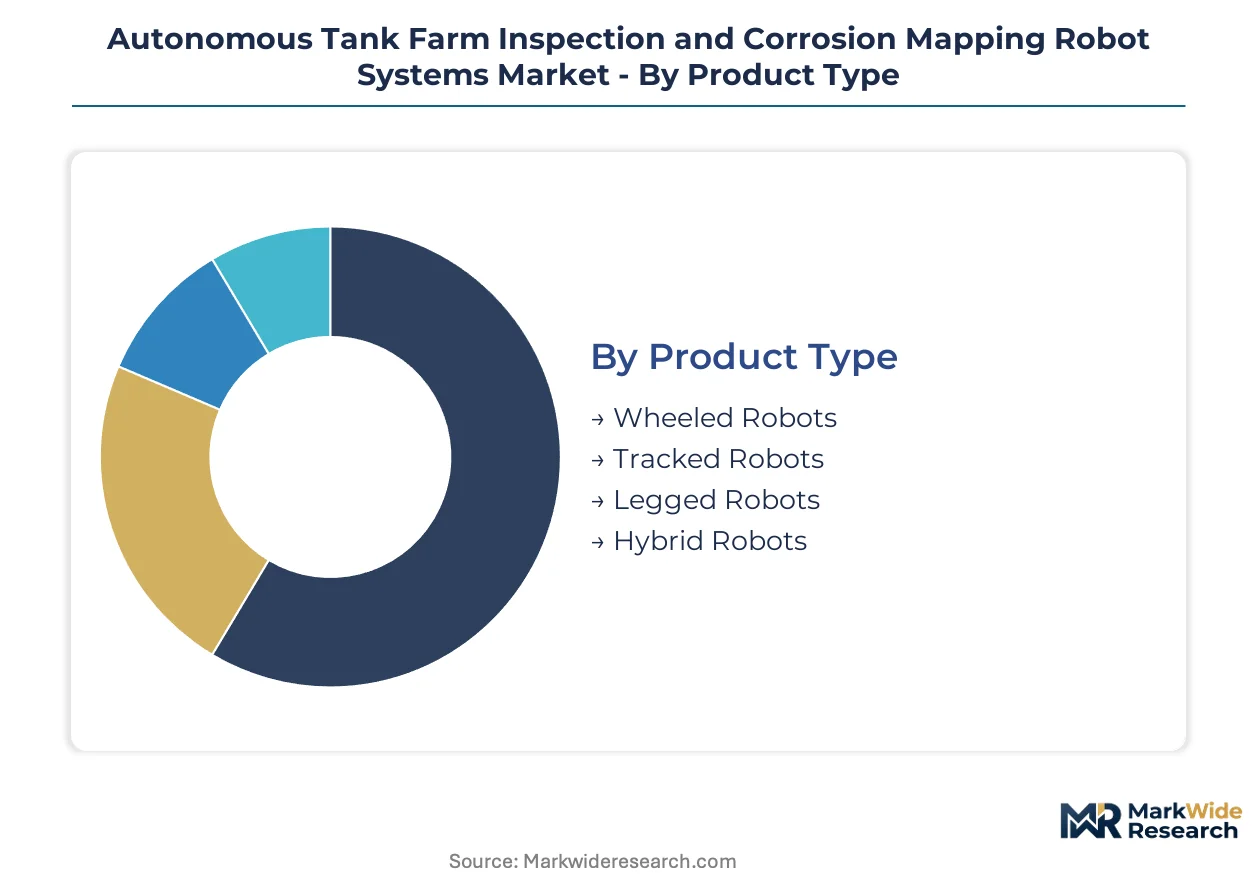
Segmentation in the autonomous tank farm inspection market determines procurement economics, technology roadmaps, and vendor positioning. Platform mobility configurations and non-destructive testing payloads face divergent substitution pressures from alternative inspection modalities.
Product Type:
Wheeled configurations face the strongest substitution threat from drone-based external inspection, while tracked and hybrid platforms defend irreplaceable positions in complex internal geometries.
- Wheeled Robots:Magnetically-adherent platforms with continuous traction on flat-bottom floors dominate aboveground cone-roof tank farms. API 653 interval compression in Texas and Louisiana terminals drives fleet-scale procurement for single-shift inspection runs.
- Tracked Robots:Articulated chassis with distributed ground pressure navigate floating-roof radial obstacle fields and pontoon variations. Higher unit economics limit deployment to sour-service terminals where wheeled traction fails.
- Legged Robots:Quadruped platforms with adaptive gait algorithms access irregular surfaces and internal structural members. Early-stage qualification delays commercial scale in petroleum storage infrastructure.
- Hybrid Robots:Configurable architectures switching between wheeled and tracked modes reduce fleet redundancy for multi-tank terminal operators. Procurement concentration in integrated coastal facilities with mixed roof architectures.
Wheeled robots retain volume leadership; hybrid robots hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor-integrated platforms from basic thickness-gauging retrofits, with ultrasonic modules commanding the highest procurement budgets.
- Ultrasonic Testing:Phased-array modules achieve sub-0.1 millimeter resolution for pitting detection and wall-loss quantification. North American terminal operators displace manual thickness gauging through autonomous deployment.
- Magnetic Flux Leakage:Full-coverage sensor arrays detect hydrogen-induced cracking in sour-service crude terminals. Specialized calibration requirements constrain vendor pool depth and extend qualification timelines.
- Lidar Scanning:3D point cloud generation for geometric deformation mapping and volumetric analysis. Secondary adoption following ultrasonic deployment for comprehensive structural documentation.
- Infrared Thermography:Thermal gradient detection for insulation failure and subsurface defect identification. Adjacent demand from tank vapor recovery system inspections under environmental mandates.
Ultrasonic testing commands installed base dominance; magnetic flux leakage arrays are climbing the fastest.
Application:
Application maturity correlates directly with regulatory mandate specificity, with corrosion mapping benefitting from quantitative API 653 requirements while surface cleaning lacks standardized performance metrics.
- Corrosion Mapping:Systematic wall-thickness documentation with predictive maintenance integration. EPA-coordinated enforcement in Gulf Coast states mandates automated coverage for compliance archiving.
- Structural Integrity Assessment:Geometric deformation quantification and stress concentration identification. Floating-roof seal inspections drive demand in coastal loading terminals.
- Leak Detection:Acoustic emission monitoring and vapor sensing for early failure identification. Regulatory pressure accelerates deployment ahead of formal mandate codification.
- Surface Cleaning:Automated sludge removal and coating preparation prior to inspection entry. Contract unbundling separates hardware provision from cleaning service subscriptions.
Corrosion mapping retains volume leadership; leak detection holds the steepest expansion curve.
End User:
Customer type determines procurement model selection between captive fleet ownership and third-party inspection contracts, with oil storage operators favoring direct control over critical infrastructure data.
- Oil Storage Operators:Integrated terminal companies with API 653 compliance liability deploy captive robotic fleets. Procurement scales with tank count and inspection frequency mandates.
- Petrochemical Plants:Process-integrated storage with combined pressure vessel and atmospheric tank inspection requirements. Multi-asset platform utilization improves fleet economics.
- Tank Maintenance Firms:Third-party service providers unbundling hardware provision from analytics subscriptions. RFP restructuring favors per-inspection pricing over bundled turnkey arrangements.
- Pipeline Inspectors:Cross-asset inspection capabilities extending from linear pipeline to tank farm geometries. Adjacent market entry with modified platform configurations.
Oil storage operators retain volume leadership; tank maintenance firms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for rare-earth magnet components shapes procurement strategies across major tank farm robotics markets, while export-oriented terminal operators in coastal zones drive fleet-scale adoption of API 653-compliant inspection platforms.
United States
Gulf Coast oil storage clusters in Texas and Louisiana anchor domestic demand as EPA-coordinated enforcement tightens tank integrity mandates. OSHA confined-space regulations eliminate human entry requirements in hydrocarbon atmospheres. Houston-Beaumont-Port Arthur corridor terminals deploy wheeled robotic fleets for single-shift inspection compression.
Germany
Rotterdam-Antwerp storage hub connectivity drives demand for vapor recovery system inspection platforms under EU F-Gas Regulation alignment. REACH chemical safety protocols extend to tank farm maintenance equipment qualification. North Rhine-Westphalia refining complexes integrate autonomous corrosion mapping into predictive maintenance workflows.
China
Strategic petroleum reserve expansion in coastal provinces accelerates procurement of magnetic adhesion systems for crude storage terminals. MIIT robotics industry standards shape domestic platform certification requirements. Shandong Peninsula and Yangtze River Delta tank farms pilot phased-array ultrasonic deployment at state-owned storage facilities.
Saudi Arabia
Offshore loading terminal integration with coastal tank farms creates demand for marine-proven inspection platforms in harsh environment specifications. The national petroleum regulator mandates integrity assessment intervals that favor autonomous coverage solutions. Eastern Province storage clusters near Ras Tanura and Jubail Industrial City lead regional fleet procurement.
Netherlands
Rotterdam storage terminal density concentrates demand for multi-tank fleet management software and sensor fusion platforms. EU Green Deal emissions monitoring requirements extend to tank vapor recovery inspection automation. Randstad region operators unbundle hardware provision from analytics subscriptions in restructured service contracts.
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market Competitive Landscape
Concentration sits with sensor-integrated platform specialists and marine-proven adhesion system developers, while third-party inspection service providers fragment the lower tier through contract unbundling. The vendor base stratifies across premium phased-array ultrasonic integrators, mid-market thickness-gauging retrofit suppliers, and emerging hybrid mobility configuration entrants. Two dominant competitive moves reshape positioning: strategic partnerships between robotics hardware firms and NDT analytics software providers, plus geographic expansion through deepwater terminal certification programs.
Within the marine adhesion specialist tier, Square Robot exemplifies platform architecture optimized for offshore loading integration. Eddyfi Technologies and Waygate Technologies occupy positions as sensor-technology anchors, with the former representing phased-array ultrasonic integration expertise and the latter exemplifying radiographic inspection channel dominance extended toward software-defined corrosion mapping workflows. These three companies illustrate how competitive positioning bifurcates between hardware mobility innovation and sensor payload depth.
| Leading Market Players |
|---|
| Square Robot |
| Sonomatic |
| AYA Robotics |
| TechCorr |
| IRISNDT |
| TCR Arabia |
| Eddyfi Technologies |
| Waygate Technologies |
| Inuktun Services |
| Others |
Pricing and Supply Chain Analysis
Phased-array ultrasonic module substitution for conventional thickness gauges simultaneously concentrates procurement budgets with sensor-integrated platform vendors and compresses pricing premiums for basic wheeled retrofits. Texas and Louisiana terminal operators now anchor fleet-scale contracts that reshape supplier geography toward EPA-coordinated enforcement corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium sensor-integrated platforms, mid-market thickness-gauging retrofits, and economy tracked configurations. Price differentiation rests on API 653 certification grade and phased-array resolution capability, with sub-0.1 millimeter platforms commanding sustained premiums. Cost compression in economy tiers is intensifying because rare-earth magnet input volatility forces margin trade-offs. Third-party inspection service providers exhibit highest price sensitivity, while integrated oil storage operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Extended lead times for neodymium magnet arrays and phased-array transducer modules now stretch procurement cycles for North American platform integrators. Component sourcing draws from China for rare-earth processing, Germany for precision sensor fabrication, and Japan for ultrasonic transducer ceramics. Single-source vulnerability in Chinese rare-earth export quotas threatens input cost stability. Distribution runs through authorized robotics distributors and direct OEM contracts to terminal operators and maintenance service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple entry points as service contract unbundling separates hardware provision from analytics subscriptions, spawning niche specialist opportunities across inspection workflow segments.
For Market Incumbents: Secure phased-array ultrasonic certification lock-in through API 653 inspector training partnerships, insulating against emerging drone-based external inspection substitutes. Deepen captive magnet supply arrangements to offset Chinese export quota volatility. Fortify software-defined analytics convergence to defend against unbundled third-party data service entrants.
For New Entrants and Emerging Players: Anchor in floating-roof geometric complexity segments where wheeled platform traction fails and tracked configurations face limited vendor depth. Target sour-service crude terminals in coastal Louisiana with hydrogen-induced cracking detection specialization. Pursue marine-proven adhesion system qualification as the go-to-market angle for deepwater terminal integration.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid mobility configuration developers with multi-architecture fleet management software, positioned for multi-tank terminal operator consolidation. Long-term viability hinges on sensor fusion standardization convergence rather than single-modality hardware scale. Watch API 653 enforcement timeline acceleration as the inflection signal for fleet-scale procurement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies ultrasonic, magnetic flux leakage, and radiographic data formats for corrosion mapping databases. |
| API 653 Inspector Certification Program | Builds robot fleet supervision talent pipeline as autonomous systems scale across Gulf Coast terminals. |
| Deepwater Terminal Qualification | Marine-proven adhesion certification anchors contracts in coastal Louisiana and Texas loading infrastructure. |
| Backward Integration into Magnet Supply | Captive rare-earth sourcing insulates against Chinese export quota volatility for adhesion system costs. |
| Software-Defined Analytics Partnership | Radiographic inspection data convergence enables real-time wall-loss prediction displacing manual reporting. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement documentation, API standards publications, and OSHA regulatory filings. Primary interviews engaged robotics engineering directors, terminal maintenance managers at Gulf Coast storage facilities, NDT service firm procurement leads, and phased-array ultrasonic module suppliers. Secondary validation drew from customs trade data, state environmental regulator inspection records, and robotics industry certification databases. Bottom-up platform shipment estimates triangulated against top-down terminal operator capital expenditure patterns.
Segmentation dimensions modeled include platform mobility configuration, non-destructive testing payload technology, inspection application type, and end-user procurement model across the projection horizon. CAGRs derived from installed base growth trajectories and replacement cycle compression under tightening API 653 intervals. Forecast inputs incorporated rare-earth magnet supply elasticity and EPA-state coordination enforcement intensity variations.
Material uncertainties — rare-earth export policy shifts, API 653 inspector certification pipeline constraints, and sensor fusion standardization timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and terminal operator fleet ownership preference stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market