
 Marine Asset Integrity Services Market | 2026-2036
Marine Asset Integrity Services Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Asset Integrity Services Market Foresight
Class-notation structural integrity certification is collapsing the gap between legacy vessel fleets and modern digital-classed assets. Bureau Veritas leverages its remote survey platform to reduce offshore mobilization costs for floating production units. DNV GL anchors its position through rule development for hydrogen-ready offshore structures. Lloyd's Register Group Limited competes on deepwater riser integrity programs in the Gulf of Mexico and West Africa.
Marine Asset Integrity Services encompass the systematic evaluation, maintenance, and certification of vessels, offshore platforms, and subsea equipment against classification society rules and flag-state requirements, employing non-destructive testing methods with detection thresholds typically calibrated to millimeter-scale crack propagation. These services prevent catastrophic failure of load-bearing structures exposed to cyclic fatigue, cathodic degradation, and pressure differentials across design life cycles. Inspection services dominate contract value due to regulatory mandation intervals, while phased array ultrasonics captures the fastest expansion as operators replace conventional radiography for subsea weld verification. Offshore wind end users represent the emerging margin pool, driven by turbine foundation scour monitoring and transition piece fatigue assessment requirements.
The International Maritime Organization's Goal-Based Standards framework and the EU's Offshore Safety Directive collectively mandate prescriptive inspection regimes for floating installations and fixed platforms, creating compliance-driven demand that resists cyclical commodity price swings. The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce overlapping structural and environmental integrity requirements in federal waters, adding jurisdictional complexity for multi-flag operators. Stakeholders must monitor how classification societies integrate artificial intelligence into predictive corrosion models, as this capability will determine which service providers retain preferred vendor status under next-generation risk-based inspection contracts.
Market Dynamics
Digital twin deployment is compressing inspection intervals across floating production units, as operators replace calendar-based maintenance with condition-monitoring triggers that reduce unplanned shutdowns.
Growth Catalysts
- EU Offshore Safety Directive:The updated directive mandates accelerated structural assessment protocols for aging North Sea platforms, forcing operators to expand integrity service contracts.
- Offshore wind farm operators:Warranty and insurance requirements are driving expanded inspection contracts for turbine foundation scour monitoring and transition piece fatigue assessment.
- Phased array ultrasonics:This non-destructive testing method is displacing conventional radiography for subsea weld verification, creating equipment upgrade cycles across inspection fleets.
Market Restraints
- Skilled technician scarcity:The specialized workforce capable of interpreting acoustic emission data and corrosion propagation models concentrates in Norway's continental shelf, creating supply bottlenecks.
- High mobilization costs:Remote platform locations require helicopter and vessel charter expenses that consume 40-60% of contract value regardless of inspection scope.
- Regulatory fragmentation:Overlapping requirements from the US Coast Guard and Bureau of Safety and Environmental Enforcement force multi-flag operators to maintain parallel compliance systems.
Strategic Opportunities
- Artificial intelligence integration:Classification societies are developing predictive corrosion models that will determine preferred vendor status under next-generation risk-based inspection contracts.
- Hydrogen-ready structures:DNV GL's rule development for hydrogen-compatible offshore platforms creates first-mover certification advantages for service providers.
- Remote survey platforms:Bureau Veritas demonstrates cost reduction potential for floating production unit inspections, opening replication paths across Southeast Asian offshore fields.
Industry Challenges
- Data interoperability gaps:Legacy vessel fleets generate inspection records in incompatible formats that resist integration with modern digital-classed asset management systems.
- Certification timeline compression:The International Maritime Organization's Goal-Based Standards framework accelerates documentation requirements while maintaining prescriptive inspection intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Asset Integrity Services Market |
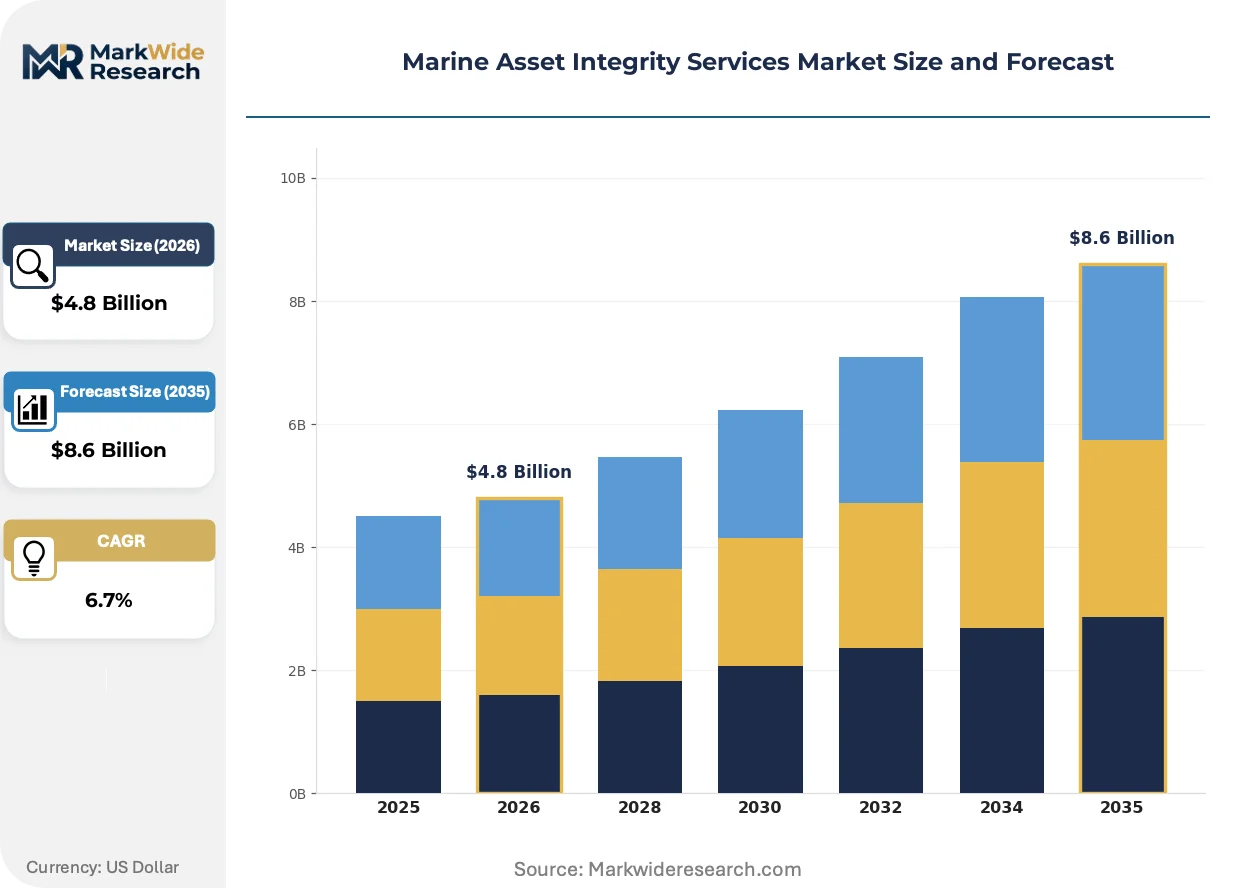
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Repair, Certification Technology: Ultrasonic Testing, Magnetic Particle Inspection, Phased Array, Visual Inspection End User: Oil & Gas, Shipping Companies, Offshore Wind, Maritime Contractors Application: Survey, Asset Management, Risk Assessment, Compliance |
| Companies Covered | Bureau Veritas, ABS Group, DNV GL, SGS SA, Intertek Group plc, Lloyd's Register Group Limited, Oceaneering International, Inc., Aker Solutions ASA, Fugro N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Asset Integrity Services Market Shifts & Advancements
Inspection technology is migrating from periodic manual intervention toward continuous sensor-based monitoring, with classification societies rewriting certification rules to accommodate real-time data streams.
Autonomous underwater vehicle platforms equipped with high-resolution imaging sonar are miniaturizing the physical footprint required for subsea infrastructure surveys. Norwegian operators are deploying these systems for unplanned inspection triggers between scheduled diver campaigns. The technology is miniaturizing mobilization logistics from multi-vessel operations to single-launch recoveries, compressing per-inspection costs by eliminating surface support requirements.
The EU's updated Offshore Safety Directive tightens structural assessment protocols specifically for installations exceeding twenty-five years of operational life. This regulatory pressure forces operators to budget for enhanced non-destructive testing coverage beyond minimum class requirements. Aging fixed platforms in the UK and Dutch sectors of the North Sea face the most immediate compliance cost escalation.
Buyers are unbundling inspection services from integrated maintenance contracts, creating direct procurement relationships with specialized non-destructive testing laboratories. Oil majors and independent operators now separately tender for ultrasonic technicians, data interpretation specialists, and remediation fabricators. This pattern is most pronounced in the Gulf of Mexico, where supermajors have consolidated vendor panels around discrete capability certifications rather than full-service portfolios.
Marine Asset Integrity Services Market Segmentation
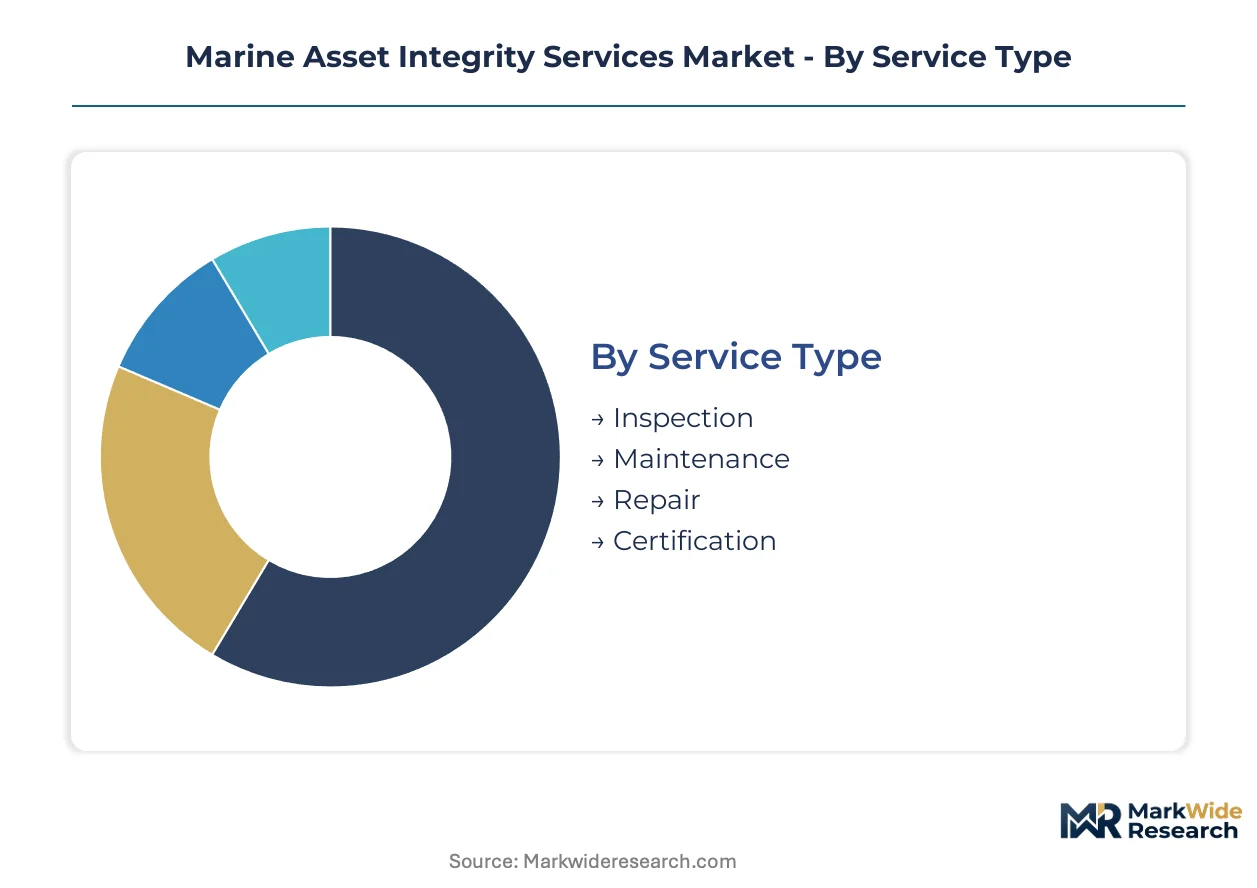
Regulatory mandation intervals vary sharply across service categories, creating divergent margin structures and vendor specialization patterns. Classification societies enforce prescriptive inspection regimes that lock in recurring revenue for certified providers while leaving discretionary maintenance exposed to operator budget cycles.
Service Type:
The EU Offshore Safety Directive and IMO Goal-Based Standards impose differentiated compliance burdens on each service category, with inspection intervals fixed by rule rather than economics.
- Inspection:Systematic evaluation of vessels, platforms, and subsea equipment against classification society rules and flag-state requirements using non-destructive testing methods. Demand concentrates in Norway's continental shelf where accelerated corrosion cycles on subsea infrastructure force operators to expand contract scope beyond minimum class requirements.
- Certification:Class-notation structural integrity validation that collapses the gap between legacy vessel fleets and modern digital-classed assets. Offshore wind farm operators in the North Sea and Baltic markets drive contract expansion to satisfy warranty and insurance requirements for turbine foundation installations.
- Maintenance:Scheduled preservation of load-bearing structures exposed to cyclic fatigue, cathodic degradation, and pressure differentials across design life cycles.
- Repair:Remediation of detected defects including weld reconstruction, structural reinforcement, and component replacement on floating production units and fixed platforms.
Established volume favors Inspection; emerging adoption favors Certification.
Technology:
Cost tier differentiation separates premium sensor platforms from conventional manual methods, with equipment upgrade cycles creating vendor lock-in around calibration protocols.
- Phased Array:Advanced ultrasonic beam steering technology that displaces conventional radiography for subsea weld verification through electronic scanning without mechanical movement. Offshore wind foundation inspections in European waters deploy these systems for transition piece fatigue assessment where detection thresholds must resolve millimeter-scale crack propagation.
- Ultrasonic Testing:Conventional pulse-echo methods for thickness measurement and flaw detection in hull structures and pressure vessels. Gulf of Mexico operators rely on these techniques for deepwater riser integrity programs where Bureau of Safety and Environmental Enforcement mandates documented coverage.
- Magnetic Particle Inspection:Surface-breaking defect detection for ferromagnetic components using magnetic field disturbance visualization.
- Visual Inspection:Direct optical assessment supplemented by remote camera systems for preliminary condition screening.
Phased Array commands premium pricing; Ultrasonic Testing anchors volume deployment.
End User:
Application maturity separates legacy hydrocarbon infrastructure from emerging renewable installations, with divergent procurement sophistication and contract structuring.
- Oil & Gas:Integrated majors and independents operating fixed platforms, floating production units, and subsea infrastructure across the North Sea, Gulf of Mexico, and West Africa. Aging installations exceeding twenty-five years of operational life in the UK and Dutch sectors face immediate compliance cost escalation under tightened EU assessment protocols.
- Offshore Wind:Developers and operators of turbine arrays requiring foundation scour monitoring, transition piece fatigue assessment, and warranty compliance documentation. Norwegian and UK project pipelines generate concentrated demand for specialized inspection capabilities that diverge from oil and gas methodologies.
- Shipping Companies:Container, tanker, and bulk vessel operators subject to flag-state renewal surveys and port state control detention risk.
- Maritime Contractors:Construction and installation firms requiring pre-acceptance testing and ongoing integrity verification for chartered equipment.
Oil & Gas retains contract value concentration; Offshore Wind climbs the fastest.
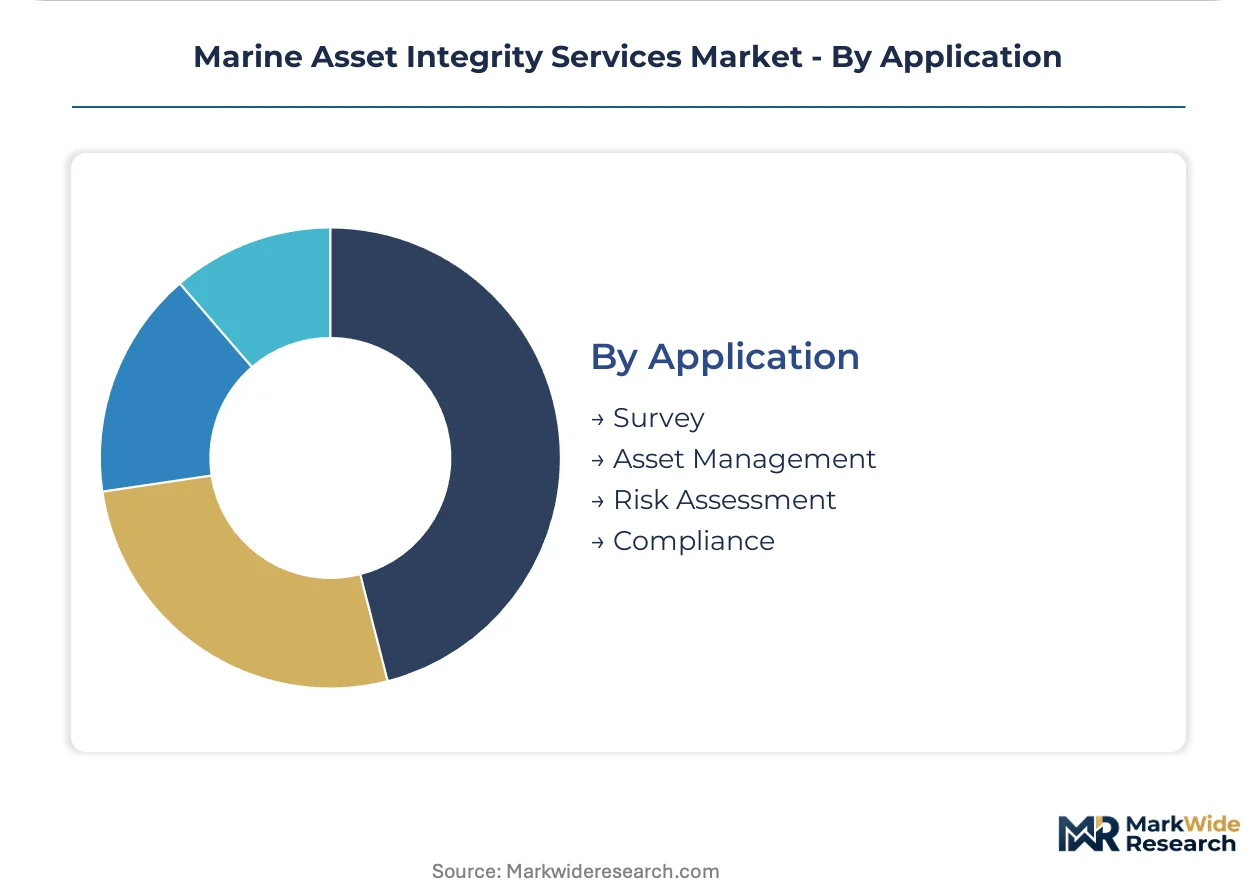
Application:
Customer type segmentation separates owner-operated assets from third-party managed portfolios, with divergent data integration requirements and vendor relationship structures.
- Compliance:Documentation and certification activities satisfying International Maritime Organization Goal-Based Standards, EU Offshore Safety Directive, and US Coast Guard overlapping requirements. Multi-flag operators in federal waters maintain parallel systems to address jurisdictional complexity between structural and environmental integrity mandates.
- Asset Management:Lifecycle optimization through digital twin deployment and condition-monitoring triggers that replace calendar-based maintenance intervals. Floating production unit operators in Southeast Asian fields adopt remote survey platforms to compress inspection logistics and reduce unplanned shutdowns.
- Survey:Baseline data acquisition for acquisition due diligence, insurance placement, and regulatory filing.
- Risk Assessment:Probabilistic evaluation of failure modes for insurance pricing and capital allocation decisions.
Compliance absorbs mandatory spend; Asset Management captures discretionary expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine asset integrity services flow from net-exporting certification hubs toward import-dependent offshore basins. Norway and the United Kingdom generate surplus technical capacity that serves demand clusters in West Africa and Southeast Asia.
Norway
Accelerated corrosion cycles on subsea infrastructure and expanding offshore wind pipelines drive contract expansion. The Norwegian Petroleum Safety Authority enforces strict structural assessment protocols for aging North Sea platforms. Stavanger anchors the continental shelf's concentrated specialist workforce, where technicians interpret acoustic emission data for unplanned inspection triggers.
United Kingdom
Aging fixed platforms exceeding twenty-five years of operational life require enhanced non-destructive testing coverage beyond minimum class requirements. The Health and Safety Executive implements the EU Offshore Safety Directive's tightened assessment timelines for UK sector installations. Aberdeen concentrates diver-deployed inspection fleets and autonomous underwater vehicle operators serving the central North Sea.
United States
Deepwater riser integrity programs in the Gulf of Mexico absorb specialized ultrasonic technician capacity. The Bureau of Safety and Environmental Enforcement mandates documented coverage for subsea infrastructure in federal waters. Houston hosts the primary vendor panels where supermajors consolidate procurement around discrete capability certifications.
Brazil
Pre-salt field development creates demand for floating production unit inspection and certification services. The national petroleum regulator enforces structural integrity requirements for offshore installations under concession agreements. Rio de Janeiro clusters engineering contractors performing class-notation validation for foreign-flagged assets operating in Brazilian waters.
Singapore
Shipyard hub status generates repair and maintenance demand from regional shipping companies and offshore contractors. The Maritime and Port Authority administers flag-state renewal survey requirements for vessels under its registry. Jurong anchors Southeast Asia's concentrated mobilization logistics for remote platform locations across Indonesian and Malaysian fields.
Marine Asset Integrity Services Market Competitive Landscape
Listed leaders compete with private specialists across certification authority and technical service delivery. The market structure concentrates around classification societies holding delegated statutory authority, while equipment operators and engineering contractors occupy fragmented tiers beneath. Three archetypes dominate: rule-developing class societies, inspection fleet operators, and integrated subsea service contractors. Competitive moves center on artificial intelligence integration for predictive corrosion modeling and remote survey platform deployment to compress mobilization costs.
Within the classification society tier, Bureau Veritas and DNV GL exemplify divergent positioning around digital certification capabilities. Lloyd's Register Group Limited occupies a position bridging legacy vessel fleet services with emerging offshore wind foundation assessment. Among integrated subsea contractors, Oceaneering International, Inc. represents the equipment-operator archetype with autonomous underwater vehicle fleets.
| Leading Market Players |
|---|
| Bureau Veritas |
| ABS Group |
| DNV GL |
| SGS SA |
| Intertek Group plc |
| Lloyd's Register Group Limited |
| Oceaneering International, Inc. |
| Aker Solutions ASA |
| Fugro N.V. |
| Others |
Supply & Pricing Matrix
Phased array ultrasonics displacing conventional radiography for subsea weld verification simultaneously concentrates equipment procurement in Norway and the United Kingdom while compressing per-inspection pricing through reduced surface support requirements. This substitution dynamic reshapes vendor economics as inspection fleet operators absorb capital upgrade cycles while passing partial savings to offshore wind developers under warranty compliance pressure.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures where pricing stratifies across certification grade, mobilization complexity, and after-sales data interpretation bundling. Price differentiation hinges on DNV GL or Bureau Veritas class-notation validation tier and geographic delivery cost to remote platform locations. Cost compression in standard ultrasonic testing tiers is intensifying because equipment operators compete for volume deployment in the Gulf of Mexico. Offshore wind developers exhibit highest price sensitivity due to warranty documentation requirements, while pre-salt field operators in Brazil demonstrate lowest sensitivity given concession agreement compliance mandates.
Supply Chain Analysis
Extended lead times for phased array probe calibration equipment tether inventory management to Norwegian and UK service hubs. Raw material and component dependencies center on piezoelectric ceramics, specialized acoustic coupling gels, and high-pressure rated sensor housings. Single-source vulnerability concentrates in European probe manufacturers serving North Sea inspection fleets. Distribution runs through engineering contractor networks anchored in Stavanger, Aberdeen, and Houston, with final mile delivery via helicopter and offshore vessel charter.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
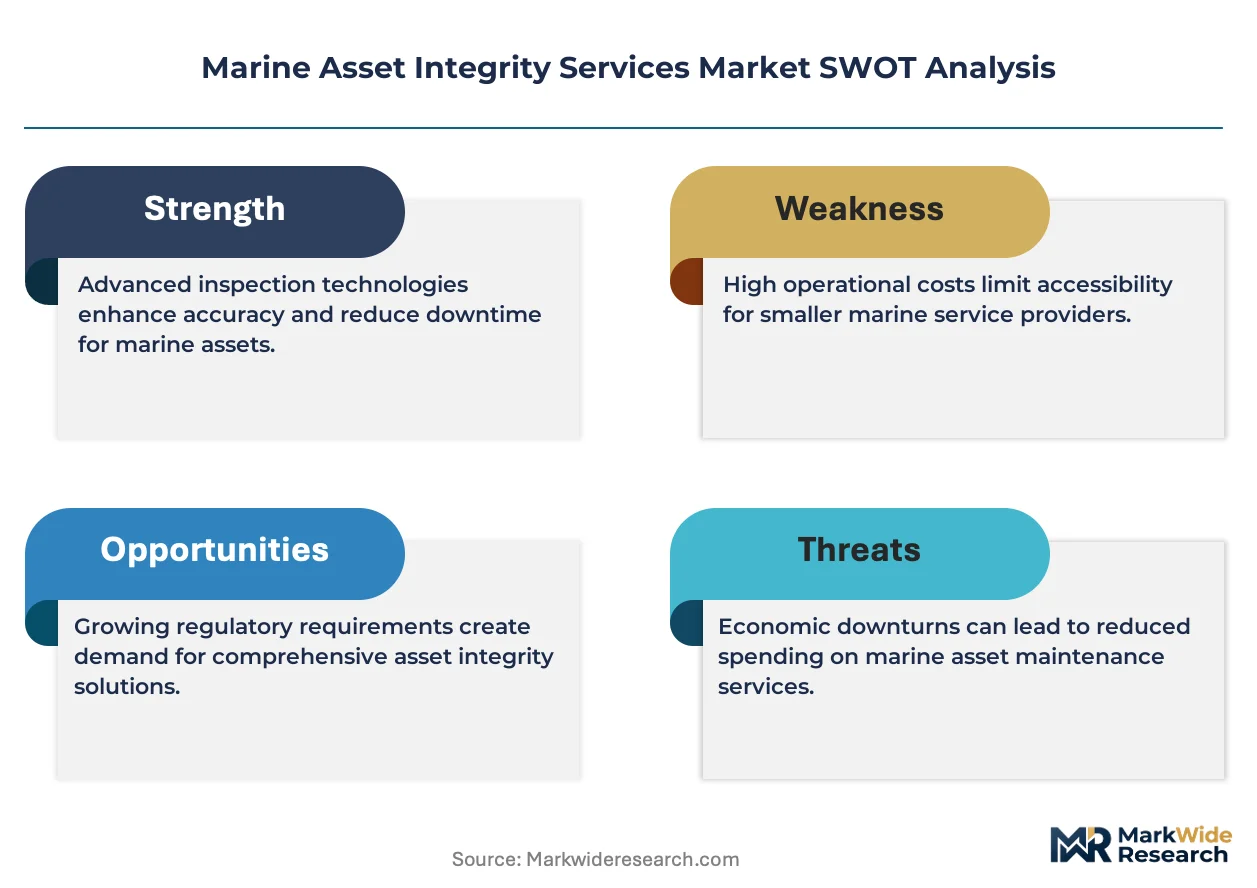
This market tracks a cyclical recovery anchored in offshore wind capital deployment waves and aging North Sea platform life-extension programs. The recovery trajectory rests on regulatory compliance mandation rather than discretionary operator spending.
For Market Incumbents: Fortify certification authority positioning through artificial intelligence integration into predictive corrosion models, as classification societies will gate preferred vendor status under next-generation risk-based inspection contracts. Deepen backward integration into autonomous underwater vehicle fleets to capture mobilization cost compression that Bureau Veritas has demonstrated in Southeast Asian floating production unit deployments. Threat exposure concentrates in specialized non-destructive testing laboratories unbundling inspection services from integrated maintenance contracts in the Gulf of Mexico. For New Entrants and Emerging Players: Fast-track certification through DNV GL's hydrogen-ready offshore structure rule development creates first-mover positioning in emerging turbine foundation assessment markets. White-space availability concentrates in Baltic Sea offshore wind scour monitoring, where procurement sophistication lags North Sea counterparts. Target direct procurement relationships with independent operators in West Africa deepwater riser integrity programs, where vendor panel consolidation around discrete capability certifications remains incomplete. Go-to-market execution should emphasize unplanned inspection trigger capabilities between scheduled diver campaigns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed inspection fleet operators holding concentrated technician capacity in Norway's continental shelf. Long-term viability over the five-to-ten year horizon favors platforms with demonstrated remote survey deployment and artificial intelligence-enabled data interpretation capabilities. Acquisition target archetype: mid-cap specialists with Bureau Veritas or Lloyd's Register preferred vendor status in offshore wind foundation certification. Signal to watch: classification society rule revisions integrating real-time sensor data streams into class-notation validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Artificial Intelligence Integration | DNV GL's predictive corrosion models will determine preferred vendor status under next-generation contracts. |
| Remote Survey Platform Deployment | Bureau Veritas demonstrates cost reduction potential for floating production unit inspections across Southeast Asia. |
| Hydrogen-Ready Structure Certification | Rule development for hydrogen-compatible offshore platforms creates first-mover advantages for service providers. |
| Autonomous Underwater Vehicle Fleet Expansion | Norwegian operators deploy miniaturized systems for unplanned inspection triggers between scheduled diver campaigns. |
| Phased Array Ultrasonics Equipment Upgrade | Electronic beam steering displaces conventional radiography for subsea weld verification in European offshore wind markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of classification society rule filings, offshore operator procurement disclosures, and regulatory mandate documentation. Primary interviews engaged asset integrity managers at oil majors and independents, certification engineers at Bureau Veritas and Lloyd's Register, and procurement leads at offshore wind developers across the North Sea and Baltic markets. Secondary validation drew from EU Offshore Safety Directive implementation guidance, US Bureau of Safety and Environmental Enforcement enforcement records, and Norwegian Petroleum Safety Authority inspection protocols. Bottom-up contract value aggregation triangulates against top-down market sizing derived from disclosed inspection fleet capacities and average contract values.
Segmentation dimensions modeled span service type, technology platform, end-user industry, and application purpose across the projection horizon. Analytical framework incorporates compliance-driven demand elasticity distinct from discretionary maintenance cycles. CAGRs derive from regression against offshore wind installation forecasts and North Sea platform life-extension capital commitment trajectories. Industry-specific forecast inputs include classification society rule revision timelines and flag-state survey interval mandation patterns.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of EU Offshore Safety Directive protocols and continued offshore wind warranty documentation expansion; material deviation would warrant model refresh. Specific risk factors encompass skilled technician scarcity concentration in Norway, regulatory fragmentation between US Coast Guard and Bureau of Safety and Environmental Enforcement jurisdictions, and data interoperability gaps resisting legacy fleet integration. Revision becomes warranted when autonomous underwater vehicle penetration in subsea infrastructure surveys crosses thresholds that fundamentally alter mobilization economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Fasteners Market
Marine
Boat Ladder Market
Marine
Unmanned Marine Vehicles Market
Marine
Marine Shackle Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Spreader Lights Market
Marine
Marine Exhaust Systems Market
Marine
Swamp Boat Market
Marine
Boat Trolling Motor Market
Marine
Marine LED Lights Market
Marine
Ship Heat Exchanger Market
Marine
Jack-Up Vessels Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Deep-V Boat Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Ballast Water Management Market